
 Europe Paper Market | 2026-2036
Europe Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paper Market Foresight
Plastic is recalibrating European packaging economics as brand owners switch to fiber-based alternatives for food contact and transport applications. Smurfit Kappa leverages its integrated containerboard network across Ireland and continental Europe to capture this substitution wave. Mondi competes through barrier-coated kraft solutions that replace multilayer plastics in fresh-produce logistics.
Paper comprises cellulosic sheets formed from wood pulp or recovered fiber, typically ranging from 40 to 400 grams per square meter, serving functions from information display to protective containment across industrial and consumer supply chains. Uncoated paper dominates commercial correspondence and office applications but faces structural decline as digital workflows displace print volumes. Specialty paper commands disproportionate margin pools in filtration, thermal transfer, and medical-grade segments where technical specifications limit commoditization.
EMA, ECHA, and the EU Green Deal collectively shape European paper demand through packaging waste directives, chemical safety assessments for food-contact coatings, and carbon-border adjustments on imported pulp. REACH compliance costs favor large integrated producers with dedicated regulatory affairs capacity over smaller independent mills. Stakeholders must monitor how the F-Gas Regulation's phase-down of fluorinated barriers affects development timelines for grease-resistant food packaging grades.
Market Dynamics
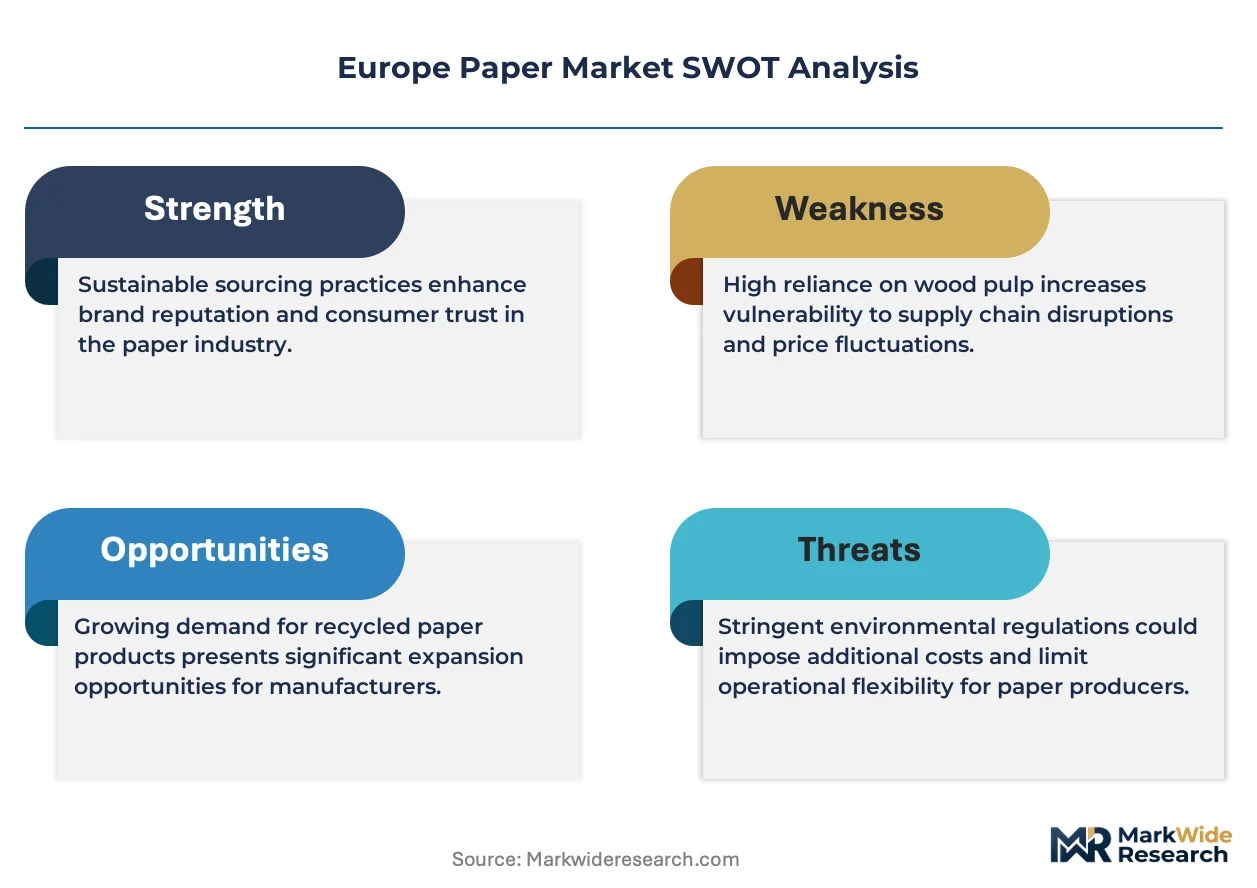
The EU Green Deal's circular-economy mandates are forcing mills to reconfigure fiber sourcing and energy systems faster than capital cycles allow. Nordic integrated producers leverage hydroelectric power and captive pulp supply to absorb these compliance costs while southern European independents face stranded asset risk.
Growth Catalysts
- E-commerce packaging surge:German retailers are expanding corrugated box specifications to meet last-mile durability requirements. This pulls fresh demand for high-performance fluting grades.
- REACH chemical safety protocols:Large integrated producers with dedicated regulatory affairs teams capture market share as compliance costs exclude smaller competitors from food-contact coating segments.
- Barrier-coated kraft innovation:Technical advances in water-based coatings enable fiber-based alternatives to replace multilayer plastics in fresh-produce logistics applications.
Market Restraints
- Recovered fiber cost volatility:Old corrugated container prices swing with municipal collection efficiency and export demand to Asian packaging markets.
- Nordic supply concentration:Integrated pulp-and-paper operations in Sweden and Finland control disproportionate shares of virgin kraft pulp capacity.
- Digital workflow displacement:Uncoated freesheet demand contracts as enterprise document management systems eliminate print-based correspondence.
Strategic Opportunities
- Poland and Czech Republic underpenetration:These markets lack domestic containerboard capacity and import from German and Austrian mills at freight disadvantage.
- F-Gas Regulation phase-down:Fluorinated barrier restrictions create white space for grease-resistant food packaging grades using bio-based alternatives.
- Pharmaceutical serialization:Track-and-trace mandates for EU drug distribution drive demand for thermal transfer and security label substrates.
Industry Challenges
- Decarbonization capex burden:Biomass boiler retrofits and carbon capture installations strain balance sheets at mid-scale mills with limited project finance access.
- Food-contact certification timelines:EFSA novel food assessments for recycled fiber in direct contact applications extend product development cycles by 18-24 months.
- Barrier chemistry IP fragmentation:Proprietary coating formulations from competing technology licensors complicate multi-product line strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paper Market |
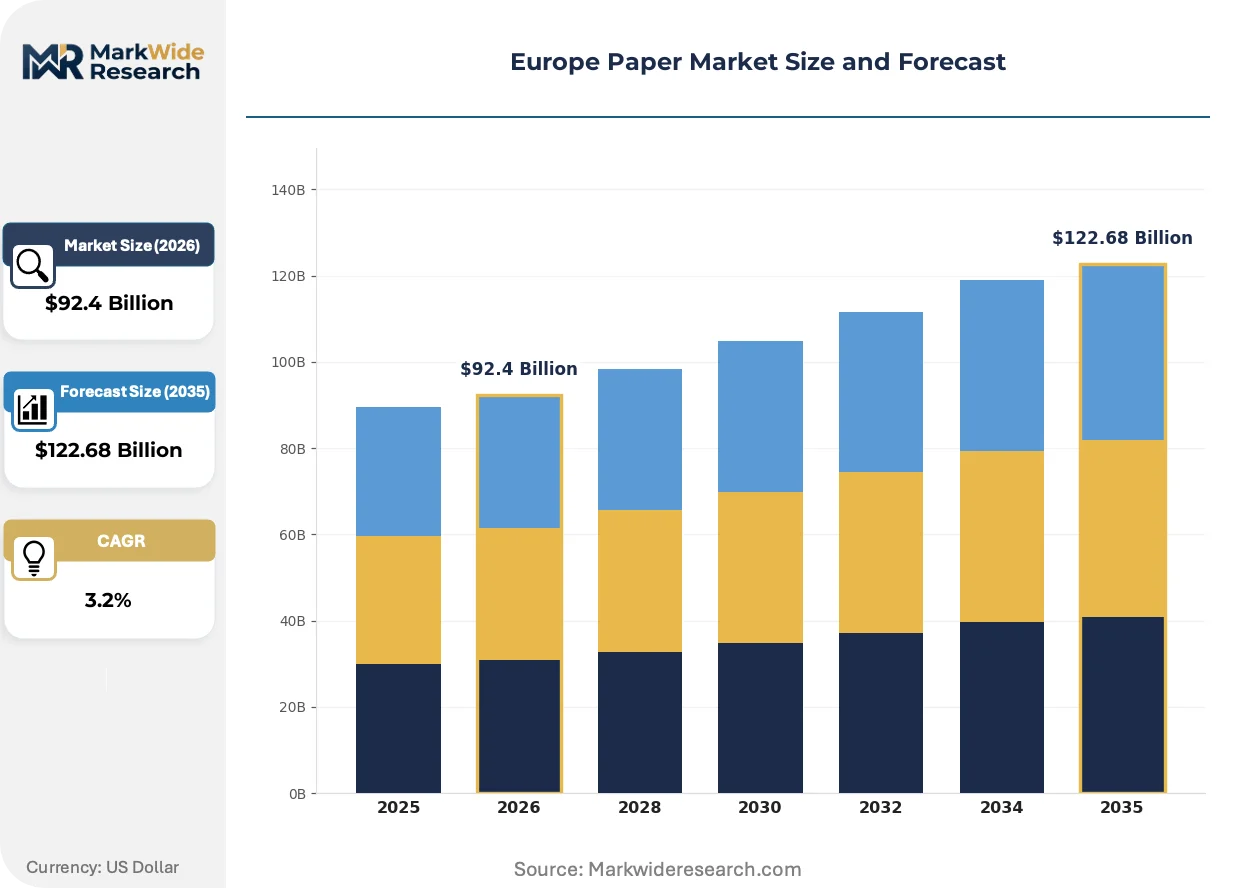
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $122.68 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Newsprint, Coated Paper, Uncoated Paper, Specialty Paper End Use Industry: Publishing, Packaging, Consumer Goods, Commercial Printing Grade: Wood-Free, Recycled, Kraft, Duplex Form: Roll, Sheet, Bulk, Custom Size |
| Companies Covered | Smurfit Kappa, Metsä Board, UPM-Kymmene, Mayr-Melnhof, DS Smith, Stora Enso, Mondi, Holmen, SCA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paper Market Shifts & Advancements
Electrification of drying sections and digital print integration are compressing the cost structure of short-run packaging. These shifts favor agile producers with modular equipment over legacy mass-scale configurations.
Heat pump drying technology is electrifying energy-intensive paper machine operations by replacing natural gas-fired hoods with electrically driven vapor recompression systems. Scandinavian mills piloting this configuration report 40-60% reductions in Scope 1 emissions. The technology is compressing the carbon intensity gap between integrated Nordic sites and southern European competitors dependent on gas grids.
The F-Gas Regulation's accelerated phase-down of per- and polyfluoroalkyl substances is eliminating incumbent grease-resistant barriers from food service applications. Coating developers race to certify cellulose-based and bio-wax alternatives through EFSA's updated food contact material pathways. Fresh-produce exporters in Spain and Italy face the steepest compliance cliffs as their current packaging specifications lose regulatory authorization.
Brand owners now specify recycled content minimums in packaging procurement contracts that exceed EU Green Deal baseline requirements. Retailers in France and the Netherlands lead this specification creep, pressuring converters to source certified circular grades. The shift fragments supplier bases as only mills with chain-of-custody certification capture premium contract tiers.
Europe Paper Market Segmentation
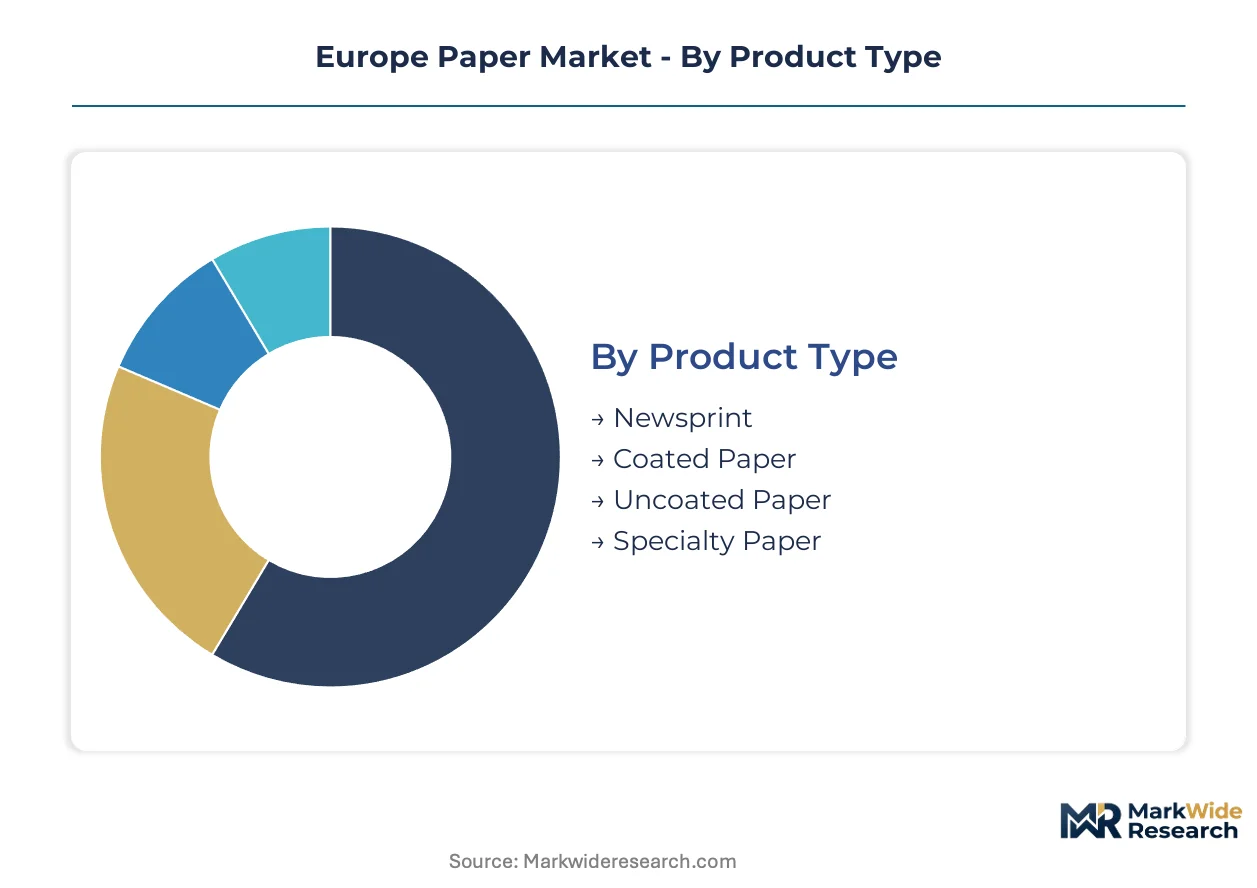
Segmentation in the Europe Paper Market reveals how fiber sourcing, coating technologies, and format specifications fragment procurement patterns. Buyers in publishing, packaging, and consumer goods each impose distinct technical requirements that reshape mill output mixes and investment priorities.
Product Type:
Standardization dominates newsprint and uncoated grades, while specialty paper demands bespoke formulation development and dedicated production runs.
- Newsprint:Lightweight groundwood sheets engineered for high-speed rotary printing with controlled opacity and minimal linting. Publishers in Germany and France consume bulk volumes for daily newspaper production, though digital subscription models erode run lengths and frequency.
- Specialty Paper:Technical substrates spanning filtration media, thermal transfer coatings, and medical-grade sterilization wraps where functional performance commands specification premiums. Nordic integrated producers capture disproportionate margin pools through captive pulp quality control and barrier chemistry R&D.
- Coated Paper:Clay- or polymer-finished sheets delivering enhanced print gloss and ink holdout for annual reports and luxury advertising inserts.
- Uncoated Paper:Freesheet grades for office correspondence and educational materials facing structural volume pressure from enterprise digitization.
Leading the category by volume: Uncoated Paper. Growing fastest: Specialty Paper.
End Use Industry:
Application-driven specifications create divergent margin profiles, with packaging commanding premium pricing for barrier performance and printability.
- Packaging:Corrugated containerboard and folding carton grades engineered for crush resistance, moisture protection, and food-contact compliance. German e-commerce retailers specify high-performance fluting for last-mile durability, pulling fresh demand through Austrian and Polish converter networks.
- Publishing:Magazine and catalog substrates requiring bulk, brightness, and reproducible color fidelity across long print runs. French and Italian publishers consolidate orders to secure volume discounts as title counts contract.
- Consumer Goods:Label stock and flexible packaging laminates for household products and personal care applications.
- Commercial Printing:General-purpose sheets for marketing collateral, direct mail, and business stationery facing displacement by digital workflows.
Highest volume concentration: Packaging. Steepest expansion trajectory: Consumer Goods.
Grade:
Raw material provenance determines cost structure and regulatory compliance burden across the fiber spectrum.
- Recycled:Post-consumer recovered fiber processed to varying de-inking and cleanliness standards for containerboard and newsprint applications. EU Green Deal circular-economy mandates accelerate procurement shifts toward certified circular grades, though Old Corrugated Container price volatility strains converter margins.
- Wood-Free:Bleached chemical pulp sheets prized for archival stability and premium print reproduction in annual reports and art books. Swedish and Finnish integrated mills leverage hydroelectric power to produce low-carbon wood-free grades for German and Dutch publishers.
- Kraft:Unbleached virgin pulp grades delivering tear strength and moisture resistance for industrial packaging and carrier bags.
- Duplex:Two-layer boards with gray back and white front for cost-sensitive folding carton applications.
Dominant by tonnage: Recycled. Gaining share fastest: Wood-Free.
Form:
Logistics and converting equipment compatibility dictate format selection across customer scale tiers.
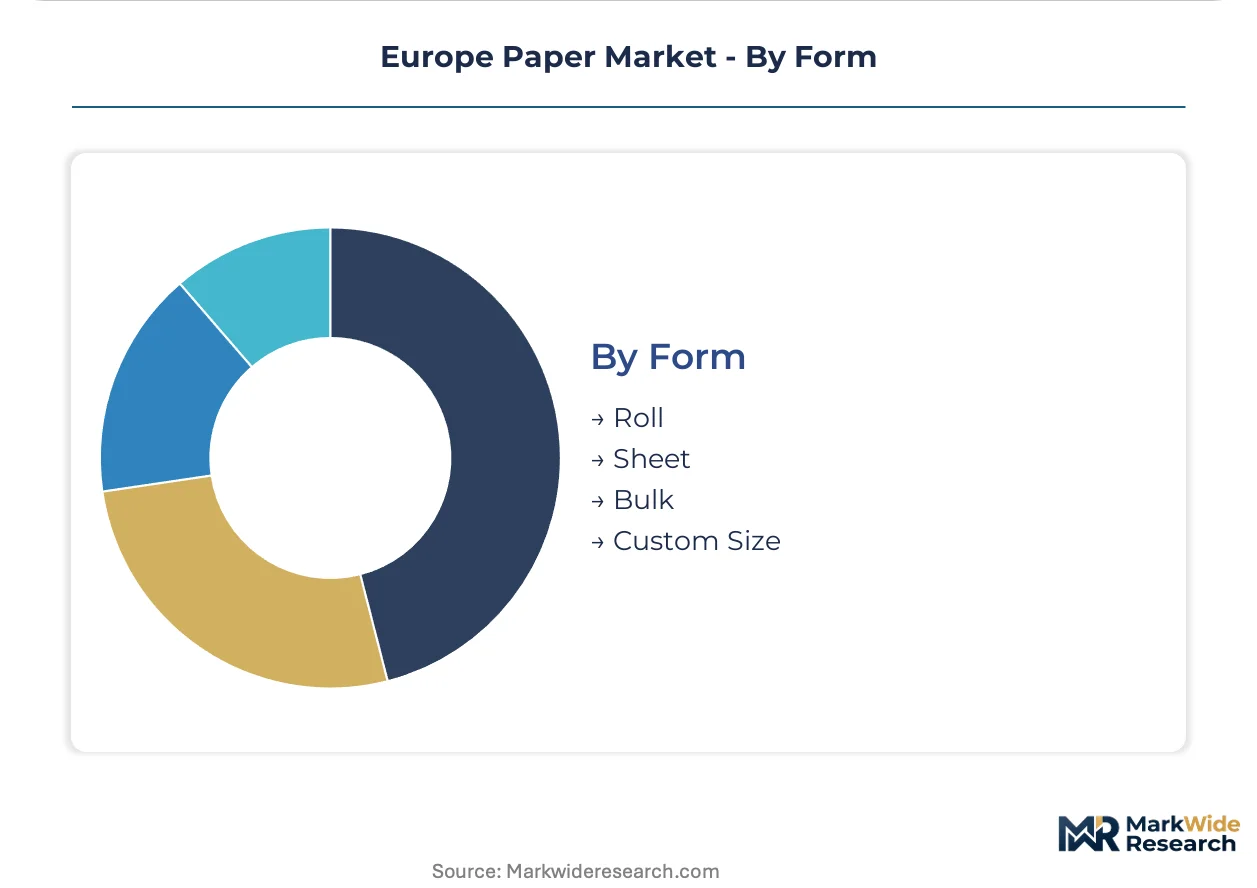
- Roll:Continuous webs for high-speed corrugators, web offset presses, and flexible packaging laminators. Large German packaging converters prefer jumbo rolls to minimize splice frequency and maximize line efficiency.
- Sheet:Cut-to-size formats for sheet-fed offset and digital print operations serving short-run commercial work.
- Bulk:Palletized loose sheets or reels for industrial users with in-house cutting capability.
- Custom Size:Dimension-specified orders for specialty equipment or unique product geometries.
Primary volume: Roll. Expanding most quickly: Custom Size.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German e-commerce retailers command the largest share of European corrugated packaging demand, pulling tonnage through Austrian and Polish converter networks. Nordic integrated producers in Sweden and Finland leverage hydroelectric power and captive pulp supply to serve premium-grade export markets. Southern European mills face stranded asset risk as EU Green Deal compliance costs accelerate faster than capital replacement cycles.
Germany
Online retail fulfillment centers in the Ruhr Valley and Berlin-Brandenburg corridor specify high-performance fluting grades for last-mile durability. The country's Packaging Act mandates minimum recycled content thresholds that exceed EU baseline requirements. Bavarian converters near the Austrian border source jumbo rolls from integrated Nordic suppliers to minimize freight costs.
Sweden
Export-oriented containerboard production serves German and Dutch packaging markets through integrated pulp-and-paper operations along the Baltic coast. National carbon pricing mechanisms and renewable energy certificates reinforce hydroelectric-powered mill economics. The Gothenburg industrial cluster hosts specialized coating development facilities for barrier chemistry innovation.
Finland
Virgin kraft pulp capacity concentrates in southeastern lake districts with captive forest ownership and energy self-sufficiency. REACH compliance protocols favor large producers with dedicated regulatory affairs teams over smaller competitors. The Kouvola region anchors folding carton board production for premium consumer goods applications.
France
Retailers in the Paris basin and Lyon corridor lead specification creep on certified circular grades exceeding EU Green Deal mandates. EFSA novel food assessments for recycled fiber in direct contact applications extend product development timelines. The Grand Est region near the German border hosts specialty paper converters serving pharmaceutical serialization requirements.
Poland
Underpenetrated domestic containerboard capacity forces packaging converters to import from German and Austrian mills at freight disadvantage. National waste collection infrastructure improvements aim to stabilize Old Corrugated Container supply for recycled-grade production. The Silesian industrial zone near Katowice clusters converting operations serving Central European distribution networks.
Europe Paper Market Competitive Landscape
Capacity expansion dominates the current landscape as mills retrofit biomass boilers and carbon capture installations to absorb EU Green Deal compliance costs. The vendor base concentrates around large integrated producers with captive pulp supply and dedicated regulatory capacity, while mid-scale independents face consolidation pressure. Three archetypes define competitive positioning: Nordic hydroelectric-integrated giants, southern European gas-dependent independents, and specialty-grade technical developers. M&A activity and barrier chemistry IP licensing represent the dominant competitive vectors as mills race to certify fluorine-free food-contact coatings.
Within the integrated Nordic tier, Smurfit Kappa and Stora Enso exemplify scale-driven positioning through containerboard network density across Ireland and continental Europe. Mondi occupies a specialist position in barrier-coated kraft solutions. These three companies anchor the competitive structure through contrasting geographic and technical specialization strategies.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Metsä Board |
| UPM-Kymmene |
| Mayr-Melnhof |
| DS Smith |
| Stora Enso |
| Mondi |
| Holmen |
| SCA |
| Others |
Supply & Pricing Matrix
Electrification of paper machine drying sections is compressing cost structures while concentrating supply advantages among Nordic mills with hydroelectric access. This technology shift simultaneously widens the carbon-intensity gap between integrated northern European producers and gas-dependent southern competitors, reshaping regional pricing power.
Pricing Analysis
Volume-margins split sharply between commodity containerboard and specialty grades. Three-tier pricing structure across premium, standard, and economy levels separates chain-of-custody certified circular grades from uncertified recycled tonnage and virgin kraft alternatives. Pricing pressure stems from Old Corrugated Container cost volatility as Asian export demand competes for European recovered fiber. German e-commerce retailers show lowest price sensitivity for high-performance fluting specifications, while southern European independents face acute margin compression from energy cost differentials.
Supply Chain Analysis
Direct-to-converter channels handle German retailer demand through jumbo roll shipments from Swedish and Finnish integrated mills. Raw material sourcing draws from Baltic Sea pulp terminals, German OCC collection networks, and Austrian folding carton converters. Single-source vulnerability concentrates in virgin kraft pulp capacity controlled by Nordic lake-district operations. Distribution runs through Ruhr Valley logistics hubs and Polish Silesian industrial zones serving Central European packaging networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal compliance costs accelerate faster than capital replacement cycles, forcing mid-scale independents toward exit or acquisition.
For Market Incumbents: Anticipate barrier chemistry IP licensing races as EFSA novel food assessments extend fluorine-free coating development timelines. Secure captive pulp supply through backward integration into Baltic forest ownership to defend margin position against energy cost volatility. Prioritize regulatory affairs capacity investment to capture food-contact coating share as REACH compliance costs exclude smaller competitors. For New Entrants and Emerging Players: Capture underpenetrated Polish and Czech containerboard markets where domestic capacity gaps force converters to import at freight disadvantage. Target pharmaceutical serialization substrates in France's Grand Est region as track-and-trace mandates drive thermal transfer demand. Lead with modular short-run equipment configurations that exploit electrification trends against legacy mass-scale competitors. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic hydroelectric-integrated specialists given carbon-border adjustment mechanics and renewable energy certificate premiums. Five-to-ten year viability favors mills with chain-of-custody certification and barrier chemistry R&D pipelines over gas-dependent southern European assets. Monitor F-Gas Regulation phase-down velocity as inflection indicator for grease-resistant food packaging grade substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Boiler Retrofit | Swedish mills absorb EU Green Deal carbon costs through hydroelectric-powered thermal integration. |
| Barrier Chemistry Licensing | EFSA novel food pathways extend development cycles for fluorine-free grease-resistant coatings. |
| Backward Integration into Forestry | Finnish lake-district producers secure captive pulp supply against OCC price volatility. |
| Modular Digital Print Integration | Agile converters compress short-run packaging economics against legacy mass-scale configurations. |
| Chain-of-Custody Certification | French retailers specify certified circular grades exceeding EU Green Deal baseline mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Paper Market assessment. Primary interviews with mill operations directors, corrugated converter procurement leads, and brand owner packaging specification managers combined with Cefic sector reports, ECHA REACH registration databases, and EU customs export records. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Reconciliation of production capacity databases, energy consumption disclosures, and end-use consumption surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, fiber grade, and geographic production hub. CAGRs derived from trend extrapolation of e-commerce packaging intensity, digital displacement rates for uncoated freesheet, and barrier-coated kraft substitution trajectories. Forecast inputs incorporated EU Green Deal compliance cost curves and F-Gas Regulation phase-down schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to energy price trajectories, regulatory enforcement timelines, and Asian recovered fiber export demand shifts. Base assumptions reflect continued electrification investment, stable Nordic hydroelectric capacity, and progressive tightening of food-contact material standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Paperboard Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Carbonless Paper Market
Paper Products
Paper Products Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
North America Specialty Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Global Copier Paper Market
Paper Products
White Top Testliner Market
Paper Products
Paper Doilies Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Paper Based Laminates Market
Paper Products
Pigmented Paper Market
Paper Products
Printing Paper Market