
 Senior Cat Food Market | 2026-2036
Senior Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Senior Cat Food Market Analytics
The premium-commodity split in senior cat nutrition is pivoting on ingredient transparency and clinical validation. Royal Canin leverages veterinary channel partnerships to sustain prescription-grade positioning. Mars Petcare anchors mass-market volume through scaled manufacturing. Hill's Pet Nutrition differentiates on science-backed formulations developed in collaboration with veterinary nutritionists.
Senior cat food denotes formulations engineered for felines aged seven years and older, typically featuring reduced phosphorus, enhanced omega-3 fatty acid content, and digestible protein sources to support renal function and joint health. Wet food commands margin pools due to palatability advantages and hydration benefits for aging cats with declining thirst drive. High protein and limited ingredient formulations attract owners managing food sensitivities or diabetes in geriatric pets.
FDA Center for Veterinary Medicine oversight of pet food labeling and safety shapes product development timelines and substantiation requirements for health claims. The Association of American Feed Control Officials establishes nutrient profiles that manufacturers must meet for senior life-stage designation. Stakeholders should monitor evolving state-level enforcement of feed safety rules and shifting veterinary consensus on optimal protein levels for cats with early-stage kidney disease.
Market Dynamics
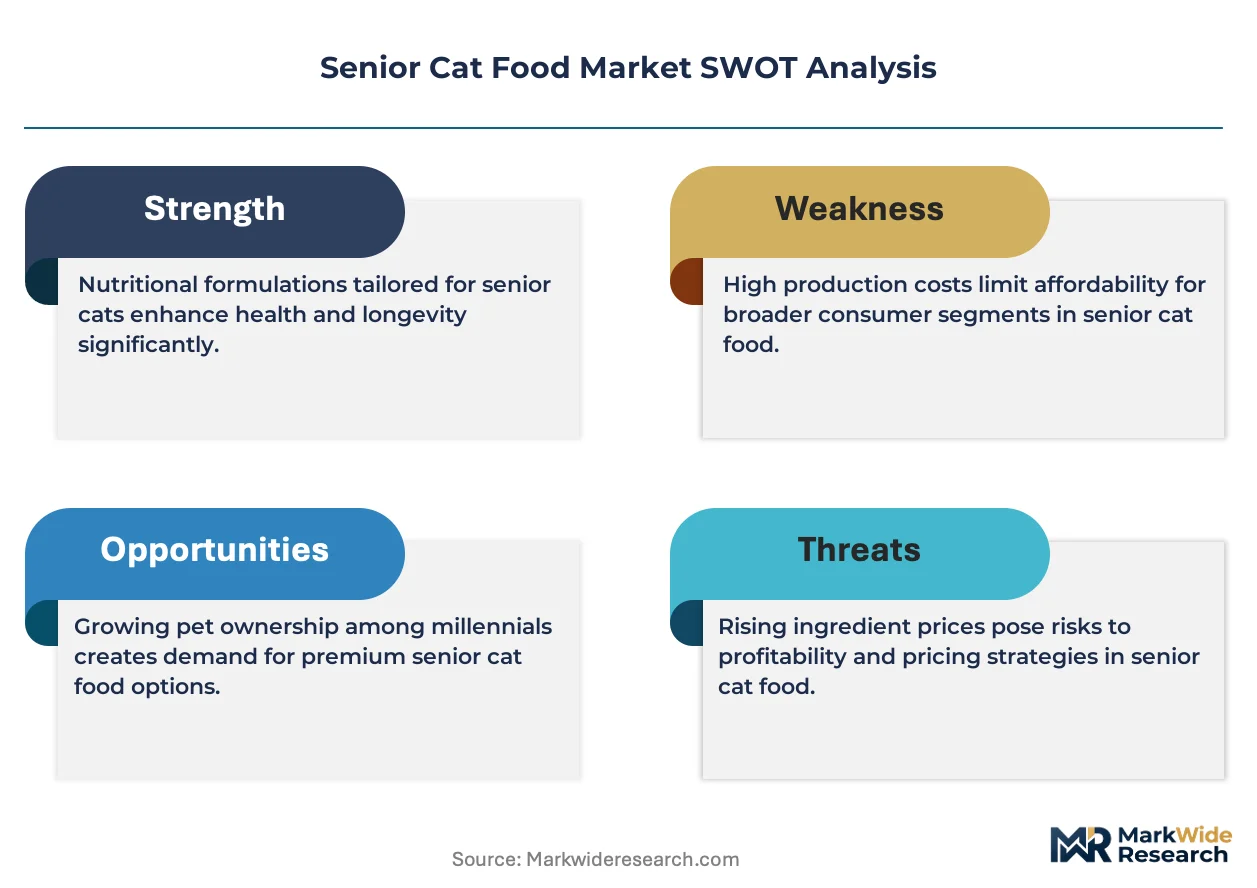
Veterinary channel consolidation and FDA Center for Veterinary Medicine label substantiation requirements are compressing product development timelines while elevating capital barriers for new entrants seeking age-specific formulation claims.
Growth Catalysts
- AAFCO Nutrient Profiles:The Association of American Feed Control Officials senior life-stage designation creates a compliance pathway that legitimizes premium pricing for clinically validated formulations in US pet specialty retail.
- Wet Food Palatability:Hydration-conscious formulations address declining thirst drive in aging felines, driving repeat purchase rates among owners managing renal health proactively.
- Omega-3 Sourcing:Antarctic krill and algae-derived DHA supply chains are stabilizing, enabling consistent formulation of joint-support claims without marine oil volatility.
Market Restraints
- Phosphorus Input Concentration:US Midwest phosphate mining consolidation exposes formulators to price volatility for renal-support low-phosphorus recipes.
- Veterinary Channel Gatekeeping:Prescription diet authorization requirements in North American clinics limit direct-to-consumer scaling for clinically positioned brands.
- Protein Source Substitution:Insect and cultivated protein alternatives face palatability rejection in taste-preference testing with geriatric cats.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Chewy and Amazon Pet are capturing recurring revenue from urban owners seeking convenience without veterinary clinic visits.
- State-Level Feed Safety Harmonization:California and New York inspection protocol alignment reduces multi-state compliance duplication for regional manufacturers.
- Diabetes Management Crossover:Limited-carbohydrate senior formulations are migrating from prescription to over-the-counter positioning as glycemic monitoring home kits proliferate.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Board-certified veterinary nutritionists command premium consulting fees, constraining smaller formulators' R&D bandwidth.
- Clinical Trial Timeline Compression:FDA substantiation requirements for health claims extend product launch windows while competitor formulations reach shelf faster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Senior Cat Food Market |
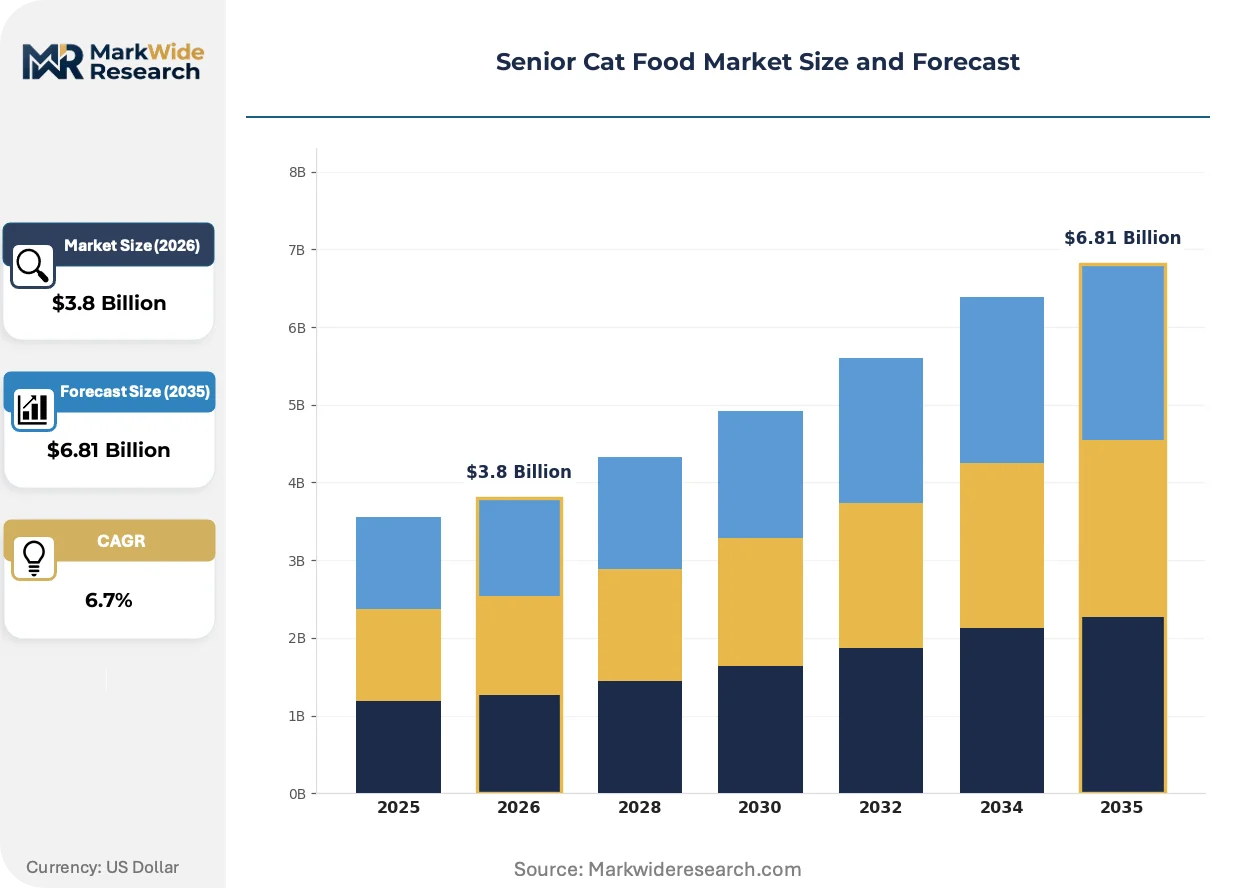
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Food, Dry Food, Treats, Supplements Ingredient Type: Natural, Grain-Free, High Protein, Limited Ingredient Package Size: Small Bags, Large Bags, Cans, Pouches Brand Type: Premium, Value, Private Label, Veterinary |
| Companies Covered | Smalls, Royal Canin, Mars Petcare, Purina Pro Plan, Fancy Feast, Nestlé Purina PetCare, Iams, Acana, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Senior Cat Food Market Evolving Landscape
Ingredient traceability systems and personalized nutrition algorithms are converging to transform how owners select age-appropriate formulations, shifting competitive advantage from mass manufacturing to data-driven recommendation engines.
Cold-pressed gentle cooking technology is unifying nutrient retention with pathogen control in wet food production. Mid-size manufacturers in the Pacific Northwest and New England are retrofitting canning lines to adopt lower-temperature processing that preserves heat-sensitive taurine and B-vitamins. This convergence is unifying artisan positioning with shelf-stable logistics, compressing the historical trade-off between premium nutrition and distribution reach.
The FDA Center for Veterinary Medicine's 2023 guidance on animal food labeling modernization is mandating quantitative calorie statements and standardized feeding directions. Small-batch manufacturers face reformulation costs to meet uniform serving-size disclosures. The natural and organic segment is responding fastest, with co-manufacturers in Oregon and Vermont accelerating label redesigns to maintain specialty retail placement.
Subscription-based auto-delivery is displacing periodic retail replenishment among millennial and Generation Z cat owners. Chewy's predictive reorder algorithms and personalized portion calculators are capturing household-level purchasing data that informs flavor and texture preferences. This behavioral shift concentrates most visibly in coastal metropolitan areas where veterinary clinic density overlaps with same-day delivery infrastructure.
Senior Cat Food Market Segmentation
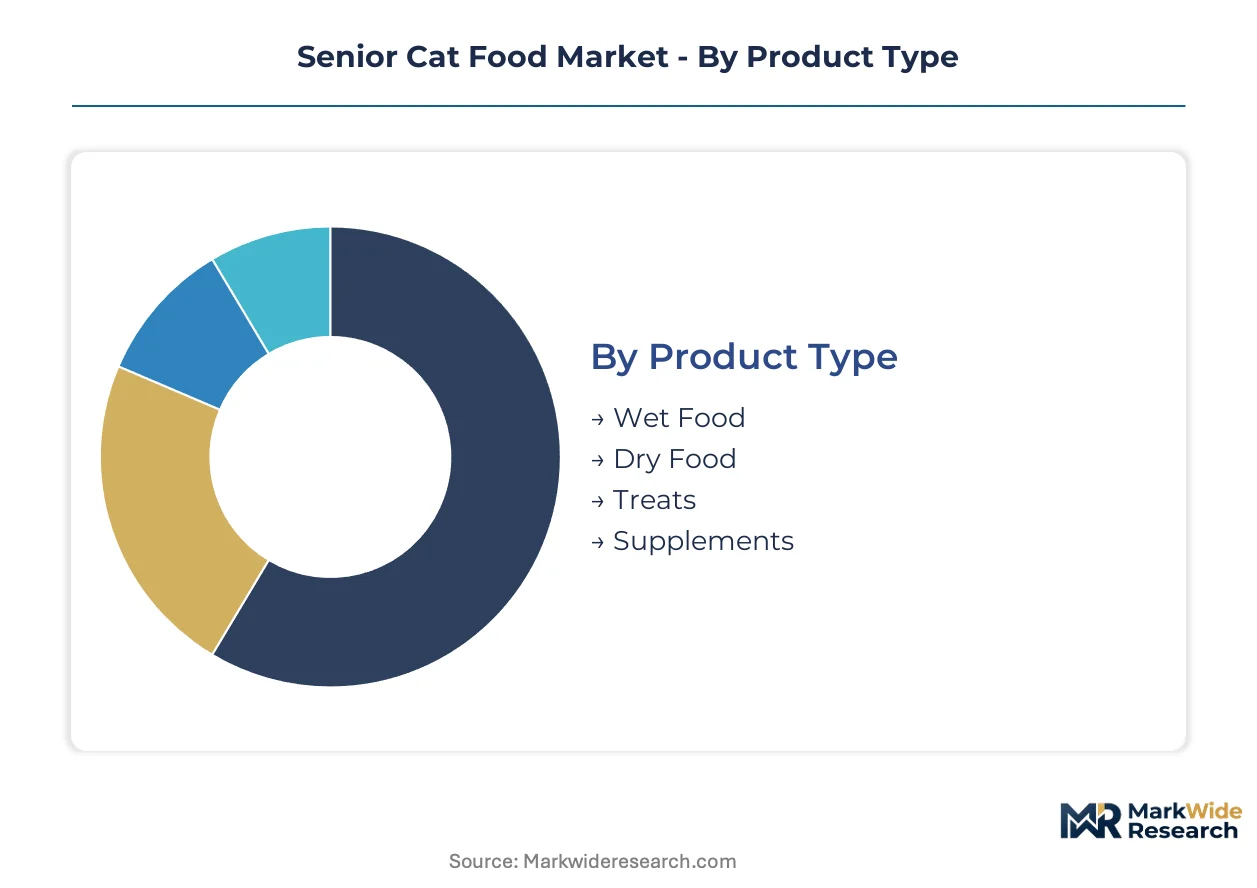
Senior cat food segmentation reflects divergent owner priorities: clinical outcomes versus convenience, ingredient purity versus cost discipline, and veterinary guidance versus autonomous purchasing. Manufacturers configure production lines and distribution channels around these fractures.
Product Type:
Customization intensity varies sharply across this category, with veterinary-prescribed formulations demanding batch-level flexibility while mass-market dry food runs on continuous processing.
- Wet Food:Moisture content of 75-85% supports renal function in aging cats with diminished thirst response. Palatability advantages drive repeat purchases among owners managing early-stage kidney disease in urban households with veterinary clinic access.
- Dry Food:Kibble formulations enable free-feeding convenience and extended shelf stability. Demand concentrates in suburban markets where cost-per-serving calculations dominate purchase decisions.
- Treats:Functional formulations deliver joint-support compounds or dental abrasion in controlled portions.
- Supplements:Omega-3 capsules and probiotic powders address specific geriatric conditions outside complete diet replacement.
Most installed capacity flows through Dry Food. Expansion is steepest in Wet Food.
Ingredient Type:
Margin capture in this category tracks ingredient certification burden and supply chain traceability investment.
- Natural:USDA Organic or non-GMO verification commands shelf space in specialty retailers. Premium pricing reflects batch testing for pesticide residues and synthetic additive exclusion.
- Grain-Free:Tapioca and legume carbohydrate substitutes address owner perceptions of feline dietary evolution. Demand clusters in coastal metropolitan markets with high veterinary clinic density.
- High Protein:Animal-derived protein exceeds 40% dry matter to preserve lean muscle mass in sedentary geriatric cats.
- Limited Ingredient:Single-protein and single-carbohydrate formulations reduce allergen exposure for cats with food sensitivities.
Natural captures the highest revenue per pound. Grain-Free is gaining share fastest among millennial owners.
Package Size:
Packaging economics in this category hinge on household penetration rates and storage constraint variation across housing types.
- Small Bags:Under 4-pound dry food packaging suits single-cat households and trial purchases. Urban apartment dwellers with limited pantry space drive volume.
- Large Bags:Bulk formats reduce per-ounce cost for multi-cat households. Suburban and rural markets with dedicated pet food storage areas sustain demand.
- Cans:Traditional metal packaging for wet food supports portion control and refrigerator storage after opening.
- Pouches:Flexible single-serve formats eliminate leftovers and enable precise calorie tracking for diabetic cats.
Large Bags dominate volume throughput. Pouches are expanding most quickly in direct-to-consumer channels.
Brand Type:
Channel access and professional endorsement separate tiers in this category, with veterinary authorization creating the steepest pricing premium.
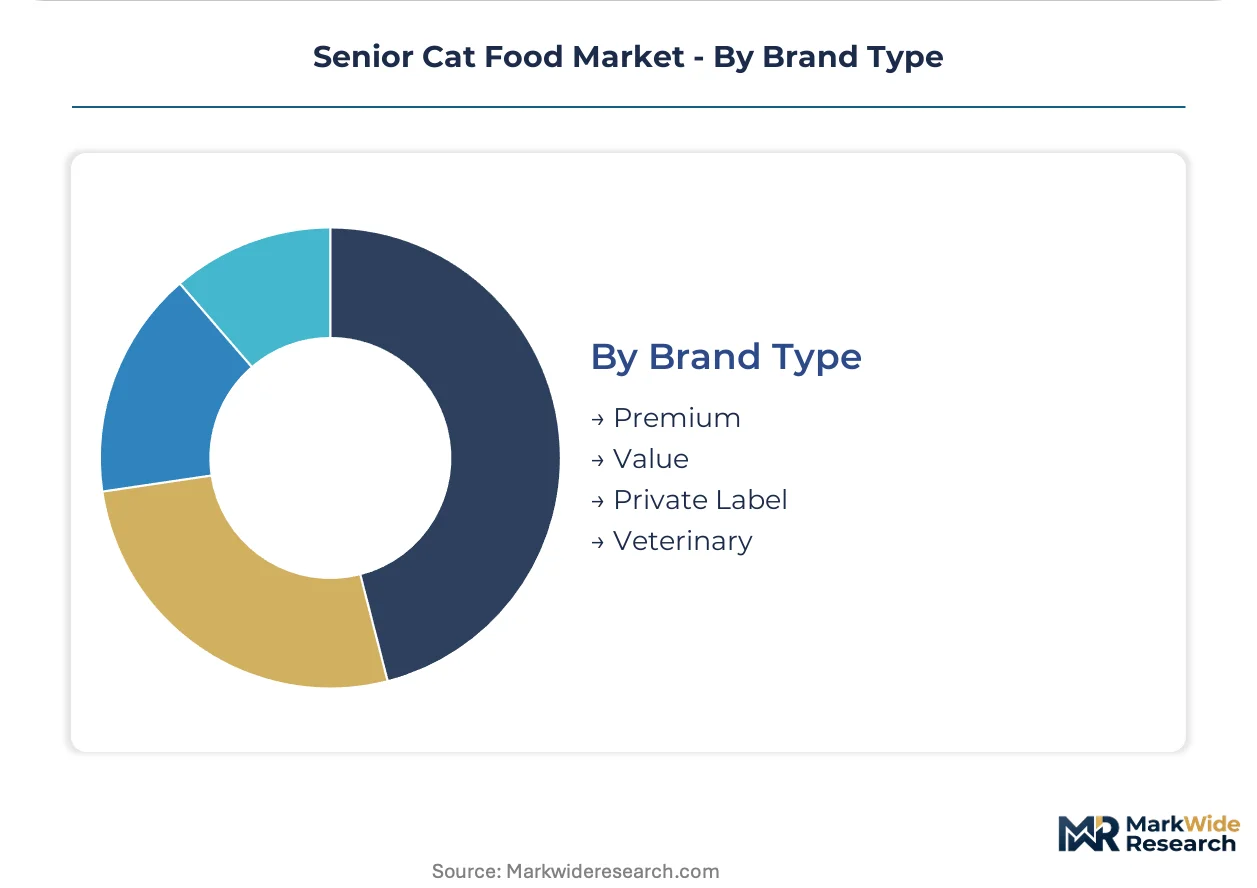
- Premium:Mass-market brands with above-average ingredient quality and life-stage specific formulations. Retail placement in pet specialty chains supports margin.
- Value:Price-focused offerings in grocery and big-box channels. Ingredient sourcing prioritizes cost stability over provenance documentation.
- Private Label:Retailer-controlled brands manufactured by co-packers. Chewy and Amazon Pet deploy proprietary formulations to capture subscription revenue.
- Veterinary:Prescription authorization requirements restrict distribution to clinic channels. FDA substantiation for therapeutic claims extends development timelines.
Premium commands the broadest retail footprint. Veterinary is climbing the fastest as chronic disease management shifts to proactive nutrition intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified veterinary nutritionists cluster in university towns and research corridors, anchoring formulation science in specific metropolitan zones where pet food R&D commands premium talent acquisition budgets.
United States
Veterinary channel consolidation in the Midwest and Southeast drives prescription diet demand, while FDA Center for Veterinary Medicine label substantiation requirements extend product development timelines. State-level feed safety inspections in California and New York create compliance friction for multi-state manufacturers. The Pacific Northwest hosts cold-pressed wet food retrofitting clusters in Oregon and Washington.
Germany
Urban pet ownership in Berlin and Munich sustains demand for natural and organic senior formulations with full ingredient traceability. EFSA pet food safety standards and national feed regulation enforcement create high barriers for imported brands. The Bavarian industrial corridor around Munich anchors co-manufacturing capacity for premium private label production.
United Kingdom
Subscription auto-delivery penetration concentrates in London and Southeast England where same-day delivery infrastructure overlaps with high veterinary clinic density. FSA pet food labeling requirements and post-Brexit import certification add compliance layers for continental European suppliers. The Midlands hosts dry food manufacturing scale for value-tier export.
Japan
Aging pet demographics in Tokyo and Osaka metro areas elevate demand for renal-support and joint-health formulations. MAFF and MHLW joint oversight of pet food safety mandates rigorous additive testing and nutritional adequacy verification. The Chubu region around Nagoya maintains wet food canning infrastructure serving domestic and export markets.
Australia
High-protein natural formulations gain traction in Sydney and Melbourne where pet humanization trends intersect with disposable income concentration. TGA-aligned state feed safety regulators enforce import quarantine protocols that protect domestic manufacturers. Queensland's pet food manufacturing belt scales grain-free and limited-ingredient production for Asia-Pacific export.
Senior Cat Food Market Competitive Landscape
Top-tier vendors anchor the veterinary-prescription segment, while mass-market manufacturers compete on manufacturing scale and retail shelf space access. The market structure stratifies across three tiers: science-backed therapeutic brands with clinic channel exclusivity, premium natural-positioned players in pet specialty retail, and value-focused commodity producers in grocery and big-box channels. Dominant competitive moves include co-manufacturer acquisition for capacity control and direct-to-consumer platform building to bypass veterinary gatekeeping.
Within the veterinary-anchored tier, Royal Canin and Hill's Pet Nutrition occupy positions defined by prescription authorization requirements and clinical validation investment. Mars Petcare and Nestlé Purina PetCare exemplify scale-driven mass-market archetypes with diversified brand portfolios spanning premium through value positioning. Smalls represents the direct-to-consumer challenger model built on subscription infrastructure and urban market concentration.
| Leading Market Players |
|---|
| Smalls |
| Royal Canin |
| Mars Petcare |
| Purina Pro Plan |
| Fancy Feast |
| Nestlé Purina PetCare |
| Iams |
| Acana |
| Hill's Pet Nutrition |
| Others |
Value Network & Pricing Analysis
Cold-pressed gentle cooking technology is compressing the historical trade-off between premium nutrition and shelf-stable logistics, simultaneously elevating capital requirements for wet food retrofits and concentrating margin capture among mid-size manufacturers with Pacific Northwest and New England facility access.
Pricing Analysis
The bundled-vs-unbundled service split separates veterinary-authorized prescription diets from over-the-counter retail formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and clinical validation investment. Pricing pressure stems from FDA label substantiation requirements extending development timelines while competitor formulations reach shelf faster. Value-tier buyers in suburban mass-market channels exhibit highest price sensitivity; veterinary-anchored purchasers accept premium positioning for renal-support and diabetes-management formulations.
Supply Chain Analysis
Reverse-logistics flows for prescription diet returns and expired veterinary inventory create specialized handling requirements distinct from standard retail channels. Supply concentrates in the United States for corn and soy protein inputs, Thailand for tuna and seafood sourcing, and New Zealand for lamb and novel protein alternatives. Formulators draw from Antarctic krill and algae-derived DHA supply chains for omega-3 stability. Single-source vulnerability in US Midwest phosphate mining exposes low-phosphorus renal formulations to input volatility. Distribution runs through pet specialty retailers, veterinary clinics, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Senior Cat Food Market functions as a regulatory compounder where FDA Center for Veterinary Medicine label modernization and state-level feed safety harmonization continuously elevate compliance barriers that favor incumbents with veterinary channel infrastructure.
For Market Incumbents: Extend veterinary nutritionist consulting relationships to sustain prescription-grade positioning against direct-to-consumer challengers. Deepen backward integration into cold-pressed wet food manufacturing capacity in Oregon and Washington to capture artisan-positioning margin pools. Fortify clinic channel exclusivity through Hill's Pet Nutrition and Royal Canin-style science-backed formulation partnerships. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription infrastructure targeting urban millennial and Generation Z owners in coastal metropolitan areas with same-day delivery overlap. White-space concentrates in limited-carbohydrate senior formulations migrating from prescription to over-the-counter positioning as home glycemic monitoring kits proliferate. Go-to-market angle: personalized nutrition algorithms leveraging household-level purchasing data from Chewy-style predictive reorder systems. For Investors and Strategic Acquirers: Roll-up economics work for mid-size natural and organic manufacturers because co-manufacturer acquisition in Vermont and Oregon accelerates label redesign capacity for FDA compliance. Long-term viability hinges on veterinary channel access and cold-pressed production retrofit capability. Acquisition target archetype: Pacific Northwest wet food specialists with artisan positioning and shelf-stable logistics. Signal to watch: state-level feed safety inspection protocol alignment between California and New York reducing multi-state compliance duplication.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Prescription authorization requirements in North American clinics sustain pricing premium for clinically validated formulations. |
| Cold-Pressed Retrofit Investment | Oregon and Washington facility upgrades preserve heat-sensitive taurine and B-vitamins in wet food production. |
| Direct-to-Consumer Platform Build | Chewy and Amazon Pet predictive reorder algorithms capture recurring revenue from urban convenience-seeking owners. |
| Omega-3 Supply Diversification | Antarctic krill and algae-derived DHA sourcing reduces marine oil price volatility for joint-support claims. |
| State-Level Compliance Harmonization | California and New York inspection protocol alignment reduces regulatory friction for regional manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged veterinary nutritionists, pet specialty retail category managers, co-manufacturer operations directors, FDA regulatory affairs specialists, and direct-to-consumer platform product leads. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, AAFCO nutrient profile standards, state feed safety inspection records, and pet specialty retail audit data. Bottom-up formulation demand modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across wet food, dry food, treats, and supplements by product type; natural, grain-free, high protein, and limited ingredient by formulation; and premium, value, private label, and veterinary by brand tier. CAGRs were derived from growth rate reconciliation across the projection horizon. Industry-specific inputs included veterinary clinic density mapping, cold-pressed manufacturing capacity tracking, and subscription auto-delivery penetration by metropolitan area.
Inputs from FDA guidance releases and AAFCO proceedings were available through the study window; gaps in real-time veterinary prescription authorization data introduce uncertainty bands around clinic channel volume estimates. Forecasts reflect documented assumptions regarding regulatory timeline adherence and protein source palatability acceptance in geriatric taste-preference testing. Practitioners should monitor state-level feed safety enforcement intensity and shifting veterinary consensus on optimal protein levels for early-stage kidney disease for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Astrology Market
Others
Rotary Dial Machine Market
Others
GCC Health and Wellness Market
Others
Pickup Truck Market
Others
Cloud DVR Market
Others
Roasted Wheat Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Smart Home Water Softener Market
Others
Global Extruded Plastics Market
Others
Asia-Pacific Air Separation Unit Market
Others
Smart Home Service Market
Others
Augmented Shopping Market
Others
Europe Postal Services Market
Others
Mainframe Market
Others
Durian Market