
 High-End Servers Market | 2026-2036
High-End Servers Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Servers Market Insights
Subscription-based management and software-defined orchestration layers is shifting how vendors monetize high-end server deployments. Hewlett Packard Enterprise Development LP leverages its GreenLake platform to extend recurring revenue beyond hardware cycles. Dell Inc. anchors its competitive stance through direct supply chain control and custom silicon partnerships. Fujitsu Limited specializes in ARM-based supercomputing architectures for national laboratory contracts in Japan and Europe.
High-end servers are enterprise-grade compute systems built around multi-socket processor configurations, error-correcting memory subsystems, and redundant power architectures designed for continuous uptime in mission-critical environments. These systems typically deploy liquid cooling or advanced air-flow management to sustain thermal design power exceeding 400 watts per CPU socket in dense rack configurations. Rack servers occupy the dominant volume position due to hyperscale data center standardization, while blade server configurations retain margin advantages in financial services and telecommunications where space constraints command premium pricing. AMD EPYC and Intel Xeon processor lines define the technology landscape, with ARM gaining traction in cloud-native and HPC workloads seeking performance-per-watt optimization.
The EPA ENERGY STAR program and EU Green Deal efficiency thresholds are tightening standby and active power requirements, compelling manufacturers to redesign power delivery and thermal management subsystems. NIST cybersecurity frameworks and ISO 27001 certifications increasingly gate market access for government and financial sector procurement. Buyers must evaluate processor roadmaps against emerging workload patterns in generative AI inference and confidential computing to avoid stranded infrastructure investments.
Market Dynamics
Generative AI training clusters and inference workloads are compressing refresh cycles and forcing hyperscale buyers to pre-commit to multi-year processor roadmaps before silicon tape-out.
Growth Catalysts
- EU Green Deal efficiency mandates:Liquid-cooled rack architectures now qualify for preferential procurement scoring in Frankfurt and Amsterdam data center developments.
- Confidential computing workloads:Financial services and healthcare verticals are deploying trusted execution environment capabilities for regulated data processing.
- Hyperscale construction in Northern Virginia:Dominion Energy and local utilities are provisioning dedicated substations to support multi-gigawatt campus expansions.
Market Restraints
- Advanced packaging substrate shortage:Taiwan-based ABF substrate suppliers cannot match CoWoS and EMIB demand from NVIDIA and AMD AI accelerators.
- EPA ENERGY STAR 3.0 standby thresholds:Power supply redesigns for sub-5W idle states extend qualification timelines by 8-14 months.
- Neuromorphic and photonic computing prototypes:Intel Labs and IBM Research demonstrations threaten von Neumann architectures for specific inference patterns.
Strategic Opportunities
- Sovereign cloud infrastructure in Germany:Gaia-X compliance requirements are creating certified-hardware procurement pools outside US hyperscale supply chains.
- Direct liquid cooling standardization:Open Compute Project and ASHRAE guidelines are converging to enable multi-vendor cold plate interoperability.
- Japan's Fugaku-class procurement pipeline:RIKEN successor architectures and regional weather modeling centers sustain ARM-based supercomputing demand.
Industry Challenges
- Power delivery engineering scarcity:48V bus architecture and transient load management expertise concentrates among former telecom rectifier specialists.
- ISO 27001 and NIST 800-53 certification backlog:Government and financial sector deployments face 6-9 month security validation queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Servers Market |
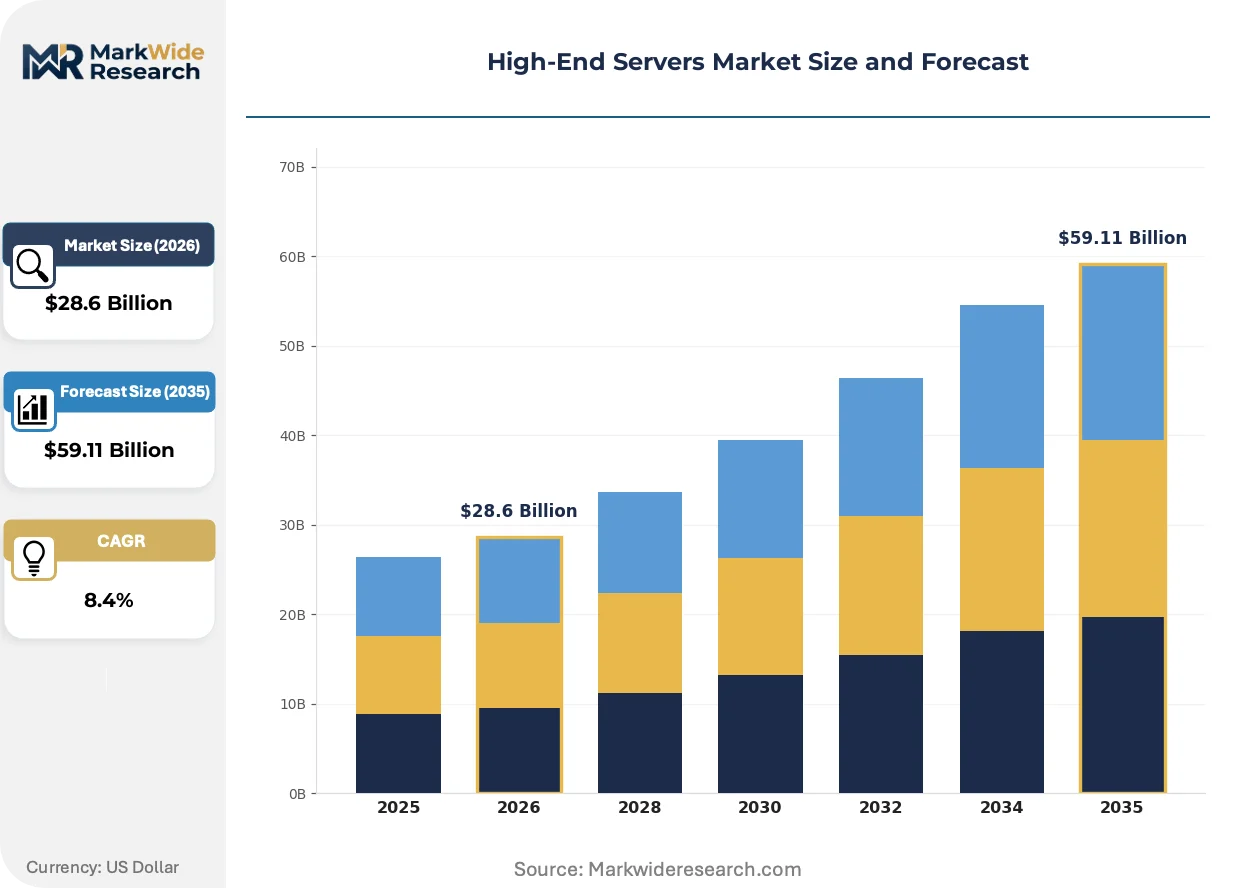
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Mainframe Servers Technology: AMD EPYC, Intel Xeon, ARM, IBM Power End User: Data Centers, Enterprises, Government, Cloud Service Providers Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Hewlett Packard Enterprise Development LP, Cisco Systems Inc., Dell Inc., Supermicro, Fujitsu Limited, Amazon Web Services, Oracle Corp., OVH Cloud, IBM Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Servers Market Trends and Innovations
Compute density requirements are outpacing air-cooling physics, forcing simultaneous redesign of chip packaging, rack power distribution, and facility thermal infrastructure.
Direct-to-chip liquid cooling is consolidating around cold plate and manifold standards from the Open Compute Project. Hyperscale operators in Phoenix and Singapore are deploying single-phase and two-phase systems at 50kW-plus rack densities. This thermal approach is consolidating vendor selection criteria around fluid compatibility testing and long-term corrosion warranties rather than legacy air-flow certification.
EPA ENERGY STAR server specifications and EU Ecodesign regulations are tightening active-mode efficiency thresholds for idle, 10%, 50%, and 100% load states. Manufacturers must now submit third-party test data across multiple workload profiles before federal procurement eligibility. Financial services buyers in London and Singapore are prioritizing certified configurations to meet CSRD Scope 3 reporting obligations.
Cloud service providers are pre-purchasing multi-year server allocations through custom silicon partnerships and direct foundry relationships. Traditional OEM distribution through value-added resellers is losing share in the 10,000-unit-plus transaction tier. This pattern is most pronounced in Northern Virginia, Frankfurt, and Shanghai where hyperscale self-build programs bypass standard channel economics entirely.
High-End Servers Market Segmentation
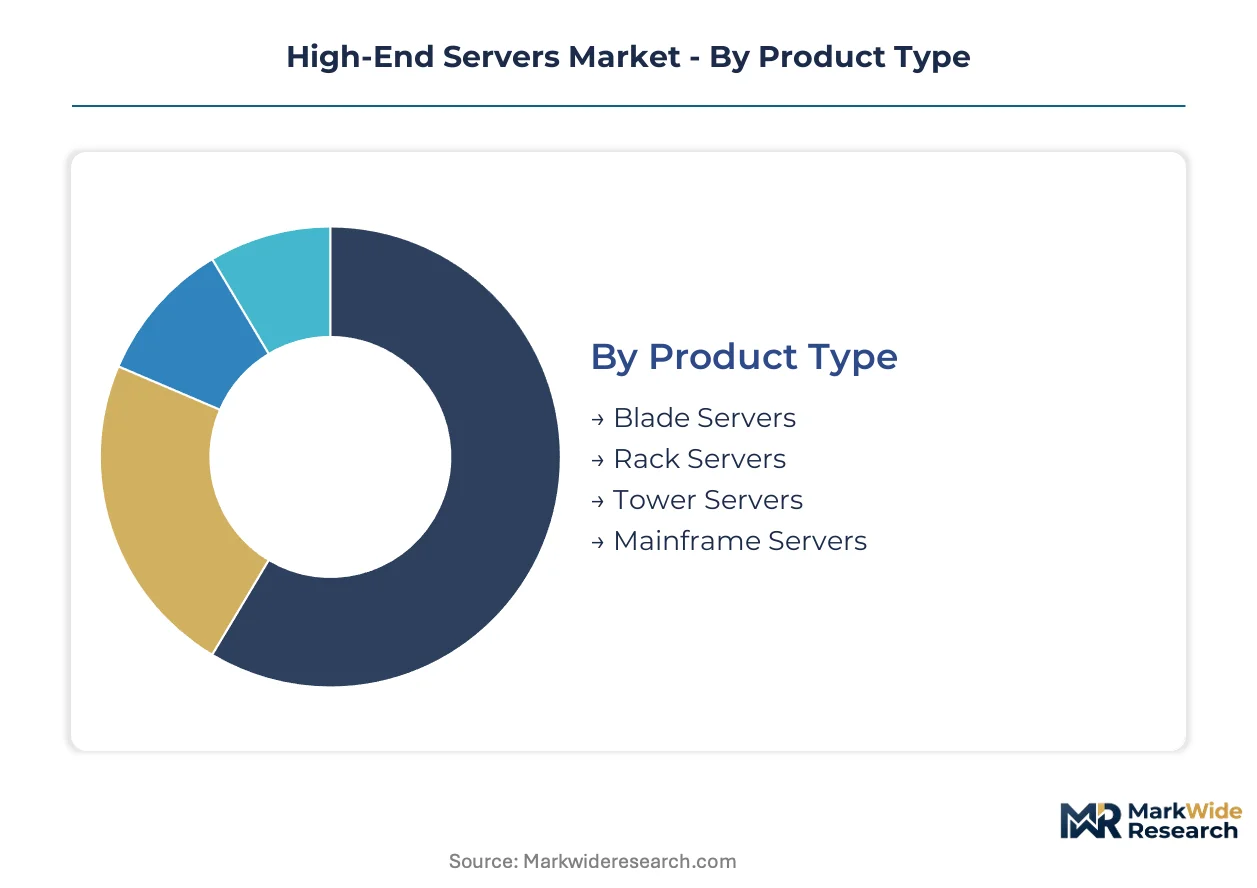
High-end server procurement patterns diverge sharply across deployment contexts, with hyperscale operators favoring stripped-down rack configurations while regulated enterprises demand integrated blade systems with embedded management. Understanding these segment boundaries clarifies where vendor specialization creates pricing power versus where standardization erodes margins.
Product Type:
Rack and blade architectures dominate standalone deployments, while tower and mainframe configurations persist in embedded or legacy-integrated environments.
- Rack Servers:Standardized 19-inch form factors with multi-socket CPU support and hot-swappable power supplies. Hyperscale data centers in Northern Virginia and Frankfurt specify these for density-optimized AI training clusters where thermal design power exceeds 400 watts per socket.
- Blade Servers:Modular chassis-based systems sharing power, cooling, and network fabrics across multiple compute nodes. Financial services firms in London and Singapore deploy these for space-constrained trading floors where chassis-level redundancy justifies premium pricing.
- Tower Servers:Vertical standalone units with acoustic dampening for office environments. Regional healthcare networks and small manufacturing operations retain these where rack infrastructure is unavailable.
- Mainframe Servers:Proprietary architectures with hardware-level encryption and parallel transaction processing. Central banks and national social security systems in Germany and Japan maintain these for COBOL-dependent core banking workloads.
Rack servers lead volumes today; blade servers are gaining share fastest in regulated verticals.
Technology:
Processor selection determines supply chain access, with x86 dominance eroding only in specialized HPC and cloud-native workloads.
- Intel Xeon:Established instruction set compatibility and mature software optimization. Enterprise procurement in the United States and Germany defaults to these for SAP and Oracle workloads where certification matrices limit migration risk.
- AMD EPYC:Higher core density and PCIe lane counts per socket. Cloud service providers in Shanghai and Amsterdam are standardizing on these for virtualization density and memory bandwidth-sensitive inference.
- ARM:Reduced instruction set computing with performance-per-watt optimization. RIKEN and European weather centers select these for Fugaku-class supercomputing where power envelopes constrain facility expansion.
- IBM Power:Big-endian architecture with hardware transactional memory. Large banks and insurance carriers retain these for AIX-dependent risk analytics where operating system migration costs exceed hardware refresh savings.
Intel Xeon retains the largest installed base; AMD EPYC is expanding most quickly in cloud procurement.
End User:
Capital allocation cycles and security certification requirements create distinct buying behaviors across customer categories.
- Cloud Service Providers:Hyperscale operators purchasing direct from foundries and ODMs. These buyers in Northern Virginia and Frankfurt bypass traditional channel economics through multi-year silicon pre-commitments.
- Data Centers:Colocation and wholesale facility operators serving multiple tenants. These providers in Singapore and Phoenix prioritize liquid-cooled rack densities above 50kW to attract AI training customers.
- Government:Sovereign cloud and classified infrastructure deployments. NIST 800-53 and ISO 27001 certification requirements in the United States and Germany create 6-9 month procurement queues.
- Enterprises:Corporate IT departments with hybrid cloud strategies. Manufacturing and pharmaceutical firms in Japan and Switzerland balance on-premises control against public cloud burst capacity.
Cloud service providers command the steepest volume trajectory; government contracts carry the longest sales cycles.
Deployment:
Infrastructure location decisions increasingly hinge on data residency regulations and latency requirements rather than cost optimization alone.
- Public Cloud:Shared infrastructure with metered consumption. SaaS vendors and startups in India and Brazil leverage these for variable workload scaling without capital commitment.
- Private Cloud:Dedicated resources with single-tenant isolation. German automotive manufacturers and French defense contractors select these for Gaia-X compliance and export control adherence.
- Hybrid:Orchestrated workloads spanning on-premises and public resources. Retail and logistics operators in the United States deploy these for seasonal demand spikes with baseline capacity retained locally.
- On-Premises:Fully owned and operated facilities. Research institutions and classified government sites in China and Saudi Arabia mandate these for air-gapped security and sovereign data control.
Public cloud deployments dominate new capacity; private cloud is climbing fastest in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's sovereign cloud investments under Gaia-X compliance are outpacing France's slower certification timelines, while China's hyperscale construction accelerates despite export control friction. The United States retains the deepest concentration of AI training clusters, though supply chain localization is fragmenting procurement patterns across jurisdictions.
United States
Hyperscale operators in Northern Virginia and Phoenix are commissioning multi-gigawatt campuses through direct utility partnerships with Dominion Energy and APS. EPA ENERGY STAR 3.0 standby thresholds below 5 watts are extending server qualification timelines by 8-14 months for federal procurement eligibility. Microsoft's expanding Boydton campus and Meta's Richmond server farms exemplify the concentration of AI inference infrastructure in the Mid-Atlantic power corridor.
Germany
Gaia-X compliance requirements are creating certified-hardware procurement pools that exclude non-EU supply chains for sovereign cloud deployments. EU Green Deal efficiency mandates under Ecodesign regulations are scoring liquid-cooled architectures preferentially in Frankfurt and Amsterdam data center developments. Bavaria's Munich-Ingolstadt corridor hosts the densest concentration of automotive-industry private cloud infrastructure for confidential computing workloads.
China
Domestic cloud service providers are pre-committing to multi-year processor roadmaps through foundry relationships with SMIC and Hua Hong to circumvent advanced node export controls. MIIT efficiency standards and dual carbon goals are accelerating liquid cooling adoption in Yangtze River Delta facilities. Alibaba's Zhangjiakou campus and Tencent's Qingyuan server farms demonstrate the scale of sovereign AI training infrastructure deployment.
Japan
RIKEN successor architectures and regional weather modeling centers are sustaining ARM-based supercomputing demand through METI-funded procurement pipelines. JIS standards for data center reliability are gating access to financial sector blade server contracts in Tokyo and Osaka. Fugaku-class installations in Kobe and Tsukuba represent the anchor demand for Fujitsu's custom silicon development.
Singapore
Colocation operators are prioritizing 50kW-plus liquid-cooled rack densities to attract AI training customers constrained by tropical ambient temperatures and land scarcity. The Infocomm Media Development Authority's sustainability standards are mandating power usage effectiveness disclosures for new facility approvals. Tuas and Loyang industrial zones concentrate the highest density of submarine cable landing stations intersecting with server farm development.
High-End Servers Market Competitive Landscape
Top-tier vendors anchor hyperscale direct procurement relationships, while mid-tier original design manufacturers compete for cloud service provider white-label contracts. The vendor base stratifies across three tiers: integrated OEMs with foundry partnerships, ODMs with captive thermal engineering capabilities, and regional system integrators serving sovereign cloud mandates. Strategic differentiation is concentrating around liquid cooling IP, custom silicon co-development agreements, and subscription-based management platforms. Competitive moves emphasize backward integration into power supply manufacturing and geographic diversification of final assembly away from Taiwan concentration.
Within the integrated OEM tier, Hewlett Packard Enterprise Development LP and Dell Inc. exemplify vendors transitioning toward recurring revenue models through subscription-based management platforms. Fujitsu Limited occupies a specialized position serving national laboratory and sovereign compute contracts requiring ARM-based architectures. These three companies represent distinct strategic archetypes: the platform-as-a-service pivot, the direct supply chain control model, and the architecture-specific specialization path.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Development LP |
| Cisco Systems Inc. |
| Dell Inc. |
| Supermicro |
| Fujitsu Limited |
| Amazon Web Services |
| Oracle Corp. |
| OVH Cloud |
| IBM Corp. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up ODM specialists in Taiwan and Shenzhen anchor supply-side discipline, translating captive thermal engineering capabilities into pricing power over liquid-cooled rack configurations while hyperscale direct procurement erodes margins on standardized air-cooled units.
Pricing Analysis
Capacity additions in Malaysia and Vietnam are reshaping price floors for mid-density rack servers, compressing spreads between ODM and OEM offerings. Subscription-based management platforms from Hewlett Packard Enterprise and Dell now capture recurring revenue streams that offset hardware margin erosion. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy stripped-down configurations reflects certification tier and volume scale differentiation. Cloud service providers exhibit lowest price sensitivity due to multi-year silicon pre-commitments, while regional healthcare networks face acute budget constraints driving aggressive tender competition.
Supply Chain Analysis
ISO 27001 and NIST 800-53 certification queues extending 6-9 months gate access to government and financial sector procurement pools, concentrating qualified supplier relationships among incumbents with established security validation track records. Taiwan, China, and South Korea dominate advanced packaging substrate and memory module supply. Power delivery components and liquid cooling manifolds draw from specialized automotive and telecom rectifier supplier bases. Single-source vulnerability around ABF substrate capacity from Taiwan-based suppliers presents structural risk. Distribution runs through direct hyperscale procurement agreements and value-added reseller channels serving enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in high-end servers hinges on liquid cooling IP monetization and subscription platform attach rates, with cost-down drivers from direct foundry relationships offsetting commodity silicon pricing pressure.
For Market Incumbents: Cement liquid cooling engineering capabilities through captive R&D or targeted acquisition of thermal management specialists, as direct-to-chip architectures become mandatory for rack densities above 50kW. Defend against hyperscale self-build programs by deepening subscription platform penetration in regulated verticals where security certification requirements create switching costs. Prioritize backward integration into power supply manufacturing to control 48V bus architecture delivery timelines. For New Entrants and Emerging Players: The price-point gap between premium liquid-cooled blade systems and economy rack configurations creates entry space for mid-tier ODMs with ASHRAE-compliant cold plate designs. Target colocation operators in Singapore and Phoenix seeking 50kW-plus rack densities without hyperscale procurement scale. Pursue sovereign cloud certification in Germany under Gaia-X compliance frameworks as the most penetrable geographic entry point. Lead with fluid compatibility testing and corrosion warranty differentiation rather than hardware performance specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among thermal engineering specialists and power delivery component manufacturers lacking direct hyperscale relationships but holding critical 48V transient load management expertise. Long-term viability over the next decade rests on positioning for confidential computing workload growth and sovereign infrastructure buildouts outside US hyperscale supply chains. Monitor EPA ENERGY STAR 3.0 qualification timelines as the key inflection signal for federal procurement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Standardization | Open Compute Project and ASHRAE guideline convergence enables multi-vendor cold plate interoperability in hyperscale deployments. |
| Custom Silicon Partnership | Cloud service provider pre-commitments to AMD and Intel roadmaps before tape-out secure allocation priority during substrate shortages. |
| Subscription Platform Expansion | Hewlett Packard Enterprise's GreenLake and Dell's APEX models extend recurring revenue beyond traditional hardware refresh cycles. |
| Sovereign Cloud Certification | Gaia-X compliance investments in Germany create procurement pools excluding non-EU supply chains for classified workloads. |
| Power Supply Backward Integration | In-house 48V bus architecture production reduces qualification timeline exposure from third-party supplier bottlenecks. |
Research Methodology
Multiple input streams — hyperscaler capex disclosures, foundry capacity announcements, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with data center procurement officers, thermal engineering directors, cloud platform architects, and government IT contract specialists informed demand-side validation. Secondary sources included EPA ENERGY STAR certification listings, EU Ecodesign regulatory filings, SEC 10-K equipment spending disclosures, and Open Compute Project technical specifications.
Data-stream reconciliation across shipment volumes, average selling price trajectories, and regional deployment patterns anchored the analytical framework over the projection horizon. Segmentation dimensions encompassed product architecture, processor technology, end-user category, and deployment model. CAGRs were derived from installed base growth rates and replacement cycle compression factors. Forecast inputs incorporated AI training cluster power density requirements and sovereign infrastructure budget allocations.
Caveats apply where advanced packaging substrate supply constraints or export control expansions could materially shift the outlook. Deviation in hyperscale capital expenditure timing or EPA qualification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East Paper Making Machine Market
Others
Food Technology Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Asia-Pacific Laser Hair Removal Market
Others
Europe Tablet PC Market
Others
Air Separation Module Kit Market
Others
Spinner Flask Market
Others
North America Agricultural Enzymes Market
Others
Taiwan Retail Market
Others
Global Surface Analysis Market
Others
Smart Electric Curtain Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Allogeneic T Cell Therapies Market
Others
Channel-In-A-Box (Ciab) Market
Others
Blockchain in BFSI Market
Others
Asia-Pacific Eyelash Serum Market