
 Surgical Simulation Market | 2026-2036
Surgical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Simulation Market Intelligence
Hospital procurement departments are collapsing the traditional dominance of medical schools as the primary buyer archetype for surgical simulation platforms. CAE Inc. leverages its installed base in aviation training to cross-sell medical simulation suites into hospital networks. Mentice AB anchors its position in endovascular simulation through specialized catheter-based haptic systems. FundamentalVR Ltd. differentiates by deploying standalone VR headsets that eliminate dedicated lab infrastructure requirements.
Surgical simulation encompasses computer-generated or physical replica environments that replicate anatomical structures, tissue behaviors, and instrument responses with force-feedback tolerances measured in Newtons, enabling repeatable skill acquisition without patient risk. Virtual reality platforms command premium pricing due to software update recurring revenue, while synthetic models retain share in open procedural training where tactile fidelity remains unmatched. Orthopedic surgery applications generate concentrated demand because joint replacement volumes drive institutional training budgets, whereas cardiovascular surgery simulation competes on integration with catheter lab equipment ecosystems.
FDA 510(k) pathways for VR surgical trainers, EU MDR clinical evidence requirements for competency validation tools, and Japan's PMDA software-as-medical-device classifications collectively determine market access timelines and product development roadmaps. ISO 9001 and IEC 62304 compliance burdens favor established vendors with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor how residency program accreditation bodies revise simulation hour mandates, as these thresholds directly shape institutional procurement cycles and platform refresh rates.
Market Dynamics
Hospital procurement departments are collapsing the traditional dominance of medical schools as the primary buyer archetype for surgical simulation platforms. Residency program accreditation bodies are tightening simulation hour mandates, forcing institutional refresh cycles and compressing vendor sales timelines.
Growth Catalysts
- FDA 510(k) pathway compression:The US regulator's streamlined clearance for VR surgical trainers is reducing product launch timelines from 18 months to under 12 months, accelerating platform commercialization.
- Orthopedic surgery volume concentration:Joint replacement procedure growth is directing institutional training budgets toward high-fidelity haptic platforms with Newton-level force feedback precision.
- EU MDR competency validation requirements:The European framework mandates simulation-based evidence for surgical device training, creating procurement pull across German and French hospital networks.
Market Restraints
- Silicon photonics component shortage:VR headset display supply concentrates among Taiwanese and South Korean foundries, creating 6-9 month lead time volatility for standalone platform vendors.
- EU MDR clinical evidence burden:The regulation's expanded documentation requirements for competency validation tools favor established vendors with dedicated regulatory affairs teams over emerging entrants.
- Synthetic cadaver substitution:Wet lab training using biological specimens retains share in open procedural instruction where tissue perfusion and anatomical variation remain unmatched by digital replication.
Strategic Opportunities
- Japan PMDA software-as-medical-device classification:The regulatory framework's clarity on VR training platforms enables faster market entry for cloud-delivered simulation content in Tokyo and Osaka academic medical centers.
- Haptic-robotics convergence:Integration of force-feedback gloves with teleoperated surgical systems is opening remote proctoring revenue streams beyond traditional institutional licensing.
- Rural hospital network penetration:Standalone VR headsets eliminating dedicated lab infrastructure requirements are unlocking procurement in non-academic US community hospitals previously excluded from simulation programs.
Industry Challenges
- ISO 62304 software lifecycle certification:Medical device software quality management requires 18-24 month validation cycles that strain startup cash reserves and extend time-to-revenue.
- Residency curriculum integration friction:Program directors face workload compression from ACGME duty hour restrictions, limiting faculty bandwidth for simulation platform onboarding and competency assessment redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Simulation Market |
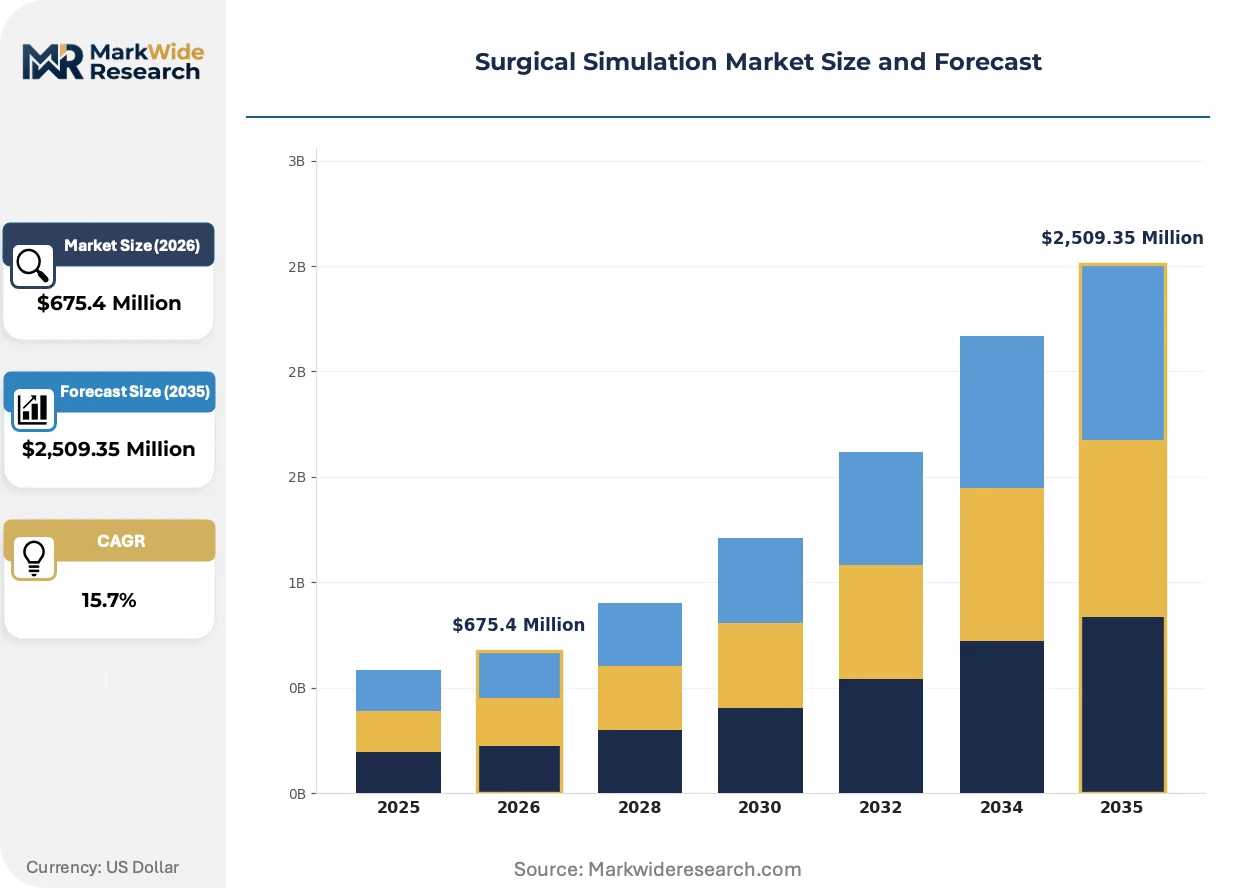
| Market Size in 2026 | $675.4 Million |
| Market Size in 2035 | $2,509.35 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Augmented Reality, Synthetic Models, Hybrid Simulators End User: Medical Schools, Hospitals, Surgical Centers, Training Organizations Technology: 3D Visualization, Haptic Feedback, Scenario-Based Training, Gamification Application: General Surgery, Orthopedic Surgery, Cardiovascular Surgery, Neurological Surgery |
| Companies Covered | Laerdal Medical AS, Mentice AB, CAE Inc., Simulab Corporation, FundamentalVR Ltd., 3D Systems, Inc., Surgical Science Sweden AB, VRmagic GmbH, VirtaMed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Simulation Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is reshaping how surgical simulation platforms generate patient-specific anatomy from standard imaging modalities. Vendors are racing to deploy on-device neural networks that eliminate cloud latency during time-pressured training scenarios.
High-fidelity haptic feedback hardware is bifurcating the platform landscape into premium catheter-lab integrated systems and portable standalone units. Academic medical centers in Germany and Japan are consolidating procurement around the former, while US community hospitals and ambulatory surgery centers are adopting the latter for cost containment. The structural consequence is compressing mid-tier vendor margins as buyers polarize toward either ecosystem-integrated suites or bare-bones VR deployments.
Japan's PMDA software-as-medical-device classification framework is clarifying compliance pathways for cloud-native simulation platforms. The regulation treats algorithmic content updates as post-market surveillance events rather than pre-market submissions, enabling subscription revenue models previously blocked by per-version regulatory holds. Vendors targeting Tokyo and Osaka residency programs are restructuring product architectures around this interpretation.
Residency program procurement committees are consolidating vendor relationships around single-platform ecosystems rather than best-of-breed point solutions. The purchasing pattern compresses switching flexibility but reduces IT integration overhead and faculty training burden. This concentration is most visible in United States academic medical centers where GME office budget authority has centralized over individual department discretionary spending.
Surgical Simulation Market Segmentation
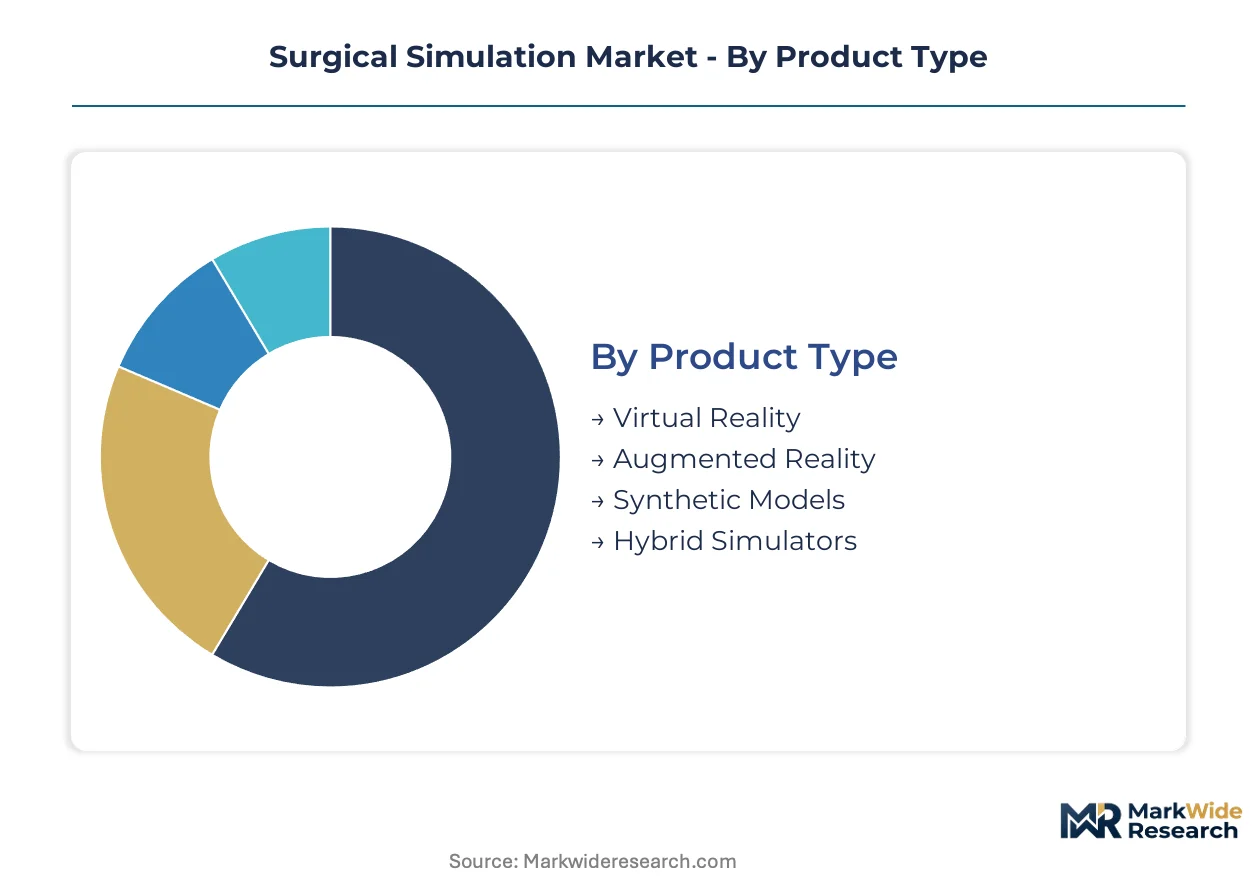
Surgical simulation platforms fragment across hardware form factors, institutional buyers, sensory technologies, and procedural specialties. Each segmentation axis carries distinct procurement cycles, regulatory pathways, and margin structures that reshape vendor go-to-market strategies.
Product Type:
Virtual Reality platforms dominate North American and Japanese procurement, while Synthetic Models retain entrenched positions in European open-surgical training programs. Export-led growth concentrates in VR headset shipments to Asia-Pacific academic centers.
- Virtual Reality:Headset-based immersive environments deliver software-update recurring revenue through cloud-delivered anatomical libraries. Demand concentrates in United States residency programs where ACGME simulation mandates drive institutional refresh cycles, though Taiwanese display supply constraints create 6-9 month procurement delays.
- Synthetic Models:Physical replicas replicate tissue perfusion and anatomical variation with tactile fidelity unmatched by digital alternatives. German and French hospital networks sustain procurement for open procedural training where haptic precision outweighs scalability advantages.
- Augmented Reality:Overlaid digital guidance onto physical anatomy bridges wet lab and virtual environments. Japanese PMDA software-as-medical-device classifications accelerate regulatory clearance for Tokyo and Osaka academic deployments.
- Hybrid Simulators:Integrated physical-digital platforms combine force-feedback hardware with VR visualization. Cost concentration limits adoption to premium academic medical centers with dedicated simulation lab infrastructure.
Synthetic Models command the established base. The steepest expansion runs through Virtual Reality.
End User:
Procurement authority is migrating from academic departments to centralized hospital supply chains, collapsing traditional purchasing hierarchies. Volume concentration now sits with integrated delivery networks rather than standalone institutions.
- Hospitals:Centralized GME office budgets dominate United States procurement, with haptic-enabled platforms prioritized for orthopedic and cardiovascular service line training. EU MDR competency validation requirements pull simulation spending into German and French network capital plans.
- Medical Schools:Traditional dominance eroding as residency program accreditation bodies tighten simulation hour mandates, forcing vendor consolidation around single-platform ecosystems.
- Surgical Centers:Ambulatory settings adopt standalone VR headsets eliminating dedicated lab infrastructure, unlocking simulation programs in cost-constrained environments previously excluded from high-fidelity training.
- Training Organizations:Commercial simulation centers serve device manufacturer certification programs and continuing medical education, with revenue tied to procedural volume growth in joint replacement and endovascular therapies.
Hospitals command the established base. The steepest expansion runs through Surgical Centers.
Technology:
Platform differentiation now hinges on sensory fidelity and adaptive content delivery rather than visualization alone. Hardware-software integration determines switching costs and renewal rates.
- Haptic Feedback:Force-feedback gloves and catheter interfaces measured in Newton-level precision anchor premium pricing. Orthopedic surgery applications in United States academic centers drive concentrated demand for joint replacement procedural training.
- 3D Visualization:Stereoscopic rendering enables anatomical depth perception without specialized hardware. Widespread adoption across Medical Schools constrained by GPU supply volatility and IT integration overhead.
- Scenario-Based Training:Algorithmically generated complications adapt difficulty to learner performance. Cloud-native architectures face EU MDR clinical evidence burdens for competency validation tools.
- Gamification:Progression systems and competitive scoring mechanics increase learner engagement metrics. Adoption concentrated in Training Organizations seeking differentiation in saturated continuing education markets.
3D Visualization commands the established base. The steepest expansion runs through Haptic Feedback.
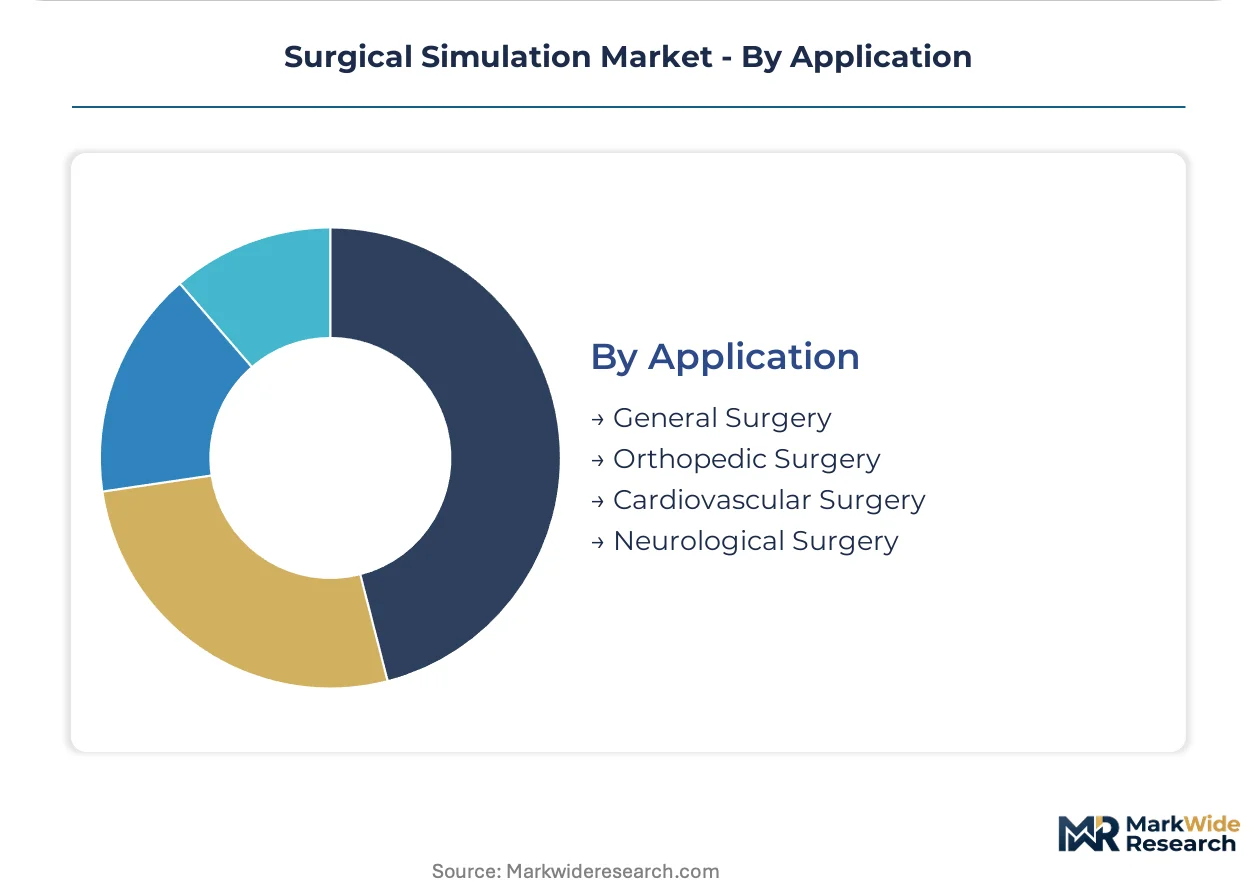
Application:
Procedure volume and device manufacturer training subsidies determine segment profitability. Reimbursement dynamics in target specialties reshape institutional training budget allocation.
- Orthopedic Surgery:Joint replacement volume growth directs capital toward high-fidelity haptic platforms with Newton-level force feedback. United States hospital procurement prioritizes this segment for service line competency assurance.
- Cardiovascular Surgery:Catheter lab equipment ecosystem integration creates vendor lock-in and recurring consumable revenue. German and Japanese academic centers consolidate procurement around integrated simulation-to-clinical workflows.
- General Surgery:Broad procedural coverage spreads demand across multiple simulation modalities without concentration in premium platforms. Cost containment pressures favor mid-tier VR deployments.
- Neurological Surgery:Patient-specific anatomy generation from standard imaging drives AI inference at the edge. Regulatory uncertainty around software-as-medical-device classifications constrains vendor investment.
General Surgery commands the established base. The steepest expansion runs through Orthopedic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among Taiwanese display foundries and South Korean semiconductor fabricators, creating procurement bottlenecks for VR headset vendors serving academic medical centers. Regulatory divergence across FDA, EU MDR, and PMDA frameworks fragments product development roadmaps and market access timelines.
United States
ACGME simulation hour mandates drive institutional refresh cycles for haptic-enabled orthopedic training platforms. FDA 510(k) pathway compression reduces product launch timelines from eighteen months to under twelve. Boston and New York academic medical centers consolidate procurement around single-platform ecosystems.
Germany
EU MDR competency validation requirements pull simulation spending into hospital network capital plans. The regulation's clinical evidence burden favors established vendors with dedicated regulatory affairs teams. Bavarian and North Rhine-Westphalian university hospitals anchor procurement for catheter-lab integrated systems.
Japan
PMDA software-as-medical-device classifications clarify compliance pathways for cloud-native platforms. Algorithmic content updates trigger post-market surveillance rather than pre-market submissions. Tokyo and Osaka residency programs restructure architectures around subscription revenue models.
United Kingdom
NHS England procurement frameworks prioritize cost containment in simulation platform selection. MHRA alignment with EU MDR transitional provisions creates temporary regulatory uncertainty. London and Southeast academic clusters concentrate demand for standalone VR headsets eliminating dedicated lab infrastructure.
France
ANSM oversight of competency validation tools intersects with EU MDR implementation timelines. Hospital network consolidation redirects simulation budgets toward centralized GME offices. Paris and Lyon academic centers drive procurement for endovascular simulation with specialized catheter-based haptic systems.
Surgical Simulation Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized medical simulation pure-plays. The vendor base spans aviation-training crossovers, surgical instrument specialists, and VR-native entrants. Three archetypes dominate: aviation-simulation diversifiers, endovascular haptic specialists, and standalone VR disruptors. Competitive moves center on hospital network consolidation and haptic-robotics convergence for remote proctoring revenue.
Among aviation-training diversifiers, CAE Inc. leverages installed base cross-selling into hospital networks. Mentice AB occupies the endovascular specialist position with catheter-based systems. FundamentalVR Ltd. exemplifies the VR-native archetype through standalone headset deployments eliminating lab infrastructure requirements.
| Leading Market Players |
|---|
| Laerdal Medical AS |
| Mentice AB |
| CAE Inc. |
| Simulab Corporation |
| FundamentalVR Ltd. |
| 3D Systems, Inc. |
| Surgical Science Sweden AB |
| VRmagic GmbH |
| VirtaMed AG |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with Taiwanese display foundries lock in supply access for VR headset vendors while capping price volatility for hospital procurement departments. These arrangements tether pricing visibility to semiconductor fabrication schedules and haptic component lead times across the surgical simulation value chain.
Pricing Analysis
Volume-discount tiering structures stratify across institutional scale, with academic medical centers commanding 25-40% unit discounts against ambulatory surgery centers. Pricing separates ecosystem-integrated suites with Newton-level haptic precision from standalone VR headsets with reduced force-feedback fidelity. Cost compression in mid-tier deployments is intensifying because procurement committees are consolidating around single-vendor ecosystems. Surgical centers exhibit highest price sensitivity due to capital constraint, while German university hospitals demonstrate lowest sensitivity given EU MDR-mandated competency validation budgets.
Supply Chain Analysis
Taiwan Strait shipping lanes underpin critical display component transit for VR headset assembly, creating geopolitical exposure for simulation platform vendors. Manufacturing concentrates in Taiwan, South Korea, and China for silicon photonics, GPU semiconductors, and force-feedback actuator assemblies. Raw material dependencies span rare-earth magnets for haptic gloves, high-resolution OLED panels, and medical-grade polymer resins for synthetic models. Single-source vulnerability concentrates in Taiwanese foundry capacity for microdisplay fabrication. Distribution runs through regional medical device distributors with GPO contracting authority in United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO 62304-certified software engineering talent constrains vendor scaling velocity and extends validation cycles for cloud-native simulation platforms. This capability gap separates established players with dedicated regulatory affairs teams from capital-constrained entrants.
For Market Incumbents: Fortify haptic-robotics integration capabilities to capture remote proctoring revenue streams beyond institutional licensing. Defend against standalone VR disruptors by embedding simulation platforms into catheter lab equipment ecosystems, creating switching costs through workflow integration. Prioritize backward integration into force-feedback hardware manufacturing to secure Newton-level precision component supply. For New Entrants and Emerging Players: Differentiate on AI-driven patient-specific anatomy generation at the edge, eliminating cloud latency for time-pressured training scenarios. Target United States community hospitals with standalone headset deployments that eliminate dedicated lab infrastructure requirements. Pursue Japan PMDA software-as-medical-device clearance to enable subscription revenue models blocked by per-version regulatory holds in other geographies. For Investors and Strategic Acquirers: Endovascular haptic specialists with catheter-lab installed bases represent priority acquisition targets given integration moats and recurring consumable revenue. Long-term viability hinges on regulatory pathway clarity for algorithmic content updates as post-market surveillance events rather than pre-market submissions. Monitor ACGME simulation hour mandate revisions as inflection indicators for institutional procurement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Streamlined clearance for VR surgical trainers compresses product launch timelines under twelve months. |
| Hospital System Partnership | Single-platform ecosystem consolidation reduces IT integration overhead for GME offices. |
| Haptic-Robotics Convergence | Force-feedback glove integration with teleoperated systems unlocks remote proctoring revenue streams. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor vendors with dedicated regulatory affairs teams. |
| Software Companion Development | Cloud-native architectures enable subscription models under Japan PMDA post-market surveillance frameworks. |
Research Approach
Operator-level perspectives from residency program directors, hospital GME office administrators, biomedical engineering leads, and surgical device training managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, PMDA software-as-medical-device registration databases, and hospital procurement contract records. Bottom-up demand modeling across hardware form factors, institutional buyer types, and procedural specialties triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across regulatory pathway acceleration scenarios, display component supply disruption events, and residency mandate revision timelines. Segmentation dimensions modeled include product type, end user archetype, sensory technology, and procedural application across the projection horizon. CAGR derivation incorporated orthopedic surgery volume trajectories, catheter lab equipment replacement cycles, and AI inference hardware cost curves as industry-specific inputs.
Material uncertainties — silicon photonics shortage duration, ACGME mandate threshold revisions, and EU MDR transitional enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway compression sustainability and hospital procurement centralization velocity. Practitioners should keep alternative scenarios live as PMDA classification interpretations and residency accreditation body priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Silicone Molding Machinery Market
Others
Global Retail Media Networks Market
Others
Smart Home and Office Market
Others
Middle East and Africa Cocoa Products Market
Others
Metal Air Battery Market
Others
Buchner Funnels Market
Others
Workbench Tanks Market
Others
Bitcoin Mining Servers Market
Others
Smart Home Market
Others
Thiamethoxam Market
Others
Propanil Market
Others
Global Optical Comparator Market
Others
Reusable Wine Bags Market
Others
Global Luxury High End Furniture Market
Others
Enterprise Video Content Management Market
Others
5G Edge Computing Market