
 North America Micro Market | 2026-2036
North America Micro Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro Market Insights
Healthcare facility procurement is rotating toward automated micro-market formats as hospital systems seek labor-efficient foodservice alternatives. Aramark leverages its integrated facilities management footprint to bundle micro-market installations with existing service contracts. Compass Group sustains competitive pressure through its Eurest division's focus on corporate campus micro-market densification. Sodexo differentiates via its specialized healthcare and education micro-market portfolios across the United States and Canada.
North America micro markets encompass unattended retail environments combining refrigerated merchandisers, self-checkout kiosks, and cloud-connected inventory management systems, typically deployed in workplaces, hospitals, and educational institutions to provide 24-hour fresh food and beverage access without staffed cafeterias. Hardware configurations integrate temperature-controlled cabinets with weight-sensing shelves and biometric or mobile payment terminals operating on 110-240V single-phase power. Cloud-based delivery models are capturing the fastest expansion as operators prioritize real-time sales telemetry and remote inventory optimization over capital-intensive on-premises server installations. Process automation applications command disproportionate margin attention because predictive restocking algorithms reduce spoilage rates and labor dispatch costs simultaneously.
FDA food code provisions and state health department retail food establishment classifications govern product handling, temperature monitoring, and sanitation protocols for micro-market operators across the United States. Canadian Food Inspection Agency standards and provincial public health regulations enforce parallel compliance requirements north of the border. OSHA workplace safety guidelines and FCC equipment authorization rules for wireless payment terminals add layered operational obligations. Stakeholders must weigh cloud migration timelines against cybersecurity insurance requirements as transaction volumes migrate from legacy cash systems to connected platforms.

Market Dynamics
Healthcare systems across the United States and Canada are consolidating foodservice operations into automated micro-market formats to offset persistent labor shortages and cafeteria staffing costs. FDA food code harmonization is simultaneously forcing equipment refresh cycles as operators upgrade temperature monitoring and sanitation protocols.
Growth Catalysts
- Hospital network densification:Healthcare campuses from Atlanta to Charlotte are expanding unattended retail footprints. Hospital systems prioritize 24-hour fresh food access without staffing overhead.
- FDA food code harmonization:Unified temperature monitoring and sanitation standards accelerate equipment replacement cycles. Operators modernize legacy vending infrastructure to maintain compliance.
- Cloud-connected inventory systems:Real-time sales telemetry enables predictive restocking algorithms. Foodservice operators reduce spoilage rates while optimizing labor dispatch.
Market Restraints
- Capital equipment intensity:Refrigerated merchandisers with weight-sensing shelves and biometric payment terminals require substantial upfront investment. Smaller operators face financing constraints.
- Cybersecurity insurance escalation:Transaction migration from cash to connected platforms triggers premium increases. Cloud migration timelines stall as operators weigh coverage costs against operational benefits.
- Power infrastructure limitations:110-240V single-phase requirements constrain deployment in older buildings. Campus facilities require electrical upgrades to support micro-market hardware.
Strategic Opportunities
- Canadian provincial expansion:Health Canada and provincial public health regulations create standardized compliance frameworks. Ontario and British Columbia hospital networks show underpenetrated micro-market deployment.
- Educational institution pivot:Universities and community colleges seek labor-efficient alternatives to staffed dining halls. Campus housing density supports 24-hour unattended retail economics.
- Biometric payment convergence:Integration of fingerprint and facial recognition with mobile wallets reduces transaction friction. Corporate campuses adopt touchless checkout for hygiene-sensitive environments.
Industry Challenges
- OSHA workplace safety compliance:Equipment installation in active healthcare and corporate environments requires coordination with facility safety protocols. Technicians need specialized certifications for hospital-grade electrical work.
- FCC equipment authorization delays:Wireless payment terminals face certification bottlenecks. Product launch timelines extend as manufacturers navigate authorization queues.
- Legacy system integration friction:Existing campus card systems and enterprise resource planning platforms require custom API development. IT departments resist parallel payment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Solutions Delivery Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Healthcare, Retail, Education, Manufacturing Application: Data Analytics, Process Automation, Customer Engagement, Supply Chain Management |
| Companies Covered | Aramark, Compass Group, Sodexo, 365 Retail Markets, Canteen Vending Services, Avanti Markets, Five Star Food Service, Cantaloupe Inc., USConnect, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro Market Trends and Innovations
Micro-market hardware and software architectures are converging around cloud-native platforms that prioritize remote operational control over on-site infrastructure. This shift is compressing vendor differentiation and reshaping procurement criteria.
Weight-sensing shelf technology is fragmenting competitive positioning among equipment suppliers. Hospital systems and corporate campuses are adopting these systems at accelerating pace to enable grab-and-go checkout without barcode scanning. The technology is fragmenting traditional vending equipment categories by merging inventory tracking, payment processing, and freshness monitoring into unified hardware units.
FDA food code provisions governing temperature monitoring and sanitation protocols are tightening enforcement across state health departments. Equipment manufacturers must embed continuous logging and automated alert systems to maintain retail food establishment classifications. Healthcare operators in the U.S. Southeast corridor are responding fastest, upgrading refrigeration units ahead of inspection cycles.
Facility management procurement is consolidating micro-market installations within broader service contracts. Corporate campuses and hospital systems now bundle unattended retail with cleaning, security, and maintenance services rather than sourcing standalone equipment. This pattern concentrates most visibly in the Atlanta-to-Charlotte corridor where corporate density overlaps with healthcare network expansion.
North America Micro Market Segmentation
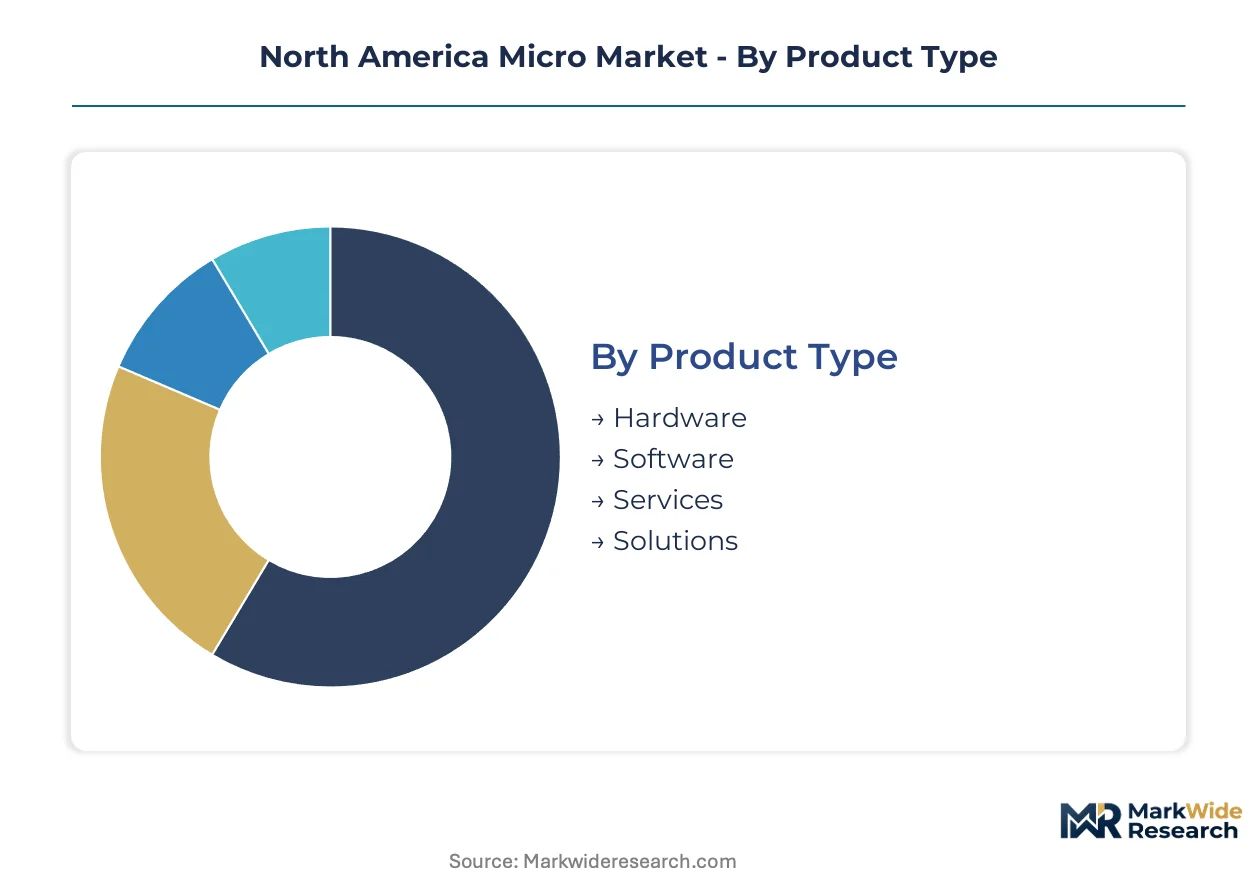
Micro-market segmentation in North America reflects divergent technology maturity and procurement sophistication across buyer types. Hardware-heavy configurations face displacement pressure from cloud-native alternatives, while service bundling reshapes vendor economics.
Product Type:
Substitution pressure intensifies as software-defined architectures displace purpose-built hardware in new deployments.
- Hardware:Refrigerated merchandisers, weight-sensing shelves, and biometric payment terminals constitute the physical infrastructure layer. Hospital systems across the U.S. Southeast corridor prioritize FDA-compliant temperature monitoring hardware to satisfy state health department inspection cycles.
- Software:Cloud-connected inventory management platforms and predictive restocking algorithms reduce spoilage rates. Corporate campuses in the Atlanta-to-Charlotte corridor adopt these systems fastest as labor dispatch optimization becomes critical.
- Services:Installation, maintenance, and compliance auditing support ongoing operations.
- Solutions:Bundled hardware-software-service packages dominate hospital network procurement.
Hardware anchors the volume base while Software gains share at the steepest rate.
Delivery Model:
Cost tier differentiation separates capital-intensive ownership from operational expenditure models favored by mid-scale operators.
- On-premises:Legacy server installations retain presence in security-sensitive healthcare environments. Canadian provincial hospital networks maintain these systems where data residency requirements intersect with Health Canada guidelines.
- Cloud-based:Real-time sales telemetry and remote inventory optimization dominate new procurement. U.S. corporate campuses adopt this model to minimize IT infrastructure overhead and accelerate deployment timelines.
- Hybrid:Local transaction processing with cloud analytics appeals to institutions with intermittent connectivity.
- Managed Services:Full operational outsourcing including restocking and equipment maintenance.
Cloud-based deployment expands most quickly while On-premises retains entrenched positions in regulated healthcare settings.
End User:
Application intensity varies sharply as healthcare automation priorities diverge from retail efficiency metrics.
- Healthcare:Hospital systems deploy micro-markets to eliminate 24-hour cafeteria staffing costs. The U.S. Southeast corridor from Atlanta to Charlotte shows concentrated network expansion as hospital densification overlaps with corporate campus clusters.
- Retail:Unattended fresh food access in non-traditional locations drives adoption.
- Education:Universities and community colleges seek labor-efficient alternatives to staffed dining halls. Campus housing density in Ontario and British Columbia supports unattended retail economics.
- Manufacturing:Shift-worker food access in industrial facilities with limited nearby retail.
Healthcare commands the largest installed base while Education demonstrates the steepest expansion trajectory among emerging verticals.
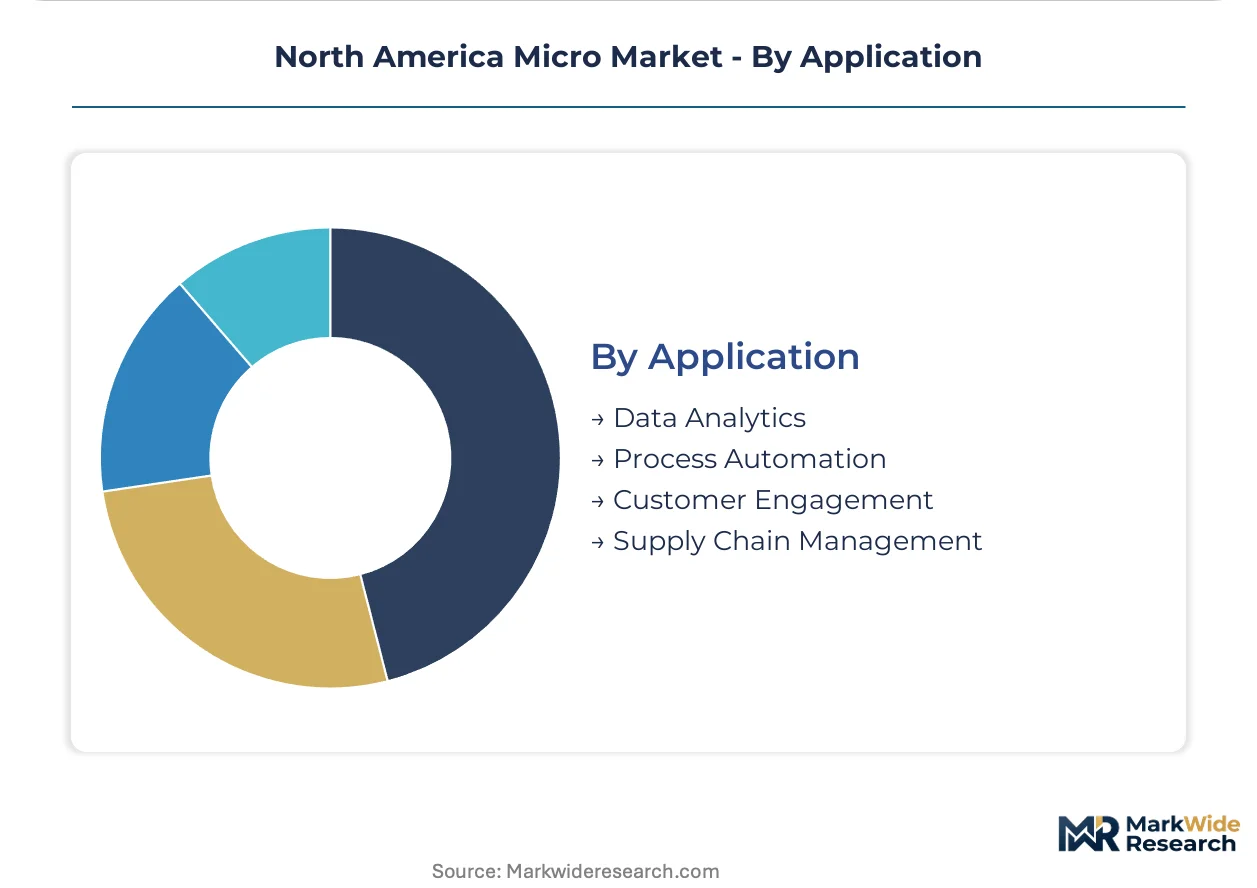
Application:
Margin concentration follows process automation capabilities that simultaneously reduce spoilage and labor dispatch costs.
- Data Analytics:Consumption pattern analysis informs product mix decisions and promotional timing.
- Process Automation:Predictive restocking algorithms and automated temperature alerts command disproportionate operator attention. FDA food code harmonization accelerates adoption as compliance documentation becomes automated.
- Customer Engagement:Mobile app integration and loyalty programs differentiate campus offerings.
- Supply Chain Management:Vendor coordination and procurement optimization complete the operational stack.
Process Automation captures the highest margin attention while Customer Engagement climbs fastest as biometric payment convergence reduces transaction friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 85 corridor from Atlanta to Charlotte anchors North American micro-market deployment density. This freight and commuter spine connects healthcare network expansion with corporate campus clusters. Canadian Pacific and CN rail interchanges support cross-border equipment distribution into Ontario and British Columbia.
United States
Hospital systems from Atlanta to Charlotte deploy automated micro-markets to eliminate 24-hour cafeteria staffing costs. FDA food code harmonization accelerates equipment refresh cycles as operators upgrade temperature monitoring protocols. The U.S. Southeast corridor shows concentrated network expansion where corporate campus density overlaps with healthcare facility construction.
Canada
Ontario and British Columbia hospital networks demonstrate underpenetrated micro-market deployment relative to U.S. benchmarks. Health Canada and provincial public health regulations create standardized compliance frameworks that reduce operator uncertainty. Toronto and Vancouver campus housing density supports unattended retail economics in educational institutions.
Mexico
Manufacturing facilities in Nuevo León and Baja California evaluate micro-markets for shift-worker food access. Mexican federal health regulations through COFEPRIS govern retail food establishment classifications for automated formats. Monterrey industrial parks attract pilot deployments as operators test cross-border service models.
North America Micro Market Competitive Landscape
Concentration sits with integrated facilities management conglomerates that bundle micro-market installations with existing service contracts. Three to four diversified foodservice operators control the majority of healthcare and corporate campus deployments. Strategic archetypes separate into full-service facilities managers, specialized unattended retail technology vendors, and regional vending operators upgrading legacy infrastructure. Competitive moves center on contract bundling with broader facility services and cloud platform partnerships that reduce client IT overhead.
Among integrated facilities management providers, Aramark, Compass Group, and Sodexo exemplify the contract-bundling archetype. Aramark leverages its hospital service footprint to anchor micro-market installations within existing relationships. Compass Group occupies a position emphasizing corporate campus densification through its Eurest division. Sodexo sits within specialized healthcare and education portfolios that differentiate its unattended retail offerings across the United States and Canada.
| Leading Market Players |
|---|
| Aramark |
| Compass Group |
| Sodexo |
| 365 Retail Markets |
| Canteen Vending Services |
| Avanti Markets |
| Five Star Food Service |
| Cantaloupe Inc. |
| USConnect |
| Others |
Pricing and Supply Chain Analysis
Cloud-native inventory platforms replacing on-premises server installations simultaneously redraw supply geography toward software development clusters and compress hardware margin pools as operators prioritize subscription economics over capital equipment procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant temperature monitoring systems from basic refrigerated merchandisers from refurbished legacy units. Price differentiation hinges on Health Canada certification grade and after-sales service bundling with preventive maintenance contracts. Pricing pressure stems from cybersecurity insurance escalation as transaction migration to connected platforms triggers premium increases. Hospital systems in the U.S. Southeast corridor demonstrate lowest price sensitivity due to bundled facilities management contracts, while independent regional vending operators face acute financing constraints.
Supply Chain Analysis
China and Mexico anchor refrigerated merchandiser fabrication and biometric payment terminal assembly respectively. Component sourcing draws from Taiwanese semiconductor foundries for weight-sensing shelf controllers and South Korean display panel manufacturers for touchscreen interfaces. Single-source vulnerability concentrates in cloud infrastructure provisioning where AWS and Azure dominance creates outage exposure. Distribution runs through integrated facilities management conglomerates that bundle micro-market installations with existing service contracts rather than standalone equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated facilities management conglomerates as hospital systems and corporate campuses consolidate procurement into bundled service contracts spanning cleaning, security, and unattended retail.
For Market Incumbents: Secure cloud platform partnerships that reduce client IT overhead and accelerate deployment timelines against specialized unattended retail technology vendors. Defend margin position by embedding predictive restocking algorithms as proprietary service differentiators rather than commoditized hardware features. Capacity addition in Ontario and British Columbia hospital networks offers geographic hedge against U.S. Southeast corridor saturation. For New Entrants and Emerging Players: Anchor in Canadian provincial expansion where Health Canada standardization reduces compliance uncertainty relative to fragmented U.S. state health department classifications. Underpenetrated deployment in Toronto and Vancouver educational institutions presents white-space target with campus housing density supporting unattended retail economics. Go-to-market angle should emphasize biometric payment convergence with mobile wallets for hygiene-sensitive healthcare environments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional vending operators upgrading legacy infrastructure toward cloud-connected formats. Five-to-ten year viability frames around process automation capabilities that simultaneously reduce spoilage and labor dispatch costs. Acquisition target archetype: specialized unattended retail technology vendors with Health Canada certification and established API integrations with campus card systems. Signal to watch: FCC equipment authorization queue lengths for wireless payment terminals as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Partnership | Reduces hospital system IT infrastructure overhead and accelerates deployment timelines. |
| Biometric Payment Integration | Enables touchless checkout for hygiene-sensitive FDA-regulated healthcare environments. |
| Canadian Provincial Expansion | Health Canada standardization lowers compliance cost versus fragmented U.S. state mandates. |
| Predictive Restocking Algorithm Development | Simultaneously cuts spoilage rates and labor dispatch costs for foodservice operators. |
| FDA-Compliant Temperature Monitoring Upgrade | Satisfies state health department inspection cycles and maintains retail food establishment classification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital foodservice directors, corporate campus facilities managers, micro-market equipment procurement leads, and cloud platform integration specialists. Secondary validation drew from FDA food code provisions, Health Canada guidelines, FCC equipment authorization databases, and GPO contract filings. Bottom-up equipment shipment data triangulated against top-down facilities management contract values across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning hardware-software-service-solutions product types, on-premises-cloud-hybrid-managed services delivery models, and healthcare-retail-education-manufacturing end-user verticals. CAGRs derived from logistic diffusion curves fitted to unattended retail penetration rates in comparable geographies. Forecast inputs incorporated hospital network densification timelines in the Atlanta-to-Charlotte corridor and Canadian provincial regulatory harmonization schedules.
Material uncertainties — cybersecurity insurance premium volatility, FCC authorization delays, and legacy campus card system integration friction — sit outside the modeled envelope. Forecasts reflect assumptions around cloud migration adoption curves and FDA food code enforcement intensity. Recalibration cycles align with material shifts in hospital consolidation patterns and provincial public health regulation updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Global Multi-Access Edge Computing Market
Others
Mobile Computer Market
Others
Duckweed Market
Others
Global Electroshock Weapons Market
Others
Global Military and Aerospace Sensors Market
Others
Snus Market
Others
Turbo Mills Market
Others
Asia-Pacific Medical Simulation Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Global Surface Analysis Market
Others
Heavy Duty Vacuum Bottle Market
Others
Global Webinar and Webcast Market
Others
North America Medical Simulation Market
Others
Industrial Hooters Market
Others
Global Process Equipment Market