
 North America Wiring Duct Market | 2026-2036
North America Wiring Duct Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wiring Duct Market Intelligence
The historic purchasing dominance of industrial MRO buyers is unwinding as project-based procurement from data center and renewable energy developers gains precedence. Panduit leverages its extensive product portfolio to capture significant share within new data center builds in the United States. HellermannTyton competes with specialized solutions for both commercial and industrial applications across North America. ABB sustains its position through deep relationships with established manufacturing and energy sector clients.
Wiring duct refers to channels that organize, route, and protect electrical cables within control panels, machinery, and buildings. Products feature slotted or solid-wall designs and are typically made from Polyvinyl Chloride (PVC) or halogen-free thermoplastics. While non-metallic Polyvinyl Chloride ducts hold the largest volume, higher margins are found in specialized flexible and modular systems. The telecommunications end-user segment is expanding faster than the traditional manufacturing base.
Product design and material selection are heavily influenced by the National Electrical Code (NEC) in the United States and the Canadian Electrical Code (CEC). Compliance with UL and CSA standards for flammability and material safety is a mandatory requirement for market access across North America. Vendor success will depend on navigating the trade-offs between cost-effective PVC solutions and premium, regulation-compliant halogen-free alternatives.
Market Dynamics
The North America wiring duct market is defined by a structural demand shift away from traditional industrial maintenance toward large-scale, project-based procurement. This change, driven by massive investment in data centers and renewable energy infrastructure, prioritizes volume and regulatory compliance.
Growth Catalysts
- Stricter Fire Codes:Revisions to the National Electrical Code and Canadian Electrical Code are compelling the use of materials with superior fire performance, creating demand for halogen-free wiring duct in sensitive applications like transit and data centers.
- Data Center Construction:The expansion of hyperscale and colocation facilities, particularly in US data center corridors like Northern Virginia and Dallas-Fort Worth, generates substantial, concentrated demand for high-density cable management solutions.
- Telecommunications Expansion:The continued rollout of 5G networks and fiber-to-the-home initiatives across the continent requires extensive use of wiring duct to organize and protect delicate fiber optic cables in enclosures and central offices.
Market Restraints
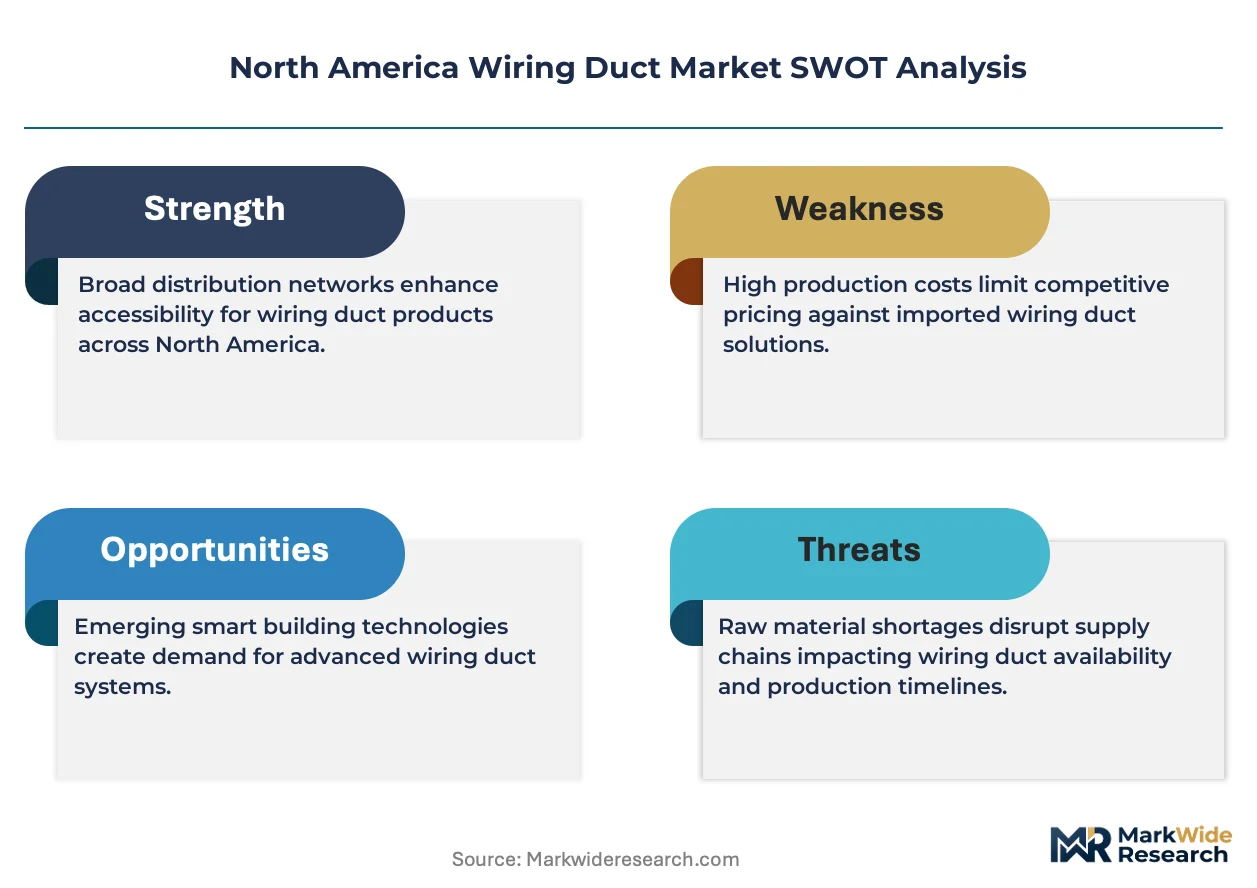
- Raw Material Volatility:Price fluctuations for Polyvinyl Chloride (PVC) resin, a primary feedstock, directly impact manufacturing costs and can lead to pricing instability for standard duct products, complicating long-term project bids.
- Substitution from Cable Trays:In many heavy industrial and commercial construction settings, metal cable trays and conduits represent a durable and often cost-effective substitute for non-metallic wiring duct, limiting market penetration in certain applications.
- Temperature Limitations of PVC:Standard PVC ducts have a relatively low maximum operating temperature, restricting their use in high-heat industrial processes or outdoor applications exposed to direct sun without upgrading to more expensive engineered thermoplastics.
Strategic Opportunities
- Renewable Energy Projects:Solar farms, wind turbine towers, and battery energy storage systems (BESS) represent a significant, underpenetrated application requiring robust solutions for organizing and protecting complex power and control wiring.
- Halogen-Free Formulations:Developing cost-effective, UL-certified halogen-free thermoplastic ducts creates an opportunity to capture premium-margin business from customers in the telecommunications, transit, and public infrastructure sectors focused on life safety.
- Manufacturing Nearshoring in Mexico:The growth of industrial manufacturing in Mexico, driven by nearshoring, expands the addressable market for control panel and facility wiring products that meet North American electrical standards.
Industry Challenges
- Dual-Code Compliance Burden:Manufacturers must engineer and certify products to meet potentially divergent requirements of the US National Electrical Code (NEC) and the Canadian Electrical Code (CEC), increasing design and inventory complexity.
- Channel Adaptation for Project Sales:Traditional distribution networks optimized for small, frequent MRO orders face logistical challenges in servicing the large-volume, just-in-time delivery requirements of major data center and infrastructure construction projects.
- Skilled Labor Scarcity:A shortage of qualified electricians and control panel builders can slow the pace of project completion, which in turn can delay and disrupt the purchasing cycle for components like wiring duct.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wiring Duct Market |
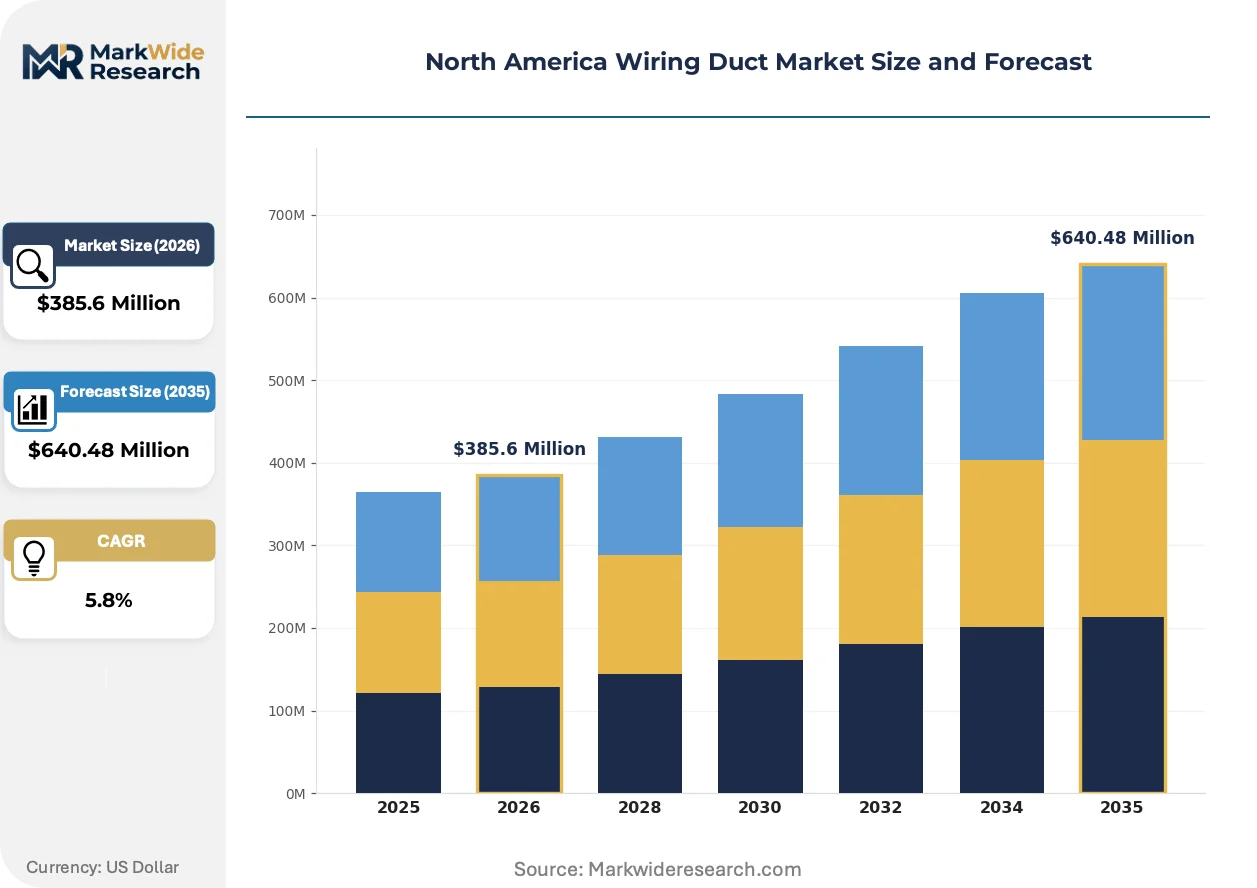
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Metallic, Metallic, Flexible, Modular End User: Telecommunications, Energy, Manufacturing, Commercial Installation Type: Surface-Mounted, Flush-Mounted, Drop-In, Integrated Material: Polyvinyl Chloride, Aluminum, Steel, Polycarbonate |
| Companies Covered | ABB, Panduit, IBOCO, HellermannTyton, TE Connectivity, Phoenix Contact, Omega Engineering, Inc, Electriduct, SESCO, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wiring Duct Market Strategic Shifts & Innovations
Material science advancements and application-specific designs are transforming wiring duct from a commodity component into a specialized system. This evolution is a direct response to stringent fire safety mandates and the unique cable management needs of high-density digital infrastructure.
Modular wiring duct systems feature removable side walls and fingers, enabling on-the-fly customization for cable breakouts. Control panel assemblers and machine builders rapidly adopt these products to accelerate production and minimize cutting waste. This design flexibility is decomposing the rigid, fixed-slot product model, pushing the market toward more configurable and tool-less solutions.
Updated articles within the National Electrical Code (NEC) and the Canadian Electrical Code (CEC) are placing greater scrutiny on the fire performance of non-metallic materials. This regulatory pressure directly incentivizes the development and use of halogen-free thermoplastics that produce less smoke and toxic fumes. The telecommunications sector, particularly in data center construction, is leading the adoption of these premium, compliant materials to enhance facility safety.
Engineering and design firms are increasingly specifying entire cable management ecosystems rather than just individual components. This practice displaces the traditional MRO procurement model, where electricians made on-the-spot choices from distributor stock. This system-level specification is most prevalent in large-scale data center and industrial projects across the United States, favoring suppliers with broad, integrated product portfolios.
North America Wiring Duct Market Segmentation
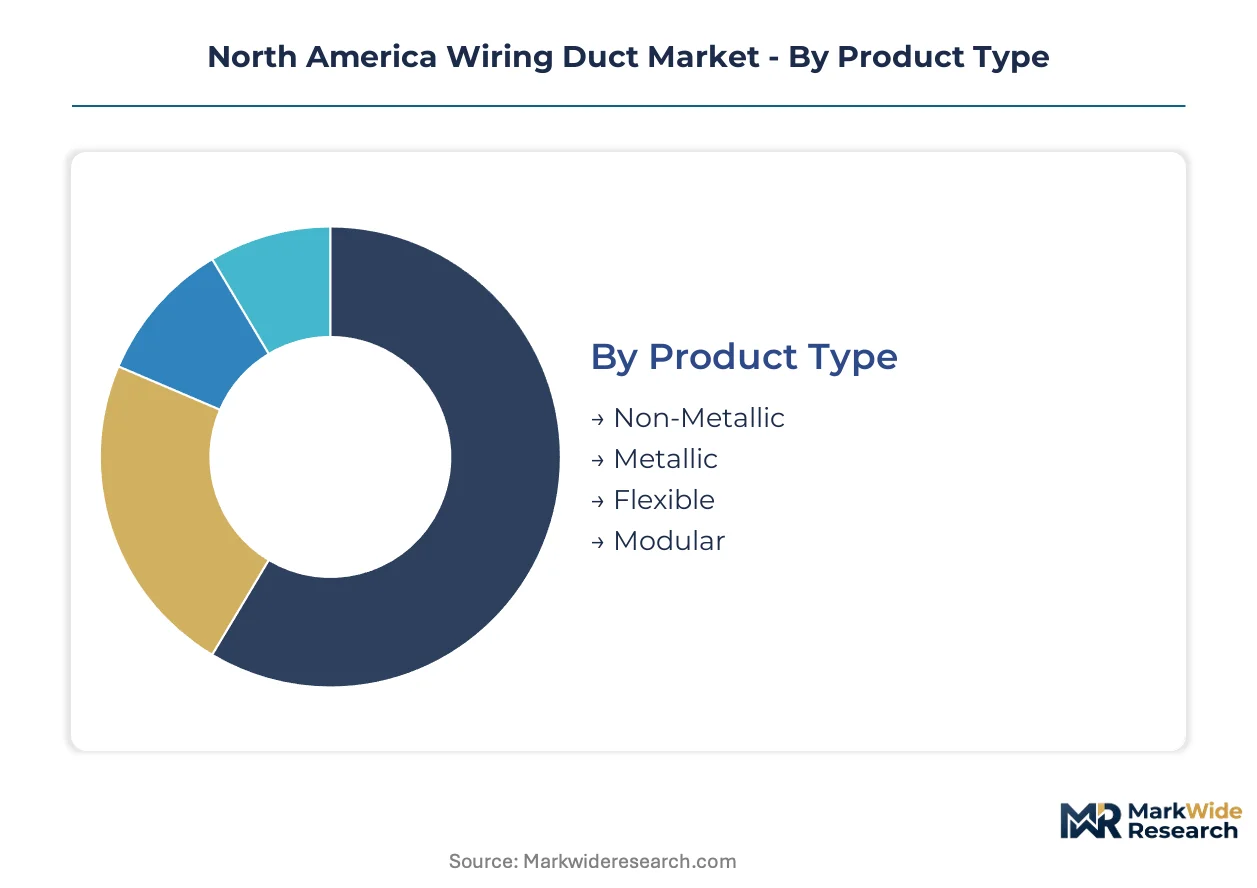
The North America wiring duct market exhibits diverse segmentation, reflecting specialized product requirements across various applications and end-user demands. Understanding these distinct segments is crucial for identifying areas of concentrated demand and emerging opportunities within the continent.
Product Type:
The product type segmentation for wiring duct in North America highlights distinct demand patterns, with some solutions primarily serving domestic infrastructure projects while others find broader application across the continent.
- Non-Metallic:These products are typically made from Polyvinyl Chloride or halogen-free thermoplastics, offering essential electrical insulation and corrosion resistance. Demand for non-metallic ducts is widespread across commercial and light industrial applications in the US and Canada, driven by their cost-effectiveness and ease of installation.
- Modular:Modular wiring duct systems feature removable side walls and fingers, allowing for flexible cable routing and on-site modifications. These systems are gaining significant traction in high-density data center builds in Northern Virginia and Texas, where rapid deployment and customization are critical for complex cable management.
- Metallic:Comprises steel or aluminum channels, providing robust physical protection and electromagnetic interference shielding in demanding environments.
- Flexible:Designed for dynamic applications or areas requiring movement, often constructed from corrugated plastics or specialized braided materials.
Non-Metallic products command the established base. The steepest expansion runs through Modular systems.
End User:
The end-user segmentation reveals how wiring duct solutions are tailored to meet the specific operational and environmental demands of various industries.
- Telecommunications:This sector requires high-density cable management for fiber optic and copper infrastructure, often prioritizing halogen-free materials for enhanced fire safety. Demand is heavily concentrated in hyperscale data centers and 5G network rollouts across the United States and Canada.
- Manufacturing:Wiring duct in manufacturing involves organizing power and control wiring within industrial machinery and complex control panels, often needing robust, temperature-resistant solutions. Demand remains strong in traditional industrial hubs but also expands with nearshoring activities observed in Mexico.
- Energy:Applications include solar farms, wind power installations, and battery energy storage systems, requiring durable outdoor-rated cable protection solutions.
- Commercial:Encompasses office buildings, retail spaces, and institutional facilities, primarily using ducts for organized power and data cable distribution within interior spaces.
Telecommunications is expanding most quickly. Manufacturing remains a foundational market segment.
Installation Type:
Wiring duct installation types reflect varying complexities and material costs, influencing overall project budgets for cable management solutions.
- Surface-Mounted:These ducts are installed directly onto walls or equipment surfaces, offering easy access for maintenance and future modifications. Demand for surface-mounted solutions is widespread across commercial and industrial settings in North America due to their simplicity and lower installation cost.
- Integrated:Integrated wiring ducts are designed to be seamlessly incorporated into machinery, control panels, or architectural elements, often requiring custom engineering. Demand is growing in advanced manufacturing and specialized data center applications where aesthetics and space optimization are critical considerations.
- Flush-Mounted:Installed within walls or ceilings, providing a clean, concealed appearance suitable for commercial and public spaces where aesthetics are important.
- Drop-In:Features a design allowing cables to be easily placed from the top, simplifying installation and future cable additions in control panels and enclosures.
Surface-Mounted installations constitute the largest volume. Integrated solutions represent a high-value niche.
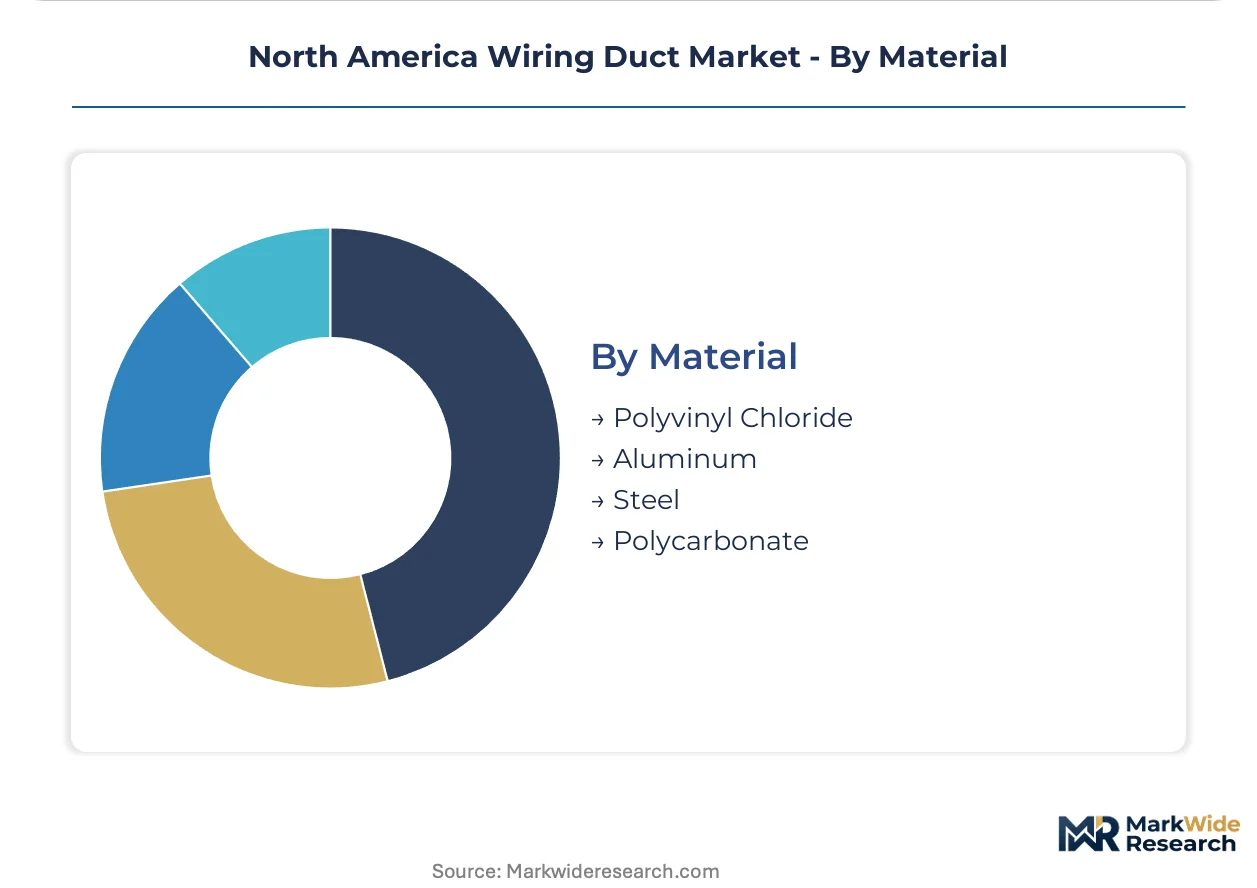
Material:
The material segmentation highlights the maturity curve of wiring duct products, from long-established plastics to newer engineered thermoplastics and metals.
- Polyvinyl Chloride:A cost-effective and widely used thermoplastic, Polyvinyl Chloride offers good electrical insulation and chemical resistance for general applications. Demand for PVC ducts dominates general-purpose applications across North America, though its market share faces challenges from evolving fire safety regulations.
- Polycarbonate:An engineered thermoplastic known for its high impact resistance, broader temperature range, and often halogen-free properties. Demand for polycarbonate ducts is increasing in sensitive applications like data centers and transit systems in the US and Canada due, in part, to stricter fire codes.
- Aluminum:Provides lightweight, corrosion-resistant cable protection, often used in outdoor or marine environments where weight and environmental exposure are concerns.
- Steel:Offers maximum physical protection and electromagnetic shielding, preferred in heavy industrial settings or high-security areas requiring robust cable containment.
Polyvinyl Chloride maintains its market lead by volume. Polycarbonate is gaining significant ground due to performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's expanding industrial base serves North American demand for wiring duct, driven by nearshoring initiatives. The market demonstrates varied regional dynamics influenced by infrastructure investment and regulatory frameworks. This analysis highlights key demand concentrations across the continent.
United States
Demand for wiring duct in the United States concentrates in hyperscale data center construction and renewable energy projects. The National Electrical Code (NEC) mandates specific fire performance for non-metallic materials. Major data center corridors, including Northern Virginia and Texas, exhibit substantial demand for high-density cable management solutions.
Canada
Canadian infrastructure projects and telecommunications expansion drive wiring duct procurement, particularly for 5G networks and fiber-to-the-home initiatives. The Canadian Electrical Code (CEC) imposes strict material safety and flammability standards. Urban centers like Toronto and Montreal are experiencing increased activity in commercial and data center developments.
Mexico
Nearshoring trends significantly boost manufacturing activities in Mexico, increasing the need for control panel wiring products. Compliance with North American electrical standards is a prerequisite for market access. Industrial clusters in Monterrey and Tijuana are expanding, generating consistent demand for industrial-grade wiring duct.
Northern Virginia
Hyperscale data center development in Northern Virginia creates concentrated demand for modular and halogen-free wiring duct systems. The region's stringent building codes and UL certifications influence material choice for enhanced fire safety. Ashburn, often called "Data Center Alley," is a primary hub for high-density cable management solutions.
Dallas-Fort Worth
Data center expansion and logistics infrastructure projects in the Dallas-Fort Worth area fuel demand for robust wiring duct solutions. Local fire safety regulations and the NEC guide material specifications for new commercial and industrial builds. This metropolitan area attracts significant investment in new data center facilities requiring extensive cable organization.
North America Wiring Duct Market Key Industry Players
Listed leaders compete with private specialists across product breadth and application focus within the North America wiring duct market. The market exhibits a tiered structure, with major industrial conglomerates operating alongside niche component manufacturers. Strategic archetypes include broad-portfolio suppliers, specialized application providers, and integrated system solution developers. Companies pursue portfolio diversification to meet varied end-user needs and engage in geographic expansion to capture new project-based demand.
At the scale-driven end of the market, ABB, a multinational industrial technology company, anchors solutions for established manufacturing and energy sector clients. Panduit, a US-based enterprise, exemplifies a broad-portfolio supplier, leveraging its extensive product range to capture significant share within new data center builds. HellermannTyton, another key player, represents specialized solution providers, offering products for both commercial and industrial applications across North America. These companies navigate the trade-offs between cost-effective PVC solutions and premium, regulation-compliant halogen-free alternatives.
| Leading Market Players |
|---|
| ABB |
| Panduit |
| IBOCO |
| HellermannTyton |
| TE Connectivity |
| Phoenix Contact |
| Omega Engineering, Inc |
| Electriduct |
| SESCO |
Cost & Logistics Intelligence
The shift from Polyvinyl Chloride to halogen-free thermoplastics is reshaping North American wiring duct supply chains and pricing. This material substitution drives higher manufacturing costs and incentivizes localized production to meet stringent regional compliance.
Pricing Analysis
The pricing gap between traditional PVC wiring duct and next-generation halogen-free alternatives reflects evolving regulatory demands. Project-based procurement for data centers drives value-based pricing for specialized modular systems. Price differentiation stems from material composition, UL/CSA certification levels, and customization for high-density applications. Pricing pressure intensifies on standard PVC products due to raw material volatility, while telecommunications developers show lower price sensitivity for compliant solutions.
Supply Chain Analysis
Dependence on Polyvinyl Chloride resin feedstock underwrites a structural vulnerability to commodity price fluctuations for standard wiring duct. Supply concentration for specialized thermoplastic compounds rests with a limited number of global chemical producers. Key manufacturing for North America occurs in the United States and Mexico, driven by nearshoring initiatives. Raw material price volatility represents a significant supply chain risk, while distribution runs through established channels for MRO and direct-to-project sales for large infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America wiring duct market faces a critical shortage of skilled labor, particularly qualified electricians and control panel builders. This capability gap impacts project completion timelines and influences strategic investment decisions for market participants.
For Market Incumbents:Consolidate market share in premium segments by investing in UL/CSA-certified halogen-free product lines. Deepen relationships with data center and renewable energy developers to secure large project-based contracts, countering substitution from cable trays. Reinforce distribution networks to efficiently manage large-volume, just-in-time deliveries for infrastructure projects. Pursue strategic partnerships with material suppliers to mitigate raw material volatility.
For New Entrants and Emerging Players:Differentiate on application-specific solutions for the rapidly expanding renewable energy sector, such as solar farms and battery energy storage systems. Target the modular wiring duct segment within emerging data center corridors like Dallas-Fort Worth, offering tool-less and customizable designs. Focus on cost-effective halogen-free formulations to capture premium-margin business from telecommunications and transit projects. Leverage agile manufacturing to provide rapid prototyping and specialized product variations.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized manufacturers specializing in halogen-free materials or modular wiring duct systems. The market offers long-term viability, driven by sustained investment in digital infrastructure and renewable energy across North America. Target companies with strong UL/CSA certifications and established relationships within the telecommunications and data center sectors. The signal to watch is the pace of new data center construction and the strictness of fire code enforcement in major metropolitan areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mexico | Supports nearshoring manufacturing growth and reduces logistics costs for North American supply. |
| Halogen-Free Product Line Extension | Captures premium demand from telecommunications and transit sectors driven by fire safety regulations. |
| Modular System Development | Addresses the need for flexible, high-density cable management in hyperscale data center builds. |
| Strategic Partnership with Raw Material Suppliers | Mitigates price volatility for Polyvinyl Chloride and secures access to advanced thermoplastics. |
| Investment in Installer Training Programs | Alleviates skilled labor scarcity and accelerates project completion for complex wiring duct installations. |
Research Approach
A spread of perspectives from control panel builders, data center operators, procurement managers, and material scientists converged on the working assumptions for this analysis. Primary interviews were conducted with industry stakeholders, complemented by secondary validation from NEC and CEC documents, UL/CSA standards, and industry association reports. This approach combined bottom-up market sizing with top-down validation to ensure data integrity.
The segmentation dimensions modeled include product type, end-user, installation type, material, and key North American regions. The analytical framework projected market expansion across the analysis window, integrating historical trends and anticipated growth drivers. Compound Annual Growth Rates were derived from an assessment of infrastructure spending and regulatory shifts. Key forecast inputs included projected data center investment and the pace of 5G network rollouts.
The analysis sits within stated boundaries; outcomes outside significant shifts in raw material costs or regulatory enforcement would require recalibration. Forecasts reflect assumptions regarding infrastructure investment and technological adoption. Practitioners should keep alternative scenarios live as economic conditions and code revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Hardware Acceleration Market
Others
Wearable Solar Devices Market
Others
Air Separation Unit Market
Others
Italy Smart Home Market
Others
Latin America 3D Printing Construction Market
Others
Operator Training Simulator Market
Others
One-Way Degassing Valve Market
Others
Europe Smart Homes Market
Others
Europe Medical Simulation Market
Others
US Mobile MRI Services Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Global Mobile Video Optimization Market
Others
Global Lavender Extracts Market
Others
Lepidolite Market
Others
Europe Aircraft Lighting Systems Market
Others
Asia-Pacific Military 4D Printing Market