
 Wall Mounted Paper Napkin Dispensers Market | 2026-2036
Wall Mounted Paper Napkin Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Mounted Paper Napkin Dispensers Market Analytics
China's manufacturing base for stainless steel restroom fixtures is tilting toward higher-capacity output lines to serve export markets. Kimberly-Clark Corporation leverages its captive tissue supply chain to bundle napkin refills with dispenser placements in North American foodservice accounts. Georgia-Pacific LLC sustains channel dominance through broad janitorial distribution partnerships. Essity AB anchors its European position with Tork-branded automatic dispensers engineered for high-traffic hospitality environments.
Wall mounted paper napkin dispensers are mechanical or electromechanical fixtures, typically fabricated from stainless steel or ABS plastic, designed to store and dispense folded or rolled paper napkins while minimizing cross-contamination through controlled single-sheet release mechanisms. These units serve commercial restrooms, foodservice counters, and hospitality venues where hygiene compliance and consumable cost control intersect. Manual dispensers still occupy the largest installed base across budget-conscious municipal and educational facilities, though automatic sensor-activated models are capturing replacement cycles in premium hotel and airport segments where touch-free operation reduces liability exposure. Stainless steel housings command durable goods positioning in institutional specifications, while plastic variants compete on first-cost economics for high-volume quick-service deployments.
The US Food and Drug Administration's Food Code provisions on hand-drying accessibility in food preparation zones shape dispenser placement mandates for restaurant operators. China's Ministry of Ecology and Environment enforces recycled content thresholds in public procurement tenders for restroom equipment, directing material sourcing decisions for suppliers serving state-owned venue projects. The EU Green Deal's embodied carbon tracking requirements are beginning to filter into hospitality sector RFPs across member states. Stakeholders must weigh sensor technology upgrade paths against extended manual dispenser lifecycles as procurement criteria fragment across hygiene, sustainability, and total cost of ownership dimensions.
Market Dynamics
Touch-free sensor technology is compressing replacement cycles across institutional foodservice and hospitality installations, forcing manufacturers to reconfigure product portfolios toward electromechanical platforms while defending legacy manual dispenser revenues in municipal and educational accounts.
Growth Catalysts
- GB Standards Compliance:China's Ministry of Ecology and Environment mandates recycled content thresholds in public restroom equipment tenders, accelerating material sourcing shifts toward certified stainless steel and post-consumer plastic housings.
- Airport Concession Networks:High-traffic transportation hubs in the United States are retrofitting manual dispensers with automatic models to reduce cross-contamination liability exposure and align with tightened FDA Food Code hand-drying accessibility provisions.
- Quick-Service Restaurant Expansion:North American fast-casual chains are standardizing dispenser specifications across franchise locations, creating bundled procurement volumes that favor suppliers with captive tissue supply chains.
Market Restraints
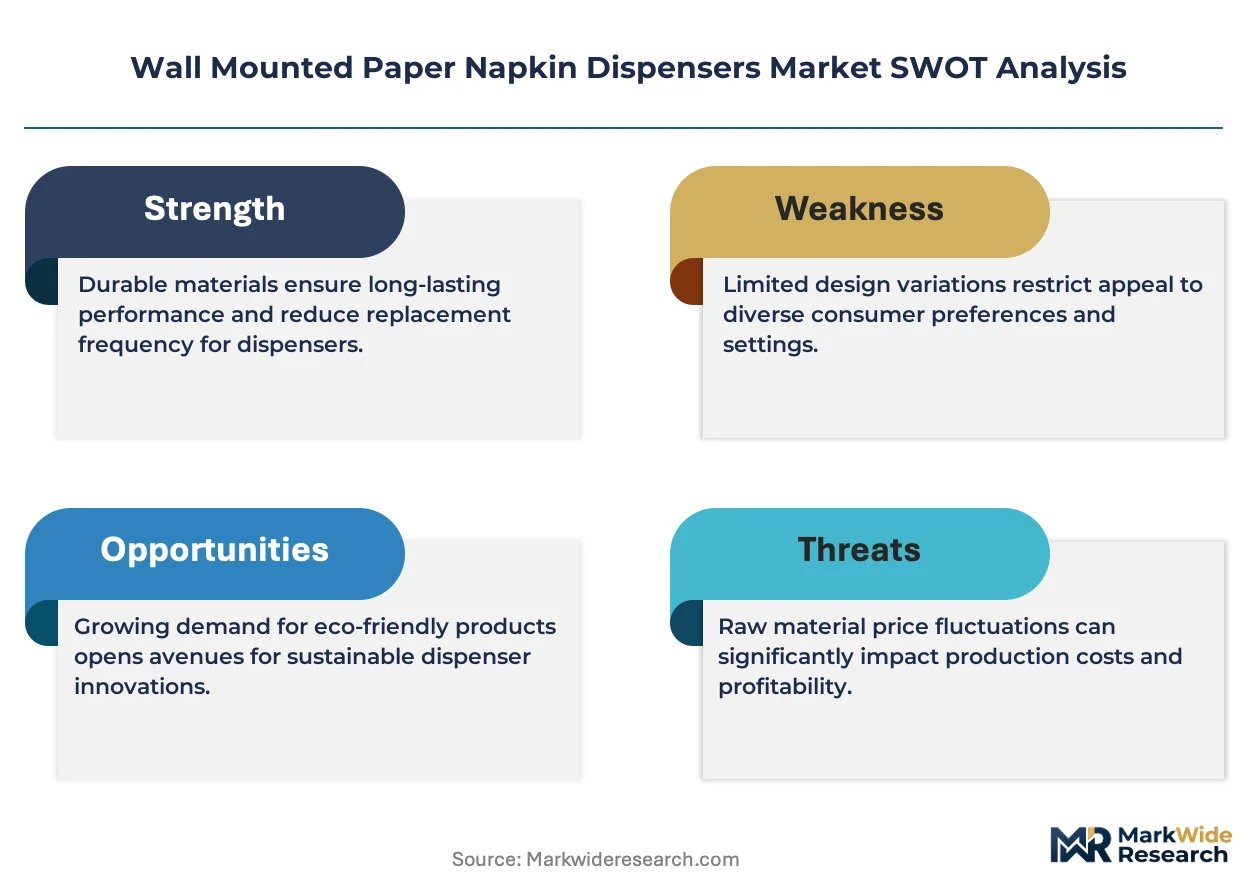
- Stainless Steel Input Volatility:Nickel and chromium price fluctuations compress margin predictability for metal housing fabricators serving institutional specification channels.
- Sensor Component Concentration:Infrared proximity sensor modules depend heavily on concentrated Asian semiconductor packaging capacity, exposing electromechanical dispenser assemblers to supply disruption risk.
- Extended Manual Dispenser Lifecycles:Budget-constrained municipal facilities defer replacement decisions, elongating revenue recognition timelines for suppliers dependent on retrofit-driven demand.
Strategic Opportunities
- EU Green Deal Procurement:Embodied carbon tracking requirements in hospitality sector RFPs across member states create positioning advantages for manufacturers with verified lifecycle assessments and low-carbon steel sourcing.
- Stadium Concession Retrofit Cycles:Major sporting venue operators in the United States are consolidating vendor relationships, opening multi-year service contracts that bundle dispenser hardware with consumable replenishment.
- Sensor-to-Cloud Integration:Convergence of IoT connectivity with napkin level monitoring enables predictive maintenance offerings and usage-based billing models for facility management providers.
Industry Challenges
- Electromechanical Engineering Talent Scarcity:Sensor calibration and firmware development capabilities reside in concentrated regional labor pools, constraining rapid product iteration for mid-tier manufacturers.
- Legacy System Integration Friction:Automatic dispenser retrofits require electrical rough-in modifications that extend installation timelines and complicate contractor coordination in occupied facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Mounted Paper Napkin Dispensers Market |
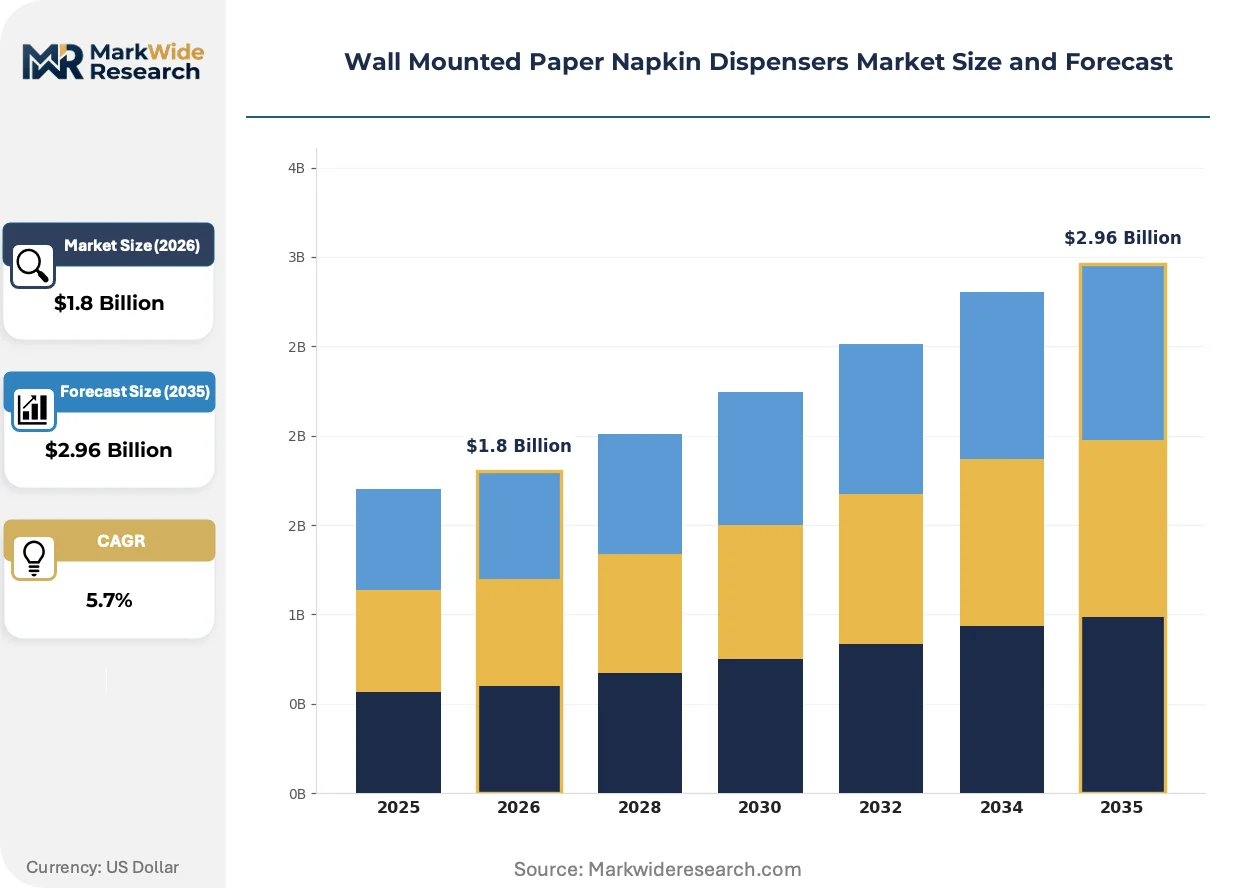
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Automatic Dispensers, Compact Dispensers, Standard Dispensers Material: Plastic, Stainless Steel, Aluminum, Wood End User: Restaurants, Cafes, Hotels, Public Restrooms Distribution Channel: Online Retailers, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Kimberly-Clark Corporation, Georgia-Pacific LLC, Essity AB, San Jamar, Inc., Bobrick Washroom Equipment, Inc., American Specialties, Inc., ALWIN Manufacturing Co., Palmer Fixture, Tork, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Mounted Paper Napkin Dispensers Market Evolving Landscape
Sensor-activated dispensing mechanisms are redefining hygiene compliance expectations across premium commercial installations, while regulatory carbon accounting and procurement consolidation reshape competitive differentiation criteria.
Capacitive proximity sensing combined with brushless motor drives is rendering obsolete spring-loaded mechanical delivery systems in airport and hotel restroom specifications. Premium hospitality operators are specifying these electromechanical platforms as standard during new construction, compressing the addressable market for manual stainless steel housings and shifting RFP evaluation criteria toward reliability metrics and remote diagnostics capability.
REACH substance restrictions and EU Green Deal embodied carbon disclosure mandates are filtering into hospitality procurement specifications across Germany, France, and the Netherlands. Manufacturers serving these markets must now document cradle-to-gate emissions for stainless steel housings and eliminate restricted substances from electronic components, with automatic dispenser product lines facing the most intensive compliance verification requirements due to integrated circuit content.
Facility management providers are consolidating vendor relationships through multi-year service agreements that unbundle dispenser hardware from consumable supply. This contracting evolution concentrates purchasing authority with national accounts teams at quick-service restaurant chains and stadium operators, displacing fragmented local distributor relationships and compressing available margin for regional assemblers lacking direct national account coverage infrastructure.
Wall Mounted Paper Napkin Dispensers Market Segmentation
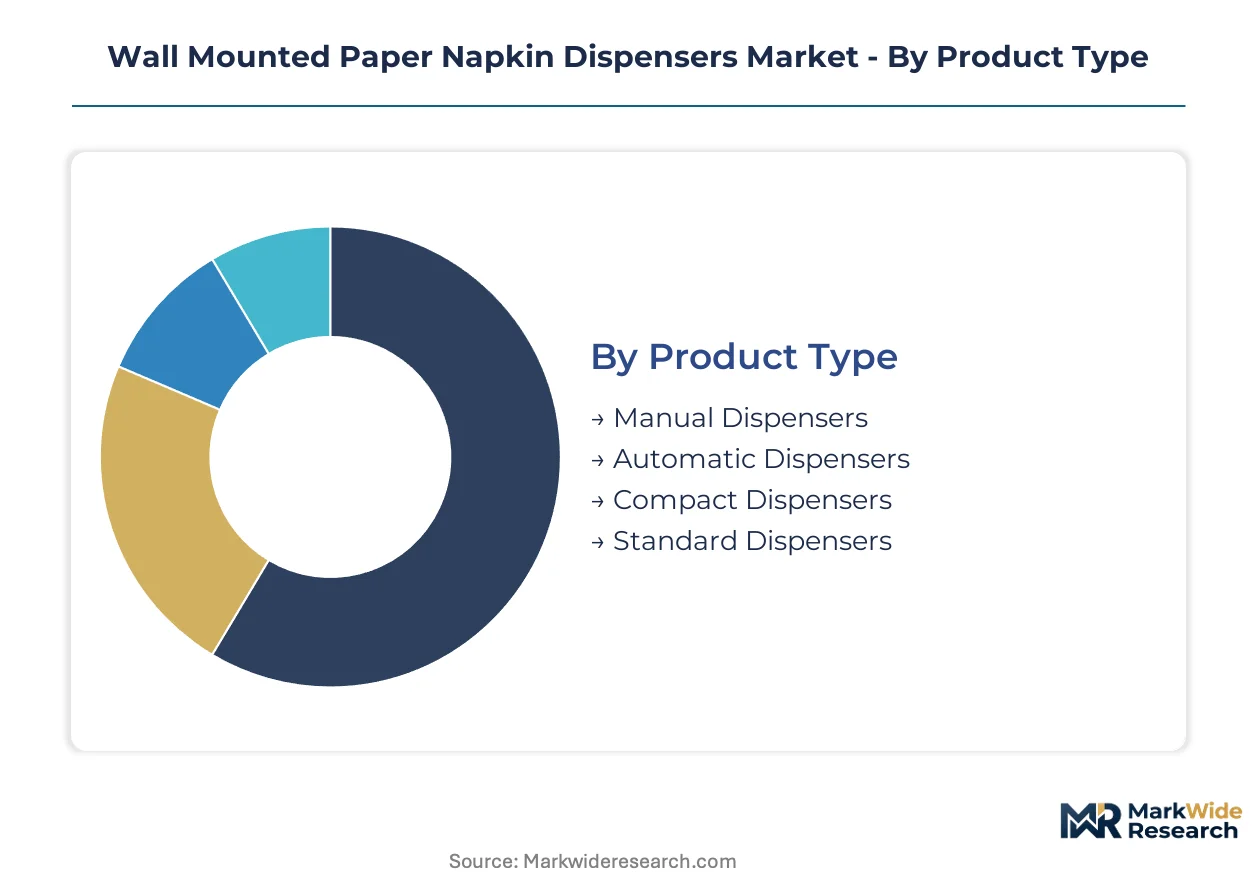
Wall mounted paper napkin dispensers serve divergent operational requirements across foodservice, hospitality, and sanitation infrastructure. Segmentation reveals how procurement criteria fragment across hygiene compliance, durability specifications, and total cost of ownership calculations.
Product Type:
Manual mechanisms dominate budget-constrained installations while sensor-activated platforms capture premium retrofit cycles.
- Manual Dispensers:Spring-loaded mechanical delivery systems fabricated from stamped steel or molded ABS plastic housings. Municipal facilities and educational institutions across the United States defer replacement decisions, elongating revenue recognition timelines for suppliers dependent on volume-driven refresh programs.
- Automatic Dispensers:Infrared proximity sensors combined with brushless motor drives dispense single sheets without physical contact. Airport concession networks and premium hotel operators specify these electromechanical platforms to reduce cross-contamination liability exposure and align with FDA Food Code hand-drying accessibility provisions.
- Compact Dispensers:Reduced-depth housings designed for constrained counter spaces in urban quick-service locations.
- Standard Dispensers:Full-capacity units serving high-traffic institutional restrooms with extended refill intervals.
Established volume favors manual dispensers; emerging adoption favors automatic dispensers.
Material:
Cost tier differentiation separates specification-grade metal fabrications from disposable plastic economics.
- Plastic:Injection-molded ABS or polypropylene housings compete on first-cost economics for high-volume quick-service deployments. China's Ministry of Ecology and Environment enforces recycled content thresholds in public procurement tenders, directing material sourcing decisions toward post-consumer plastic variants.
- Stainless Steel:AISI 304 or 316-grade sheet metal fabrication commands durable goods positioning in institutional specifications. Nickel and chromium price fluctuations compress margin predictability for fabricators serving specification channels requiring corrosion resistance and vandal resistance.
- Aluminum:Lightweight extruded housings balance durability against installation weight constraints in retrofit applications.
- Wood:Veneered or solid hardwood finishes serve boutique hospitality environments where aesthetic integration supersedes utilitarian specifications.
Plastic captures volume in quick-service; stainless steel anchors specification premiums.
End User:
Application intensity varies dramatically across consumption patterns and compliance exposure.
- Restaurants:Food preparation zones mandate dispenser accessibility under FDA Food Code provisions, driving placement density at service counters and back-of-house stations. Quick-service chains standardize specifications across franchise locations, creating bundled procurement volumes.
- Hotels:Premium hospitality operators specify automatic platforms as standard during new construction, compressing the addressable market for manual housings. EU Green Deal embodied carbon disclosure mandates filter into procurement specifications across Germany, France, and the Netherlands.
- Cafes:Limited-service beverage concepts prioritize compact footprints and rapid refill cycles.
- Public Restrooms:State-owned venue projects in China face GB standards compliance pressure toward touch-free automatic models.
Restaurants drive unit volume; hotels command technology upgrade premiums.
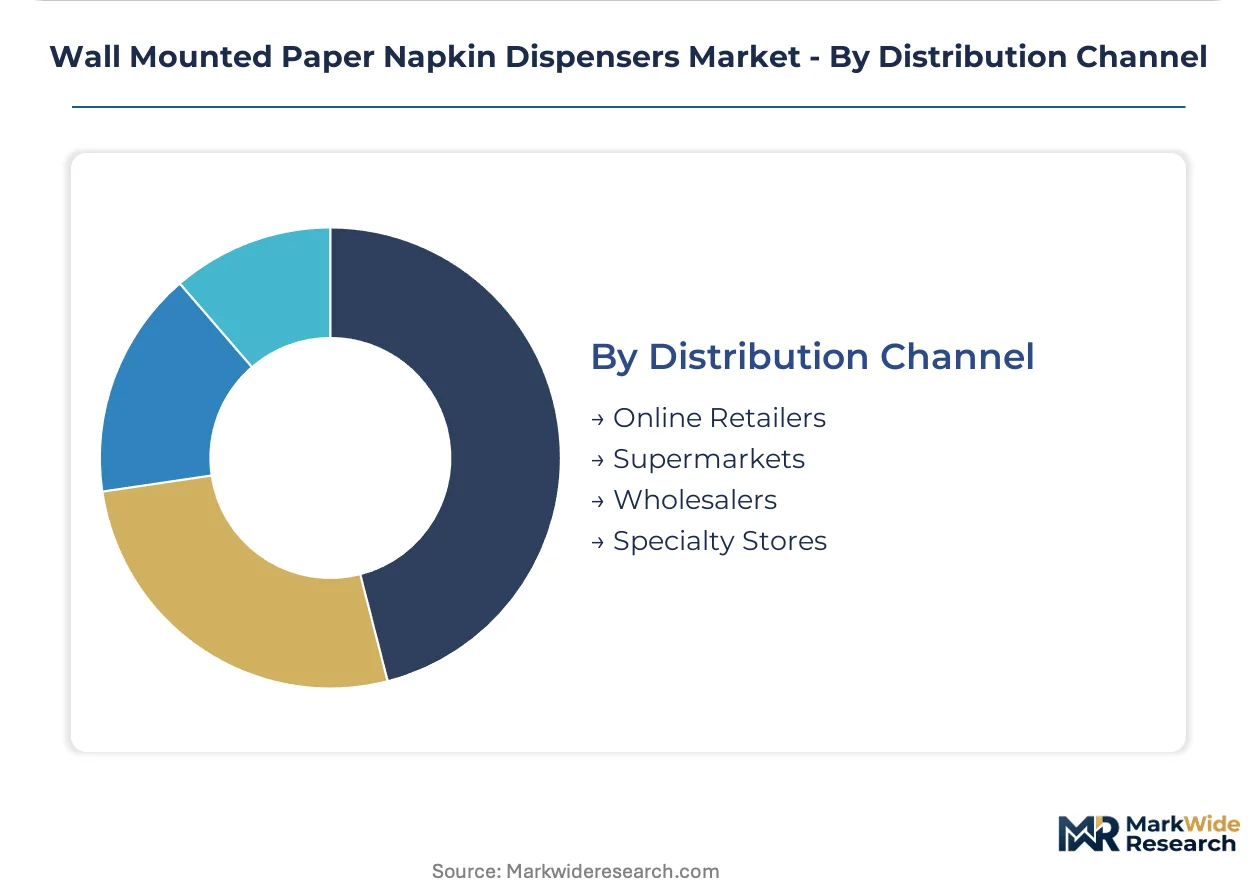
Distribution Channel:
Customer type determines channel economics and service bundling requirements.
- Wholesalers:Broad janitorial distribution partnerships sustain channel dominance for institutional accounts requiring consolidated facility supply procurement. National accounts teams at quick-service chains displace fragmented local distributor relationships.
- Online Retailers:E-commerce platforms serve independent operators and replacement part demand with reduced service overlay.
- Supermarkets:Mass retail placement captures small commercial and residential adjacent demand.
- Specialty Stores:Contract furniture dealers serve new construction specifications with design-integrated dispenser selections.
Wholesalers anchor institutional volume; online retailers expand addressable reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel fabrication clusters in China's Guangdong and Zhejiang provinces feed export demand for institutional-grade housings, while North American quick-service restaurant chains drive specification standardization across franchise networks.
United States
Airport concession networks in Atlanta, Chicago, and Dallas-Fort Worth are retrofitting manual dispensers with automatic models to reduce cross-contamination liability. FDA Food Code hand-drying accessibility provisions mandate dispenser placement density at foodservice counters. Georgia-Pacific LLC leverages captive tissue supply chains to secure bundled procurement contracts with national quick-service chains.
China
GB standards for public restroom sanitation equipment are pressuring state-owned venue projects toward touch-free automatic models. The Ministry of Ecology and Environment enforces recycled content thresholds in procurement tenders, directing material sourcing toward certified stainless steel variants. Manufacturing clusters in Foshan and Wenzhou are expanding higher-capacity output lines to serve European and North American export markets.
Germany
EU Green Deal embodied carbon tracking requirements are filtering into hospitality sector RFPs across Berlin, Munich, and Hamburg hotel developments. REACH substance restrictions eliminate restricted substances from electronic components in automatic dispenser product lines. Essity AB anchors its European position with Tork-branded automatic dispensers engineered for high-traffic hospitality environments.
Japan
Tokyo's commercial corridor operators specify compact dispensers for constrained urban quick-service locations. METI efficiency standards shape electromechanical platform specifications for imported restroom equipment. Osaka-based facility management providers are consolidating vendor relationships through multi-year service agreements bundling hardware with consumable replenishment.
United Kingdom
London's premium hospitality sector drives specification upgrades toward sensor-activated platforms during new construction cycles. CSRD disclosure requirements extend carbon accounting expectations to restroom fixture procurement across hotel and restaurant portfolios. Manchester and Birmingham municipal facilities defer replacement decisions, elongating revenue recognition timelines for manual dispenser suppliers.
Wall Mounted Paper Napkin Dispensers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor modules and motor drives. The vendor base organizes around three strategic archetypes: multinational hygiene conglomerates with captive tissue supply chains, regional metal fabrication specialists serving institutional specifications, and electromechanical platform developers targeting premium retrofit cycles. Competitive moves concentrate on vertical integration into consumable supply and geographic expansion through janitorial distribution partnerships.
Within the multinational tier, Kimberly-Clark Corporation, Georgia-Pacific LLC, and Essity AB exemplify platform integrators that bundle dispenser hardware with tissue refills to secure national account contracts. These corporations leverage scale advantages in procurement and captive manufacturing to defend position against mid-tier regional assemblers lacking direct distribution infrastructure.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Georgia-Pacific LLC |
| Essity AB |
| San Jamar, Inc. |
| Bobrick Washroom Equipment, Inc. |
| American Specialties, Inc. |
| ALWIN Manufacturing Co. |
| Palmer Fixture |
| Tork |
| Others |
Value Network & Pricing Analysis
Foshan's stainless steel fabrication cluster in Guangdong Province commands outsized influence over global dispenser housing economics, with capacity expansions directly translating into pricing leverage for institutional-grade specification channels serving North American and European hospitality procurement.
Pricing Analysis
GB standards compliance dictates the pricing tier structure across Chinese state-owned venue tenders, separating certified recycled-content stainless steel variants from uncertified imports. Three-tier pricing structure across premium automatic, standard manual metal, and economy plastic housings anchors procurement evaluation. Cost compression in sensor-activated electromechanical platforms is intensifying because infrared module sourcing concentrates in concentrated Asian semiconductor packaging capacity. Quick-service restaurant chains exhibit highest price sensitivity due to franchise-standardization volume mandates, while premium hotel operators prioritize reliability metrics over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for metal housing fabricators serving North American institutional accounts. Manufacturing gravity centers on Guangdong and Zhejiang provinces in China, with secondary stainless steel stamping capacity in South Korea and Taiwan. Nickel and chromium feedstock draws from Indonesian mining operations and Russian ferrochrome smelters. Single-source vulnerability in infrared proximity sensor modules constrains electromechanical platform scaling. Distribution runs through broad janitorial distribution partnerships and direct national accounts teams at quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wall mounted paper napkin dispenser market rewards service-attach strategies, with predictive maintenance and consumable replenishment contracts expanding faster than standalone hardware sales across facility management consolidation trends.
For Market Incumbents: Insulate core revenue streams by deepening captive tissue supply chain integration and securing multi-year service agreements with stadium concession operators and airport authorities. Sensor-to-cloud integration capabilities represent a critical defensive lever against mid-tier electromechanical specialists lacking firmware development talent pools. Counter margin pressure from extended manual dispenser lifecycles in municipal accounts by bundling retrofit financing with automatic platform upgrades.
For New Entrants and Emerging Players: Establish a beachhead in compact dispenser segments serving Japan's constrained urban quick-service locations, where METI efficiency standards create specification barriers for legacy Western suppliers. White-space opportunity concentrates in IoT-enabled napkin level monitoring for European facility management providers facing CSRD disclosure requirements. Pursue direct procurement relationships with fast-casual chains standardizing specifications across franchise networks, bypassing fragmented janitorial distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with captive consumable supply and national accounts infrastructure. Long-term viability over the five-to-ten year horizon favors electromechanical platform developers with verified EU Green Deal lifecycle assessments and low-carbon steel sourcing documentation. Acquisition target archetype: regional metal fabricators with institutional specification relationships but lacking sensor integration capabilities. Monitor GB standards enforcement intensity in Chinese state-owned venue procurement as inflection indicator for automatic platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Integration | Enables predictive maintenance offerings and usage-based billing for facility management providers. |
| Captive Tissue Supply Chain | Secures bundled procurement contracts with quick-service chains through vertical control over consumables. |
| EU Green Deal Certification | Positions manufacturers for hospitality sector RFPs requiring verified cradle-to-gate emissions documentation. |
| National Accounts Infrastructure | Displaces fragmented distributor relationships as purchasing authority consolidates with chain procurement teams. |
| GB Standards Compliance Investment | Unlocks Chinese state-owned venue tenders mandating touch-free automatic models and recycled content thresholds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facility management providers, quick-service restaurant procurement directors, hospitality specification architects, janitorial distribution channel managers, and stainless steel fabrication plant engineers. Secondary validation drew from FDA Food Code provisions, China's GB standards documentation, EU Green Deal implementation guidance, customs trade data on restroom fixture imports, and SEC filings from listed hygiene conglomerates. Bottom-up unit demand estimates triangulated against top-down market value reconstructions across the analysis window.
Calibration against historical replacement cycle data and retrofit program announcements anchored volume projections. Segmentation dimensions modeled include product type, material grade, end-use application intensity, and regional regulatory framework. CAGRs were derived from growth rate convergence analysis applied to installed base refresh timelines and new construction specifications. Industry-specific forecast inputs incorporated nickel price volatility indices and semiconductor packaging capacity utilization rates for sensor module availability.
Sensitivities concentrate around Chinese environmental enforcement intensity, stainless steel input cost trajectories, and electromechanical engineering talent scarcity constraining product iteration velocity. Forecasts reflect documented assumptions regarding franchise standardization timelines and airport concession retrofit acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Kraft Paper Mailer Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
SCK Paper Market