
 Secondary Paper and Paperboard Luxury Packaging Market | 2026-2036
Secondary Paper and Paperboard Luxury Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Paper and Paperboard Luxury Packaging Market Analytics
Asset-light leasing of coating and embossing equipment is fragmenting competitive entry barriers in secondary luxury packaging. Mondi leverages its integrated pulp-to-paperboard chain to secure long-term contracts with European cosmetics houses. WestRock Company anchors North American supply through advanced folding carton capacity near metropolitan brand hubs. Fedrigoni S.P.A. differentiates via specialized textured papers for high-end apparel and spirits applications.
Secondary paper and paperboard luxury packaging denotes non-primary protective structures—rigid boxes, sleeves, and presentation wraps—manufactured from caliper ranges typically spanning 12 to 30 point board, often incorporating foil stamping, embossing, and laminated coatings to convey brand prestige. These structures serve as tangible brand touchpoints, designed for unboxing experiences and retail shelf distinction rather than direct product containment. Boxes dominate value capture across the product type dimension, sustained by rigid setup box demand in cosmetics and electronics. Bags and wraps represent faster-growing formats, particularly in apparel and limited-edition food gifting, where lightweight portability and surface printability matter. Coated paper and kraft paper anchor the material split, with recycled grades gaining traction as brand sustainability commitments harden into procurement specifications.
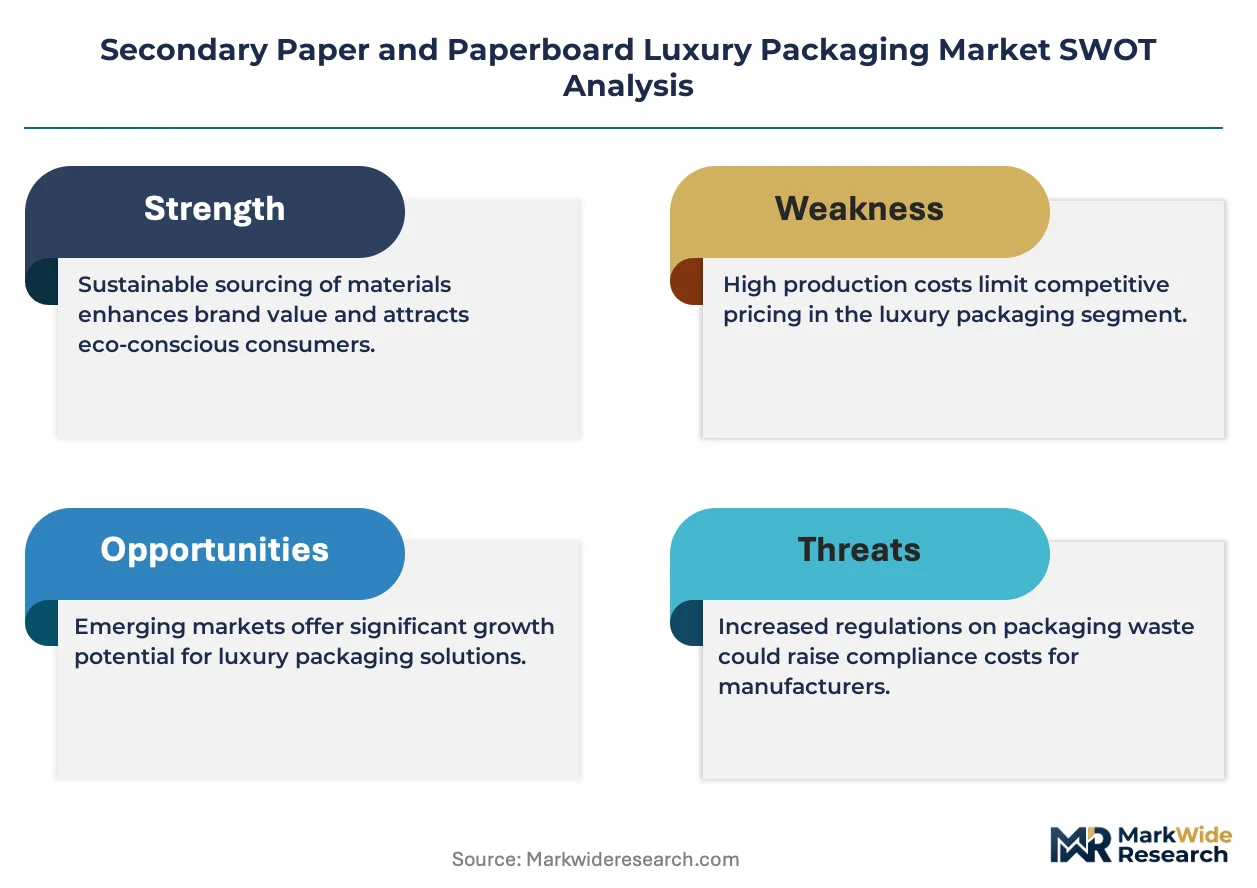
EMA guidelines on pharmaceutical packaging traceability and the EU Packaging and Packaging Waste Regulation together elevate compliance costs for converters serving European luxury brands. FDA food-contact substance notifications and state-level extended producer responsibility laws in California and New York impose parallel requirements on paperboard destined for food and beverage gift applications. Stakeholders must monitor how recycled fiber availability and chemical coating restrictions reshape specification flexibility across premium client portfolios.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing specification flexibility for converters, forcing rapid qualification of recycled fiber grades and FSC-certified substrates across European cosmetics and spirits portfolios.
Growth Catalysts
- EU recycled content mandates:The EU Packaging and Packaging Waste Regulation hardens procurement specifications, pushing luxury houses toward coated kraft and post-consumer fiber grades that converters must now certify.
- China tier-one city demand:Domestic luxury brands in Shanghai, Beijing, and Shenzhen source elaborate rigid box structures for seasonal gift sets, concentrating volume in high-complexity folding carton applications.
- FSC certification penetration:Premium cosmetics houses in France and Italy now specify chain-of-custody documentation for secondary cartons, converting sustainability commitments into binding supplier requirements.
Market Restraints
- Recycled fiber supply concentration:European recovered paper collection rates plateau while Asian import restrictions tighten, squeezing availability of OCC and DLK grades qualified for luxury applications.
- Chemical coating compliance friction:ECHA restrictions on per- and polyfluoroalkyl substances limit conventional grease-resistant treatments, forcing costly reformulation of barrier coatings for food-contact gift packaging.
- Rigid box automation limits:Setup box manufacturing resists full mechanization, constraining throughput scaling for small-batch luxury runs and preserving labor-intensive cost structures.
Strategic Opportunities
- India premium retail expansion:Domestic cosmetics and jewelry brands in Mumbai and Delhi commission rigid presentation packaging as mall-based luxury retail deepens, creating demand for imported textured paperboard.
- Digital embellishment convergence:Hybrid presses combining inkjet personalization with conventional foil stamping enable mass-customized unboxing experiences for limited-edition spirits releases.
- California EPR tailwinds:State-level extended producer responsibility laws impose recycled content floors that advantage early-qualifying converters in North American food and beverage gifting.
Industry Challenges
- Hot foil stamping skill scarcity:Master craftsmen capable of registering complex multi-level embossing on rigid boxes command premium wages, constraining capacity expansion for heritage European converters.
- Dual certification timelines:Simultaneous FSC chain-of-custody and FDA food-contact substance notifications extend qualification cycles, delaying supplier onboarding for cross-category luxury portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Paper and Paperboard Luxury Packaging Market |
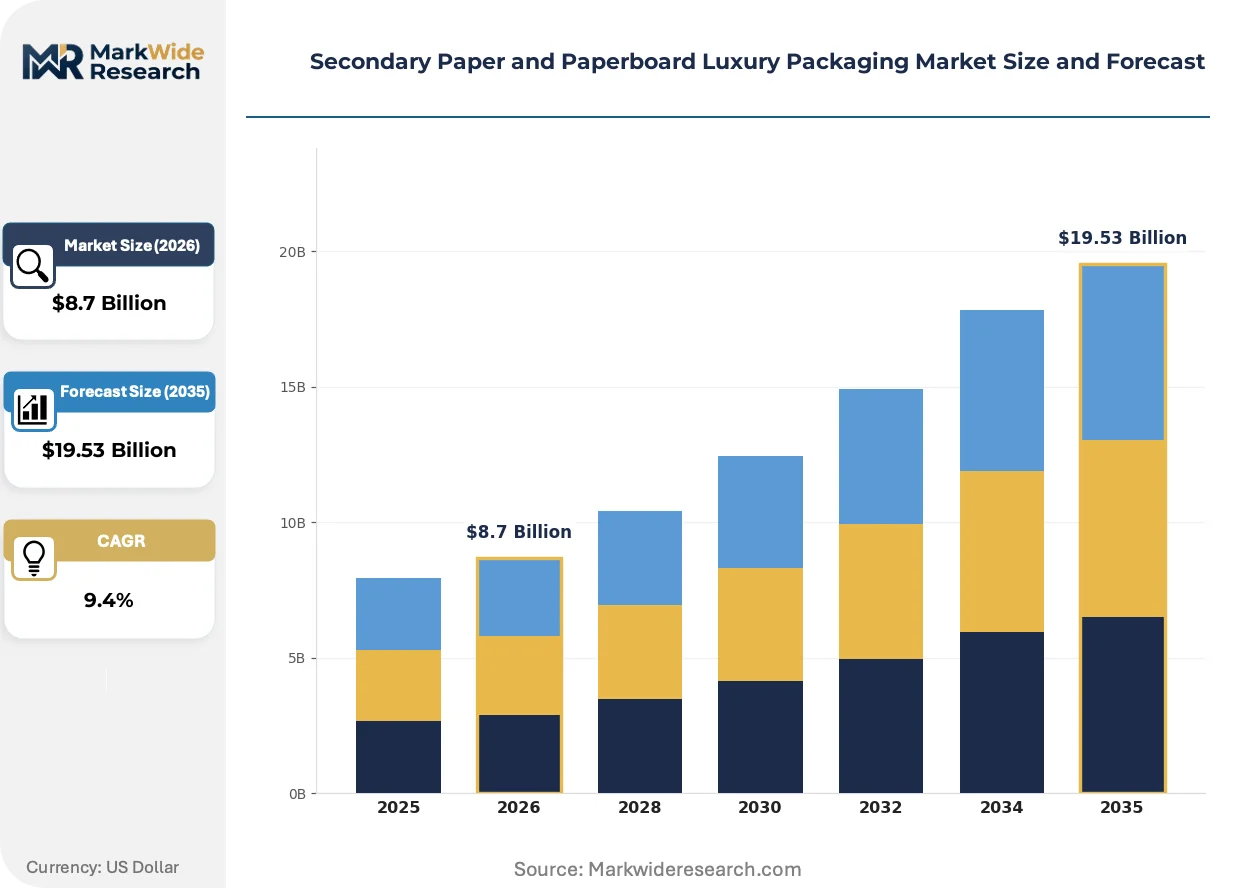
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Sleeves End User: Cosmetics, Food & Beverage, Electronics, Apparel Material: Recycled Paper, Kraft Paper, Coated Paper, Non-Woven Fabrics Design Type: Minimalist, Vintage, Modern, Thematic |
| Companies Covered | Mondi, Sappi, WestRock Company, Mayr-Melnhof Karton AG, Fedrigoni S.P.A., International Paper, Stora Enso, Holmen Iggesund, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Paper and Paperboard Luxury Packaging Market Evolving Landscape
Digital production workflows are compressing traditional make-ready times, while regulatory chemical restrictions and unboxing experience economics reshape specification priorities across cosmetics, spirits, and electronics verticals.
Structural embossing dies produced via additive manufacturing is collapsing setup times for intricate multi-level patterns previously requiring weeks of manual engraving. High-end cosmetics houses in Milan and Paris adopt these digitally-tooled formats for seasonal launches, compressing design-to-delivery cycles from months to days while preserving tactile differentiation.
The EU Packaging and Packaging Waste Regulation's recycled content mandates tighten through 2030, forcing converters to qualify post-consumer fiber grades that previously failed luxury whiteness and caliper specifications. European spirits brands respond by redesigning secondary cartons around visible fiber flecking, converting regulatory compliance into aesthetic storytelling.
Direct brand procurement of rigid box structures is displacing traditional trading house intermediaries in China's tier-one cities. Domestic luxury cosmetics and electronics brands now contract converters directly, unbundling design, materials sourcing, and logistics to capture margin and accelerate iteration cycles for limited releases.
Secondary Paper and Paperboard Luxury Packaging Market Segmentation
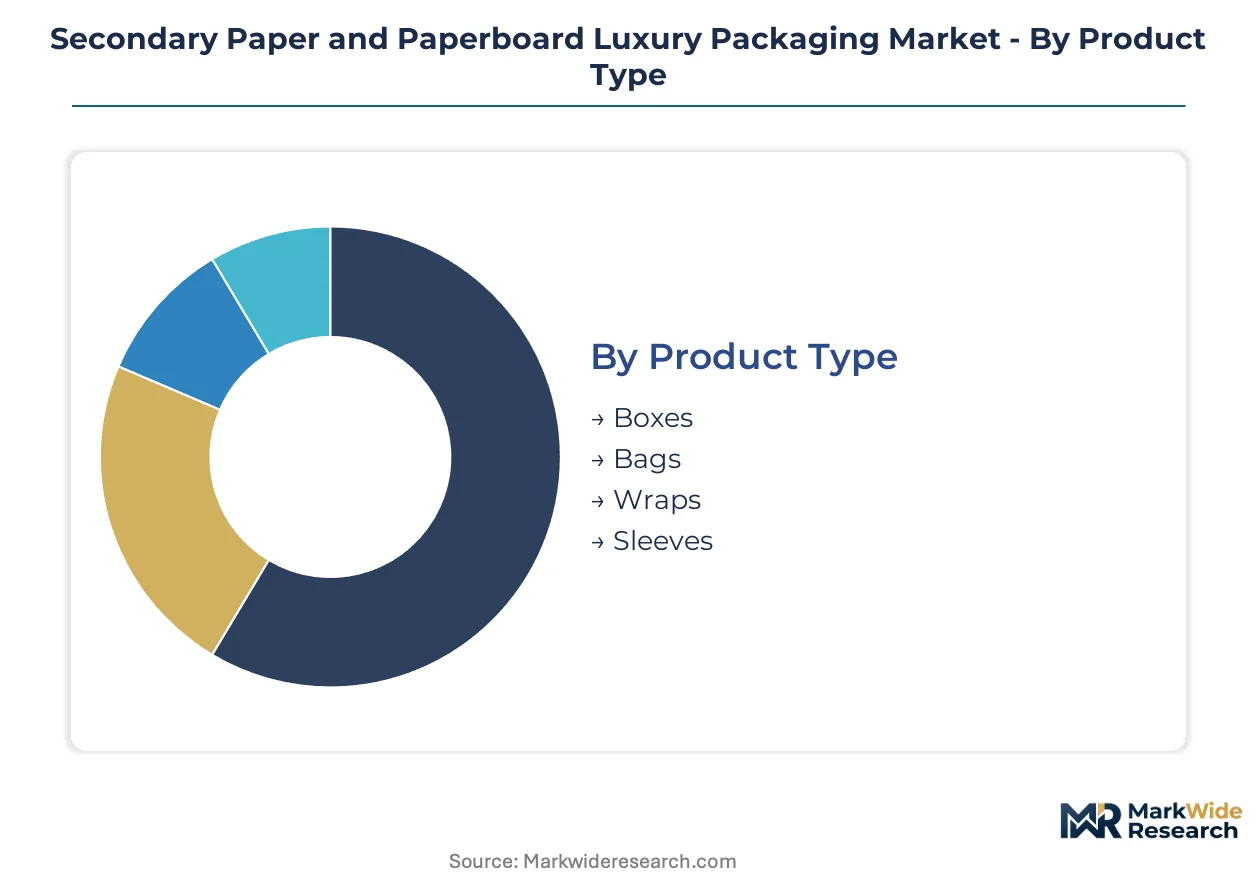
Secondary paper and paperboard luxury packaging serves distinct functional and aesthetic roles across product protection, retail presentation, and unboxing experience. Segment boundaries reflect divergent specification requirements for rigidity, printability, and sustainability certification.
Product Type:
The use-case spectrum spans protective containment, portable carriage, surface wrapping, and structural reinforcement.
- Boxes:Rigid setup boxes and folding cartons manufactured from 18 to 30 point board dominate cosmetics and electronics applications. Demand concentrates in China's tier-one cities where domestic luxury brands commission elaborate structures for seasonal gift sets, constrained by setup box automation limits that preserve labor-intensive cost structures.
- Bags:Lightweight carriers with reinforced handles and laminated surfaces serve apparel and limited-edition food gifting where portability and surface printability matter. European spirits brands redesign formats around visible fiber flecking to convert EU recycled content mandates into aesthetic storytelling.
- Wraps:Flexible presentation layers for bottle necks and box exteriors.
- Sleeves:Structural bands for multi-item bundling and tamper evidence.
The dominant share belongs to Boxes, while Bags is closing the gap fastest.
End User:
Customer procurement patterns diverge across certification requirements, batch sizes, and embellishment complexity.
- Cosmetics:Premium houses in France and Italy specify FSC-certified paperboard for secondary cartons and rigid boxes, converting sustainability commitments into binding supplier requirements with chain-of-custody documentation.
- Food & Beverage:Spirits and gourmet gifting applications face ECHA restrictions on per- and polyfluoroalkyl substances that limit conventional grease-resistant treatments, forcing costly reformulation of barrier coatings.
- Electronics:Unboxing experience economics drive demand for multi-level embossing and foil stamping on rigid presentation structures.
- Apparel:Lightweight bags and wraps represent the fastest-expanding format as mall-based luxury retail deepens in India.
Cosmetics commands the largest specification volume, though Food & Beverage is gaining share fastest through regulatory-driven substrate redesign.
Material:
Substrate selection trades off whiteness, caliper consistency, and post-consumer fiber content against regulatory qualification timelines.
- Coated Paper:Clay-coated surfaces deliver premium print reproduction for high-end cosmetics and spirits applications. European converters face compressed specification flexibility as EU Packaging and Packaging Waste Regulation mandates tighten through 2030.
- Kraft Paper:Unbleached fibers provide structural integrity and visible sustainability credentials. Availability tightens as European recovered paper collection rates plateau while Asian import restrictions squeeze OCC and DLK grades.
- Recycled Paper:Post-consumer fiber grades gain traction as brand sustainability commitments harden into procurement specifications.
- Non-Woven Fabrics:Synthetic fiber alternatives for specialized textile-like presentations.
Coated Paper retains the dominant position, yet Kraft Paper is climbing the fastest on regulatory tailwinds.
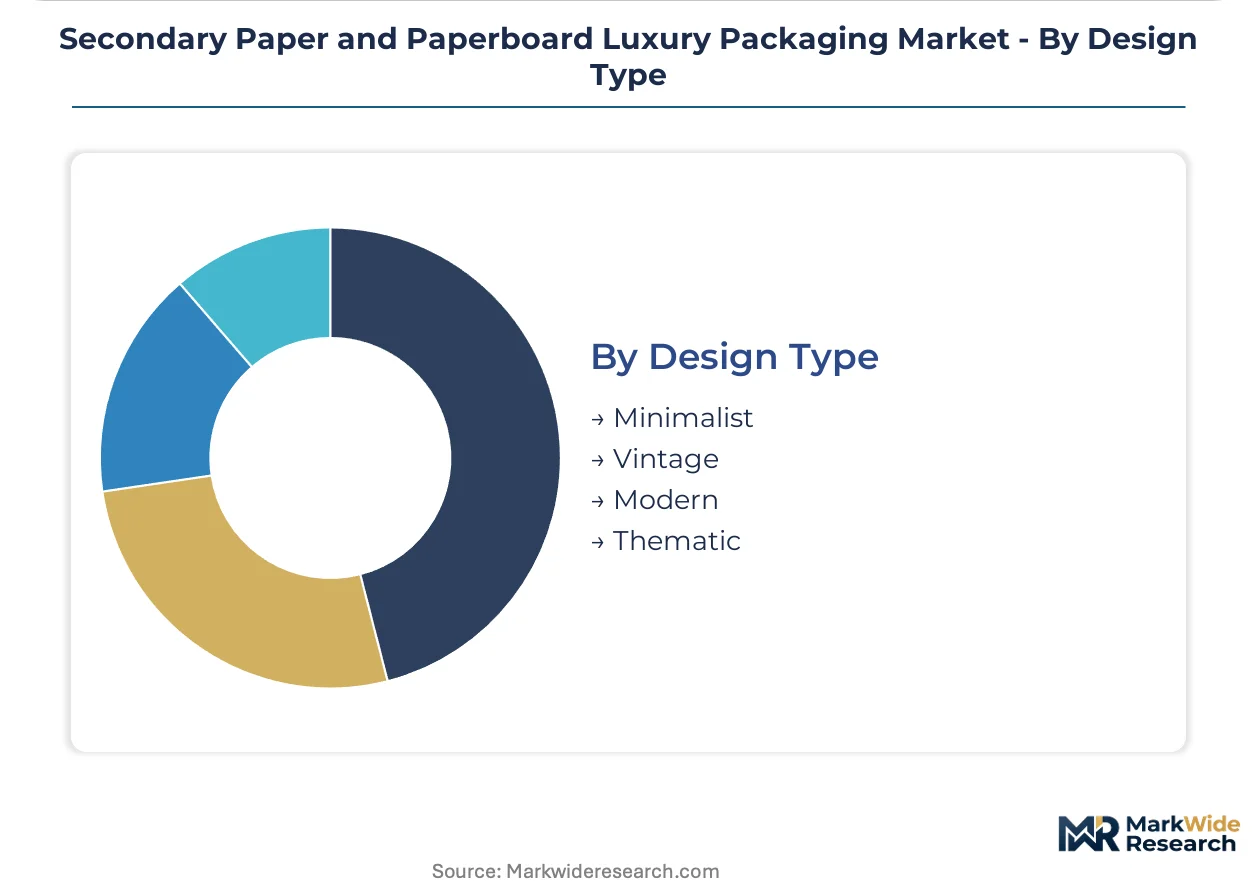
Design Type:
Aesthetic positioning strategies range from heritage signaling to contemporary minimalism, each demanding distinct tooling and production workflows.
- Minimalist:Clean lines and restrained embellishment reduce make-ready complexity while requiring precise substrate whiteness and uniform caliper.
- Vintage:Ornate patterns and tactile textures command master craftsmen capable of registering complex multi-level embossing, constraining capacity expansion for heritage European converters.
- Modern:Hybrid digital-conventional production enables mass-customized unboxing experiences through inkjet personalization combined with foil stamping.
- Thematic:Seasonal and limited-edition formats compress design-to-delivery cycles through additive manufacturing of structural embossing dies.
Minimalist approaches hold the largest share, while Thematic designs are expanding most quickly through digital production workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetics houses in France and Italy anchor buyer concentration for FSC-certified secondary cartons, while China's tier-one cities drive rigid box demand for seasonal gift sets. Regulatory pressure from the EU Packaging and Packaging Waste Regulation and state-level extended producer responsibility laws in California and New York reshape substrate specifications across all major markets.
France
Premium cosmetics houses in Paris and Lyon specify chain-of-custody documentation for secondary cartons, converting sustainability commitments into binding procurement requirements. ECHA restrictions on per- and polyfluoroalkyl substances limit conventional grease-resistant treatments for food-contact gift packaging. The Île-de-France cluster concentrates heritage converters mastering complex multi-level embossing on rigid boxes.
China
Domestic luxury brands in Shanghai, Beijing, and Shenzhen commission elaborate rigid box structures for seasonal gift sets, concentrating volume in high-complexity folding carton applications. SAMR enforcement of GB standards for packaging traceability elevates compliance costs for converters serving multinational cosmetics portfolios. Direct brand procurement now displaces traditional trading house intermediaries in the Yangtze River Delta.
United States
Advanced folding carton capacity near metropolitan brand hubs anchors North American supply for electronics and spirits unboxing experiences. California and New York state-level extended producer responsibility laws impose recycled content floors that advantage early-qualifying converters in food and beverage gifting. The Northeast Corridor concentrates demand for FDA food-contact substance notifications on paperboard destined for gourmet applications.
Germany
Converters serving European spirits portfolios face compressed specification flexibility as EU Packaging and Packaging Waste Regulation mandates tighten through 2030. REACH compliance timelines extend qualification cycles for post-consumer fiber grades previously excluded from luxury whiteness specifications. The North Rhine-Westphalia industrial corridor hosts integrated pulp-to-paperboard chains securing long-term contracts with heritage cosmetics houses.
India
Domestic cosmetics and jewelry brands in Mumbai and Delhi commission rigid presentation packaging as mall-based luxury retail deepens, creating demand for imported textured paperboard. BIS certification requirements for imported paperboard grades add qualification friction for European and North American suppliers. The Maharashtra-Gujarat industrial belt attracts converters establishing dedicated capacity for premium apparel and spirits applications.
Secondary Paper and Paperboard Luxury Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated pulp-to-paperboard chains hold supply security advantages over independent converters. The vendor base clusters around three strategic archetypes: integrated forest products groups with captive fiber supply, independent specialty paperboard converters with embellishment expertise, and multinational packaging conglomerates with geographic scale. Dominant competitive moves include backward integration into coated kraft production and strategic partnerships with luxury houses for co-developed seasonal formats.
Within the integrated forest products tier, Mondi and Stora Enso exemplify upstream control over FSC-certified substrate supply. Among specialty converters, Fedrigoni S.P.A. occupies a position emphasizing textured papers for high-end apparel and spirits applications. At the scale-driven end, WestRock Company anchors North American market presence through metropolitan-proximate folding carton capacity. Mayr-Melnhof Karton AG represents the European independent converter archetype with specialized rigid box capabilities.
| Leading Market Players |
|---|
| Mondi |
| Sappi |
| WestRock Company |
| Mayr-Melnhof Karton AG |
| Fedrigoni S.P.A. |
| International Paper |
| Stora Enso |
| Holmen Iggesund |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
The North Rhine-Westphalia industrial corridor anchors European substrate supply, where integrated pulp-to-paperboard chains convert captive fiber access into pricing leverage over independent converters serving Paris and Milan cosmetics houses.
Pricing Analysis
Long-term cost-plus contracts with OCC and DLK indexation dominate procurement between heritage European converters and luxury cosmetics houses. Price differentiation rests on FSC chain-of-custody certification and caliper consistency for multi-level embossing applications. Pricing pressure stems from recycled fiber supply concentration as Asian import restrictions tighten availability of qualified grades. Mass-market apparel brands exhibit highest price sensitivity, while heritage spirits houses absorb premiums for tactile differentiation.
Supply Chain Analysis
Contract manufacturing concentrates among integrated forest products groups in Germany, Finland, and Austria with captive kraft pulp production. Raw material dependencies center on northern European softwood pulp, South American eucalyptus fibers, and post-consumer OCC streams. Single-source vulnerability runs through recovered paper collection networks facing plateauing European rates. Distribution feeds from mill-direct arrangements to brand-owned converting facilities near Shanghai, Shenzhen, and Delhi retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where direct brand procurement ecosystems in China's tier-one cities are unbundling traditional trading house intermediaries, forcing interoperability between converter design workflows and brand digital asset management systems.
For Market Incumbents: Insulate margin structures by securing backward integration into coated kraft production and locking long-term fiber supply agreements with Nordic pulp mills. The threat of asset-light leasing entrants fragmenting embellishment capacity demands preemptive control over FSC-certified substrate pipelines. For New Entrants and Emerging Players: Pursue white-space expansion in India's Maharashtra-Gujarat industrial belt, where mall-based luxury retail growth outpaces domestic converting capacity. The most penetrable segment lies in textured paperboard for jewelry and apparel applications, accessed through partnerships with European specialty paper importers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core luxury converting divisions with stranded rigid box capabilities. Long-term viability hinges on qualification speed for post-consumer fiber grades under tightening EU mandates. Watch for inflection when direct brand procurement models achieve critical mass in Chinese tier-one cities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coated Kraft | Captive substrate supply secures margin against OCC price volatility and Asian import restrictions. |
| FSC Chain-of-Custody Certification | Binding procurement requirements from Paris and Milan cosmetics houses convert compliance into contract lock-in. |
| Digital Embellishment Convergence | Hybrid inkjet-foil stamping workflows enable mass-customized unboxing for limited-edition spirits releases. |
| Direct Brand Procurement Models | Bypassing trading house intermediaries in Shanghai and Shenzhen captures margin and accelerates design iteration. |
| Additive Manufacturing Tooling | Structural embossing dies produced via 3D printing collapse setup times from weeks to days for seasonal launches. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with procurement directors at European cosmetics houses, converters' technical sales leads, and sustainability compliance officers at luxury spirits brands; and secondary validation against FSC chain-of-custody databases, EU Packaging and Packaging Waste Regulation implementation trackers, and Chinese customs records for textured paperboard imports. Bottom-up volume estimates from converter capacity utilization rates triangulated against top-down demand projections from brand seasonal launch calendars.
Forecast inputs incorporated product type segmentation across boxes, bags, wraps, and sleeves; material grades spanning coated paper, kraft, and recycled fiber; and end-user verticals in cosmetics, food and beverage, electronics, and apparel. CAGRs derived from regression analysis of historical procurement volumes against regulatory mandate timelines and brand sustainability commitment trajectories. Industry-specific inputs included FSC certification penetration curves and rigid box automation adoption rates.
Sensitivities concentrate around recycled fiber availability shocks, ECHA chemical coating restrictions, and Chinese domestic luxury brand procurement model shifts. Cross-checking against FSC annual market reports and EU recovered paper collection statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Coated Paper Market