
 Leukocytoclastic Vasculitis Market | 2026-2036
Leukocytoclastic Vasculitis Market Size, Share, and Industry Trends Forecast 2026-2036
Leukocytoclastic Vasculitis Market Analysis
Aftermarket service revenue from patient monitoring and long-term remission management is narrowing as biologics manufacturers shift toward outcome-based contracts. F. Hoffmann-La Roche Ltd leverages its diagnostics-to-therapeutics integration to capture value across the care continuum. Bristol Myers Squibb Company anchors its position through deep immunology expertise and established rheumatology networks. ChemoCentryx, Inc. specializes in complement pathway modulation, differentiating its pipeline from broader immunosuppressant offerings.
Leukocytoclastic vasculitis denotes a small-vessel inflammatory condition characterized by neutrophilic infiltration, fibrinoid necrosis of vessel walls, and fragmented nuclear debris visible on histopathology, with primary clinical purpose being the diagnosis and management of cutaneous and systemic organ involvement. The biologics segment commands premium positioning due to targeted cytokine inhibition and superior remission rates in refractory cases. Injectable delivery modes lead hospital settings where infusion supervision ensures safety monitoring, while oral corticosteroids retain volume dominance in initial flare management across clinics and homecare settings.
FDA oversight of immunosuppressive biologics through Risk Evaluation and Mitigation Strategies shapes prescriber behavior and distribution channels, while EMA pharmacovigilance requirements for systemic vasculitis therapies influence post-market surveillance obligations across European markets. Health Canada and WHO guidelines on corticosteroid-sparing protocols further constrain conventional therapy expansion. Stakeholders must weigh pipeline positioning against evolving payer criteria for step-therapy protocols and biologic access restrictions.
Market Dynamics
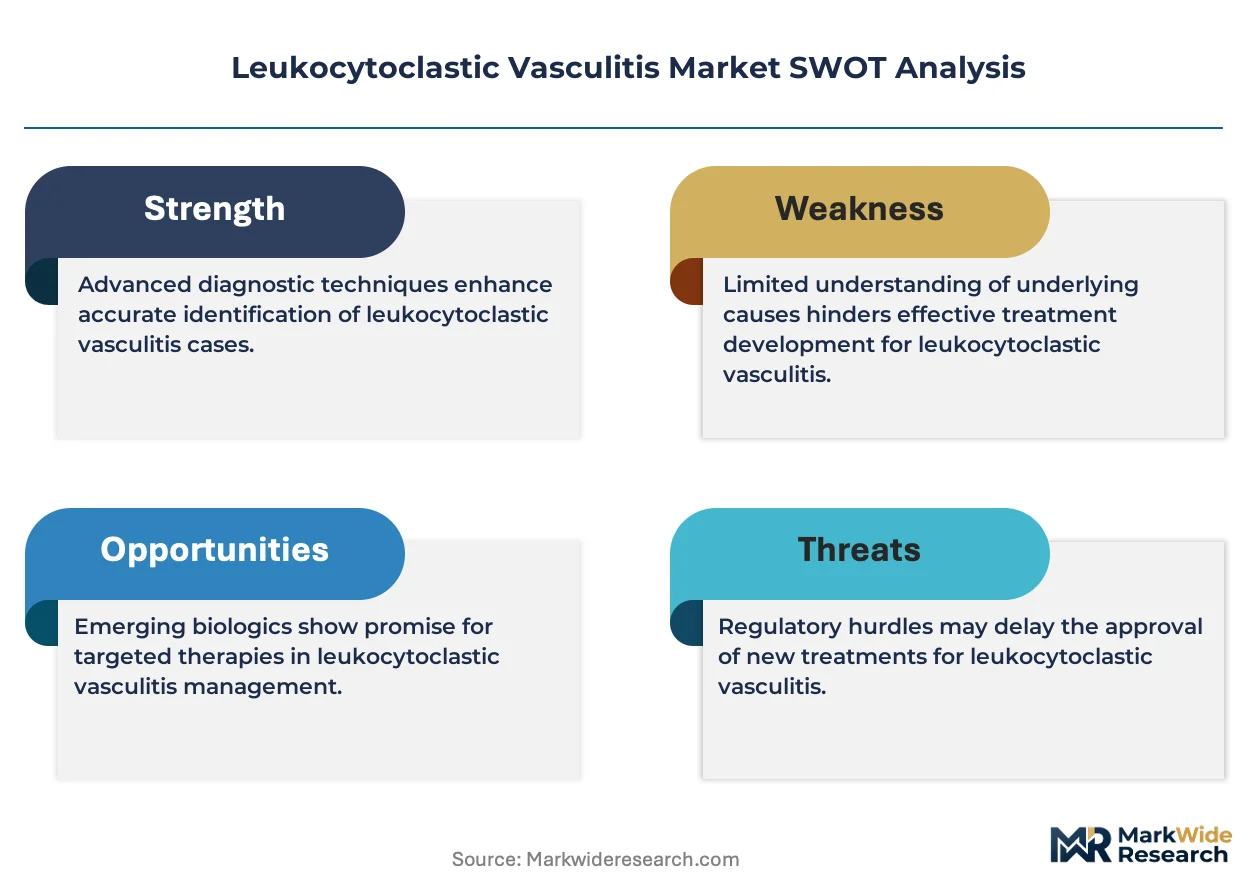
Biologics manufacturers face mounting pressure from FDA Risk Evaluation and Mitigation Strategies that lengthen approval timelines while specialty clinics demand corticosteroid-sparing protocols. This regulatory-clinical tension compresses conventional immunosuppressant margins and accelerates pipeline investment in targeted cytokine inhibitors.
Growth Catalysts
- EMA Pharmacovigilance Framework:Post-market surveillance obligations for systemic vasculitis therapies elevate biologics with cleaner safety profiles above conventional immunosuppressants in European prescribing hierarchies.
- Specialty Clinic Expansion:Dermatology-focused outpatient centers in the United States deploy infusion-capable infrastructure that captures refractory patients requiring biologic supervision.
- Complement Pathway Science:Advances in C5a receptor antagonism create mechanistic differentiation from TNF-alpha and IL-6 blockade, opening addressable subsets within treatment-resistant populations.
Market Restraints
- Infusion Infrastructure Concentration:Hospital-based administration requirements limit biologic penetration to urban centers with hematology-oncology suites, excluding rural and suburban patient pools.
- Corticosteroid Cost Floor:Generic prednisone at sub-dollar daily dosing creates insurmountable price competition for novel agents in initial flare management protocols.
- Step-Therapy Payer Mandates:United States commercial insurers and Medicare Advantage plans require documented failure on corticosteroids plus conventional immunosuppressants before biologic authorization.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered injection platforms bypass hospital infusion requirements and unlock homecare and community clinic channels previously inaccessible to intravenous biologics.
- India Outpatient Dermatology:Rising cutaneous vasculitis diagnosis rates in tier-1 cities create demand for corticosteroid-sparing options among private-pay patients seeking premium therapeutic outcomes.
- Health Canada Biosimilar Pathway:Accelerated approval frameworks for reference biologics with expired exclusivity enable cost-positioned entrants to capture provincial formulary listings.
Industry Challenges
- Histopathology Specialist Shortage:Accurate leukocytoclastic vasculitis diagnosis requires dermatopathology expertise concentrated in academic medical centers, creating diagnostic bottlenecks and treatment delays.
- Remission Definition Heterogeneity:Absence of standardized outcome measures across clinical trials complicates payer value demonstration and cross-product efficacy comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukocytoclastic Vasculitis Market |
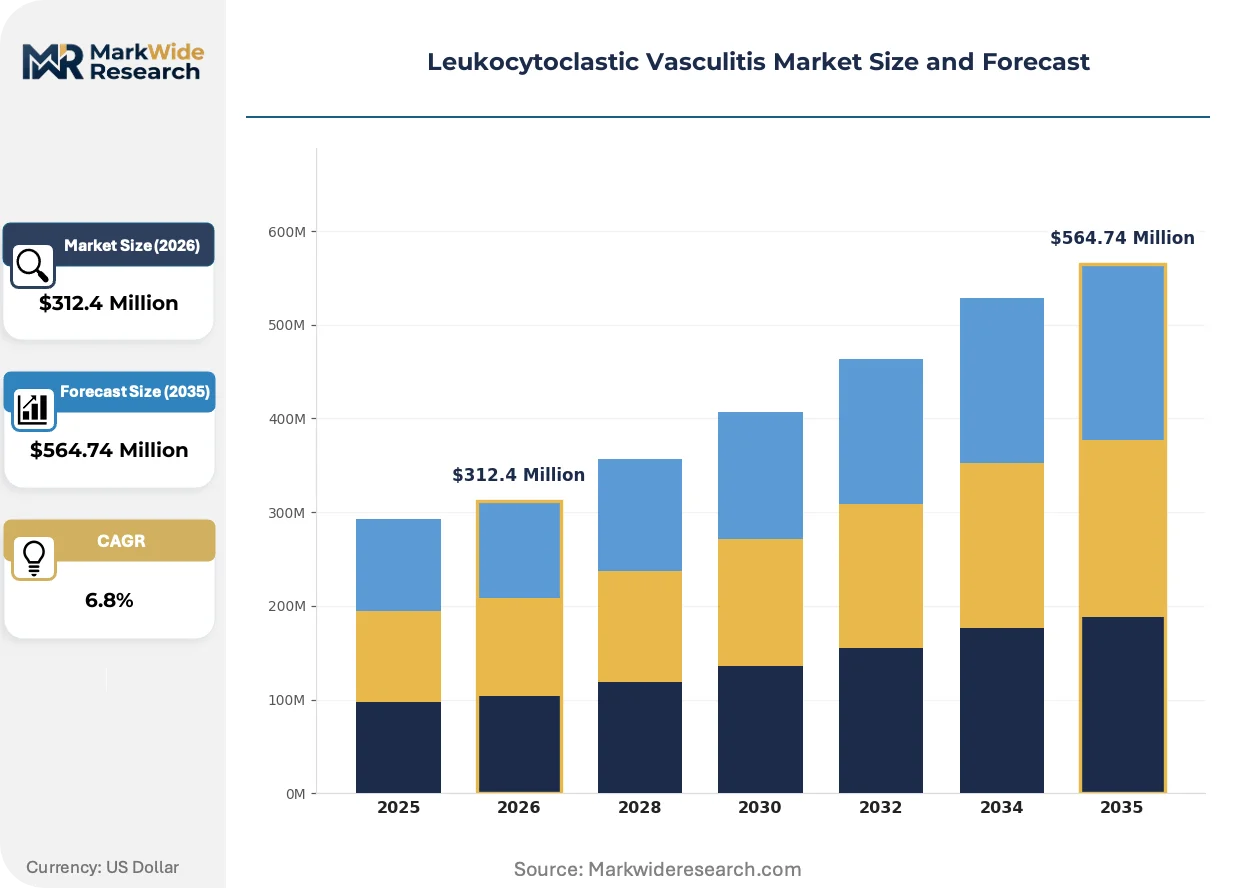
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, Antihistamines Therapy Area: Dermatology, Rheumatology, Nephrology, Allergy End User: Hospitals, Clinics, Specialty Clinics, Homecare Delivery Mode: Oral, Injectable, Topical, Infusion |
| Companies Covered | F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Bristol Myers Squibb Company, AstraZeneca plc, Pfizer Inc., Novartis AG, Johnson & Johnson, Celgene Corporation, ChemoCentryx, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukocytoclastic Vasculitis Market Emerging Trajectories
Digital biomarker capture and remote monitoring platforms are compressing the gap between clinical trial endpoints and real-world evidence generation. These technologies enable continuous safety surveillance that satisfies both FDA and EMA post-authorization requirements while reducing site visit burdens.
Machine learning algorithms applied to smartphone-captured lesion photography are digitizing severity assessment workflows previously dependent on clinician visual analog scales. Specialty clinics in the United States pilot these tools to standardize treatment response documentation for payer prior authorization submissions. The structural consequence is digitizing subjective clinical judgment into quantifiable data streams that accelerate reimbursement decisions.
REACH regulation amendments tightening environmental risk assessments for immunosuppressive manufacturing effluent are forcing European production facilities to deploy closed-system bioreactors and solvent recovery units. Contract manufacturers serving Bristol Myers Squibb and Roche networks absorb capex increases through long-term supply agreements. Small-molecule corticosteroid producers face disproportionate compliance costs relative to biologics manufacturers with existing green chemistry investments.
Patient advocacy organizations now drive formulary access campaigns that bypass traditional physician-channel influence over payer policy. The Vasculitis Foundation and similar groups in Germany and France mobilize refractory case narratives to secure exceptions from step-therapy protocols. This behavioral shift concentrates leverage among organized patient populations with documented biologic response histories, particularly in United States commercial insurance markets where employer-sponsored plans retain flexibility for case-by-case appeals.
Leukocytoclastic Vasculitis Market Segmentation
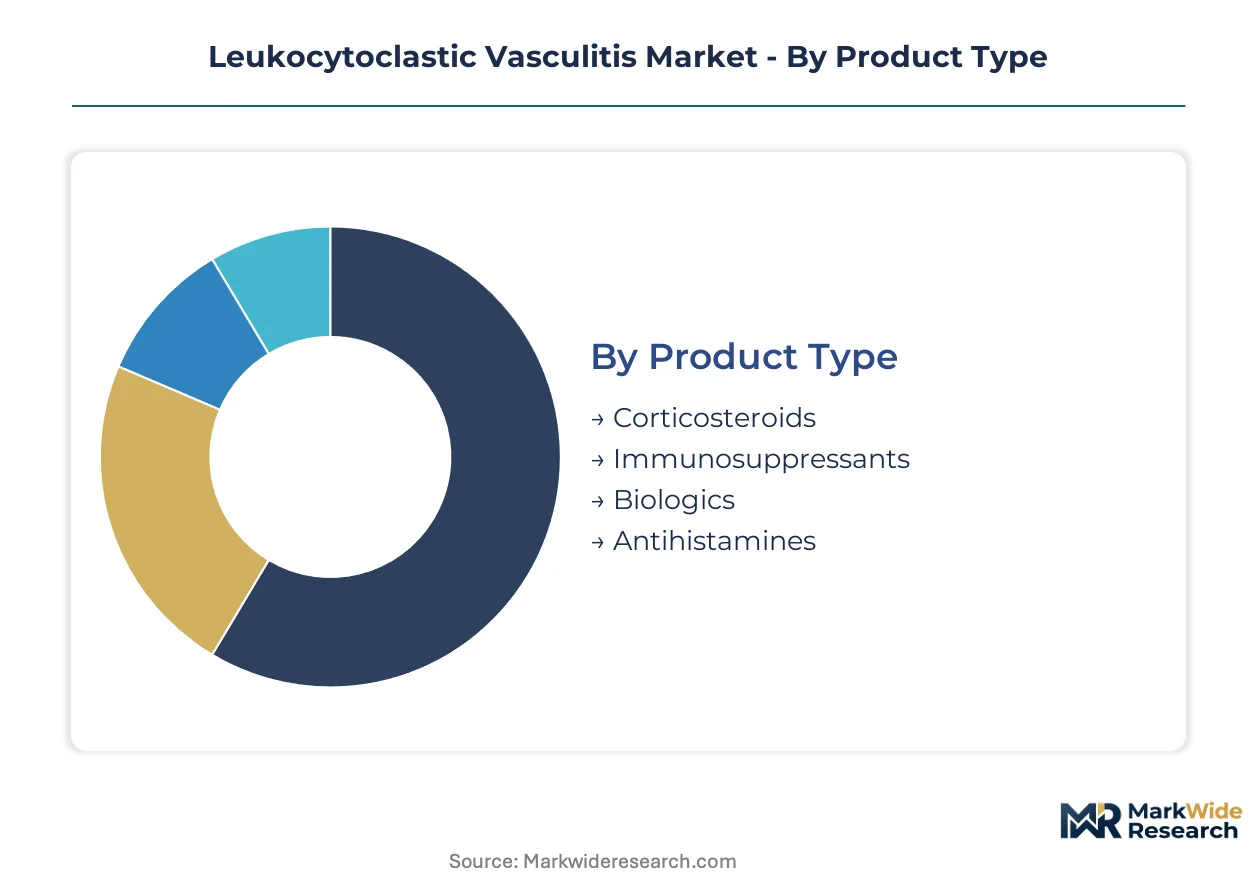
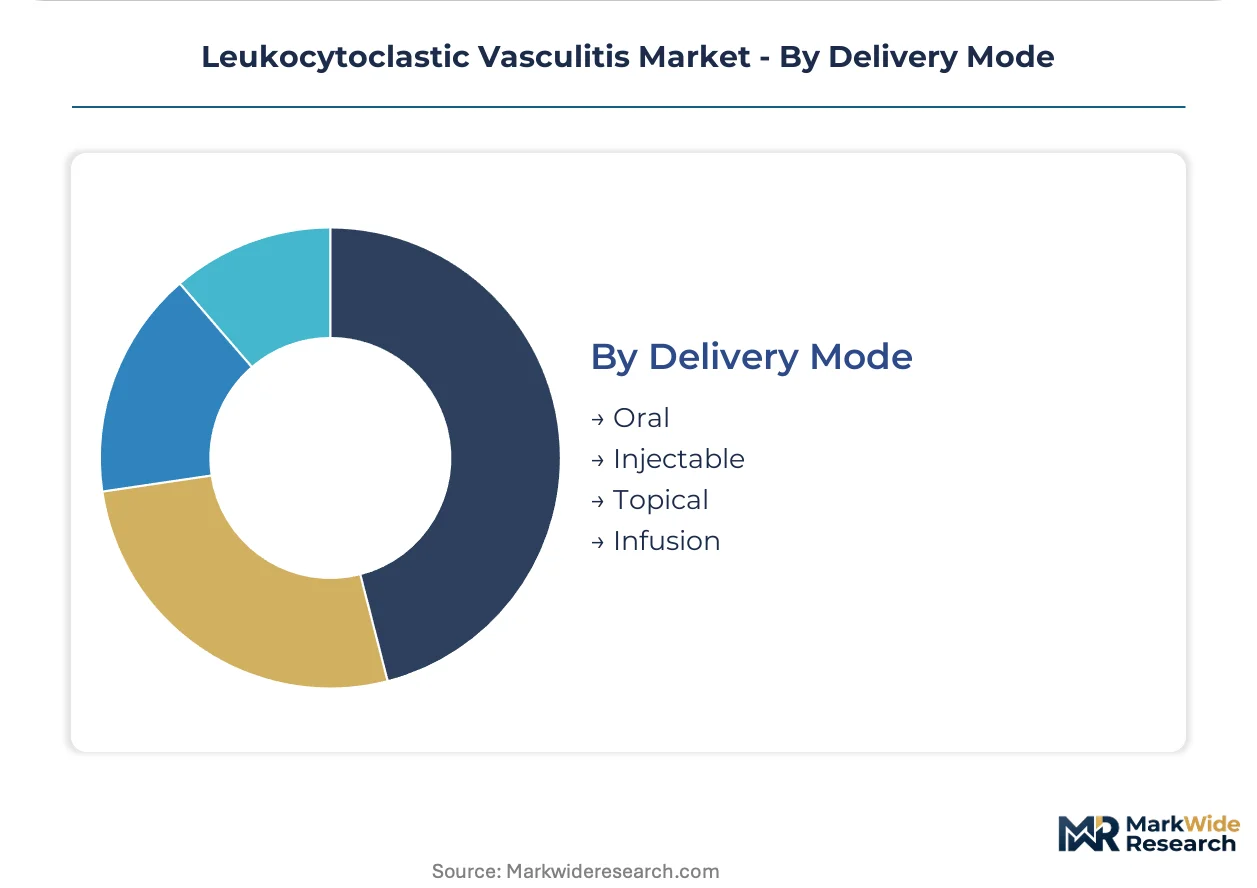
Segmentation in leukocytoclastic vasculitis therapeutics reveals divergent margin structures across acute flare management and chronic remission maintenance. Product type and delivery mode decisions cascade through reimbursement pathways, prescriber specialty, and site-of-care economics.
Product Type:
Use-case spectrum spans immediate symptom suppression through long-term immunomodulation, with each tier commanding distinct pricing authority and regulatory scrutiny.
- Biologics:Engineered monoclonal antibodies and fusion proteins target specific cytokine pathways including TNF-alpha, IL-6, and complement C5a. Demand concentrates in United States specialty clinics where prior authorization workflows favor documented refractory cases and corticosteroid-sparing protocols drive formulary positioning.
- Corticosteroids:Synthetic glucocorticoids such as prednisone and methylprednisolone remain the first-line intervention for acute cutaneous and systemic flares. Generic pricing at sub-dollar daily doses dominates initial therapy in India outpatient dermatology and United States urgent care settings where cost floors preclude novel agent penetration.
- Immunosuppressants:Small-molecule agents including azathioprine, mycophenolate mofetil, and cyclophosphamide serve as corticosteroid-sparing bridges. These occupy the mid-tier in European prescribing hierarchies governed by EMA pharmacovigilance frameworks that elevate agents with established safety databases.
- Antihistamines:H1-receptor antagonists address pruritus and urticarial components in mild cutaneous presentations. These support symptomatic management in homecare and primary care channels where specialist access remains limited.
The dominant share belongs to corticosteroids, while biologics are closing the gap fastest.
Therapy Area:
Prescriber specialty determines diagnostic sophistication, treatment sequencing, and access to infusion infrastructure.
- Dermatology:Cutaneous vasculitis presentations drive the majority of initial diagnoses through lesion biopsy and direct immunofluorescence. United States dermatology-focused outpatient centers deploy infusion-capable infrastructure that captures refractory patients requiring biologic supervision.
- Rheumatology:Systemic involvement with arthralgia, myalgia, or constitutional symptoms triggers rheumatology consultation. This segment demands coordinated corticosteroid-sparing protocols and navigates complex step-therapy mandates from commercial insurers.
- Nephrology:Renal involvement with hematuria, proteinuria, or declining glomerular filtration rate necessitates nephrology co-management. Cases concentrate in academic medical centers with histopathology specialist availability.
- Allergy:Drug-induced and hypersensitivity-associated vasculitis variants fall under allergy-immunology evaluation. This channel manages medication withdrawal protocols and desensitization where appropriate.
Dermatology commands the largest patient volume, though rheumatology generates the highest per-patient revenue.
End User:
Site-of-care economics shape product mix through reimbursement rates, supervision requirements, and patient acuity thresholds.
- Specialty Clinics:Dermatology and rheumatology-focused outpatient centers combine diagnostic capability with infusion infrastructure. United States metropolitan markets see rapid expansion of these facilities as health systems consolidate chronic disease management.
- Hospitals:Inpatient admission governs severe systemic presentations with organ-threatening involvement. Biologic infusions and intensive immunosuppression require hematology-oncology suite access and continuous monitoring.
- Clinics:General outpatient settings manage stable patients on oral corticosteroid tapers and conventional immunosuppressants. These sites face margin pressure from generic substitution and limited prior authorization support staff.
- Homecare:Self-administered oral therapies and emerging subcutaneous biologic platforms enable treatment outside institutional settings. This channel expands with remote monitoring technologies that satisfy FDA and EMA post-authorization surveillance obligations.
Specialty clinics capture the most favorable reimbursement, while homecare is expanding most quickly through subcutaneous formulation adoption.
Delivery Mode:
Administration route dictates prescriber specialty, patient convenience, and safety monitoring intensity.
- Oral:Tablets and capsules dominate corticosteroid and immunosuppressant prescribing across all care settings. This mode enables home initiation and taper protocols but requires patient adherence monitoring.
- Injectable:Subcutaneous biologics and conventional immunosuppressants bypass gastrointestinal absorption variability. Self-injection platforms unlock community clinic and homecare channels previously inaccessible to intravenous agents.
- Infusion:Intravenous biologics require hospital-based or specialty clinic administration with supervision for infusion reactions. Urban concentration of hematology-oncology suites limits geographic penetration.
- Topical:Corticosteroid creams and calcineurin inhibitors address localized cutaneous lesions. These serve as adjunctive therapy in mild presentations and steroid-sparing maintenance.
Oral delivery retains volume leadership, though injectable formats show the steepest expansion trajectory as subcutaneous biologics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters concentrate in Switzerland, the United States, and Germany, creating supply corridors that shape patient access patterns across high-income markets. Distribution networks for temperature-sensitive monoclonal antibodies radiate from these hubs through cold-chain logistics partnerships.
United States
Dermatology-focused specialty clinics in metropolitan markets deploy infusion-capable infrastructure that captures refractory patients requiring biologic supervision. FDA Risk Evaluation and Mitigation Strategies lengthen approval timelines for immunosuppressive therapies while shaping prescriber behavior through mandatory safety monitoring. Boston and San Francisco anchor academic medical centers with histopathology specialist concentration, creating diagnostic bottlenecks that delay treatment initiation.
Germany
Rheumatology networks in Bavaria and North Rhine-Westphalia coordinate corticosteroid-sparing protocols across integrated care systems. EMA pharmacovigilance requirements for systemic vasculitis therapies elevate post-market surveillance obligations, favoring biologics with established safety databases. Heidelberg and Berlin host dermatopathology reference laboratories that serve cross-border diagnostic demand from neighboring European markets.
Switzerland
Basel anchors diagnostics-to-therapeutics integration capabilities that span companion biomarker development through commercial biologic production. Swissmedic oversight aligns with EMA frameworks while maintaining distinct national formulary processes that influence launch sequencing. The Lake Geneva corridor concentrates contract manufacturing organizations serving Roche networks with closed-system bioreactor capacity.
India
Tier-1 cities including Mumbai, Delhi, and Bengaluru report rising cutaneous vasculitis diagnosis rates among private-pay patients seeking premium therapeutic outcomes. CDSCO accelerated approval pathways for biologics with reference product equivalence enable cost-positioned entrants to capture outpatient dermatology channels. Maharashtra and Karnataka host the largest concentration of infusion-capable specialty clinics outside academic hospital settings.
United Kingdom
NHS England step-therapy protocols require documented corticosteroid failure before biologic authorization, compressing novel agent penetration timelines. London and Manchester academic medical centers concentrate vasculitis specialist referrals from regional secondary care networks. MHRA post-Brexit regulatory autonomy creates divergence from EMA pharmacovigilance timelines, influencing sponsor market entry sequencing.
Leukocytoclastic Vasculitis Market Vendor Landscape
Integrated pharmaceutical conglomerates and targeted biotechnology specialists split the market across premium biologics and conventional immunosuppressant tiers. The structure favors players with existing immunology expertise and rheumatology sales infrastructure over pure-play entrants lacking prescriber relationships. Three archetypes dominate: diversified biopharmaceutical majors with diagnostics integration, mid-cap immunology specialists with complement pathway focus, and generic manufacturers capturing corticosteroid volume. Competitive moves center on subcutaneous formulation development to bypass hospital infusion requirements and outcome-based contracting to secure payer preference.
Within the diversified major tier, F. Hoffmann-La Roche Ltd and Bristol Myers Squibb Company exemplify contrasting integration strategies. Roche leverages diagnostics-to-therapeutics capabilities across the care continuum, while Bristol Myers Squibb anchors through deep immunology expertise and established rheumatology networks. Among targeted specialists, ChemoCentryx, Inc. occupies a distinct position in complement pathway modulation, differentiating from broader cytokine inhibition approaches.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Bristol Myers Squibb Company |
| AstraZeneca plc |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Celgene Corporation |
| ChemoCentryx, Inc. |
| Others |
Supply Flow & Price Mechanics
Basel anchors diagnostics-to-therapeutics integration capabilities that concentrate biologics manufacturing capacity and create asymmetric pricing power for monoclonal antibody producers serving United States specialty clinics. Contract manufacturers with closed-system bioreactor investments absorb REACH compliance capex through long-term supply agreements with Roche networks, while small-molecule corticosteroid producers face disproportionate environmental cost burdens that compress generic margins.
Pricing Analysis
Aftermarket service revenue from patient monitoring and long-term remission management contracts drives lifetime value capture for biologics manufacturers shifting toward outcome-based arrangements with United States commercial insurers. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroids reflects FDA Risk Evaluation and Mitigation Strategies compliance costs and step-therapy payer mandates. Pricing pressure stems from generic prednisone at sub-dollar daily dosing that creates insurmountable competition for novel agents in initial flare management. United States urgent care settings exhibit highest price sensitivity due to formulary cost controls, while academic medical centers with histopathology specialist concentration demonstrate lowest sensitivity due to refractory case complexity.
Supply Chain Analysis
Lonza and Catalent hold contract manufacturing capacity for temperature-sensitive monoclonal antibodies, with production clusters concentrated in Switzerland, the United States, and Germany. Cold-chain logistics partnerships radiate from these hubs through validated distribution networks serving hospital-based hematology-oncology suites and specialty clinic infusion centers. Supply chain risk centers on single-source vulnerability for complement pathway inhibitors where C5a receptor antagonism manufacturing requires specialized bioreactor configurations. Distribution runs through pharmaceutical wholesale networks with direct-to-site cold storage for biologics, while oral corticosteroids flow through conventional retail pharmacy channels with generic substitution protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leukocytoclastic vasculitis therapeutics market rewards players with integrated diagnostics capabilities and established rheumatology prescriber relationships, while histopathology specialist scarcity creates diagnostic bottlenecks that delay treatment initiation and compress addressable patient pools.
For Market Incumbents: Insulate biologic positioning through subcutaneous formulation development that bypasses hospital infusion requirements and unlocks homecare channels previously inaccessible to intravenous agents. Deepen captive supply of companion diagnostic biomarkers to capture value across the care continuum from lesion identification through remission monitoring. Defend against biosimilar erosion by securing provincial formulary listings through Health Canada accelerated approval frameworks and outcome-based contracting with United States Medicare Advantage plans. For New Entrants and Emerging Players: Pursue India outpatient dermatology expansion where rising cutaneous vasculitis diagnosis rates in Mumbai, Delhi, and Bengaluru create demand for corticosteroid-sparing options among private-pay patients seeking premium therapeutic outcomes. Target CDSCO accelerated approval pathways for biologics with reference product equivalence to capture cost-positioned market share. Deploy direct-to-specialist education campaigns that bypass step-therapy protocols through documented refractory case narratives mobilized by patient advocacy organizations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core immunology assets with established rheumatology sales infrastructure but limited pipeline differentiation. Long-term viability across the analysis window hinges on complement pathway science advances that create mechanistic separation from TNF-alpha and IL-6 blockade saturation. Monitor FDA Risk Evaluation and Mitigation Strategies approval timelines for systemic vasculitis therapies as inflection indicator for biologics access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Biologic Formulation Development | Bypasses hospital infusion requirements and expands addressable patient pools into community clinic and homecare channels. |
| Companion Diagnostic Biomarker Integration | Roche leverages diagnostics-to-therapeutics capabilities to standardize treatment response documentation for payer prior authorization. |
| Outcome-Based Contracting with Commercial Insurers | Aligns manufacturer revenue with documented remission rates and corticosteroid-sparing outcomes in United States specialty clinics. |
| CDSCO Accelerated Approval Pathway Navigation | Enables cost-positioned biologic entrants to capture India outpatient dermatology channels with reference product equivalence. |
| Patient Advocacy Organization Partnership | Vasculitis Foundation mobilizes refractory case narratives to secure exceptions from United States step-therapy protocols. |
Methodological Framework
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork captured prescriber behavior patterns and payer access workflows across United States specialty clinics and European integrated care systems. Secondary validation drew from SEC 10-K disclosures, WHO guidelines on corticosteroid-sparing protocols, and national health technology assessment reports. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Assumptions held fixed across the modeling period include FDA Risk Evaluation and Mitigation Strategies oversight intensity, EMA pharmacovigilance framework stability, and REACH regulation amendment implementation timelines. Variables included subcutaneous biologic adoption velocity, India private-pay patient growth, and biosimilar entry sequencing through Health Canada pathways. Forecast outputs reflect treatment line progression, administration route migration, patient population severity distribution, and regional regulatory cluster differentiation. CAGRs were derived from segment-level volume and value trajectories calibrated to historical biologics penetration patterns in immunology indications.
Sensitivities concentrate around FDA approval timeline extensions for immunosuppressive therapies, EMA post-market surveillance obligation intensification, and REACH compliance cost escalation for small-molecule manufacturing. Forecasts reflect these assumptions and acknowledge revision risk from step-therapy mandate relaxation, histopathology specialist supply expansion, or complement pathway competitor entry. Quarterly review of FDA biologics approval decisions, EMA safety signal publications, and India CDSCO accelerated approval grants is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Aflatoxicosis Treatment Market