
 Sports Medicine Market | 2026-2036
Sports Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Medicine Market Analysis
Amateur fitness enthusiasts and recreational athletes are unwinding the historical dominance of professional sports teams as the primary demand anchor for sports medicine products. Arthrex leverages its specialization in arthroscopic surgical devices to command premium positioning in orthopedic repair. Stryker anchors its portfolio through integrated trauma and extremities platforms that span implants to powered instruments. Johnson & Johnson competes across the full continuum from consumer braces to surgical robotics through its diversified MedTech footprint.
Sports medicine encompasses the prevention, diagnosis, treatment, and rehabilitation of injuries sustained during athletic activity, employing devices ranging from bioresorbable interference screws with polylactic acid compositions to cold compression systems operating at controlled temperature differentials. Braces and orthotics constitute the largest product category by installed base, though electrotherapy and cryotherapy technologies are capturing disproportionate growth in outpatient and home settings. Rehabilitation applications generate the steadiest recurring revenue streams, while performance enhancement represents an emerging margin pool as wearable-integrated recovery systems gain clinical validation.
FDA 510(k) clearances govern orthopedic device market access in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked sports medicine products in Europe. ISO 13485 quality management standards and ASTM F2077 test methods for ligament fixation devices further shape manufacturing compliance and product liability exposure. Stakeholders must monitor how evolving reimbursement codes for remote therapeutic monitoring reshape channel economics between clinic-based and direct-to-consumer delivery models.
Market Dynamics
Amateur fitness enthusiasts are displacing professional sports teams as the primary demand anchor for sports medicine products, compressing average selling prices while expanding total addressable volume across outpatient and direct-to-consumer channels.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process accelerates orthopedic device commercialization in the United States, reducing time-to-revenue for arthroscopic repair systems and bioresorbable implants.
- Collegiate Athletic Infrastructure:NCAA Division I programs are expanding in-house sports medicine capabilities, driving procurement volume for rehabilitation equipment and injury prevention technologies across campus training facilities.
- Polylactic Acid Bioresorbables:Advanced polymer compositions in interference screws and suture anchors eliminate secondary removal surgeries, improving patient compliance and reducing long-term healthcare costs.
Market Restraints
- EU Medical Device Regulation Clinical Burden:Stricter evidence requirements for CE-marked products extend certification timelines and inflate development costs for European market entry.
- Reimbursement Code Uncertainty:Evolving CPT classifications for remote therapeutic monitoring create pricing volatility and channel margin compression between clinic-based and home delivery models.
- Raw Material Concentration:Medical-grade polymer supply chains cluster in select Asian manufacturing hubs, exposing producers to input cost volatility and logistics disruption.
Strategic Opportunities
- Home-Based Cryotherapy Systems:Controlled temperature differential devices for post-operative recovery represent underpenetrated white space outside institutional settings.
- India PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing create localized supply advantages and tariff arbitrage for export-oriented producers.
- Wearable-Integrated Recovery Monitoring:Convergence of biometric sensors with rehabilitation protocols enables subscription-based recurring revenue models validated by clinical outcomes data.
Industry Challenges
- ISO 13485 Quality System Implementation:Small and mid-cap device manufacturers face capital intensity and timeline compression when scaling compliant manufacturing operations.
- ASTM F2077 Test Method Variability:Ligament fixation device validation protocols lack harmonization across notified bodies, creating certification friction and market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Medicine Market |
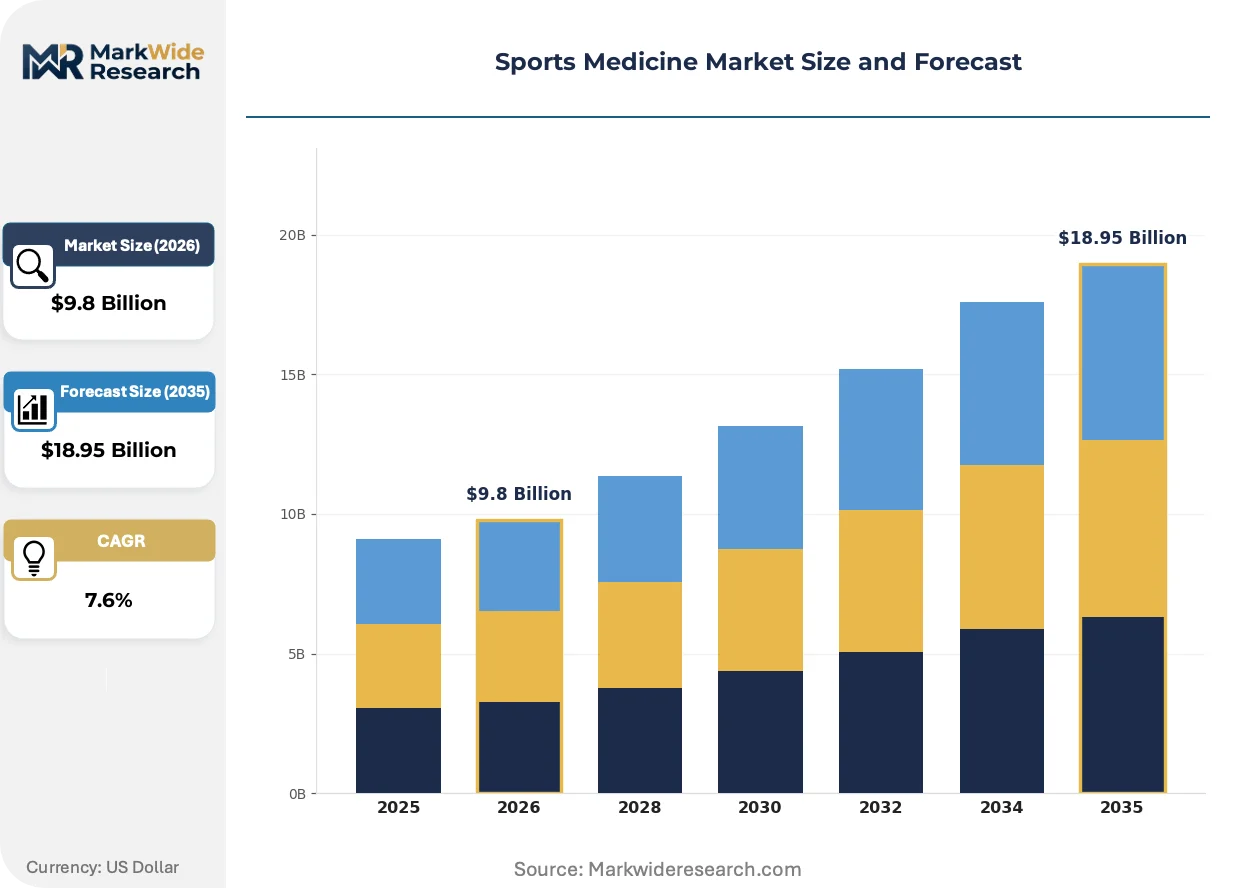
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Orthotics, Compression Gear, Tapes Technology: Physical Therapy, Electrotherapy, Cryotherapy, Ultrasound Application: Injury Prevention, Rehabilitation, Performance Enhancement, Pain Management End User: Athletes, Coaches, Sports Teams, Fitness Enthusiasts |
| Companies Covered | Smith & Nephew, Arthrex, Stryker, Novartis, CONMED Corporation, Johnson & Johnson, Medtronic, Bioventus, Zimmer Biomet Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Medicine Market Emerging Trajectories
Digital biomarkers and connected rehabilitation hardware are compressing the traditional boundary between clinical intervention and self-managed recovery, forcing incumbents to rearchitect service delivery models around continuous patient engagement rather than episodic treatment.
Arthroscopic surgical visualization systems are decomposing the historical trade-off between image fidelity and instrument miniaturization. Outpatient surgery centers in the United States are adopting 4K and 3D-enabled platforms at replacement-cycle pace. This capability convergence is decomposing the premium pricing power of integrated system vendors and enabling modular component sourcing.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for CE-marked sports medicine implants. Manufacturers must now maintain active registries tracking device performance across multi-year horizons. High-volume hip and knee arthroplasty segments face the steepest compliance cost escalation, with mid-tier orthopedic repair producers pursuing notified body partnerships to share surveillance infrastructure.
Direct-to-consumer distribution is capturing share from traditional durable medical equipment channels as fitness-oriented buyers research and purchase braces, compression systems, and electrotherapy devices through specialized e-commerce platforms. Amazon and dedicated sports medicine retailers are building private-label portfolios around ASTM-certified products. This channel rotation is most pronounced in the United States, where high-deductible health plans accelerate out-of-pocket purchasing behavior.
Sports Medicine Market Segmentation
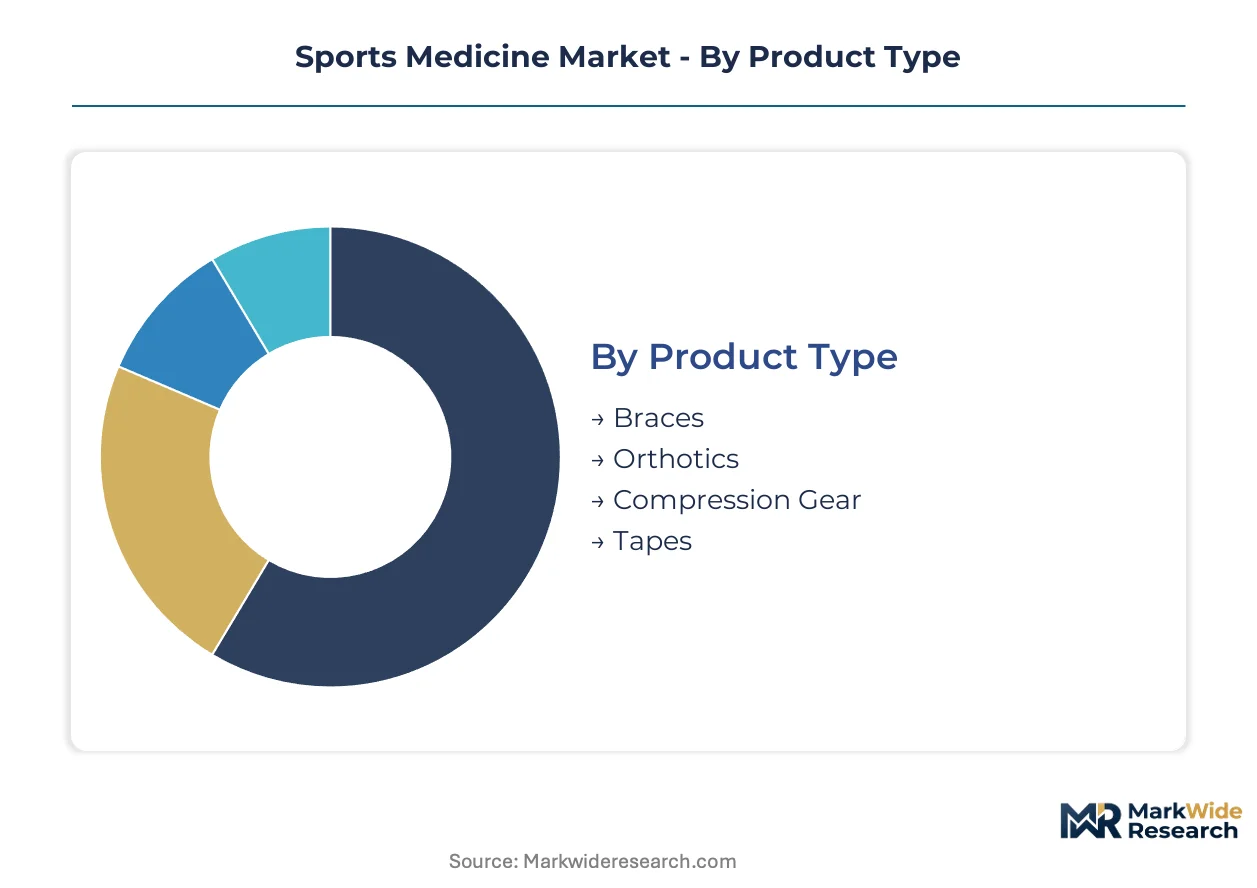
Segmentation in sports medicine reveals divergent channel economics between institutional procurement and direct-to-consumer flows. Each dimension carries distinct margin profiles, regulatory exposure, and growth trajectories that reshape competitive positioning across the value chain.
Product Type:
Braces and compression systems flow through durable medical equipment distributors and Amazon's marketplace in roughly equal volume, while orthotics concentrate in podiatry clinics and specialty retail.
- Braces:Rigid and semi-rigid structural supports fabricated from aluminum, carbon fiber, or molded thermoplastics stabilize joints post-injury. Demand concentrates in collegiate athletic programs and outpatient surgery centers across the United States, driven by ACL reconstruction volume and preventive taping protocols. By volume, braces lead. By growth pace, compression gear is ahead.
- Orthotics:Custom-molded and prefabricated footbeds correct biomechanical alignment using EVA foam, polypropylene shells, or carbon fiber composites. Podiatry practices and running specialty stores in Germany and the United States drive procurement, constrained by reimbursement code variability for custom fabrication.
- Compression Gear:Graduated-pressure garments employing spandex-nylon blends enhance circulation and reduce edema during recovery.
- Tapes:Kinesiology and athletic tapes with cotton-elastic or synthetic substrates provide proprioceptive feedback and joint stabilization.
Compression gear gains share fastest in direct-to-consumer channels as fitness enthusiasts self-prescribe recovery protocols.
Technology:
Cost tier stratification separates capital-intensive clinic-based modalities from portable home-use devices, with electrotherapy and cryotherapy bridging both tiers through rechargeable, app-connected form factors.
- Physical Therapy:Manual techniques combined with therapeutic exercise equipment require skilled clinician delivery and dedicated facility space. Hospital-based outpatient departments and physical therapy chains in the United States absorb the highest equipment procurement volume, constrained by therapist staffing shortages and bundled payment compression.
- Electrotherapy:Transcutaneous electrical nerve stimulation and neuromuscular electrical stimulation devices deliver pulsed current for pain modulation and muscle re-education. Home-use portable units with Bluetooth connectivity are expanding fastest in Japan and South Korea, driven by aging populations and reimbursement for remote therapeutic monitoring.
- Cryotherapy:Cold compression systems and whole-body cryo chambers operate at controlled temperature differentials to reduce inflammation.
- Ultrasound:Therapeutic ultrasound generators apply acoustic energy for tissue heating and phonophoresis drug delivery.
Physical therapy commands the largest installed base. Electrotherapy climbs the fastest as wearable-integrated systems penetrate home recovery.
Application:
Customer type determines channel routing: injury prevention flows through team equipment managers and coaches, while pain management increasingly bypasses clinical gatekeepers via direct-to-consumer platforms.
- Injury Prevention:Pre-participation screening tools, proprioceptive training devices, and protective equipment reduce incident rates before athletic activity. Professional sports franchises and NCAA Division I programs in the United States drive concentrated procurement, validated by biometric screening mandates and liability risk management.
- Rehabilitation:Post-surgical and post-injury recovery protocols span continuous passive motion machines, resistance bands, and aquatic therapy systems. Outpatient surgery centers and hospital-affiliated physical therapy departments generate steadiest recurring revenue, constrained by prior authorization requirements and episode-based reimbursement.
- Performance Enhancement:Wearable-integrated recovery monitoring and normobaric hypoxic training systems optimize athletic output.
- Pain Management:Topical analgesics, TENS devices, and thermal modalities address acute and chronic musculoskeletal discomfort.
Rehabilitation generates the most stable revenue streams. Performance enhancement expands most quickly as validated biometric feedback commands premium pricing.
End User:
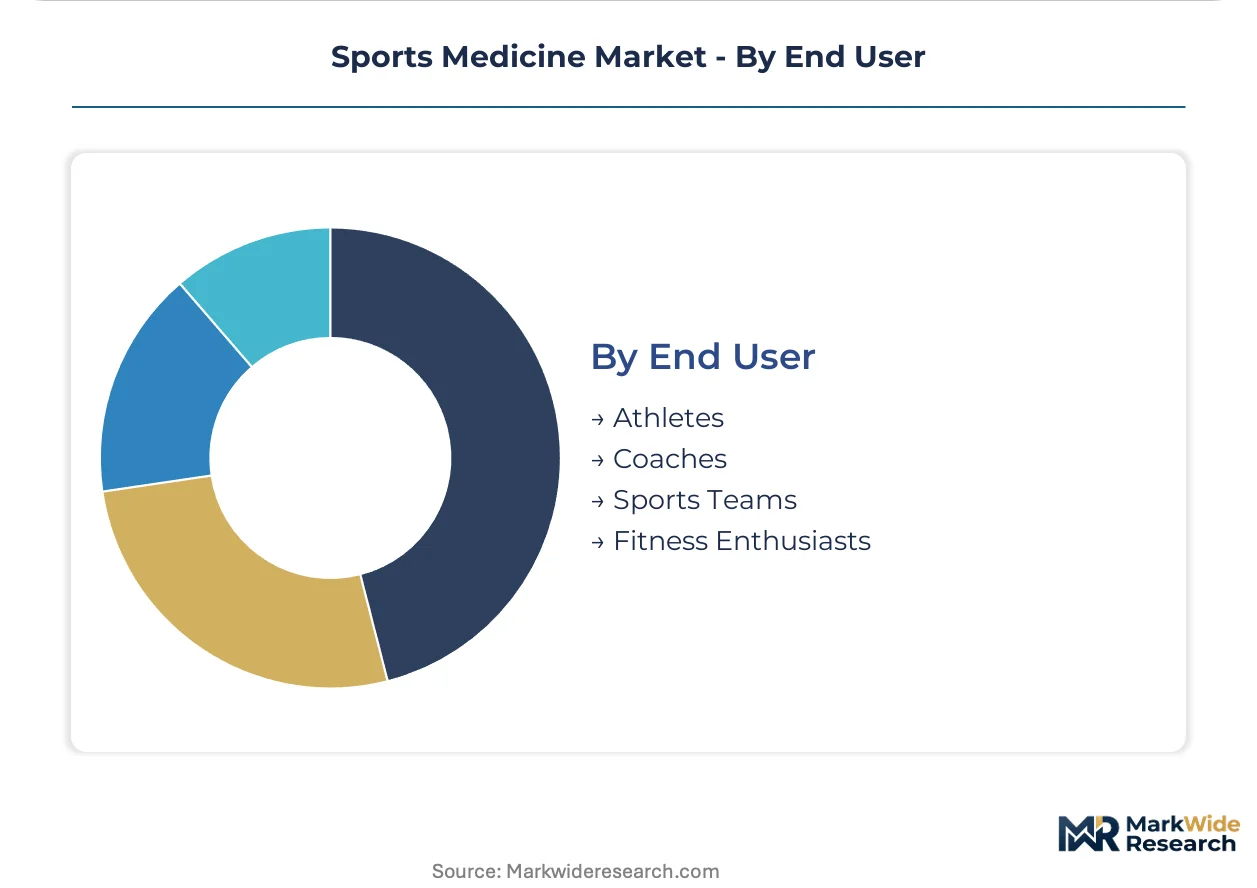
Volume concentration sits with amateur fitness enthusiasts purchasing through Amazon and specialty e-commerce, while margin concentration remains with sports teams procuring integrated systems through GPO contracts.
- Athletes:Individual competitive and recreational participants purchase braces, compression gear, and recovery devices based on self-diagnosis and peer recommendation. Direct-to-consumer channels in the United States capture disproportionate volume, accelerated by high-deductible health plans and out-of-pocket spending behavior.
- Coaches:Athletic trainers and team medical staff specify preventive taping protocols and sideline emergency equipment. High school and collegiate programs across Texas, California, and Florida drive seasonal procurement cycles, constrained by budget variability across district funding models.
- Sports Teams:Professional franchises and organized clubs maintain in-house medical infrastructure.
- Fitness Enthusiasts:Non-competitive recreational athletes pursue wellness-oriented recovery and injury prevention.
Fitness enthusiasts lead by volume. Sports teams sustain the highest per-capita spending as integrated medical infrastructure investments compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic device manufacturers export arthroscopic repair systems to United States collegiate athletic programs and outpatient surgery centers, capturing premium pricing through FDA 510(k) clearance advantages.
United States
NCAA Division I programs and professional sports franchises drive procurement volume for rehabilitation equipment and injury prevention technologies. The FDA's streamlined 510(k) premarket notification pathway accelerates commercialization timelines for domestic and foreign manufacturers. Minneapolis and Boston anchor major orthopedic device clusters where arthroscopic visualization system vendors concentrate engineering talent.
Germany
Podiatry practices and running specialty stores sustain demand for custom-molded orthotics and biomechanical correction devices. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked products, extending certification timelines. Bavaria hosts specialized polymer processing facilities supplying medical-grade PLA bioresorbables to interference screw manufacturers.
Japan
Aging demographics and reimbursement for remote therapeutic monitoring expand home-use electrotherapy device adoption. METI standards govern electrical safety and electromagnetic compatibility for portable neuromuscular stimulation units. Osaka-based rehabilitation equipment distributors are building direct-to-consumer channels for compression and cryotherapy systems.
India
The PLI scheme for medical devices attracts domestic manufacturing investment in orthopedic implants and surgical instruments. CDSCO regulations govern import licensing and quality standards for foreign device suppliers. Gujarat and Karnataka are emerging as production hubs where contract manufacturers serve export markets with cost-optimized brace and orthotic fabrication.
Australia
TGA approval pathways enable relatively rapid market entry for sports medicine devices with predicate device equivalence. High-deductible private health insurance structures accelerate out-of-pocket purchasing of braces and recovery systems through e-commerce channels. Sydney and Melbourne concentrate specialist sports medicine clinics that drive demand for advanced arthroscopic repair platforms.
Sports Medicine Market Vendor Landscape
Player mix skews toward diversified MedTech conglomerates with orthopedic divisions alongside specialized arthroscopy and sports medicine pure-plays. The competitive structure tiers across premium integrated system vendors, mid-scale trauma and extremities specialists, and emerging direct-to-consumer recovery device brands. Dominant competitive moves include portfolio diversification into adjacent rehabilitation technologies and strategic partnerships with outpatient surgery center networks.
Within the diversified MedTech tier, Johnson & Johnson and Stryker occupy positions spanning consumer braces to surgical robotics. Arthrex exemplifies the specialized arthroscopy archetype with concentrated expertise in minimally invasive joint repair. These three anchors represent contrasting strategic postures: full-continuum coverage versus deep vertical specialization in procedural innovation.
| Leading Market Players |
|---|
| Smith & Nephew |
| Arthrex |
| Stryker |
| Novartis |
| CONMED Corporation |
| Johnson & Johnson |
| Medtronic |
| Bioventus |
| Zimmer Biomet Holdings |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at medical-grade polymer facilities in Bavaria and Osaka directly shapes minimum viable pricing for bioresorbable interference screws, concentrating margin leverage with integrated compounders while compressing price floors for device assemblers sourcing through distributors.
Pricing Analysis
Three-generation pricing stratification separates legacy arthroscopic visualization platforms from 4K-enabled systems and emerging 3D-integrated surgical suites. Transactional per-unit pricing dominates capital equipment, while subscription models penetrate wearable-integrated recovery monitoring. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in standard braces intensifies as Amazon private-label entrants absorb distributor margins. Amateur fitness enthusiasts exhibit highest price sensitivity; professional sports teams sustain premium tolerance for integrated system procurement.
Supply Chain Analysis
Germany and Japan anchor medical-grade PLA bioresorbable production for interference screws and suture anchors. China concentrates molded thermoplastic component fabrication for braces and orthotics. The supply chain draws from petroleum-derived polymer feedstocks, precision-machined titanium alloys, and cotton-elastic textile substrates. Single-source vulnerability concentrates in Asian polymer compounding hubs. Distribution runs through GPO contracts for institutional procurement and Amazon marketplace for direct-to-consumer flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as wearable-integrated recovery systems force interoperability standards between device hardware and clinical software ecosystems.
For Market Incumbents: Shield installed base revenue by embedding proprietary data protocols within rehabilitation hardware, preventing disintermediation by third-party analytics platforms. Accelerate backward integration into medical-grade polymer compounding to neutralize raw material cost volatility from Asian supply concentration. Prioritize ISO 13485 certification maintenance as EU MDR surveillance requirements escalate compliance barriers for mid-tier competitors. For New Entrants and Emerging Players: Anchor in home-based cryotherapy systems where clinical validation gaps and reimbursement code uncertainty have slowed incumbent penetration. Target direct-to-consumer channels for compression gear and electrotherapy devices, exploiting Amazon's logistics infrastructure to bypass traditional durable medical equipment distributor networks. Pursue FDA 510(k) clearance through predicate device equivalence to compress time-to-market versus de novo pathways. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized arthroscopy pure-plays with concentrated R&D in minimally invasive joint repair over diversified MedTech conglomerates facing portfolio complexity drag. Long-term viability across the projection horizon rests on recurring revenue attachment rates from software-enabled recovery monitoring. Watch FDA remote therapeutic monitoring reimbursement determinations as inflection signal for channel economics reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined premarket notification reduces commercialization timelines for arthroscopic repair platforms in the United States. |
| Hospital System Partnership | Integrated procurement agreements with outpatient surgery centers secure volume commitments for visualization system vendors. |
| Software Companion Development | Bluetooth-connected rehabilitation apps enable subscription revenue streams validated by biometric outcomes data. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation extends certification timelines but creates defensive moats against undercapitalized competitors. |
| Reimbursement Strategy Formulation | CPT code capture for remote therapeutic monitoring reshapes margin allocation between clinic-based and home delivery channels. |
Methodological Framework
A standing panel of orthopedic surgeons, biomedical engineers, GPO contracts managers, and rehabilitation clinic directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement records, and ASTM standard development archives. Bottom-up demand modeling triangulated against top-down macroeconomic benchmarks to ensure segmentation consistency.
Output consistency was verified against external volume benchmarks including arthroscopic procedure registries and durable medical equipment trade flows. The analytical framework modeled product type, technology tier, application purpose, and end-user channel across the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle dynamics. Forecast inputs incorporated NCAA athletic program expansion trajectories and EU MDR implementation pace.
Decision-makers should treat outputs as directional under assumptions of stable FDA clearance timelines and continued reimbursement for remote monitoring; material deviation in either would warrant model refresh. Specific risks include polymer supply disruption from Asian manufacturing hubs and CPT code reclassification for home-use electrotherapy. Recalibration cycles align with material shifts in regulatory approval pathways and collegiate athletic infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market