
 Multiple Sclerosis Market | 2026-2036
Multiple Sclerosis Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Sclerosis Market Intelligence
Specialized neurology nursing capacity is unwinding access bottlenecks across infusion centers and academic medical centers. Biogen sustains leadership through its entrenched interferon and anti-CD20 franchise. F. Hoffmann-La Roche Ltd dominates the high-efficacy monoclonal antibody segment with ocrelizumab. Novartis AG differentiates via oral sphingosine 1-phosphate receptor modulators that reduce clinical site dependency.
Multiple sclerosis is a chronic autoimmune demyelinating disorder of the central nervous system characterized by inflammatory lesions, axonal loss, and progressive neurological disability; disease-modifying therapies target lymphocyte trafficking, B-cell depletion, or sphingosine receptor signaling to reduce relapse frequency and slow disability accumulation. Monoclonal antibodies command the highest margin pool due to infusion-based administration and premium pricing, while oral sphingosine 1-phosphate receptor modulators represent the fastest-growing delivery mode as patients seek hospital-avoidant options. Immunomodulators retain substantial volume despite maturation, particularly in markets with established interferon infrastructure and conservative payer formularies.
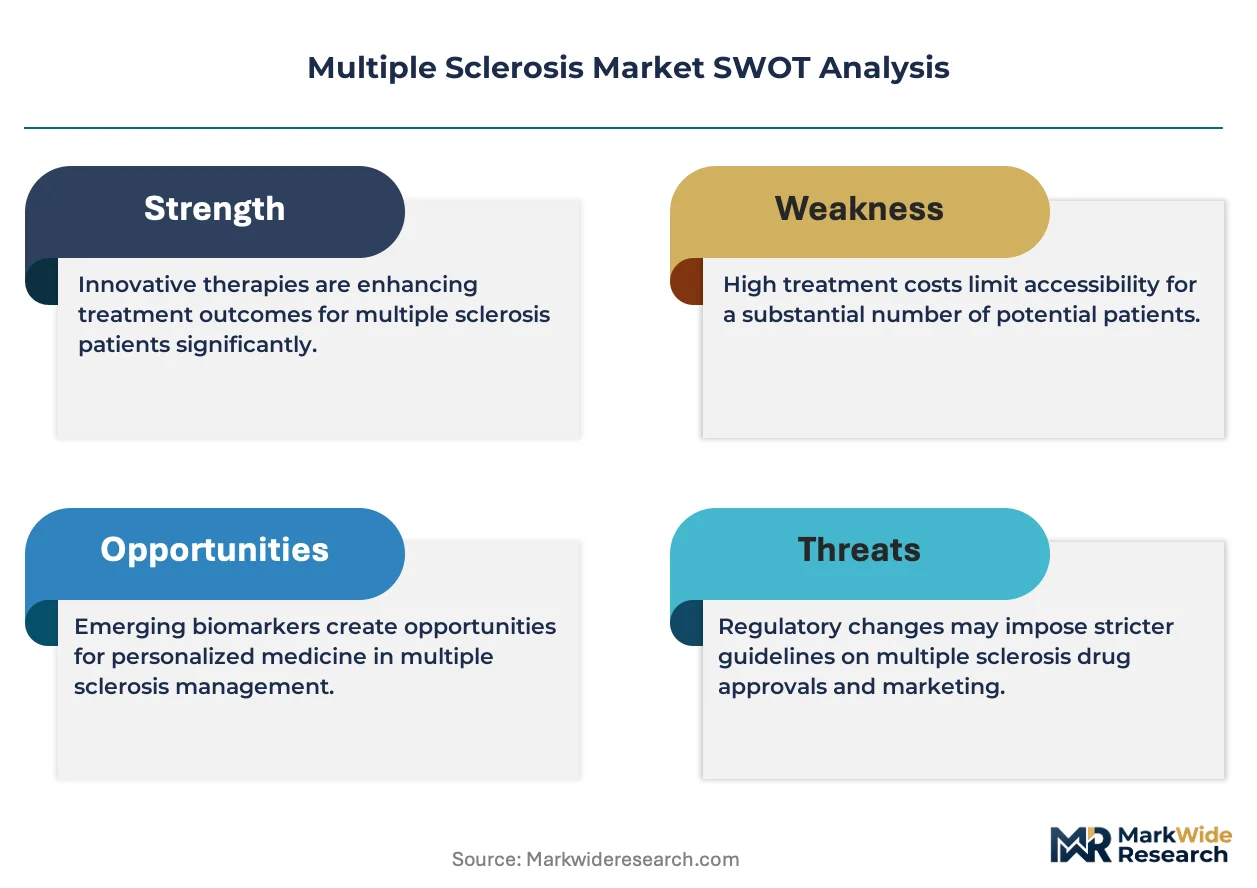
The FDA's Breakthrough Therapy and Fast Track designations compress development timelines for novel mechanisms, while the EMA's Committee for Medicinal Products for Human Use enforces rigorous benefit-risk standards that filter entrants across European markets. Japan's PMDA maintains distinct clinical trial requirements that delay launch parity with Western markets. Stakeholders must monitor evolving biosimilar erosion timelines for reference interferons and natalizumab, as well as real-world evidence requirements that payers increasingly embed in value-based contracts.
Market Dynamics
The FDA's accelerated approval pathways for neurological drugs are compressing development timelines and intensifying competitive pressure among manufacturers racing to bring novel mechanisms to market ahead of biosimilar erosion.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review pathway compresses clinical development timelines for novel disease-modifying therapies, enabling faster patient access to high-efficacy monoclonal antibodies.
- Infusion center expansion:Academic medical centers and specialty clinics are scaling nursing capacity to accommodate anti-CD20 antibody administration, unwinding historical access bottlenecks.
- Oral therapy preference:Patient demand for hospital-avoidant options is accelerating adoption of sphingosine 1-phosphate receptor modulators that reduce clinical site dependency.
Market Restraints
- Premium pricing pressure:Payer formularies in Germany and Japan are tightening reimbursement criteria for infusion-based biologics, compressing margin pools for established franchises.
- Biosimilar pipeline concentration:Reference interferon and natalizumab biosimilars are advancing through late-stage development, threatening volume erosion in markets with established infrastructure.
- EMA benefit-risk rigor:The Committee for Medicinal Products for Human Use enforces stringent safety standards that filter entrants and delay European market access relative to FDA timelines.
Strategic Opportunities
- Real-world evidence integration:Value-based contracts incorporating patient-reported outcomes and disability progression data are opening differentiated positioning for therapies with robust long-term safety profiles.
- Japan parity acceleration:Harmonization efforts between PMDA and Western regulators are narrowing clinical trial requirement gaps, enabling faster launch synchronization for novel mechanisms.
- Home infusion infrastructure:Subcutaneous monoclonal antibody formulations are creating channel expansion opportunities outside traditional hospital-based infusion centers.
Industry Challenges
- Specialized neurology nursing scarcity:Infusion center capacity constraints limit patient throughput for high-efficacy biologics requiring monitored administration.
- Legacy system integration:Electronic health record fragmentation across academic medical centers complicates patient monitoring for long-term disability outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Sclerosis Market |
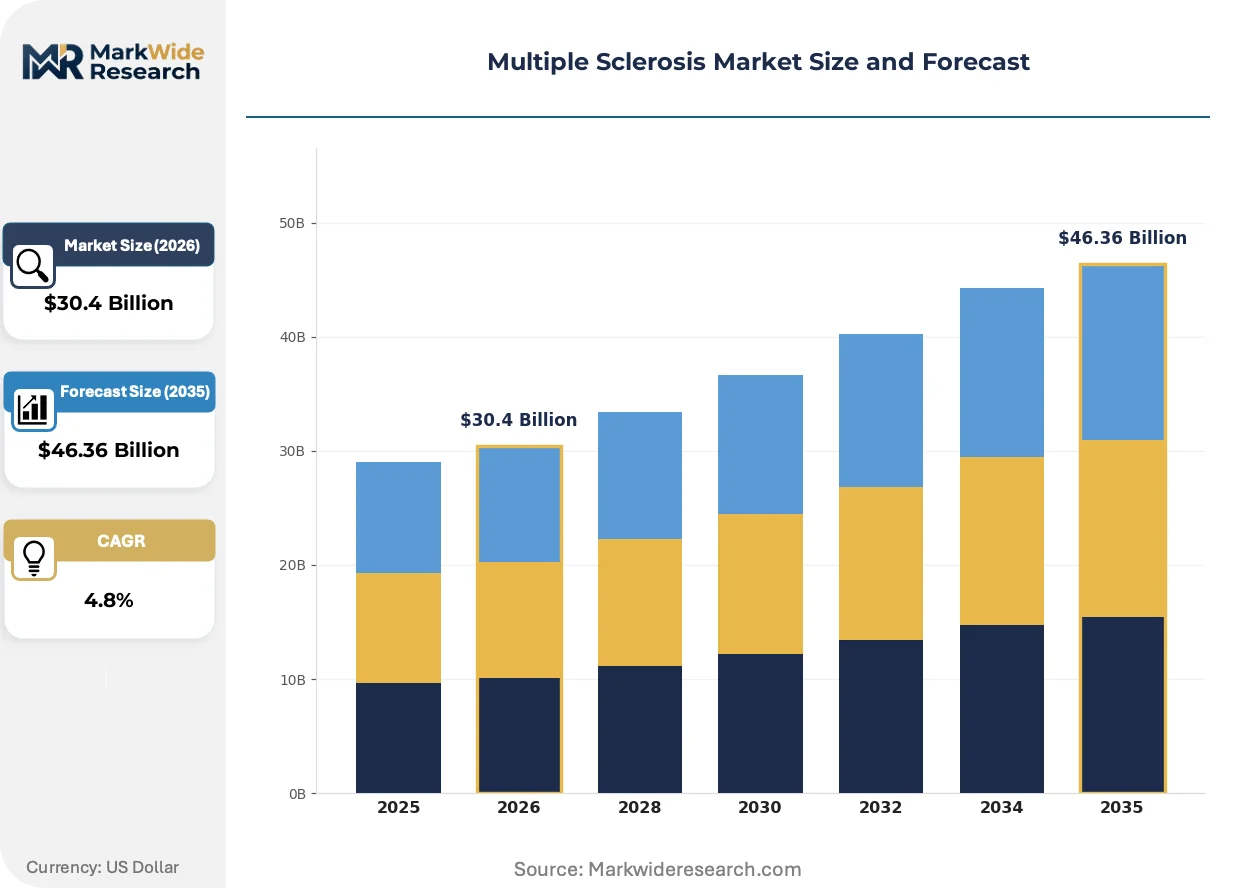
| Market Size in 2026 | $30.4 Billion |
| Market Size in 2035 | $46.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunomodulators, Corticosteroids, Monoclonal Antibodies, Sphingosine 1-Phosphate Receptor Modulators End User: Hospitals, Specialty Clinics, Home Care, Rehabilitation Centers Therapy Area: Neurology, Pain Management, Drug Rehabilitation, Palliative Care Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal |
| Companies Covered | Biogen, F. Hoffmann-La Roche Ltd, Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd., Merck KGaA, Bristol-Myers Squibb Company, Bayer AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Sclerosis Market Strategic Shifts & Innovations
Neurology drug development is pivoting toward patient-centric delivery models that minimize clinical burden while preserving therapeutic efficacy, reshaping competitive positioning across administration routes.
Wearable injection devices for subcutaneous monoclonal antibodies are miniaturizing administration hardware to enable home-based therapy delivery. Multiple sclerosis patients and caregivers are adopting these systems at accelerating rates in the United States and Germany. This technology is miniaturizing the care setting, compressing hospital revenue per patient while expanding addressable patient populations previously excluded by travel constraints.
The EMA's evolving guidance on neurodegenerative disease biomarkers is tightening evidentiary standards for surrogate endpoints in progressive multiple sclerosis trials. Manufacturers must now demonstrate direct disability impact rather than relying solely on magnetic resonance imaging lesion reduction. Oral sphingosine 1-phosphate modulators face heightened scrutiny in European markets, prompting portfolio diversification into complementary mechanisms.
Patient advocacy organizations are consolidating purchasing influence through collective negotiation platforms that aggregate treatment demand across regional networks. Specialty pharmacies and integrated delivery networks are responding by unbundling infusion services from drug pricing. This behavioral shift is most visible in United States commercial payer contracts, where outcomes-based arrangements now tie reimbursement to confirmed disability progression stability.
Multiple Sclerosis Market Segmentation
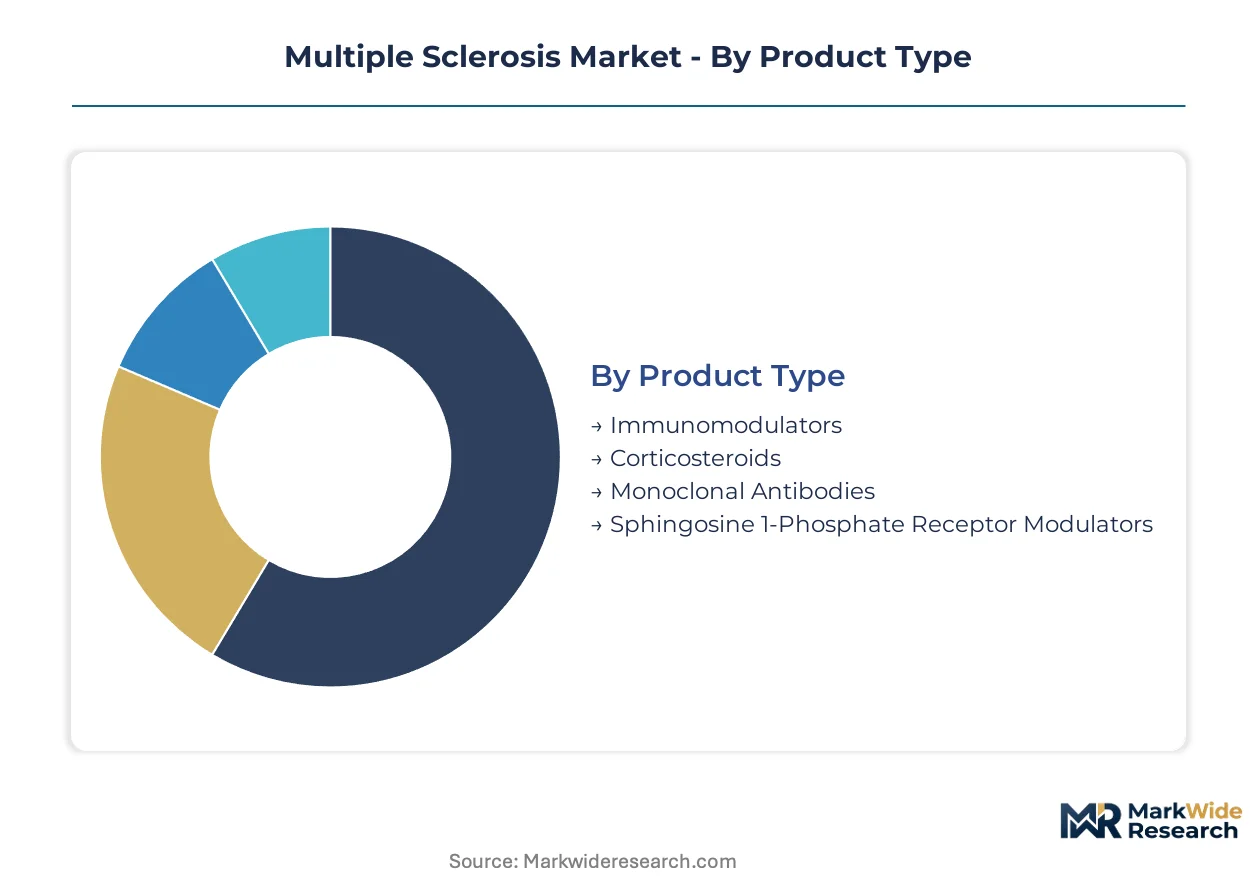
Multiple sclerosis treatment selection hinges on disease course severity, patient lifestyle constraints, and payer reimbursement tiers. Manufacturers compete across mechanism classes and administration routes that carry distinct clinical site dependencies and pricing power profiles.
Product Type:
Substitution pressure intensifies most acutely within immunomodulators as biosimilar interferons erode branded reference product volumes and compress margin pools for legacy franchises.
- Monoclonal Antibodies:Engineered proteins targeting B-cell surface markers or adhesion molecules enable precise lymphocyte depletion. Demand concentrates in academic medical centers across the United States and Germany where infusion nursing capacity has expanded to accommodate anti-CD20 administration schedules. Payer acceptance of premium pricing depends on demonstrated disability progression arrest.
- Sphingosine 1-Phosphate Receptor Modulators:Small-molecule agents sequester lymphocytes in lymph nodes through functional antagonism of S1P receptors on T and B cells. Oral bioavailability drives patient preference in Japan and United States markets where hospital-avoidant therapy reduces indirect cost burdens and travel constraints for rural populations.
- Immunomodulators:Interferon-beta formulations and glatiramer acetate represent first-generation disease-modifying therapy infrastructure.
- Corticosteroids:High-dose methylprednisolone protocols manage acute relapses through broad immunosuppression.
Immunomodulators anchor the volume base while monoclonal antibodies gain share at the steepest rate.
End User:
Cost tier stratification separates hospital-based infusion delivery from lower-acuity settings where reimbursement rates and facility fees diverge substantially.
- Specialty Clinics:Dedicated neurology infusion centers concentrate nursing expertise and monitoring equipment for biologic administration. Germany's outpatient clinic network and United States independent specialty practices are deepening investment in anti-CD20 capacity to capture patient volumes migrating from academic hospitals.
- Hospitals:Academic medical centers retain complex case referrals and progressive MS populations requiring multidisciplinary coordination. United States tertiary centers leverage 340B pricing advantages to maintain monoclonal antibody dispensing despite higher overhead structures.
- Home Care:Subcutaneous self-injection and emerging wearable infusion devices enable administration outside clinical facilities.
- Rehabilitation Centers:Physical therapy integration supports disability management for advanced disease stages.
Hospitals retain the highest revenue per patient while home care expands most quickly as device technology matures.
Therapy Area:
Application focus determines prescriber specialty and formulary placement, with neurology dominance creating gatekeeper dynamics that other indications struggle to penetrate.
- Neurology:Disease-modifying therapy prescribing remains concentrated among board-certified neurologists with MS fellowship training. United States and German neurology practices are consolidating into larger group structures that enhance negotiating leverage with specialty pharmacies and integrated delivery networks.
- Pain Management:Neuropathic pain protocols address secondary symptom burden through gabapentinoids and tricyclic agents.
- Drug Rehabilitation:Substance use comorbidity management supports adherence optimization for oral therapy regimens.
- Palliative Care:End-stage symptom control addresses spasticity, dysphagia, and respiratory compromise in progressive disease.
Neurology commands the prescribing volume base while pain management climbs fastest as patient-reported outcome integration expands.
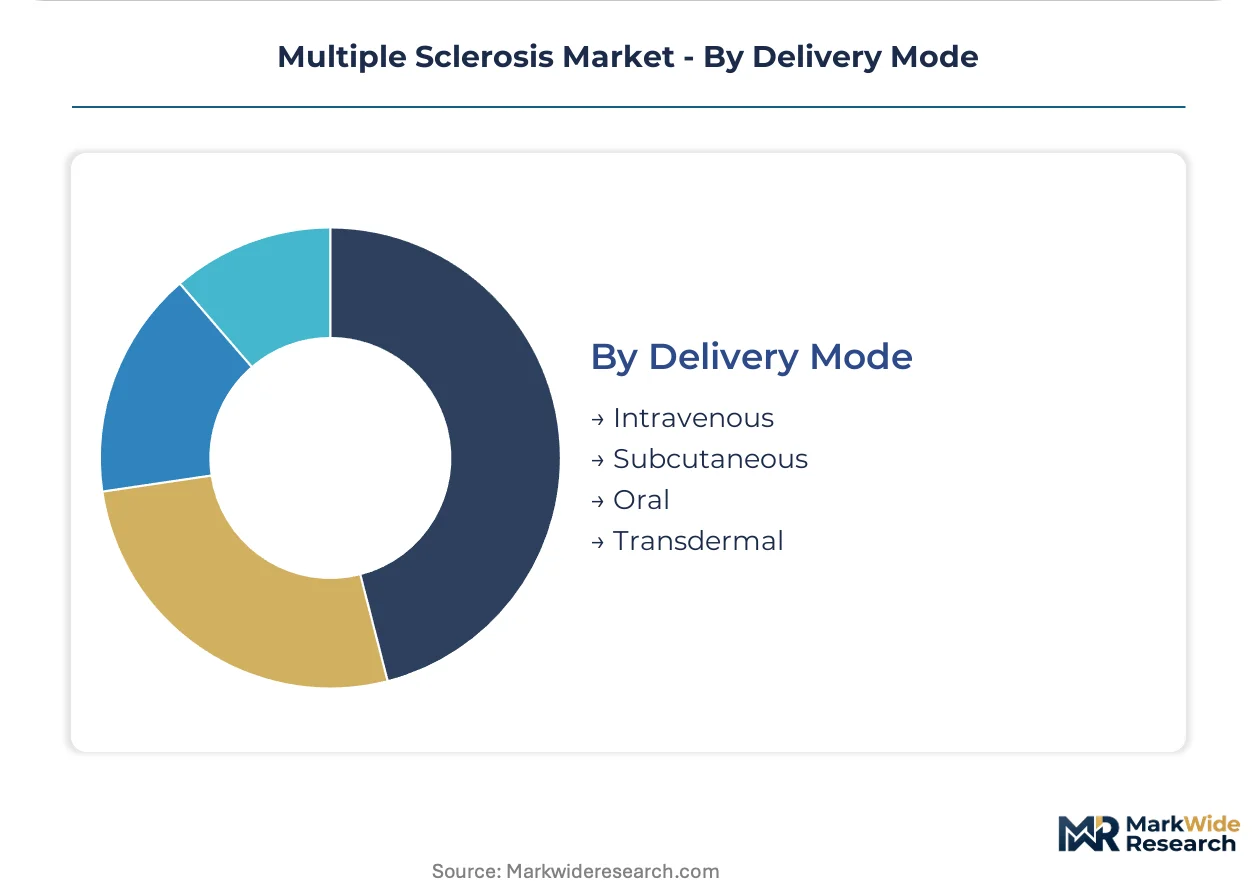
Delivery Mode:
Supply concentration in infusion pharmacy networks shapes competitive access for parenteral formats against the pharmacy-distributed oral channel.
- Intravenous:Infusion-based monoclonal antibodies require monitored administration with cardiac telemetry and hypersensitivity protocols. United States specialty pharmacy networks and German ambulatory care centers are competing to consolidate this volume through exclusive distribution arrangements with manufacturers.
- Oral:Sphingosine 1-phosphate modulators and fumarate esters eliminate clinical site dependency entirely. Patient preference in Japan and United States markets is accelerating pharmacy benefit manager formulary placement and mail-order dispensing penetration.
- Subcutaneous:Self-injection formulations reduce but do not eliminate clinical oversight requirements.
- Transdermal:Patch-based delivery remains investigational for MS immunomodulation.
Intravenous administration anchors the revenue base while oral delivery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor United States market dynamics, while EMA benefit-risk standards and PMDA clinical trial requirements create divergent access timelines across major therapy markets.
United States
Academic medical centers in Boston and Baltimore are expanding infusion nursing capacity for anti-CD20 antibody administration. The FDA's Breakthrough Therapy designation compresses development timelines for novel disease-modifying therapies. Specialty pharmacy networks in the Northeast are consolidating exclusive distribution arrangements with manufacturers to capture biologic dispensing volume.
Germany
Outpatient neurology clinics in Bavaria and North Rhine-Westphalia are deepening investment in monitored infusion infrastructure. The Federal Joint Committee (G-BA) is tightening reimbursement criteria for premium-priced biologics through benefit assessment protocols. Heidelberg and Munich medical centers are competing to attract progressive MS patient referrals through multidisciplinary care coordination.
Japan
Mail-order pharmacy penetration is accelerating oral sphingosine 1-phosphate modulator adoption among rural populations in Kanto and Kansai regions. PMDA harmonization efforts with Western regulators are narrowing clinical trial requirement gaps for novel mechanisms. Tokyo and Osaka neurology practices are consolidating into larger group structures to enhance negotiating leverage with regional insurers.
United Kingdom
NHS England's specialized commissioning framework is concentrating high-cost biologic administration in designated neurology centers across London and Manchester. The National Institute for Health and Care Excellence (NICE) is embedding real-world evidence requirements in value-based contracts for disease-modifying therapies. Scottish and Welsh health boards are negotiating outcomes-based arrangements that tie reimbursement to confirmed disability progression stability.
Canada
Provincial formularies in Ontario and Quebec are diverging on reimbursement criteria for infusion-based versus oral therapies. Health Canada's priority review pathways are accelerating access timelines for drugs addressing unmet needs in progressive multiple sclerosis. Toronto and Vancouver academic hospitals are leveraging 340B-equivalent pricing mechanisms to maintain monoclonal antibody dispensing despite facility fee compression.
Multiple Sclerosis Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the multiple sclerosis therapeutics market. The upper tier comprises diversified pharmaceutical conglomerates with entrenched interferon, monoclonal antibody, and oral small-molecule franchises. The specialist tier includes mid-scale biotechnology firms and regional generics manufacturers concentrated on biosimilar development. Three archetypes dominate competitive positioning: integrated innovators with full mechanism-class coverage, infusion-focused biologic specialists, and oral therapy pure-plays seeking hospital-avoidant market segments. M&A activity concentrates on subcutaneous formulation capabilities and real-world evidence platforms, while portfolio diversification into progressive MS neuroprotection represents the second dominant vector.
Among Swiss-based integrated leaders, F. Hoffmann-La Roche Ltd and Novartis AG exemplify divergent strategic positioning within the same geography. Roche anchors the high-efficacy monoclonal antibody segment through ocrelizumab's entrenched anti-CD20 franchise, while Novartis occupies the oral therapy vector with sphingosine 1-phosphate receptor modulators that reduce clinical site dependency. Biogen represents the archetype of legacy franchise defense, sustaining market presence through interferon infrastructure and anti-CD20 diversification despite biosimilar pressure on reference products.
| Leading Market Players |
|---|
| Biogen |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Merck KGaA |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
FDA Breakthrough Therapy designation gates both supply qualification and price differentiation simultaneously, compressing development timelines for manufacturers while enabling premium positioning for therapies that demonstrate disability progression arrest. Payer formularies in the United States and Germany then stratify reimbursement tiers based on clinical site dependency and real-world evidence profiles.
Pricing Analysis
Long-term offtake contracts between manufacturers and specialty pharmacy networks anchor pricing for infusion-based monoclonal antibodies, while oral sphingosine 1-phosphate modulators trade through pharmacy benefit manager tiered formularies. Price differentiation hinges on demonstrated efficacy in progressive multiple sclerosis and cardiac monitoring requirements during administration. Pricing pressure stems from biosimilar interferon erosion in markets with established infrastructure. Hospital systems exhibit highest price sensitivity due to 340B pricing exposure, while academic medical centers retain leverage through exclusive distribution negotiations.
Supply Chain Analysis
Biologics manufacturing capacity chokepoints in Switzerland, Ireland, and Massachusetts underwrite supply security for anti-CD20 antibody franchises. Active pharmaceutical ingredient production draws from specialized fermentation and cell culture facilities with multi-year qualification timelines. Single-source vulnerability concentrates in fill-finish operations for parenteral formulations. Distribution runs through cold-chain specialty pharmacy networks with temperature-controlled logistics mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in patient-centric delivery models as rural populations and working-age patients demand hospital-avoidant therapy options, creating white-space niches between established infusion centers and traditional oral pharmacy channels.
For Market Incumbents: Fortify anti-CD20 franchise positioning through backward integration into subcutaneous formulation manufacturing, capturing patients migrating from hospital-based infusion. Deepen real-world evidence platforms to defend margin pools against payer outcomes-based contracting. Expand nursing capacity partnerships in Germany's outpatient clinic network to preempt biosimilar volume erosion.
For New Entrants and Emerging Players: Anchor in Japan's mail-order pharmacy channel where PMDA harmonization is narrowing trial requirement gaps with Western regulators. Target progressive multiple sclerosis neuroprotection as the most penetrable mechanism class with unmet need. Pursue licensing arrangements with academic medical centers for biomarker-validated surrogate endpoints.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed infusion center operators consolidating in United States metropolitan markets. Five-to-ten year viability hinges on home infusion infrastructure deployment and wearable device adoption curves. Monitor FDA accelerated approval withdrawal rates as inflection indicator for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Wearable injection devices enable home administration outside hospital infusion centers. |
| Real-World Evidence Platform Investment | Patient-reported outcomes data satisfies payer value-based contract requirements. |
| Specialty Pharmacy Network Partnership | Exclusive distribution arrangements secure biologic dispensing volume against competitors. |
| Progressive MS Pipeline Diversification | Neuroprotection mechanisms address disability progression with limited current options. |
| Japan Regulatory Harmonization | PMDA alignment with FDA timelines accelerates launch parity for novel mechanisms. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation cross-checked segmentation outputs.
Sensitivity analysis tested forecast robustness across pricing scenarios and biosimilar erosion timelines. The analytical framework segmented by treatment line, administration route, regional regulatory cluster, and patient disability progression stage. CAGRs derived from epidemiological prevalence projections and therapy penetration curves. Modeled inputs included infusion center capacity expansion rates and mail-order pharmacy adoption patterns.
Underlying assumptions cover reimbursement stability and regulatory pathway continuity, with deviation risk concentrated in payer formulary tightening and accelerated approval withdrawal events. Practitioners should keep alternative scenarios live as real-world evidence requirements and biosimilar launch timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market