
 Global Wolff Parkinson White Syndrome Market | 2026-2036
Global Wolff Parkinson White Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wolff Parkinson White Syndrome Market Foresight
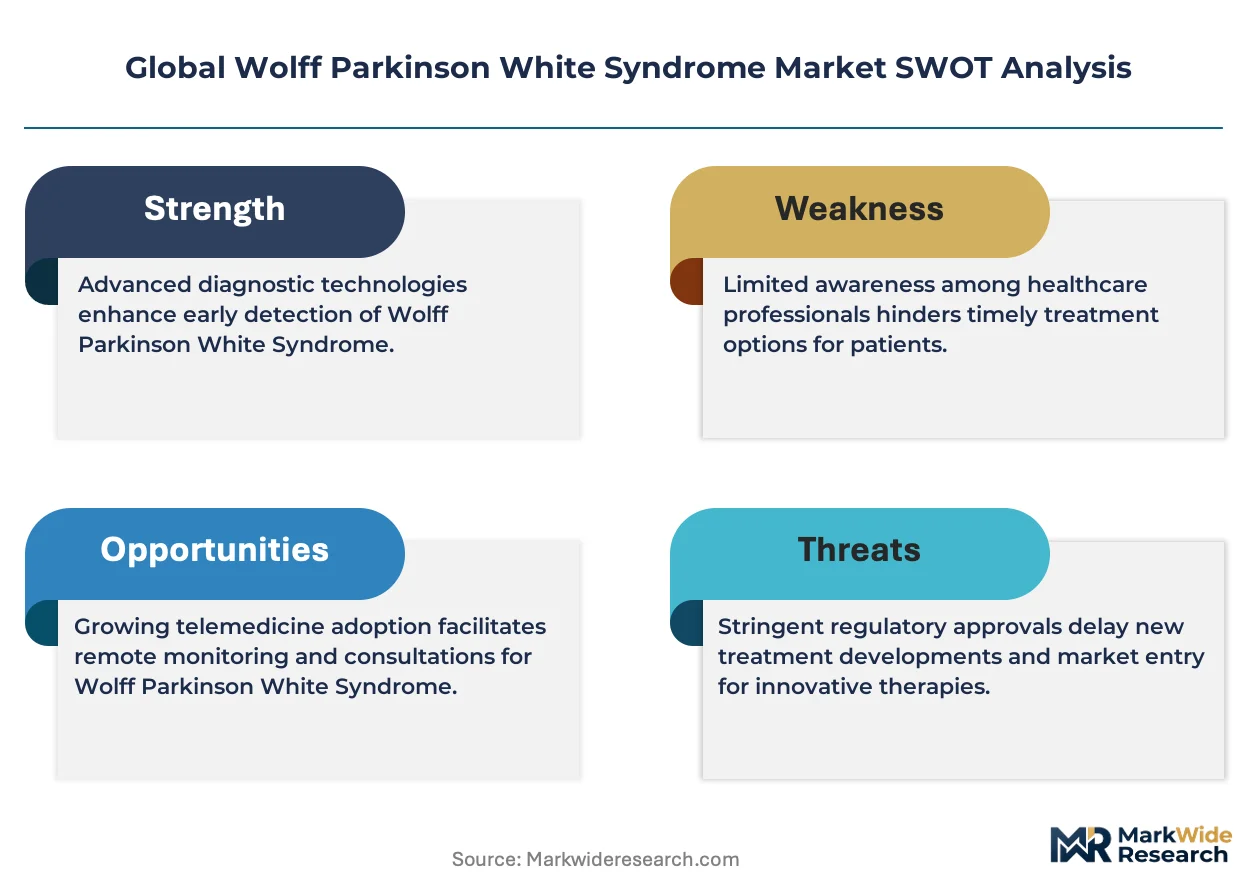
Radiofrequency ablation catheters are restructuring treatment economics by displacing long-term pharmacological management in symptomatic patients. Johnson & Johnson leverages its broad electrophysiology portfolio across catheter and monitoring platforms. Medtronic plc anchors North American supply through integrated mapping and ablation system manufacturing. Abbott Laboratories differentiates via cryoablation technology leadership in pediatric and complex accessory pathway cases.
Wolff Parkinson White syndrome is a congenital cardiac pre-excitation disorder characterized by an accessory atrioventricular pathway that enables aberrant electrical conduction, with diagnostic confirmation requiring electrophysiology study demonstrating a delta wave and short PR interval on surface ECG. Catheters and ablation systems command the largest product revenue pools, while monitoring equipment represents a mature replacement-driven segment with lower growth velocity. Radiofrequency ablation dominates treatment mode volumes, though cryoablation is gaining structural share in anatomically challenging pathways near the atrioventricular node due to its lower thrombogenic risk profile.
FDA premarket notification and EMA medical device regulation frameworks govern electrophysiology device commercialization, with FDA breakthrough device designations accelerating access for novel mapping technologies. Japan's PMDA and China's NMPA impose additional clinical trial requirements that shape regional launch sequencing for multinational manufacturers. Stakeholders must monitor evolving reimbursement thresholds for same-day ablation discharge across Germany, Japan, and the United States as these determine site-of-care migration from inpatient cardiac centers to ambulatory surgical settings.
Market Dynamics
Radiofrequency catheter ablation is displacing chronic pharmacological management as first-line intervention for symptomatic Wolff Parkinson White patients, compressing treatment timelines from years to single-session resolution while redirecting revenue from pharmaceutical dispensing toward device-procedure bundles.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for novel electrophysiology mapping systems compress commercialization timelines by 12-18 months versus standard 510(k) submissions.
- Ambulatory surgical center expansion:United States outpatient cardiac labs are building dedicated electrophysiology suites to capture same-day ablation reimbursement differentials over inpatient settings.
- Cryoablation technology maturation:Lower thrombogenic risk profiles in anatomically challenging accessory pathways near the atrioventricular node are expanding addressable patient populations previously excluded from thermal ablation.
Market Restraints
- Supply concentration in mapping system manufacturing:Integrated catheter and navigation platform production clusters in Massachusetts and Minnesota create single-source vulnerability for North American catheter supply.
- EMA Medical Device Regulation compliance costs:Enhanced clinical evidence requirements for Class III electrophysiology devices impose documentation burdens that delay European market entry for smaller manufacturers.
- Fluoroscopy-dependent workflow persistence:Radiation exposure concerns limit operator pool expansion and constrain procedure throughput in training-constrained cardiac centers.
Strategic Opportunities
- Japan PMDA streamlined approval harmonization:Convergence with FDA predicate device recognition pathways reduces redundant clinical trials for electrophysiology catheter systems.
- Pediatric electrophysiology service line development:Cryoablation preference in congenital accessory pathway cases creates dedicated pediatric cardiac center partnerships for technology suppliers.
- Remote monitoring integration:Post-ablation arrhythmia surveillance via wearable ECG patches enables recurrence detection and retreatment scheduling with reduced clinic burden.
Industry Challenges
- Electrophysiology fellow training pipeline constraints:Three-year subspecialty certification requirements limit annual graduating operator supply relative to expanding ablation center demand.
- Catheter sterilization and reprocessing complexity:Single-use disposable economics clash with sustainability mandates from hospital procurement committees, forcing hybrid reprocessing protocol development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wolff Parkinson White Syndrome Market |
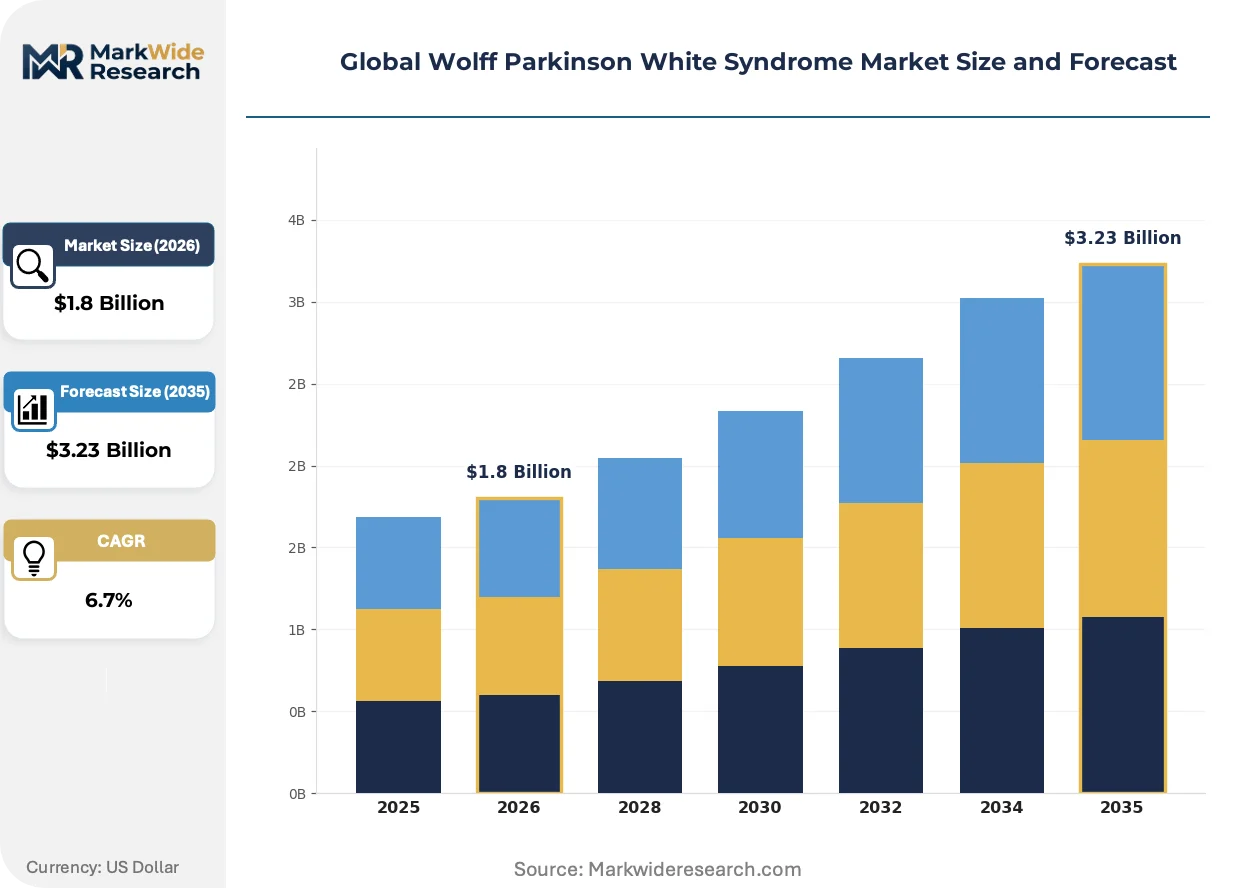
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Electrophysiology Devices, Ablation Systems, Monitoring Equipment Therapy Area: Arrhythmia Management, Heart Rate Regulation, Electrical Pathway Correction, Sudden Cardiac Event Prevention End User: Cardiac Centers, Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers Treatment Mode: Radiofrequency Ablation, Cryoablation, Pharmacological Therapy, Device-based Intervention |
| Companies Covered | Johnson & Johnson, St. Jude Medical, Medtronic plc, MicroPort Scientific Corporation, Terumo Corporation, Abbott Laboratories, BIOTRONIK SE & Co. KG, AtriCure, Inc., Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wolff Parkinson White Syndrome Market Shifts & Advancements
Three-dimensional electroanatomical mapping is restructuring procedural workflow efficiency while regulatory harmonization efforts compress multi-jurisdiction launch timelines. Device manufacturers are converging hardware and software platforms into integrated ecosystems that lock in catheter purchasing.
High-density mapping catheters with multipolar electrode configurations are consolidating diagnostic and therapeutic functions into single-procedure workflows. Academic medical centers in Germany and the United States are adopting these systems to reduce fluoroscopy time and eliminate separate diagnostic electrophysiology studies. This consolidation is compressing capital equipment procurement cycles as centers prioritize all-in-one platform investments over discrete component purchases.
China's NMPA has implemented priority review channels for electrophysiology devices addressing unmet arrhythmia treatment needs, compressing registration timelines from 18 months to 9 months for qualifying submissions. Domestic manufacturers in Shanghai and Beijing are leveraging these pathways to challenge multinational positions in mid-tier catheter segments. European and Japanese manufacturers are responding by establishing local clinical trial infrastructure to access the accelerated pathway.
Hospital purchasing committees are unbundling device-procedure bundles and negotiating catheter pricing separately from ablation service contracts. United States integrated delivery networks are centralizing electrophysiology procurement through regional cardiovascular service line administrators, displacing individual physician preference item selection. This concentration is most visible in Texas and Florida health systems where cardiac service line consolidation has reduced active catheter suppliers from five to two per network.
Global Wolff Parkinson White Syndrome Market Segmentation
Wolff Parkinson White syndrome treatment pathways fragment across multiple technical and clinical dimensions. Each segmentation layer reveals distinct procurement patterns, reimbursement thresholds, and technology substitution dynamics that shape manufacturer positioning.
Product Type:
Replacement cycles vary sharply across this category, with capital equipment demanding 7-10 year refresh intervals while disposable catheters operate on quarterly replenishment rhythms.
- Catheters:Multipolar electrode configurations now consolidate diagnostic and therapeutic functions into single-procedure workflows. Demand clusters in academic medical centers across Germany and the United States that prioritize fluoroscopy reduction.
- Ablation Systems:Integrated radiofrequency and cryoablation platforms anchor hospital capital budgets, with procurement committees favoring all-in-one systems over discrete component purchases. United States integrated delivery networks in Texas and Florida have reduced active suppliers from five to two per network.
- Electrophysiology Devices:Three-dimensional electroanatomical mapping systems command premium positioning through software-hardware ecosystem lock-in.
- Monitoring Equipment:Post-ablation arrhythmia surveillance via wearable ECG patches represents a mature replacement-driven segment with lower growth velocity.
Volume placements concentrate in catheters; the faster expansion belongs to ablation systems.
Therapy Area:
Cost tier differentiation separates emergency intervention from elective pathway correction, with sudden cardiac event prevention commanding premium reimbursement codes.
- Arrhythmia Management:Radiofrequency catheter ablation displaces chronic pharmacological management as first-line intervention, compressing treatment timelines from years to single-session resolution. United States ambulatory surgical centers are building dedicated electrophysiology suites to capture same-day discharge reimbursement.
- Electrical Pathway Correction:Cryoablation technology maturation expands addressable populations in anatomically challenging accessory pathways near the atrioventricular node. Lower thrombogenic risk profiles previously excluded these patients from thermal ablation.
- Heart Rate Regulation:Pharmacological bridging therapy maintains residual demand among patients awaiting ablation scheduling.
- Sudden Cardiac Event Prevention:Risk stratification protocols drive diagnostic electrophysiology study volumes in symptomatic patient cohorts.
Revenue concentration sits with arrhythmia management; electrical pathway correction climbs the fastest.
End User:
Customer type fragmentation creates distinct sales motion requirements, from capital-intensive cardiac center platform deals to high-velocity ambulatory surgical center disposable contracts.
- Cardiac Centers:Tertiary institutions anchor North American supply through integrated mapping and ablation system manufacturing clusters in Massachusetts and Minnesota. These centers train the limited annual graduating supply of electrophysiology fellows.
- Ambulatory Surgical Centers:Outpatient cardiac labs capture same-day ablation reimbursement differentials over inpatient settings. United States site-of-care migration accelerates as Medicare reimbursement thresholds evolve.
- Specialty Clinics:Pediatric electrophysiology service lines prefer cryoablation for congenital accessory pathway cases.
- Diagnostic Laboratories:Pre-procedure electrophysiology study confirmation supports delta wave and short PR interval diagnostic workflows.
Procedure throughput concentrates in cardiac centers; ambulatory surgical centers gain share fastest.
Treatment Mode:
Maturity gradients separate established thermal ablation from emerging cryothermal alternatives, with pharmacological therapy retreating to bridge and contraindicated populations.
- Radiofrequency Ablation:Thermal energy delivery dominates procedural volumes through proven efficacy in standard accessory pathway locations. Catheter-based ablation adoption expands across cardiac centers in Germany with established fluoroscopy-dependent workflows.
- Cryoablation:Cryothermal energy enables safer ablation near critical structures, with pediatric and complex pathway applications driving technology differentiation. Japan's PMDA and China's NMPA impose additional clinical trial requirements that shape regional launch sequencing.
- Pharmacological Therapy:Antiarrhythmic drug maintenance retreats to symptomatic patients awaiting procedural scheduling or refusing intervention.
- Device-based Intervention:Implantable solutions address residual conduction abnormalities in select refractory cases.
Procedure volume concentrates in radiofrequency ablation; cryoablation expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ambulatory surgical centers concentrate demand through same-day ablation reimbursement differentials, while Germany's cardiac centers anchor European catheter adoption. Regulatory pathways in Japan and China reshape multinational launch sequencing, with domestic manufacturers leveraging accelerated approval channels.
United States
Medicare reimbursement thresholds for outpatient electrophysiology procedures drive site-of-care migration from inpatient cardiac centers to ambulatory surgical settings. FDA breakthrough device designations compress commercialization timelines for novel mapping systems. Massachusetts and Minnesota host integrated catheter and navigation platform manufacturing clusters that supply North American catheter demand.
Germany
Catheter-based ablation adoption expands across tertiary cardiac centers with established fluoroscopy-dependent workflows. EMA Medical Device Regulation compliance costs for Class III electrophysiology devices impose documentation burdens on market entrants. Bavaria and North Rhine-Westphalia concentrate academic medical center procurement of high-density mapping systems that consolidate diagnostic and therapeutic functions.
Japan
PMDA streamlined approval harmonization with FDA predicate device recognition pathways reduces redundant clinical trials for electrophysiology catheter systems. METI industrial policy supports domestic medical device manufacturing competitiveness. Tokyo and Osaka metropolitan areas anchor pediatric electrophysiology service lines that prefer cryoablation for congenital accessory pathway cases.
China
NMPA priority review channels for electrophysiology devices compress registration timelines from 18 months to 9 months for qualifying submissions. Domestic manufacturers in Shanghai and Beijing challenge multinational positions in mid-tier catheter segments. Yangtze River Delta and Pearl River Delta clusters concentrate local clinical trial infrastructure development for accelerated pathway access.
India
CDSCO medical device registration requirements shape regional launch sequencing for multinational electrophysiology manufacturers. Government hospital procurement committees prioritize cost-effective catheter sourcing for public cardiac centers. Maharashtra and Karnataka host expanding private hospital electrophysiology lab investments that drive disposable catheter volume demand.
Global Wolff Parkinson White Syndrome Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers converge hardware and software platforms into integrated ecosystems. The vendor base concentrates around multinational conglomerates with broad electrophysiology portfolios and mid-tier specialists with regional manufacturing advantages. Three archetypes define competitive positioning: integrated platform providers, cryoablation technology specialists, and regional catheter fabricators. M&A activity and strategic partnerships represent the dominant competitive moves, with technology licensing agreements accelerating geographic expansion.
Among integrated platform providers, Johnson & Johnson and Medtronic plc exemplify the capital-intensive archetype that anchors hospital procurement through ecosystem lock-in. Abbott Laboratories occupies a differentiated position within the cryoablation specialization tier. Boston Scientific Corporation represents the diversified portfolio approach across catheter and monitoring segments. These three companies illustrate how competitive positioning stratifies between comprehensive platform coverage and targeted technology leadership.
| Leading Market Players |
|---|
| Johnson & Johnson |
| St. Jude Medical |
| Medtronic plc |
| MicroPort Scientific Corporation |
| Terumo Corporation |
| Abbott Laboratories |
| BIOTRONIK SE & Co. KG |
| AtriCure, Inc. |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Electrophysiology fellow concentration in Massachusetts and Minnesota creates labor-cost differentials that widen pricing spreads between premium integrated platforms and mid-tier catheter alternatives. Hospital procurement committees exploit this geographic supply clustering to negotiate steeper discounts on capital equipment while absorbing premium markups on disposable catheter replenishment cycles.
Pricing Analysis
Volume placements concentrate in disposable catheters with compressed margins, while ablation systems and mapping platforms capture value through premium positioning against replacement timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated mapping ecosystems from CE-marked mid-tier alternatives and unbranded catheter generics. Cost compression in standard-tier catheters is intensifying because integrated delivery networks in Texas and Florida have consolidated suppliers from five to two per network. Ambulatory surgical centers exhibit highest price sensitivity due to thin reimbursement differentials, whereas academic cardiac centers prioritize fluoroscopy-reduction capabilities over unit cost.
Supply Chain Analysis
Reverse-logistics flows for catheter reprocessing and remanufacturing are emerging as procurement committees impose sustainability mandates that clash with single-use disposable economics. Manufacturing concentrates in the United States, Germany, and China, with Massachusetts and Minnesota anchoring North American integrated platform production. Raw material dependencies span platinum-iridium electrode alloys, specialized polymer catheter shafts, and cryogenic coolant gases. Single-source vulnerability in high-density mapping catheter electrode fabrication creates supply risk if Massachusetts production clusters face disruption. Distribution runs through hospital purchasing committees and group purchasing organizations that centralize electrophysiology procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EMA Medical Device Regulation compliance costs and integrated platform ecosystem lock-in are forcing smaller catheter manufacturers toward exit or acquisition. Surviving players will capture share from displaced competitors.
For Market Incumbents: Anchor hospital procurement relationships through software-hardware ecosystem bundling that raises switching costs for catheter purchasing committees. Deepen backward integration into platinum-iridium electrode supply to insulate margin structures from commodity volatility. Defend against domestic Chinese manufacturers by establishing local clinical trial infrastructure for NMPA priority review pathway access. For New Entrants and Emerging Players: Pediatric electrophysiology service lines represent the most penetrable white-space target given cryoablation preference in congenital accessory pathway cases and limited dedicated supplier focus. Target ambulatory surgical center disposable contracts where procurement concentration is less advanced than in integrated delivery networks. Pursue cryoablation technology licensing agreements with established mapping platform providers to bypass capital-intensive hardware development. For Investors and Strategic Acquirers: Re-rating potential sits with cryoablation technology specialists given pediatric application expansion and lower thrombogenic risk profile differentiation against thermal ablation. Long-term viability over a multi-year window favors manufacturers with FDA breakthrough device designations and established reimbursement codes for same-day discharge. Monitor Japan PMDA-FDA harmonization progress as the signal indicating accelerated geographic expansion opportunity for platform-integrated catheter suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses commercialization timelines for novel mapping systems by 12-18 months versus standard 510(k) pathways. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida consolidate supplier relationships from five to two active vendors per network. |
| CE Marking Pathway | EMA Medical Device Regulation compliance for Class III electrophysiology devices imposes documentation burdens that filter smaller manufacturers. |
| Software Companion Development | Three-dimensional electroanatomical mapping integration locks catheter purchasing into proprietary hardware ecosystems. |
| Reimbursement Strategy | Same-day ablation discharge codes in United States ambulatory surgical centers redirect site-of-care migration from inpatient cardiac centers. |
Research Methodology
Independent corroboration across electrophysiology device manufacturer filings, hospital procurement database records, and regulatory submission documents underwrites the qualitative findings. Primary interviews with electrophysiology fellows, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) clearances, EMA CE marking databases, and CMS Medicare reimbursement schedules. Bottom-up catheter volume estimates and top-down ablation system revenue figures were reconciled across the analysis window.
Comparable-period anchoring to historical electrophysiology lab installation cycles and catheter replacement rhythms structured the forecast window. Segmentation dimensions modeled include product type, therapy area, end user facility type, treatment mode, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and procedure volume trajectories. Cryoablation technology maturation curves and ambulatory surgical center reimbursement evolution served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden regulatory pathway reversals in China or Japan, electrophysiology fellow training pipeline collapse, and breakthrough mapping technology obsolescence of fluoroscopy-dependent workflows. Forecasts reflect assumptions about reimbursement stability and supply chain continuity. Material deviation in NMPA priority review timelines, EMA MDR enforcement intensity, or Medicare same-day discharge coding warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Tinnitus Management Market