
 Bronchiectasis Market | 2026-2036
Bronchiectasis Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchiectasis Market Analysis
China is fragmenting as local manufacturers scale inhalation-device capacity alongside multinational entrants. Insmed leverages its liposomal amikacin platform to anchor inhaled antibiotic leadership across North American and European hospital networks. AstraZeneca sustains broad-spectrum respiratory R&D pipelines that compete for share in corticosteroid and bronchodilator segments. Boehringer Ingelheim differentiates through decades of chronic obstructive pulmonary disease expertise that extends into bronchiectasis-adjacent prescribing workflows.
Bronchiectasis denotes irreversible dilation of bronchi with chronic inflammation, mucus accumulation, and recurrent infection requiring sustained pharmacological intervention through inhaled, oral, or intravenous routes. The condition demands long-term antibiotic prophylaxis, mucolytic clearance, and intermittent bronchodilator support to preserve lung function and reduce exacerbation frequency. Antibiotics occupy the largest margin pool given chronic suppressive therapy requirements, while inhalation routes lead volume growth due to targeted pulmonary delivery and reduced systemic exposure. Homecare settings represent the fastest-expanding end-user channel as payors push cost-efficient outpatient management and patients gain access to nebulizer and dry-powder inhaler technologies.
FDA orphan-drug designations and EMA centralized marketing authorizations shape product development timelines and reimbursement thresholds for novel inhaled formulations. The EPA regulates residual solvent limits and environmental release from active pharmaceutical ingredient manufacturing, constraining contract manufacturer selection for liposomal and complex generic programs. WHO Essential Medicines List inclusion criteria for aztreonam and tobramycin alternatives influence national procurement tenders across emerging markets. Stakeholders must monitor pipeline-to-practice translation for once-daily inhaled regimens and the evolving payer evidence requirements that will determine formulary positioning ahead of upcoming patent expiries.
Market Dynamics
Inhaled liposomal antibiotic platforms are compressing hospital length-of-stay metrics and redistributing prescribing authority from inpatient infectious-disease specialists to outpatient pulmonology clinics. This delivery-technology shift alters reimbursement bundling and site-of-care economics across developed markets.
Growth Catalysts
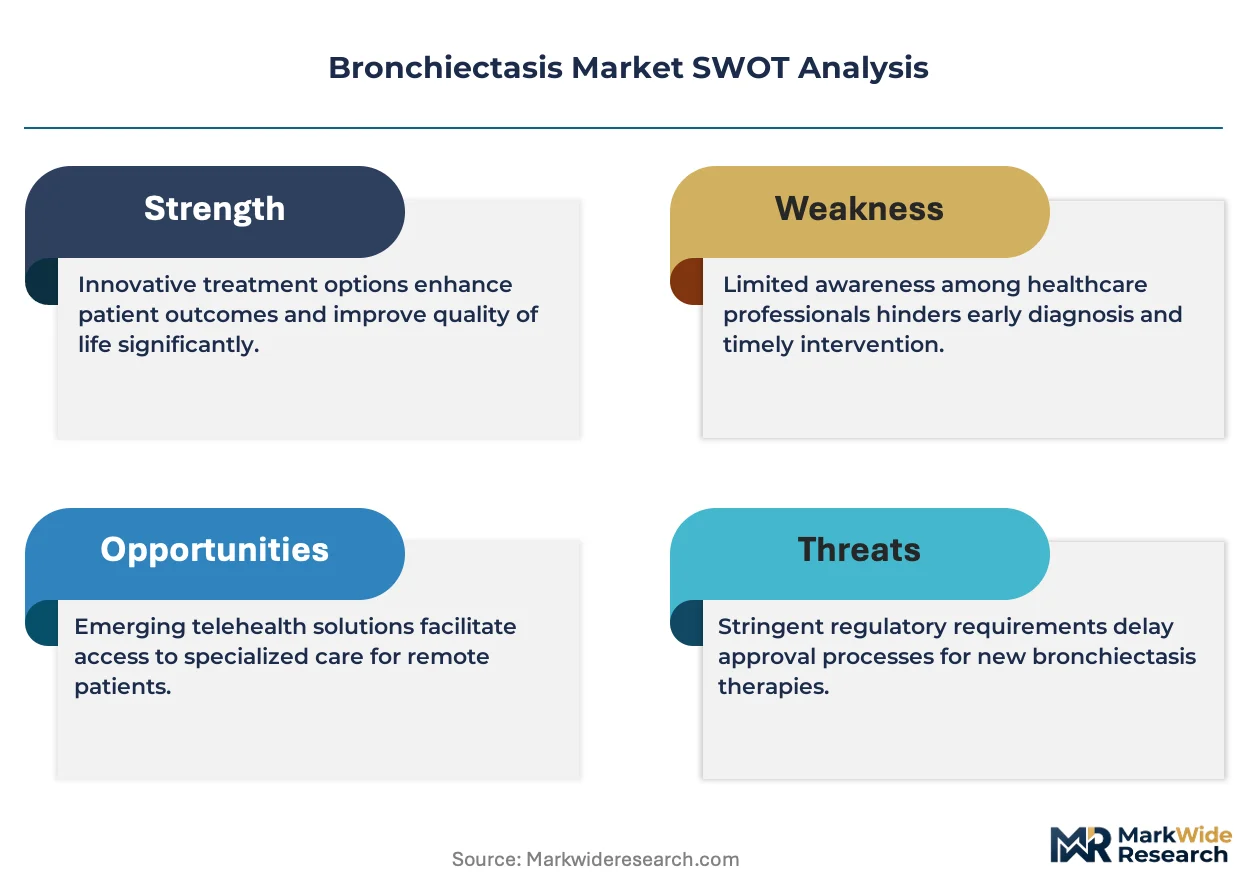
- Orphan-drug exclusivity frameworks:FDA and EMA accelerated review pathways for inhaled antibiotics reduce development timelines and secure premium pricing corridors for novel formulations targeting Pseudomonas aeruginosa colonization.
- Home nebulization infrastructure:Reimbursement codes for durable medical equipment in the United States and Japan expand patient-managed chronic suppressive therapy outside acute-care settings.
- Liposomal encapsulation advances:Sustained-release pulmonary deposition technology improves antibiotic pharmacokinetics and reduces dosing frequency, driving formulary preference in hospital networks.
Market Restraints
- API manufacturing concentration:Active pharmaceutical ingredient production for aminoglycosides concentrates in China and India, exposing supply chains to geopolitical friction and environmental compliance disruptions.
- Inhalation-device technical barriers:Nebulizer-to-patient interface variability limits dose reproducibility compared to oral solids, constraining adoption in cost-sensitive public health systems.
- Substitution by oral macrolides:Long-term azithromycin prophylaxis offers comparable exacerbation reduction at lower per-patient cost, pressuring inhaled antibiotic volume in maintenance indications.
Strategic Opportunities
- Underpenetrated German outpatient networks:Specialist pulmonology practices in Bavaria and North Rhine-Westphalia lack standardized home-monitoring protocols, creating whitespace for integrated device-pharma service bundles.
- Japanese super-aging municipalities:METI regional health innovation clusters in rural prefectures seek bronchiectasis management models that reduce elderly hospitalization burden.
- Convergence of digital adherence sensors:Bluetooth-enabled nebulizers paired with pharmacy benefit management data streams enable payor-preferred value-based contracts for chronic antibiotic therapy.
Industry Challenges
- Aerosol physicist talent scarcity:Formulation science expertise for complex generic liposomal programs concentrates in fewer than twelve academic centers globally, elongating hiring timelines.
- Legacy electronic health record integration:Hospital systems running Cerner and Epic variants require customized interoperability layers to capture respiratory therapy adherence data for quality reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchiectasis Market |
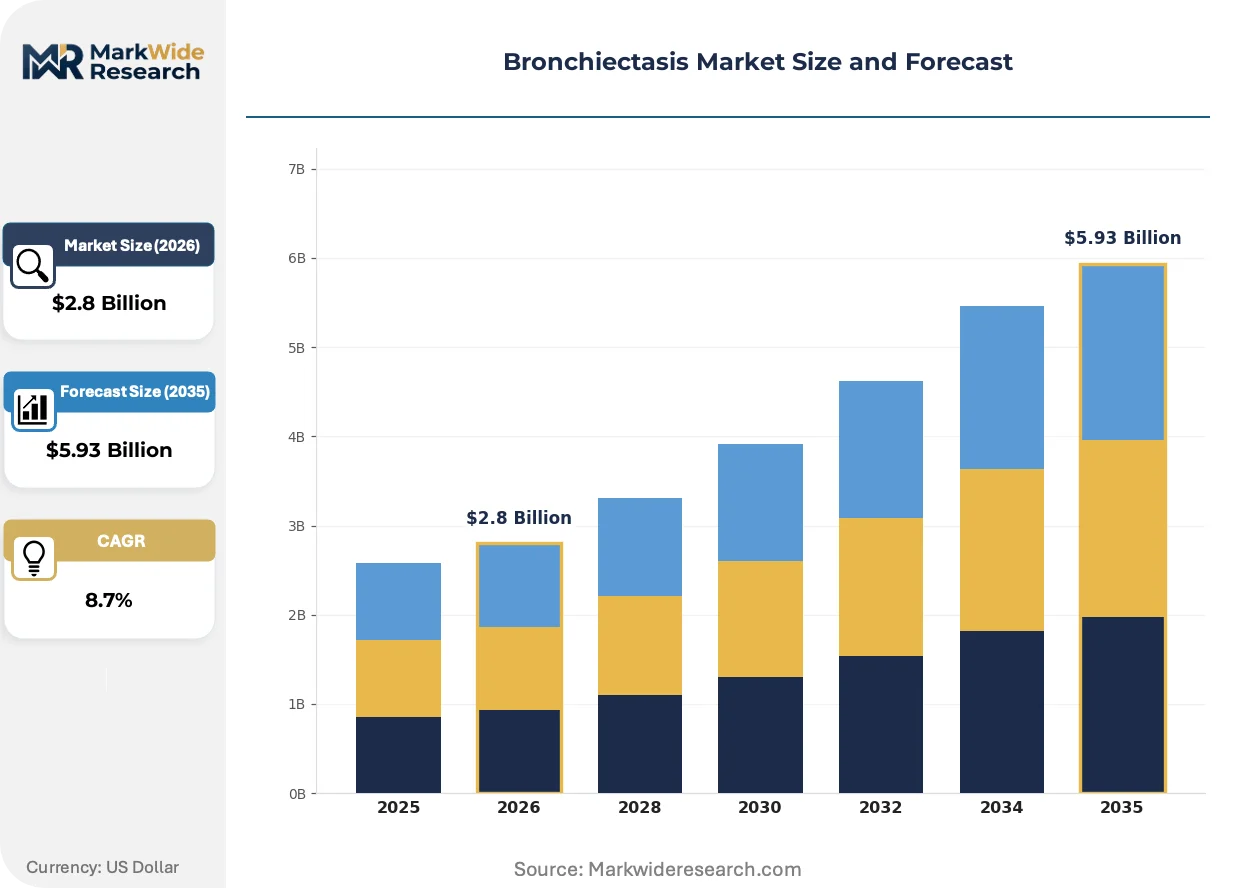
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Mucolytics, Bronchodilators, Corticosteroids End User: Hospitals, Homecare, Clinics, Specialty Centers Treatment Protocol: Pharmacological, Surgical, Holistic, Palliative Administration Route: Inhalation, Oral, Intravenous, Subcutaneous |
| Companies Covered | Insmed, AstraZeneca, Boehringer Ingelheim, GlaxoSmithKline, Bayer AG, Chiesi Farmaceutici, Zambon, Sanofi, Sunovion Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchiectasis Market Emerging Trajectories
Pharmaceutical delivery science and respiratory device engineering are converging to compress treatment cycles and shift economic value from acute intervention toward chronic disease management platforms.
Dry-powder inhaler antibiotic formulations are migrating from nebulizer-dependent hospital protocols toward ambulatory care settings. Pulmonology practices in the United States and Germany are adopting these devices for maintenance suppressive therapy. This migration from liquid nebulization to breath-actuated powder systems reduces clinic nursing burden and enables patient self-administration.
EMA centralized marketing authorization requirements for inhaled combination products are tightening quality-by-design documentation standards for device-drug pairs. Manufacturers must submit integrated development plans covering both active pharmaceutical ingredient and delivery mechanism. Liposomal amikacin programs face extended regulatory timelines as they navigate this framework.
Hospital procurement committees are unbundling device and drug purchasing decisions that were historically bundled under single-source contracts. Pharmacy directors in Japan and the United States now separately evaluate nebulizer platforms and antibiotic vials or cartridges. This unbundling creates contracting complexity for integrated solution providers but opens entry points for generic drug manufacturers with compatible device form factors.
Bronchiectasis Market Segmentation
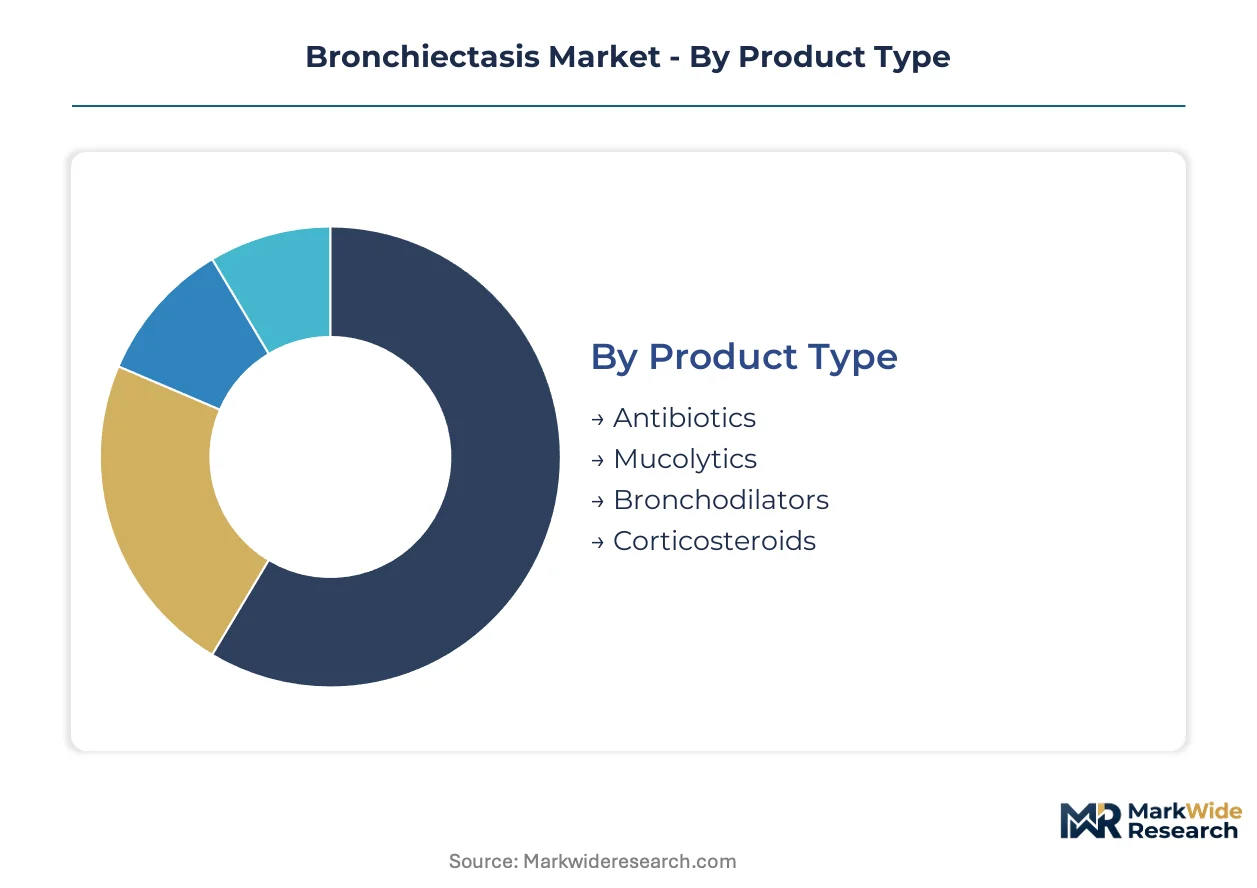
Bronchiectasis treatment selection hinges on disease severity, infection burden, and site-of-care capabilities. Segmentation reveals where pharmaceutical investment concentrates and which delivery technologies command premium positioning across acute and chronic care pathways.
Product Type:
After-sales service intensity varies sharply across product categories, with inhaled formulations requiring device calibration support and patient training programs that oral therapies do not demand.
- Antibiotics:Chronic suppressive therapy against Pseudomonas aeruginosa and other colonizing organisms drives sustained prescription volume. Hospital networks in the United States and Germany favor liposomal amikacin formulations for their pharmacokinetic profile and reduced nephrotoxicity risk relative to systemic alternatives.
- Mucolytics:Agents such as dornase alfa and hypertonic saline reduce sputum viscosity and improve airway clearance. Demand clusters in Japanese super-aging municipalities where elderly patients require daily home administration support and municipal health innovation clusters subsidize device distribution.
- Bronchodilators:Beta-agonist and anticholinergic therapy provides intermittent symptomatic relief during exacerbations.
- Corticosteroids:Inhaled anti-inflammatory therapy addresses eosinophilic-predominant phenotypes with overlapping asthma pathology.
By volume, antibiotics lead. By growth pace, mucolytics are ahead.
End User:
Cost tier differentiation separates capital-intensive hospital infrastructure from leaner outpatient and home-based alternatives.
- Hospitals:Acute exacerbation management and intravenous antibiotic initiation occur in tertiary pulmonary centers with infectious-disease consultation. German hospital networks in Bavaria and North Rhine-Westphalia anchor inpatient volume through integrated bronchoscopy and physiotherapy services.
- Homecare:Nebulization infrastructure and remote monitoring enable chronic suppressive therapy outside institutional settings. United States durable medical equipment reimbursement codes and Japanese regional health innovation clusters accelerate patient-managed care adoption in rural prefectures.
- Clinics:Outpatient pulmonology practices handle stable patient monitoring and prescription renewal.
- Specialty Centers:Dedicated respiratory institutes concentrate complex case referral and clinical trial access.
By installed base, hospitals dominate. By expansion trajectory, homecare is climbing the fastest.
Treatment Protocol:
Application severity determines protocol selection, with pharmacological intervention forming the backbone of all but terminal disease stages.
- Pharmacological:Long-term antibiotic prophylaxis, mucolytic clearance, and intermittent bronchodilator support preserve lung function. FDA orphan-drug designations and EMA centralized marketing authorizations shape development timelines for novel inhaled formulations targeting maintenance indications.
- Surgical:Lobectomy or lung resection addresses localized disease refractory to medical management.
- Holistic:Physiotherapy, nutritional optimization, and smoking cessation complement pharmaceutical therapy.
- Palliative:Symptom-focused care predominates in end-stage respiratory failure with limited reversibility.
By patient volume share, pharmacological protocols lead. By intervention cost per episode, surgical approaches command the highest expenditure.
Administration Route:
Supply concentration in device manufacturing creates divergent margin structures across delivery modalities.
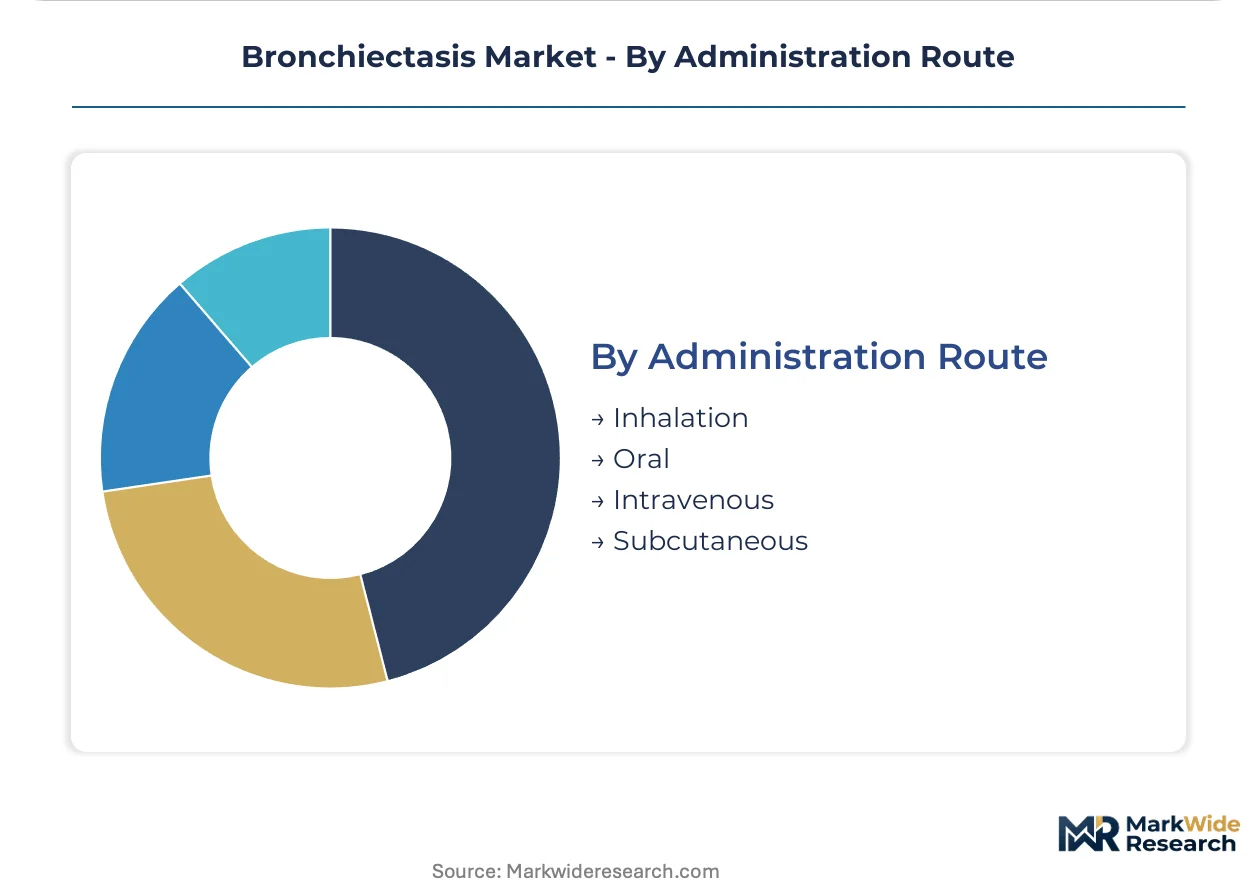
- Inhalation:Nebulized solutions, dry-powder inhalers, and metered-dose devices enable targeted pulmonary deposition with reduced systemic exposure. EPA residual solvent regulations constrain contract manufacturer selection for liposomal programs, while EMA quality-by-design documentation requirements extend regulatory timelines for device-drug pairs.
- Oral:Macrolide prophylaxis offers convenient chronic suppressive therapy with lower per-patient cost than inhaled alternatives.
- Intravenous:Acute exacerbation management requires hospital-based infusion capability.
- Subcutaneous:Limited current application with emerging investigation in depot antibiotic formulations.
By prescription volume, oral administration leads. By innovation investment intensity, inhalation routes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for aminoglycosides concentrates in China and India, while device assembly and clinical trial activity cluster in the United States, Germany, and Japan. Hospital networks in these markets anchor demand for inhaled liposomal formulations.
United States
FDA orphan-drug designations accelerate development timelines for inhaled antibiotics targeting Pseudomonas aeruginosa colonization. Medicare durable medical equipment reimbursement codes expand home nebulization infrastructure for chronic suppressive therapy. Boston and San Francisco Bay Area pulmonary centers concentrate clinical trial access and specialist pulmonology referral networks.
Germany
EMA centralized marketing authorizations shape quality-by-design documentation standards for device-drug combination products. Bavaria and North Rhine-Westphalia hospital networks anchor inpatient volume through integrated bronchoscopy and physiotherapy services. Specialist practices in these regions lack standardized home-monitoring protocols, creating whitespace for integrated service bundles.
Japan
METI regional health innovation clusters in rural prefectures seek bronchiectasis management models that reduce elderly hospitalization burden. PMDA marketing authorization pathways influence development timelines for novel inhaled formulations. Super-aging municipalities subsidize mucolytic device distribution and homecare infrastructure.
China
NMPA regulatory frameworks govern marketing authorization for inhaled combination products and complex generics. Local manufacturers scale inhalation-device capacity alongside multinational entrants, fragmenting competitive positioning. Yangtze River Delta pharmaceutical clusters concentrate API production for aminoglycosides.
United Kingdom
NICE technology appraisal processes determine reimbursement thresholds for inhaled antibiotic therapies within NHS England commissioning frameworks. London and Southeast England respiratory centers concentrate complex case referral and specialist training capacity. Procurement committees unbundle device and drug purchasing decisions historically managed under single-source contracts.
Bronchiectasis Market Vendor Landscape
Specialist respiratory pharmaceutical developers and diversified multinational pharmaceutical conglomerates split the market between focused inhaled antibiotic platforms and broad-spectrum respiratory portfolios. The competitive structure consolidates around liposomal encapsulation expertise and chronic obstructive pulmonary disease extension strategies. Three archetypes dominate: liposomal formulation specialists, respiratory portfolio generalists, and chronic disease platform extenders. M&A activity targets device-pharma integration capabilities, while strategic partnerships secure nebulizer-to-patient interface standardization.
Within the liposomal specialist tier, Insmed anchors inhaled antibiotic leadership across North American and European hospital networks. AstraZeneca exemplifies the respiratory generalist archetype with sustained R&D pipelines competing across corticosteroid and bronchodilator segments. Boehringer Ingelheim occupies a position as chronic disease platform extender, leveraging decades of obstructive pulmonary expertise into adjacent prescribing workflows. These three entities represent the dominant strategic positioning vectors in the market.
| Leading Market Players |
|---|
| Insmed |
| AstraZeneca |
| Boehringer Ingelheim |
| GlaxoSmithKline |
| Bayer AG |
| Chiesi Farmaceutici |
| Zambon |
| Sanofi |
| Sunovion Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese and Indian aminoglycoside API production exposes pricing tiers to environmental compliance disruptions and geopolitical friction, compressing margin structures for liposomal formulations while forcing hospital procurement committees toward dual-source contracting strategies that reshape downstream distribution economics.
Pricing Analysis
FDA orphan-drug exclusivity dictates the pricing tier structure across inhaled antibiotic portfolios, with three-tier pricing separating liposomal amikacin premium positioning from standard nebulized tobramycin and economy oral macrolide alternatives. Price differentiation rests on pharmacokinetic certification grade and bundled device service intensity. Cost compression in the maintenance therapy tier is intensifying because azithromycin prophylaxis offers comparable exacerbation reduction at lower per-patient cost. Public health systems exhibit highest price sensitivity; private hospital networks in the United States and Germany demonstrate lowest sensitivity due to reimbursement code protections.
Supply Chain Analysis
Upstream aminoglycoside fermentation feedstock concentrates in Yangtze River Delta pharmaceutical clusters and Indian API manufacturing zones, with liposomal encapsulation phospholipids sourcing from European and North American specialty chemical producers. Active pharmaceutical ingredient production draws from China and India, device assembly feeds from the United States and Germany, and final packaging hinges on Japanese quality-controlled facilities. Single-source vulnerability in aminoglycoside API supply creates exposure to environmental regulatory enforcement actions. Distribution runs through hospital procurement committees, specialty pharmacy networks, and durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liposomal encapsulation technology disruption and FDA accelerated review pathway expansion create a high-growth inflection, compressing development timelines while redistributing economic value toward chronic disease management platforms.
For Market Incumbents: Harden liposomal formulation expertise through captive phospholipid supply arrangements and aerosol physicist talent acquisition from the twelve global academic centers concentrating this capability. Anchor hospital network formulary positioning against substitution threat from oral macrolide prophylaxis by emphasizing pharmacokinetic differentiation and reduced nephrotoxicity profiles in Pseudomonas aeruginosa colonization protocols. For New Entrants and Emerging Players: German outpatient pulmonology practices in Bavaria and North Rhine-Westphalia present whitespace for integrated device-pharma service bundles targeting home-monitoring protocol standardization. Japanese super-aging municipalities seek bronchiectasis management models reducing elderly hospitalization burden, creating entry points through METI regional health innovation cluster partnerships. Pursue Bluetooth-enabled nebulizer companion technology as the go-to-market anchor for payor-preferred value-based contracting. For Investors and Strategic Acquirers: FDA and EMA centralized marketing authorization convergence reshapes the acquisition landscape, extending regulatory timelines for device-drug pairs while elevating quality-by-design documentation capabilities as scarce assets. Long-term viability favors platforms spanning inhaled antibiotic, mucolytic, and bronchodilator segments with integrated device control. Target acquisition archetypes: liposomal formulation specialists with hospital network anchoring and aerosol physicist bench strength. Monitor pipeline-to-practice translation for once-daily inhaled regimens as the signal indicating competitive inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA orphan-drug designation accelerates inhaled antibiotic development timelines and secures premium pricing corridors. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion in North American and European contract manufacturing organizations reduces API supply chain exposure. |
| Pipeline Diversification | Once-daily inhaled regimen development targets maintenance indication substitution pressure from oral macrolides. |
| Hospital System Partnership | Integrated bronchoscopy and physiotherapy service bundling anchors Bavaria and North Rhine-Westphalia inpatient volume. |
| Reimbursement Strategy | Medicare durable medical equipment code expansion enables United States home nebulization infrastructure for chronic suppressive therapy. |
Methodological Framework
Desk research of FDA orphan-drug filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and hospital procurement database records preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Bottom-up prescription volume modeling across administration routes and top-down market size validation through pharmaceutical revenue disclosure triangulation anchored quantitative outputs. Secondary validation incorporated WHO Essential Medicines List inclusion criteria and national procurement tender documentation across emerging markets.
Assumptions held fixed include observed FDA and EMA review pathway timelines, current reimbursement code structures in the United States and Japan, and liposomal encapsulation technology diffusion rates. Variables incorporated across the analysis window encompass oral macrolide substitution elasticity, home nebulization infrastructure penetration curves, and environmental compliance enforcement intensity in Chinese API manufacturing zones. Segmentation modeling spanned product type, end user, treatment protocol, and administration route dimensions. CAGRs derived from patient population epidemiology, treatment rate assumptions, and pricing trajectory inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oral macrolide generic manufacturers or Bluetooth-enabled nebulizer technology disruptors would shift outcomes materially. Cross-checking against hospital procurement committee purchasing decision unbundling trends and PMDA marketing authorization pathway evolution is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market