
 Desmoid Tumor Market | 2026-2036
Desmoid Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
Desmoid Tumor Market Analysis
Oncology centers is broadening their share of desmoid tumor care as hospitals shift complex cases to specialized settings. SpringWorks Therapeutics leverages its gamma secretase inhibitor portfolio to anchor clinical development in this niche. Novartis AG competes through established tyrosine kinase inhibitor infrastructure. Pfizer sustains manufacturing scale across oncology biologics that supports off-label utilization patterns.
Desmoid tumors are locally aggressive, non-metastatic neoplasms arising from musculoaponeurotic structures, characterized by beta-catenin mutations and infiltrative growth patterns that complicate surgical margins. These lesions primarily serve as targets for systemic therapy when resection risks functional impairment or recurrence probability exceeds acceptable thresholds. Targeted therapy represents the fastest-expanding segment, with tyrosine kinase inhibitors capturing disproportionate clinical investment as chemotherapy utilization matures. The drug class dimension stratifies around kinase inhibitors versus hormonal agents, where margin pools favor novel mechanisms with orphan exclusivity.
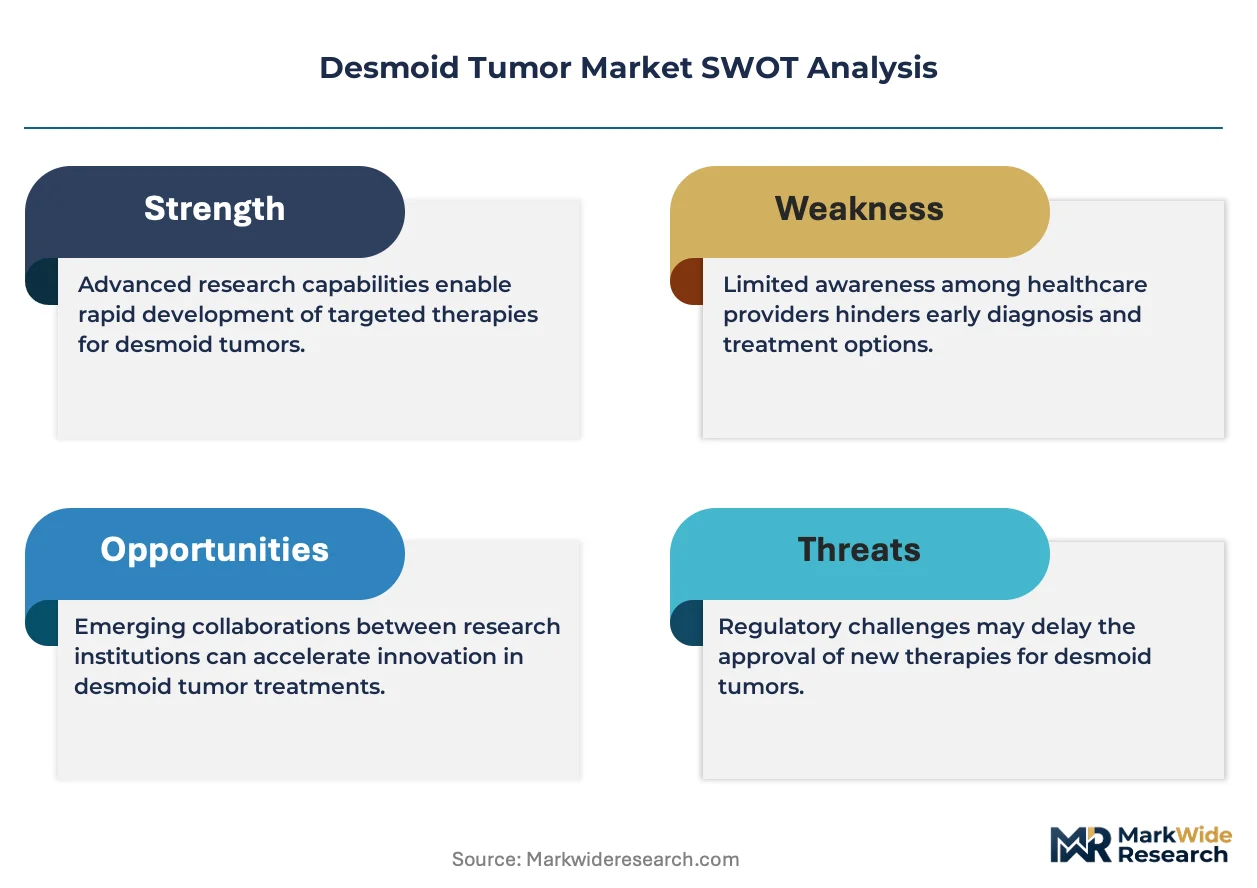
The FDA orphan drug program shapes development economics through tax credits and market exclusivity windows, while EMA parallel designation accelerates European access timelines. ISO 14155 governs clinical trial conduct across jurisdictions, ensuring data integrity for regulatory submissions. Stakeholders must monitor biomarker-defined patient subsets and evolving payer evidence requirements for non-curative chronic therapy positioning.
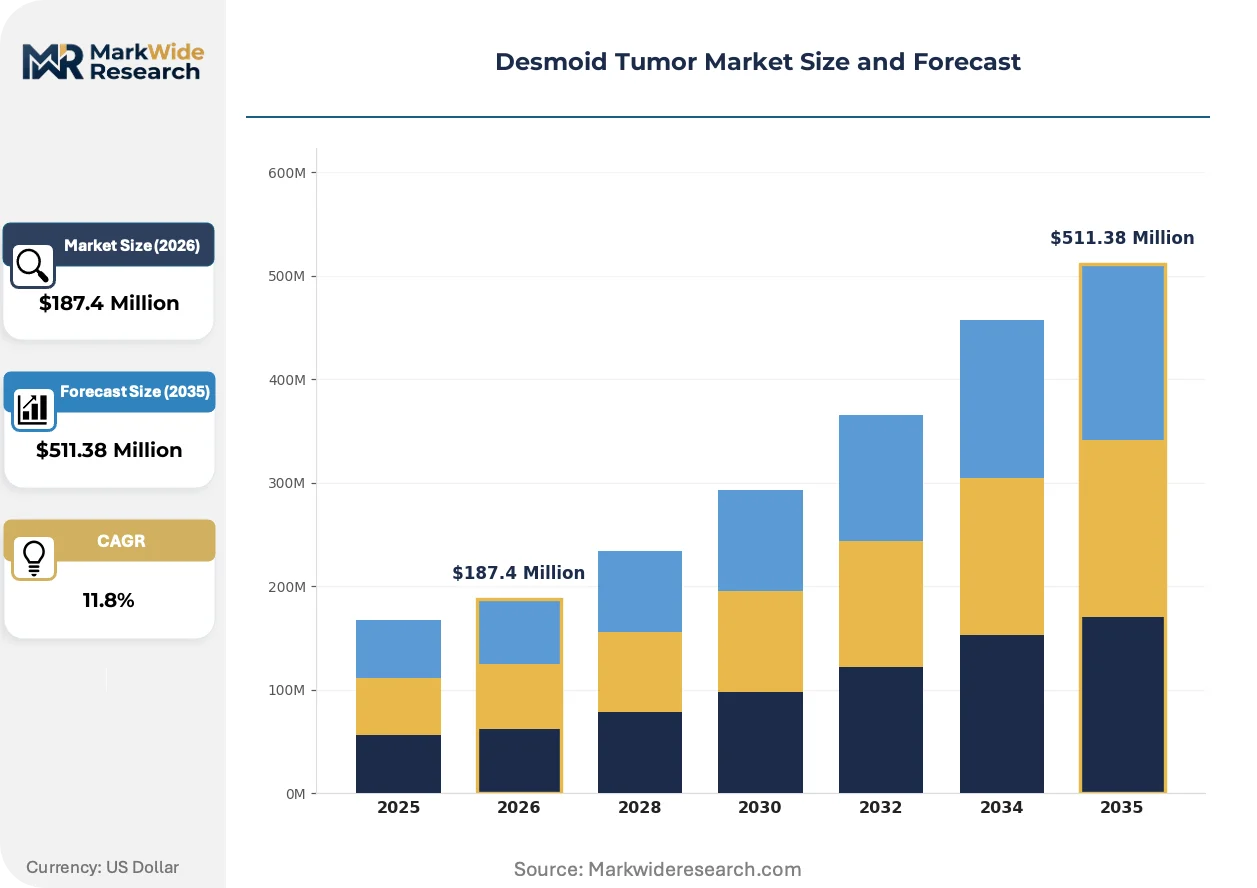
Market Dynamics
The orphan drug designation pathway is concentrating development resources toward desmoid tumor indications, as FDA tax credits and seven-year exclusivity windows compress competitive timelines and reshape portfolio prioritization across biopharma pipelines.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits offset clinical trial costs for desmoid tumor programs, accelerating sponsor commitment to this rare indication.
- Sarcoma Network Expansion:Dedicated oncology centers in the United States are centralizing complex case referrals, concentrating treatment volume and specialist expertise.
- Gamma Secretase Inhibition:Novel mechanism targeting Notch pathway dysregulation offers differentiated efficacy profiles versus existing tyrosine kinase inhibitors.
Market Restraints
- Small Patient Populations:Ultra-rare incidence rates below two per million limit commercial scale and inflate per-patient development costs.
- Biomarker Complexity:Beta-catenin mutation heterogeneity complicates patient stratification and predictive enrichment strategies.
- Reimbursement Uncertainty:Chronic non-curative therapy positioning creates payer resistance for high-cost targeted agents without overall survival endpoints.
Strategic Opportunities
- Combination Regimens:Pairing tyrosine kinase inhibitors with immunomodulatory agents offers mechanistic synergy in treatment-naive populations.
- Real-World Evidence Pathways:FDA's Project Orbis enables parallel regulatory submissions across the United States, Australia, Canada, Singapore, Switzerland, and the United Kingdom.
- Companion Diagnostic Development:CTNNB1 mutation testing penetration creates service revenue streams and treatment-eligible patient identification.
Industry Challenges
- Trial Recruitment Velocity:Sparse patient geography necessitates multi-country enrollment and complex site activation timelines.
- Endpoint Validation:Progression-free survival as primary endpoint requires harmonized imaging protocols across investigator sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desmoid Tumor Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Radiation Therapy, Targeted Therapy End User: Hospitals, Clinics, Research Institutions, Oncology Centers Drug Class: Non-Steroidal Anti-Inflammatory Drugs, Tyrosine Kinase Inhibitors, Antineoplastics, Hormonal Agents Stage: Early Stage, Advanced Stage, Recurrent Stage, Metastatic Stage |
| Companies Covered | SpringWorks Therapeutics, Ayala Pharmaceuticals, Iterion Therapeutics, Bayer AG, Novartis AG, AbbVie, Amgen, Pfizer, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desmoid Tumor Market Emerging Trajectories
Clinical development is consolidating around mechanism-driven patient selection, with sponsors abandoning broad enrollment in favor of biomarker-defined subsets that demonstrate amplified response signals.
Tyrosine kinase inhibitor development is consolidating as the dominant systemic approach, with sorafenib and pazopanib regimens establishing efficacy benchmarks that novel agents must exceed. Oncology centers are adopting these protocols as first-line standards, compressing chemotherapy's residual role to salvage settings. The competitive landscape is consolidating around kinase inhibitor infrastructure, with manufacturing scale and safety databases becoming defensive moats.
FDA's breakthrough therapy designation pathway is compressing review timelines for desmoid tumor agents demonstrating substantial improvement over available options. Sponsors are leveraging rolling submission procedures to accelerate approval decisions. The regulatory environment is consolidating expectations around randomized controlled data, with single-arm studies facing heightened scrutiny for marketing authorization.
Patient advocacy networks are compressing information asymmetries between trial sponsors and eligible participants. Desmoid Tumor Research Foundation registries are enabling matched natural history controls and accelerating recruitment through centralized referral coordination. The United States exhibits the most mature advocacy infrastructure, with European patient organizations replicating this engagement model.
Desmoid Tumor Market Segmentation
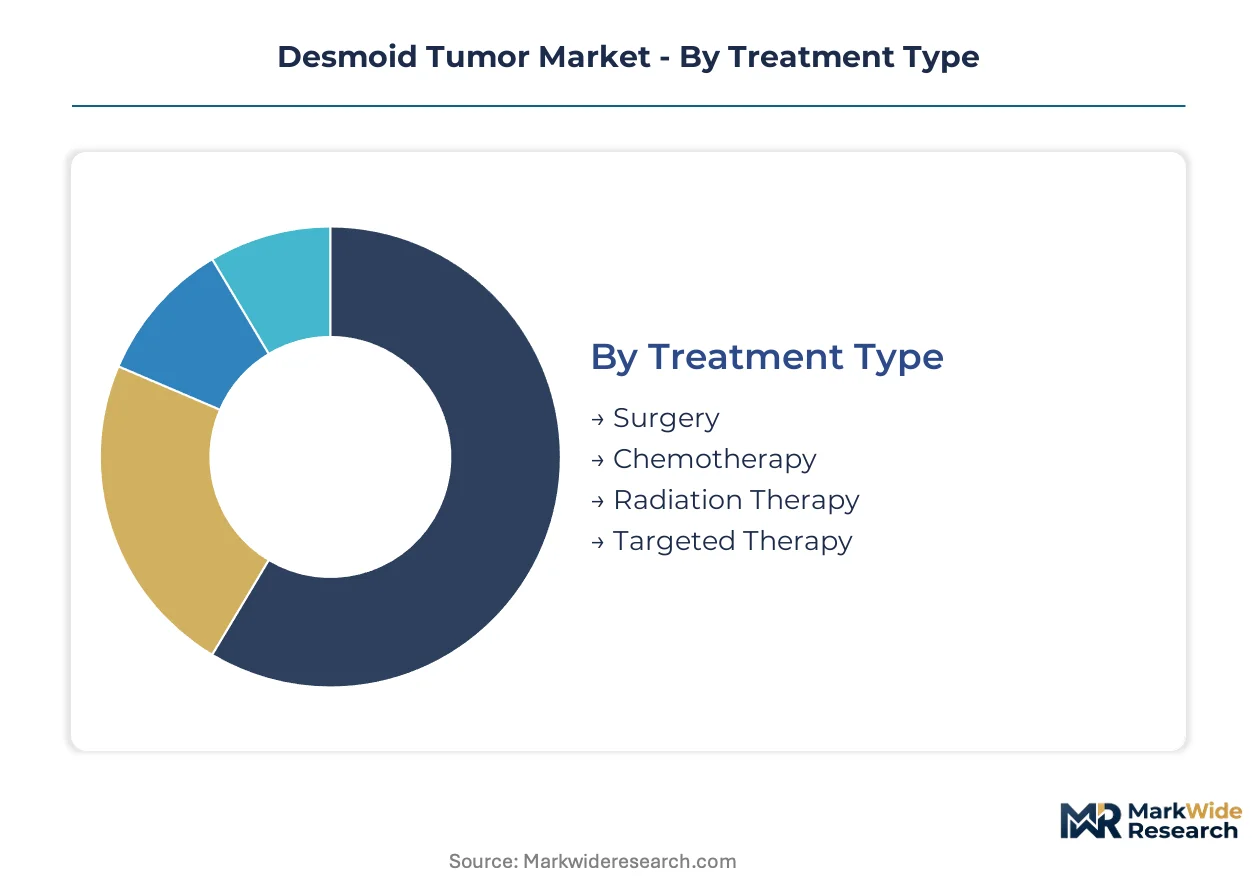
Desmoid tumor treatment pathways fragment across intervention modalities, patient disease states, and care delivery settings. Each segmentation dimension carries distinct regulatory requirements, reimbursement profiles, and clinical evidence standards that reshape competitive positioning.
Treatment Type:
Integration depth varies sharply: surgery operates as standalone curative intent, while systemic therapies embed within longitudinal care protocols.
- Surgery:Resection remains the foundational intervention for localized, resectable lesions with clear margins. United States sarcoma centers concentrate complex cases requiring limb-sparing or functional preservation techniques. Margin status dictates adjuvant therapy decisions and recurrence monitoring intensity.
- Targeted Therapy:Tyrosine kinase inhibitors and gamma secretase inhibitors function as embedded components of chronic disease management. Oncology centers in the United States deploy these as first-line systemic options when surgical morbidity exceeds acceptable thresholds. FDA breakthrough designations accelerate access for novel mechanisms.
- Chemotherapy:Anthracycline and alkylating agent regimens retain salvage positioning after targeted therapy failure.
- Radiation Therapy:Adjuvant or definitive radiation serves unresectable cases with functional preservation requirements.
Volume placements concentrate in Surgery; the faster expansion belongs to Targeted Therapy.
End User:
Cost tier stratification separates high-complexity academic centers from community-based delivery nodes.
- Oncology Centers:Dedicated sarcoma programs anchor multidisciplinary care with embedded clinical trial access. United States metropolitan clusters concentrate referral volumes and specialist density. Reimbursement premiums attach to NCCN-designated comprehensive cancer centers.
- Hospitals:General acute care facilities handle initial diagnosis and stabilization before transfer. Community hospitals in the United States maintain limited systemic therapy capabilities for stable patients. Capital constraints limit molecular diagnostics and specialized surgical infrastructure.
- Research Institutions:Academic medical centers generate natural history data and biomarker discovery.
- Clinics:Outpatient settings manage stable patients on oral targeted therapy with remote monitoring.
Patient flow concentrates in Oncology Centers; the steepest capacity expansion is occurring in Research Institutions.
Drug Class:
Application logic separates acute symptom management from disease-modifying systemic intervention.
- Tyrosine Kinase Inhibitors:Sorafenib, pazopanib, and imatinib constitute the dominant systemic drug class with established progression-free survival benchmarks. United States prescribing concentrates in academic oncology networks with prior authorization expertise. Manufacturing scale at established sponsors creates competitive moats.
- Hormonal Agents:Tamoxifen and toremifene serve hormone-responsive subsets with lower toxicity profiles. European prescribing patterns retain higher hormonal agent utilization than United States practice. Response heterogeneity limits biomarker-driven patient selection.
- Non-Steroidal Anti-Inflammatory Drugs:Sulindac maintains niche utilization for stable, asymptomatic disease.
- Antineoplastics:Cytotoxic chemotherapy agents occupy salvage positioning after targeted therapy exhaustion.
Prescription volume concentrates in Tyrosine Kinase Inhibitors; Hormonal Agents are gaining share fastest in stable disease management protocols.
Stage:
Customer type stratification separates incident cases from complex recurrent populations with distinct evidence requirements.
- Advanced Stage:Locally aggressive, unresectable disease drives systemic therapy initiation and clinical trial enrollment. United States academic centers concentrate these patients for novel agent access. Payer scrutiny intensifies for chronic non-curative therapy positioning without overall survival endpoints.
- Recurrent Stage:Prior treatment exposure reshapes therapeutic options and resistance profiles. Specialist networks in the United States maintain registries tracking sequential therapy outcomes. Cross-resistance patterns between tyrosine kinase inhibitors complicate subsequent line selection.
- Early Stage:Incident localized disease retains curative intent surgical or surveillance approaches.
- Metastatic Stage:True metastatic behavior is rare; this category captures exceptional extra-abdominal dissemination.
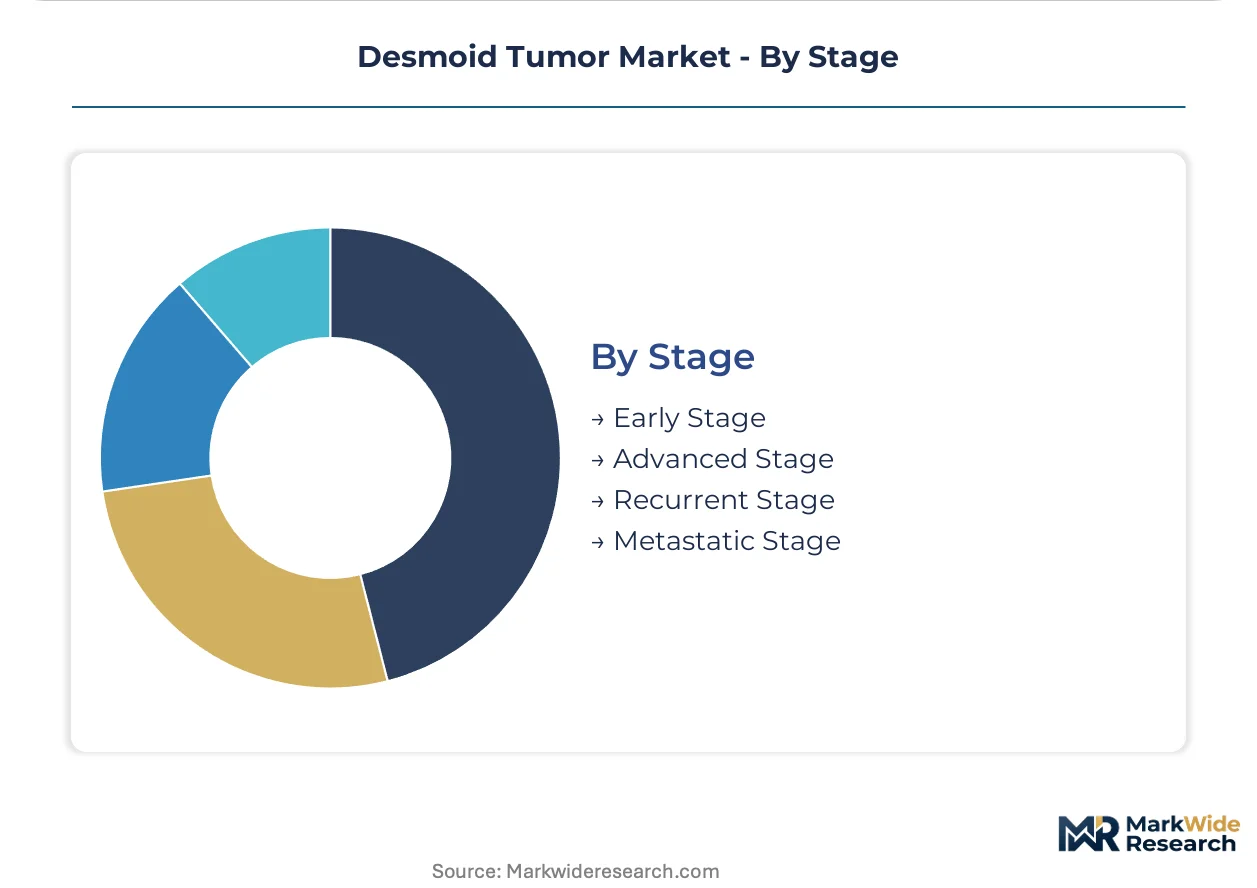
Clinical trial recruitment concentrates in Advanced Stage; the expanding eligible population sits in Recurrent Stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug tax credits under the United States FDA program concentrate clinical trial investment and manufacturing capacity in designated metropolitan oncology clusters.
United States
NCCN-designated comprehensive cancer centers in Boston and New York anchor sarcoma specialist networks that centralize complex desmoid tumor referrals. FDA breakthrough therapy designations compress review timelines for novel gamma secretase inhibitors. The Desmoid Tumor Research Foundation in Philadelphia coordinates patient registries that accelerate trial recruitment through matched natural history controls.
Germany
EMA parallel orphan drug designation accelerates European market access for tyrosine kinase inhibitors developed under FDA programs. The country's national pharmaceutical regulator enforces ISO 14155 clinical trial standards that ensure data integrity for cross-border submissions. Heidelberg and Berlin academic medical centers generate biomarker discovery data that supports CTNNB1 mutation testing protocols.
United Kingdom
NHS England specialized commissioning frameworks concentrate desmoid tumor care in London and Manchester sarcoma units with embedded clinical trial access. MHRA participation in FDA's Project Orbis enables parallel regulatory submissions that compress approval timelines. The Royal Marsden Hospital maintains sequential therapy outcome registries that inform resistance pattern analysis.
Switzerland
Swissmedic alignment with EMA centralized procedures streamlines orphan drug marketing authorization for targeted therapy sponsors. Basel and Zurich oncology centers participate in multinational Phase II trials through EU clinical trial infrastructure. The country's pharmaceutical manufacturing base supplies active pharmaceutical ingredients for kinase inhibitor production.
Japan
PMDA orphan drug designation provides tax incentives and priority review vouchers that attract sponsor investment in desmoid tumor indications. Tokyo and Osaka academic hospitals concentrate sarcoma expertise with embedded gamma secretase inhibitor trial protocols. The country's aging demographic expands the addressable patient pool for chronic non-curative therapy positioning.
Desmoid Tumor Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biopharma companies dominating systemic therapy development while academic medical centers anchor surgical intervention volume. The vendor base concentrates around kinase inhibitor infrastructure, with manufacturing scale and safety databases becoming defensive moats for established oncology players. Three archetypes define positioning: gamma secretase innovators pursuing differentiated mechanisms, tyrosine kinase incumbents defending efficacy benchmarks, and diversified biopharma leveraging orphan drug tax credits. Competitive moves center on biomarker-driven patient selection and rolling submission procedures that compress approval timelines.
Within the gamma secretase innovation tier, SpringWorks Therapeutics and Ayala Pharmaceuticals exemplify mechanism-first development strategies targeting Notch pathway dysregulation. Novartis AG anchors the tyrosine kinase incumbent position through established infrastructure in targeted oncology. These three companies occupy distinct archetype positions that reshape portfolio prioritization across the development pipeline.
| Leading Market Players |
|---|
| SpringWorks Therapeutics |
| Ayala Pharmaceuticals |
| Iterion Therapeutics |
| Bayer AG |
| Novartis AG |
| AbbVie |
| Amgen |
| Pfizer |
| Bristol Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up oncology service networks anchor supply-side concentration in the United States, compressing procurement timelines for gamma secretase inhibitors while extracting volume-based rebates that discipline pricing across tyrosine kinase inhibitor portfolios. This ownership structure concentrates purchasing power at NCCN-designated centers, forcing manufacturers to absorb certification costs and maintain dual-source API strategies to retain formulary positioning.
Pricing Analysis
Short lead-time premiums attach to breakthrough-designated agents with rolling FDA submissions, while spot inventory discounts emerge for mature tyrosine kinase inhibitors facing biosimilar pressure. The dominant pricing structure is value-based with outcomes guarantees tied to progression-free survival milestones. Price differentiation rests on orphan exclusivity windows versus off-label utilization patterns, with United States academic centers showing least price sensitivity due to dedicated sarcoma funding streams and European oncology networks exhibiting highest sensitivity amid centralized NHS tendering.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification gates active pharmaceutical ingredient sourcing for desmoid tumor therapies, restricting qualified suppliers to facilities in the United States, Switzerland, and Japan with validated beta-catenin assay compatibility. Raw material dependencies center on high-purity kinase inhibitor intermediates, gamma secretase modulator scaffolds, and CTNNB1 companion diagnostic reagents. Single-source vulnerability concentrates in Swiss contract manufacturing organizations producing clinical-grade gamma secretase inhibitors. Distribution runs through specialty pharmacy networks with cold-chain integrity requirements for biologic stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around mechanism-first developers with FDA breakthrough designations, as reimbursement uncertainty for chronic non-curative therapy positioning forces marginal players toward partnership or exit.
For Market Incumbents: Cement kinase inhibitor market share through backward integration into API production in Basel and Zurich manufacturing corridors, insulating against Swissmedic supply disruptions. Expand companion diagnostic partnerships with CTNNB1 testing laboratories to lock in treatment-eligible patient identification before gamma secretase competitors reach market. For New Entrants and Emerging Players: Novel Notch pathway modulation mechanisms offer the most penetrable wedge for desmoid tumor indication expansion, targeting treatment-naive populations at United States sarcoma centers with embedded clinical trial infrastructure. Pursue FDA Project Orbis parallel submissions to compress regulatory timelines against entrenched tyrosine kinase benchmarks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap gamma secretase specialists with completed Phase II enrollment in the United States and pending EMA parallel orphan designation. Watch for inflection signals in real-world evidence registry maturation at the Desmoid Tumor Research Foundation, which precedes payer coverage determinations for novel mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II enrollment velocity at NCCN centers determines competitive positioning against sorafenib benchmarks. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines and accelerates Medicare coverage determinations. |
| Licensing Agreement | Companion diagnostic partnerships with CTNNB1 testing laboratories secure treatment-eligible patient funnels. |
| Manufacturing Scale-Up | Swiss and Japanese API capacity expansion reduces single-source vulnerability for gamma secretase inhibitors. |
| Pipeline Diversification | Combination regimens pairing tyrosine kinase inhibitors with immunomodulatory agents address cross-resistance patterns. |
Methodological Framework
Independent corroboration across drug development executives at gamma secretase innovators, regulatory affairs leads navigating FDA orphan pathways, formulary directors at NCCN-designated centers, and payer access specialists at major United States insurers underwrites the qualitative findings. Secondary validation draws from FDA breakthrough therapy designation filings, EMA parallel orphan drug submissions, ClinicalTrials.gov enrollment trackers, and Medicare coverage determination databases. Bottom-up patient flow modeling triangulates against top-down pharmaceutical revenue estimates across the analysis window.
Comparable-period anchoring to historical tyrosine kinase inhibitor launch trajectories shapes the forecast framework across treatment type, drug class, disease stage, and regional regulatory cluster dimensions. CAGRs derive from segmented adoption curves calibrated to orphan drug exclusivity windows and biomarker-defined addressable populations. Modeled inputs incorporate gamma secretase inhibitor clinical readout timelines and EMA centralized procedure approval velocities.
Several conditions sit outside the modeled scope, including unforeseen FDA advisory committee rejections, CTNNB1 testing reimbursement collapses, and gamma secretase mechanism safety signals requiring protocol amendments. A model refresh is warranted upon material change in Medicare national coverage determination policy for chronic non-curative oncology therapy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market