
 Aircraft Aluminium Plate Market | 2026-2036
Aircraft Aluminium Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Aluminium Plate Market Insights
Project finance tied to fleet renewal programs is fragmenting capital requirements across tiered supplier networks. Constellium leverages European rolling capacity to serve Airbus A320-family fuselage contracts. Alcoa anchors North American primary metal supply through integrated smelter-to-plate operations. Kaiser Aluminum competes on specialized 7000-series heat treatment for wing rib applications.
Aircraft aluminium plate comprises wrought aluminium alloy slabs, typically 6-250mm thick, produced through hot and cold rolling of cast ingots for structural airframe applications. Primary alloys include 2024-T3 for fatigue-critical wing skins, 7075-T6 for high-strength landing gear fittings, and 7050-T7451 for damage-tolerant fuselage frames, with melt metallurgy and thermomechanical processing dictating grain structure and mechanical performance. The 7000 Series segment leads value contribution due to premium pricing on high-strength plate for wing and landing gear applications, while Aluminium-Lithium alloys represent the fastest-growing product category as OEMs pursue density reductions for next-generation single-aisle programs. Heat Treatment technology dominates process value-add, with stretch forming and age hardening steps consuming significant capital and energy inputs.
FAA damage tolerance requirements under 14 CFR Part 25, EASA CS-25 certification standards, and China's CAAC CCAR-25 framework collectively dictate alloy qualification timelines and testing protocols for plate suppliers seeking airframe OEM approval. REACH restrictions on hexavalent chromium surface treatments and evolving EU Green Deal carbon border adjustments reshape pretreatment and cladding process investments. Stakeholders must monitor CAAC type certification reciprocity negotiations and alloy substitution trends in composite-intensive wing designs.
Market Dynamics
Fleet renewal cycles and composite-to-metal hybrid airframe designs are compressing qualification timelines for next-generation aluminium alloys, forcing plate suppliers to synchronize R&D with OEM platform development schedules rather than aftermarket replacement patterns.
Growth Catalysts
- 2024-T3 wing skin specifications:Fatigue-critical applications on narrow-body programs sustain demand for high-strength plate with established damage tolerance credentials.
- FAA 14 CFR Part 25 damage tolerance mandates:Airworthiness directives accelerate alloy substitution toward 7050-T7451 grades with superior crack-arrest properties.
- China CAAC CCAR-25 reciprocity negotiations:Expanding type certification alignment opens qualification pathways for Western suppliers into COMAC supply chains.
Market Restraints
- Primary aluminium ingot cost volatility:Smelter energy costs and alumina supply disruptions transmit directly to plate pricing, compressing rolling margin buffers.
- European rolling capacity concentration:Three integrated mills control the majority of thick-plate output for Airbus fuselage contracts, creating single-source vulnerability.
- Carbon-fiber wing spar substitution:Boeing 787 and Airbus A350 programs demonstrate composite displacement of 7000-series plate in primary structure.
Strategic Opportunities
- Aluminium-lithium density reduction:Airbus A321XLR wing rib applications validate 2195 and 2050 alloys for next-generation single-aisle weight targets.
- India PLI scheme aerospace tier:Domestic rolling mill investments under production-linked incentives target import substitution for defence airframe programs.
- REACH hexavalent chromium phase-out:Chromate-free conversion coating development creates first-mover advantage in European surface treatment qualification.
Industry Challenges
- Heat treatment furnace certification backlog:Age-hardening process validation for new alloy temper designs extends OEM approval timelines by 18-24 months.
- Ultrasonic inspection technician scarcity:Non-destructive testing capacity constraints limit plate throughput at peak aerospace build rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Aluminium Plate Market |
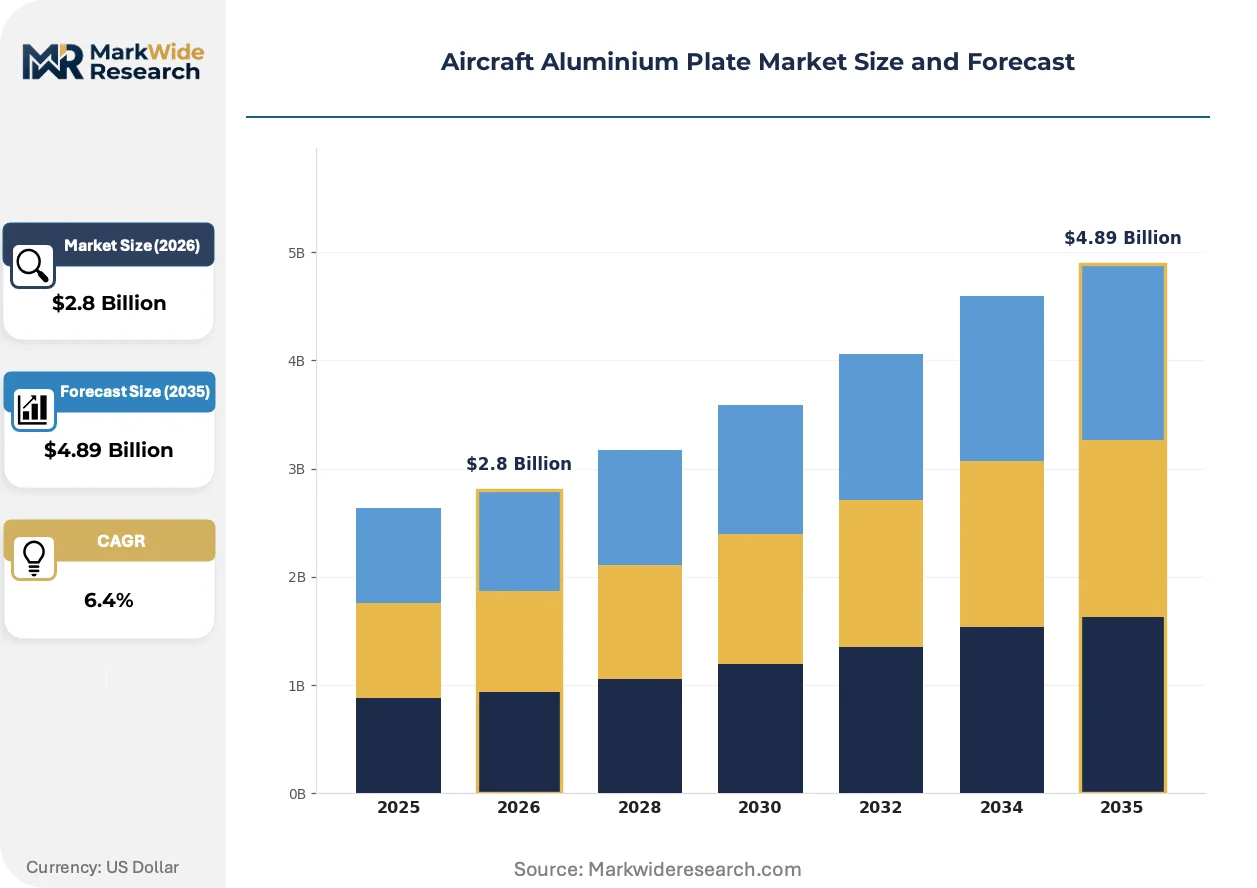
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminium-Lithium, 2000 Series, 6000 Series, 7000 Series, 5000 Series Technology: Heat Treatment, Cold Rolling, Anodizing, Cladding, Stretching Application: Fuselage Panels, Wing Structures, Engine Components, Landing Gear, Cargo Hold End User: Airframe Manufactures, Aero Engine Producers, Component Assemblers, Maintenance Providers |
| Companies Covered | Constellium, Alcoa, Kaiser Aluminum, Aleris, Novelis, Arconic, Hulamin, AMAG, Kobelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Aluminium Plate Market Trends and Innovations
Digital thread integration across melting, rolling, and heat treatment operations is compressing process variability and enabling lot-traceable mechanical property certification. Material informatics and in-line sensor networks are reshaping how plate suppliers demonstrate conformance to airframe OEM specifications.
Machine learning-based predictive metallurgy is digitizing grain structure control in continuous casting operations. Alcoa and Constellium deploy neural networks to forecast 7050-T7451 yield strength from real-time thermocouple data, reducing downstream mechanical testing frequency. The technology is digitizing quality assurance workflows and accelerating release-to-ship timelines for fuselage frame contracts.
EASA CS-25 amendments on damage tolerance and the EU Green Deal carbon border adjustment mechanism are tightening alloy qualification and embodied carbon documentation requirements. Plate suppliers must now submit life-cycle assessment data alongside mechanical test reports for new temper approvals. European rolling mills face the steepest compliance burden as CBAM phase-in exposes primary metal carbon intensity to tariff adjustments.
Airframe OEMs are consolidating qualified supplier lists and demanding direct mill relationships rather than distributor intermediation for critical 7000-series plate. Boeing and Airbus procurement teams now specify heat lot traceability to cast house origin, bypassing traditional aerospace metal service centers. This concentration is most visible in United States and French supply chains where final assembly line proximity dictates logistics optimization.
Aircraft Aluminium Plate Market Segmentation
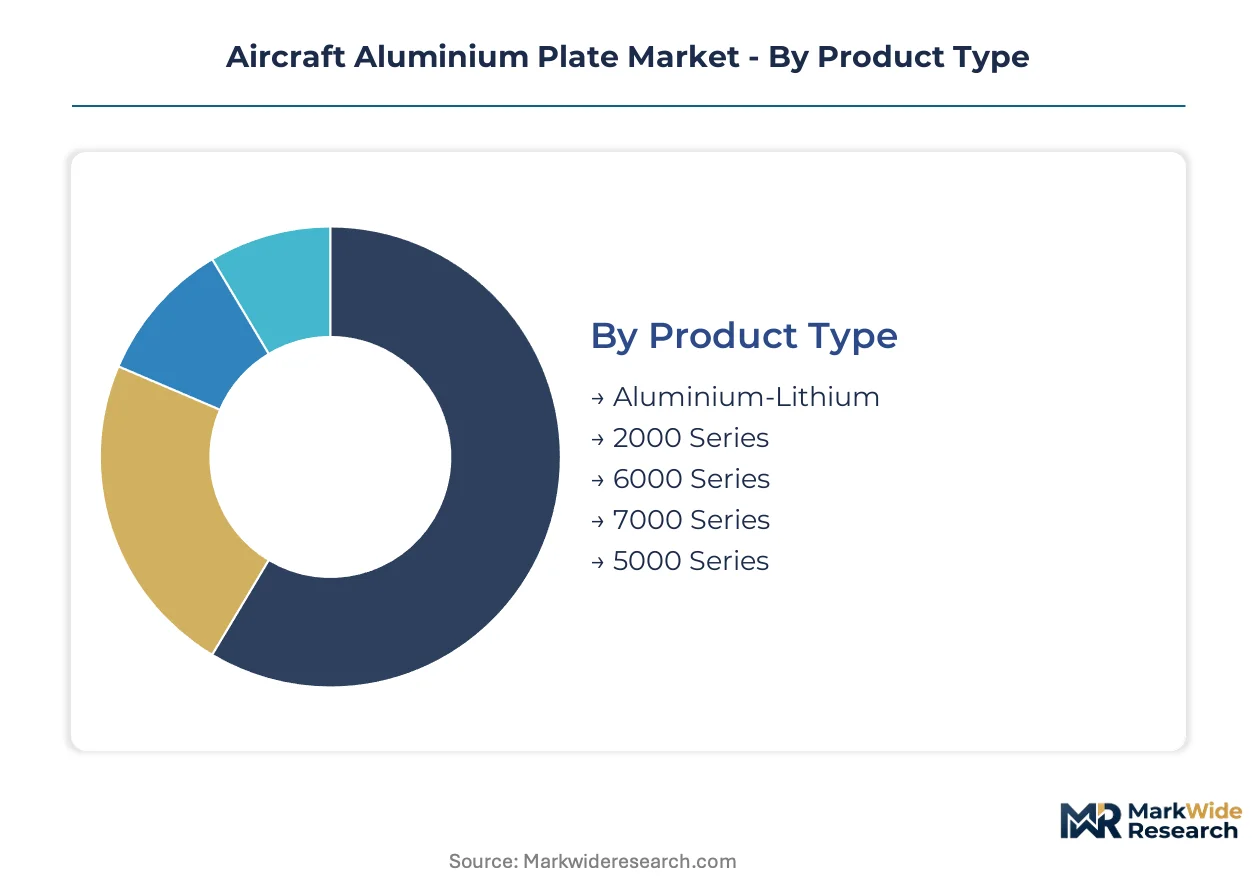
Aircraft aluminium plate segmentation reveals how alloy chemistry, forming technology, and airframe application intersect to determine supplier qualification pathways. OEM procurement teams segment supply pools by damage tolerance credentials and heat treatment capability rather than commodity metallurgy alone.
Product Type:
Mature high-strength alloys anchor current production while emerging lightweight chemistries reshape next-generation platform specifications.
- 7000 Series:High-strength zinc-magnesium-copper alloys such as 7075-T6 and 7050-T7451 deliver superior specific strength for wing spars and landing gear fittings. Demand concentrates in United States and France where Boeing and Airbus final assembly lines require damage-tolerant plate with established crack-arrest properties under FAA and EASA certification frameworks.
- Aluminium-Lithium:Copper-lithium additions reduce density by 8-10% versus conventional alloys while maintaining stiffness. Airbus A321XLR wing rib applications in France validate 2195 and 2050 alloys as OEMs pursue single-aisle weight targets; COMAC programs in China are expanding qualification pathways for Western suppliers.
- 2000 Series:Copper-dominated alloys such as 2024-T3 provide fatigue resistance for wing skins on narrow-body programs.
- 6000 Series:Silicon-magnesium chemistry offers moderate strength with excellent corrosion resistance and formability for fuselage applications.
- 5000 Series:Magnesium-bearing alloys deliver weldability and marine-grade corrosion resistance for non-structural airframe elements.
7000 Series handles the majority of throughput; Aluminium-Lithium is the fastest mover on share.
Technology:
Process value-add concentrates in thermal treatment steps where capital intensity creates supplier differentiation.
- Heat Treatment:Solution heat treatment, quenching, and artificial aging control yield strength and fracture toughness in 7000-series plate. Stretch forming and age hardening consume significant furnace capacity; EASA CS-25 damage tolerance amendments extend validation timelines for new temper designs.
- Cladding:Roll-bonded pure aluminium layers protect 2000-series and 7000-series substrates from galvanic corrosion in fuselage applications. REACH hexavalent chromium restrictions in Europe drive chromate-free conversion coating development, reshaping pretreatment investments for suppliers serving Airbus supply chains.
- Cold Rolling:Thickness reduction below recrystallization temperature refines grain structure and surface finish for tight-tolerance wing skin specifications.
- Anodizing:Electrochemical oxide layer formation enhances wear resistance and paint adhesion for exterior airframe components.
- Stretching:Post-quench mechanical stretching relieves residual stresses and improves dimensional stability in thick plate for machined structural fittings.
Heat Treatment commands the dominant share of process margin; Cladding is gaining share fastest amid regulatory chemistry transitions.
Application:
Structural criticality determines alloy selection and supplier qualification tier.
- Wing Structures:Spars, ribs, and skins demand high-strength 7000-series and 2000-series plate with damage tolerance certification. Boeing 787 and Airbus A350 composite wing boxes have displaced primary aluminium in wide-body platforms, compressing addressable volume to narrow-body and regional jet programs.
- Fuselage Panels:Circumferential frames and longitudinal stringers utilize 6000-series and 7000-series plate for pressurized cabin structures. Airbus A320-family production in France and Germany sustains rolling mill throughput at European suppliers.
- Landing Gear:Forged and machined 7000-series plate provides high-strength fittings for main and nose gear assemblies.
- Engine Components:Nacelle structures and thrust reverser components require heat-resistant alloys with specific stiffness characteristics.
- Cargo Hold:Floor beams and liner panels utilize lower-strength 5000-series and 6000-series plate with cost-optimized specifications.
Wing Structures retains the largest qualified supplier base despite composite substitution; Fuselage Panels is expanding fastest with single-aisle production rates.
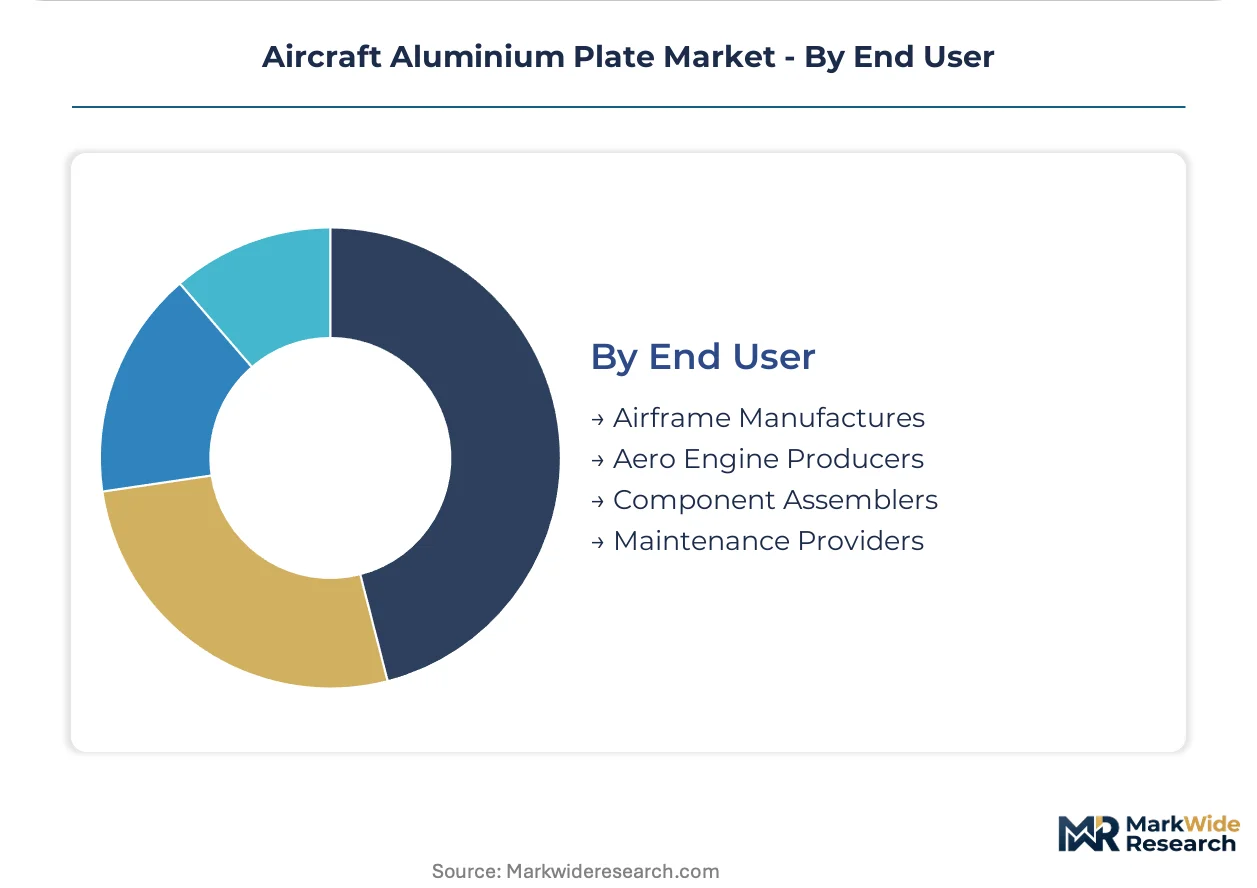
End User:
Procurement authority is consolidating at airframe OEMs while maintenance channels fragment across distributed MRO networks.
- Airframe Manufacturers:Boeing, Airbus, and COMAC specify heat lot traceability to cast house origin, bypassing traditional aerospace metal service centers. Direct mill relationships now dominate 7000-series plate procurement for A320 and 737 programs in United States, France, and China.
- Component Assemblers:Tier-1 aerostructures suppliers machine plate into wing ribs, bulkheads, and frame segments for JIT delivery to final assembly lines. Constellium and Alcoa maintain dedicated supply agreements with Spirit AeroSystems and GKN Aerospace.
- Aero Engine Producers:Pratt & Whitney and Rolls-Royce procure specialized plate for nacelle and pylon structures with distinct metallurgical specifications.
- Maintenance Providers:MRO operators source replacement plate for damage repair and modification programs through distributor channels with less stringent traceability requirements.
Airframe Manufacturers direct the majority of qualified volume; Component Assemblers is climbing fastest as OEMs outsource machined subassemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aircraft aluminium plate trade flows reveal a structural deficit in Asia-Pacific final assembly capacity against concentrated European and North American rolling mill output. Import dependency patterns reshape supplier qualification strategies across major aerospace manufacturing clusters.
United States
Boeing 737 MAX and 777X production lines in Washington and South Carolina sustain demand for 7000-series plate with FAA 14 CFR Part 25 damage tolerance certification. The FAA mandates strict alloy qualification timelines for new temper designs. Alcoa operates integrated smelter-to-plate facilities in Tennessee and Texas, anchoring domestic primary metal supply for wing spar contracts.
France
Airbus A320-family final assembly in Toulouse and Hamburg-bound fuselage sections drive premium plate consumption for narrow-body programs. EASA CS-25 amendments tighten damage tolerance documentation requirements for European suppliers. Constellium leverages rolling capacity in Issoire to serve Airbus fuselage frame contracts with dedicated supply agreements.
China
COMAC C919 production ramp-up and ARJ21 regional jet programs expand addressable volume for qualified Western suppliers. CAAC CCAR-25 reciprocity negotiations with FAA and EASA determine alloy import pathways. Shanghai and Tianjin final assembly clusters concentrate demand for 7050-T7451 grade plate in wing and landing gear applications.
Germany
Airbus wing component manufacturing in Bremen and Augsburg generates specialized demand for 2024-T3 fatigue-critical plate. EU Green Deal carbon border adjustment mechanisms expose primary aluminium imports to tariff adjustments based on embodied carbon documentation. Bavarian and Lower Saxony aerostructures suppliers source heat-treated plate through direct mill relationships bypassing distributors.
Japan
Boeing 787 subcontractor networks and domestic MRJ program sustain niche demand for high-strength plate. METI industrial standards align with FAA damage tolerance frameworks for alloy qualification. Nagoya aerospace cluster imports 7000-series plate through qualified supplier channels with heat lot traceability to North American cast house origins.
Aircraft Aluminium Plate Market Competitive Landscape
On the supply side, the industry is consolidated around a handful of integrated primary aluminium producers with captive aerospace rolling capacity. Three strategic archetypes dominate: vertically integrated smelter-to-plate operators, specialized heat treatment specialists, and regional rolling mills serving single OEM programs. Competitive moves center on direct mill relationship cultivation with Boeing and Airbus procurement teams, plus furnace capacity expansion to compress OEM approval timelines for new alloy tempers.
Within the integrated primary metal tier, Constellium and Alcoa exemplify the smelter-to-plate archetype with European and North American rolling capacity respectively. Kaiser Aluminum occupies a position among specialized heat treatment specialists focused on 7000-series temper optimization for wing rib applications. These three anchors demonstrate how supplier qualification concentrates around damage tolerance credentials and heat lot traceability capabilities rather than commodity scale alone.
| Leading Market Players |
|---|
| Constellium |
| Alcoa |
| Kaiser Aluminum |
| Aleris |
| Novelis |
| Arconic |
| Hulamin |
| AMAG |
| Kobelco |
| Others |
Pricing and Supply Chain Analysis
Issoire's European rolling capacity anchors premium plate pricing for Airbus fuselage contracts, with Constellium's dedicated supply agreements creating concentrated pricing power against fragmented tier-1 aerostructures buyers. Alcoa's Tennessee smelter-to-plate integration in the United States reinforces this geographic bifurcation, compressing margin buffers for distributors excluded from direct mill relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with heat lot traceability premiums. Price differentiation separates damage-tolerant 7050-T7451 grades certified under FAA 14 CFR Part 25 from standard 6000-series fuselage specifications, with certification tier and volume scale as primary levers. Pricing pressure stems from primary aluminium ingot cost volatility transmitting through alumina supply disruptions. Component assemblers exhibit highest price sensitivity due to JIT delivery penalties, while airframe manufacturers absorb premiums for qualified supplier consolidation.
Supply Chain Analysis
Primary aluminium feedstock draws from smelter complexes in the United States, Canada, and Russia, with alumina refining concentrated in Australia and Brazil. Bauxite ore and petroleum coke anodes constitute critical input dependencies alongside rolling mill furnace capacity. Single-source vulnerability pervades European thick-plate output where three integrated mills control Airbus fuselage contracts. Distribution runs through direct mill relationships for 7000-series plate, bypassing traditional aerospace metal service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where COMAC's C919 production ramp demands interoperability with FAA-EASA qualification pathways, reshaping supplier ecosystem entry rules.
For Market Incumbents: Harden damage tolerance certification moats by accelerating heat treatment furnace capacity expansion in France and the United States before CAAC reciprocity negotiations conclude. Deepen backward integration into primary aluminium smelting to offset carbon border adjustment exposure under EU Green Deal frameworks. Composite wing spar substitution in wide-body programs remains the core threat compressing addressable volume. For New Entrants and Emerging Players: Build out chromate-free conversion coating capabilities to capture REACH phase-out first-mover advantage in European surface treatment qualification. India's PLI scheme aerospace tier offers the most penetrable geography for import substitution into defence airframe programs. Target component assembler relationships rather than direct OEM procurement, leveraging less stringent traceability requirements in MRO channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because airframe OEM procurement teams are compressing qualified supplier lists and demanding cast house origin traceability that only integrated smelter-to-plate operators can deliver. Acquisition targets should display captive 7000-series heat treatment capacity and established EASA CS-25 temper approvals. Watch for CAAC-FAA reciprocity agreement announcements as the signal for Western supplier volume inflection into COMAC supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Treatment Furnace Certification | Age-hardening process validation accelerates OEM approval timelines for new alloy temper designs. |
| Chromate-Free Conversion Coating Development | REACH hexavalent chromium phase-out creates qualification barriers for European Airbus supply chains. |
| Direct Mill Relationship Cultivation | Boeing and Airbus procurement teams now specify heat lot traceability bypassing metal service centers. |
| Aluminium-Lithium Alloy Qualification | Airbus A321XLR wing rib applications validate density reduction pathways for next-generation single-aisle programs. |
| CAAC Reciprocity Pathway Investment | Expanding type certification alignment opens Western supplier qualification into COMAC C919 production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating rolling mill operations directors, Airbus and Boeing procurement leads, heat treatment process engineers, and tier-1 aerostructures supplier quality managers. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment documentation, COMAC type certification records, customs trade data for aluminium plate shipments, and SEC 10-K disclosures from integrated primary metal producers. Bottom-up alloy-grade volume estimates and top-down aerospace build rate projections were triangulated to constrain forecast variance.
Calibration against historical damage tolerance adoption curves and fleet renewal cycle timing anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated alloy chemistry tier, heat treatment capability, airframe application criticality, and end-user procurement authority. CAGRs were derived from rolling mill capacity utilization trends and OEM platform delivery schedules. Forecast inputs included primary aluminium LME price volatility bands and ultrasonic inspection technician pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed rolling mill investors or accelerated composite wing adoption by airframe OEMs would shift outcomes. Cross-checking against Airbus and Boeing published delivery guidance and CAAC certification timeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market