
 Global AFP/ATL Machines Market | 2026-2036
Global AFP/ATL Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global AFP/ATL Machines Market Analysis
A shift from single-source to multi-source equipment procurement is recalibrating how tier-one aerostructures suppliers manage capital deployment. Mikrosam leverages its European installed base to sustain long-term service contracts with Airbus-tier suppliers. Electroimpact Inc. anchors North American demand through its dominance in large-scale wing assembly systems for Boeing programs. Coriolis Composites differentiates via compact robotic AFP cells targeting space-launch vehicle producers.
Automated Fiber Placement and Automated Tape Laying systems deposit thermoset or thermoplastic composite tapes onto molds with precision measured in fractions of a millimeter, producing aerostructures that replace heavier metallic assemblies. Automated Fiber Placement equipment commands the largest installed base due to its suitability for complex double-curved geometries in fuselage sections and inlet ducts. Thermoplastic technology represents the fastest-expanding segment as out-of-autoclave processing cycles promise throughput gains for high-rate commercial aircraft production.
FAA airworthiness standards and EASA CS-25 certification requirements compel manufacturers to validate process repeatability and traceability in AFP/ATL operations. ISO standards for automated composite manufacturing further shape equipment specifications and supplier qualification protocols. Stakeholders must monitor how evolving thermoplastic welding standards and sustainability-linked procurement criteria reshape equipment specifications and factory certification timelines.
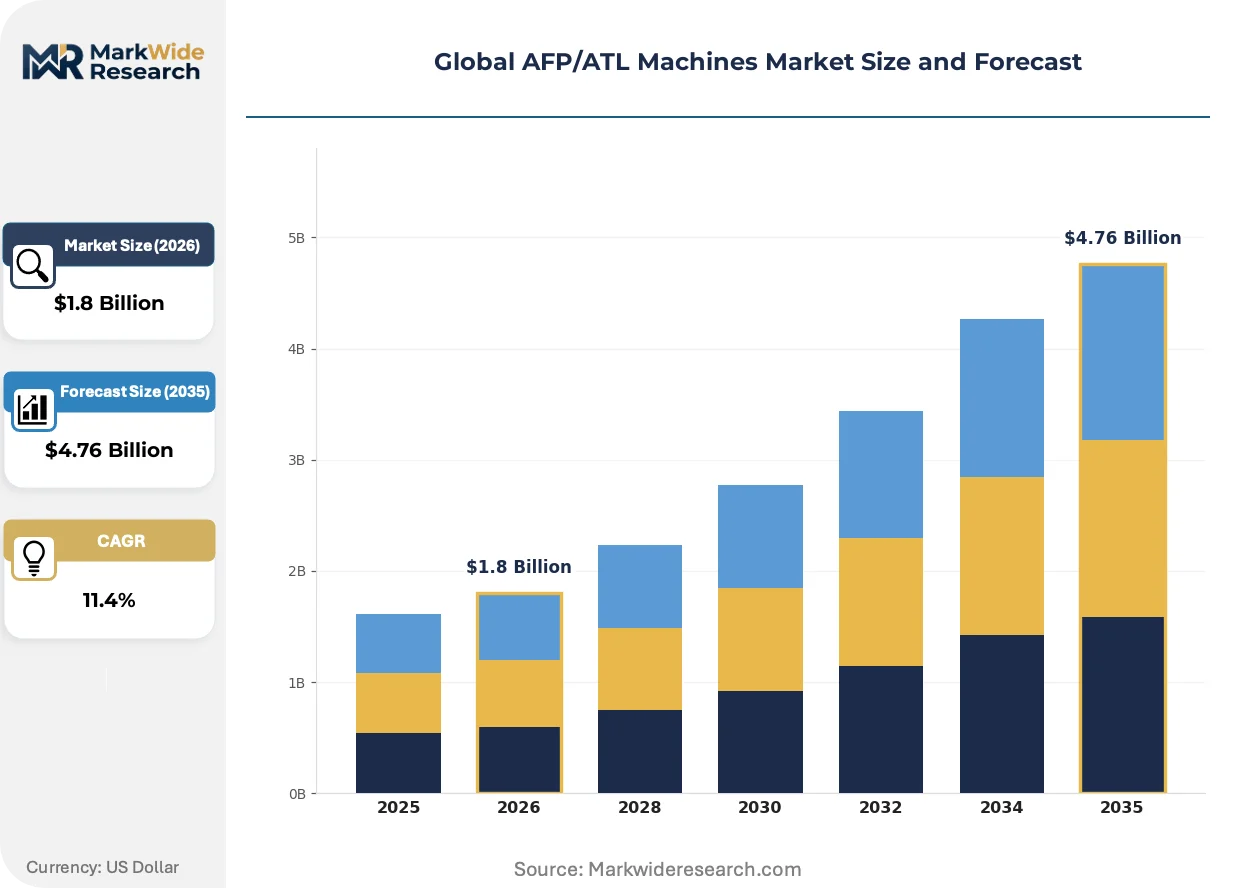
Market Dynamics
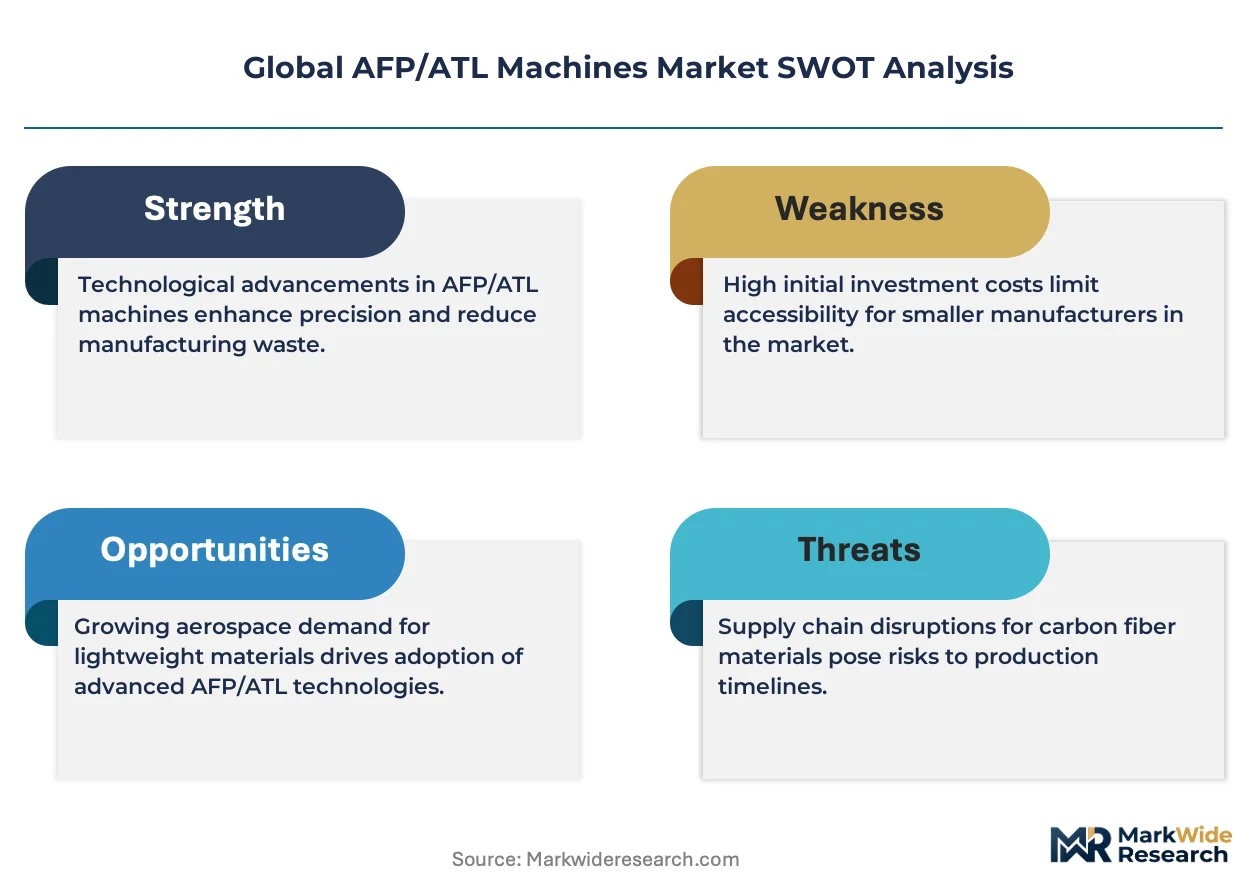
Thermoplastic AFP technology is compressing processing cycles and forcing equipment suppliers to reengineer heat control systems, reshaping capital allocation across tier-one aerostructures programs.
Growth Catalysts
- FAA airworthiness directives:Mandates for process traceability in composite manufacturing are compelling aerospace suppliers to upgrade legacy ATL systems with integrated inspection modules.
- Thermoplastic out-of-autoclave processing:Elimination of autoclave bottlenecks is accelerating throughput for high-rate single-aisle aircraft production lines.
- Germany's composite cluster density:Concentrated Airbus-tier supply chains in Hamburg and Munich sustain continuous equipment refresh cycles among Mittelstand tooling specialists.
Market Restraints
- Carbon fiber prepreg cost volatility:Raw material price swings compress margins for ATL machine operators dependent on aerospace-grade tape supply.
- European equipment supply concentration:German and French system builders control critical gantry and robotic head technologies, creating single-source vulnerability for Asian entrants.
- ISO 14692 standard gaps:Incomplete harmonization between thermoplastic welding protocols delays factory certification timelines for multi-material fuselage programs.
Strategic Opportunities
- Urban air mobility airframes:Electric vertical take-off vehicle manufacturers in China and the United States require compact AFP cells for prototype-to-production scaling.
- EU Green Deal sustainable manufacturing incentives:Carbon footprint reduction mandates favor thermoplastic recycling compatibility in next-generation equipment specifications.
- Convergence of AFP with automated inspection:Real-time thermography integration creates premium positioning for systems capable of in-situ defect detection.
Industry Challenges
- Multi-axis robotic programming expertise:Shortage of operators capable of simultaneous 7-axis path optimization constrains equipment utilization rates at new installations.
- EASA CS-25 certification timelines:Extended validation periods for novel thermoplastic bond lines delay revenue recognition on greenfield aerospace programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AFP/ATL Machines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Fiber Placement, Automated Tape Laying, Hybrid Systems, Others End User: Aerospace, Automotive, Marine, Industrial Technology: Continuous Fiber, Interleaved Fiber, Thermoplastic, Thermosetting Application: Structural Components, Interior Parts, Exterior Parts, Tooling |
| Companies Covered | Mikrosam, Accudyne Systems, Inc., Electroimpact Inc., Fives Group, M.Torres Diseños Industriales S.A.U, Ingersoll Machine Tools Inc., Automated Dynamics, Coriolis Composites, Addcomposites Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AFP/ATL Machines Market Emerging Trajectories
Digital thread integration and in-process sensing capabilities are compressing the gap between deposition and quality assurance, altering how manufacturers specify AFP/ATL capital equipment.
Continuous fiber 3D printing is rewriting the boundary between additive manufacturing and automated fiber placement. Space-launch vehicle producers in the United States are piloting hybrid systems that deposit thermoplastic rings with AFP precision at deposition rates exceeding conventional tape laying. This convergence is collapsing the distinction between prototyping and production tooling in satellite bus manufacturing.
REACH regulation amendments on per- and polyfluoroalkyl substances are restricting release agent chemistries used in thermoset AFP operations. European aerostructures suppliers must reformulate mold preparation protocols or face supply chain disruption for export-bound components. The regulatory pressure is accelerating adoption of laser-assisted thermoplastic deposition that eliminates consumable release systems entirely.
Multi-year service contracts with guaranteed uptime clauses are displacing traditional equipment purchase models among Boeing and Airbus tier-one suppliers. Risk-sharing arrangements now bundle preventive maintenance, software updates, and consumables into per-flight-hour equivalent pricing. This shift concentrates aftermarket revenue with original equipment manufacturers possessing embedded installed base intelligence.
Global AFP/ATL Machines Market Segmentation
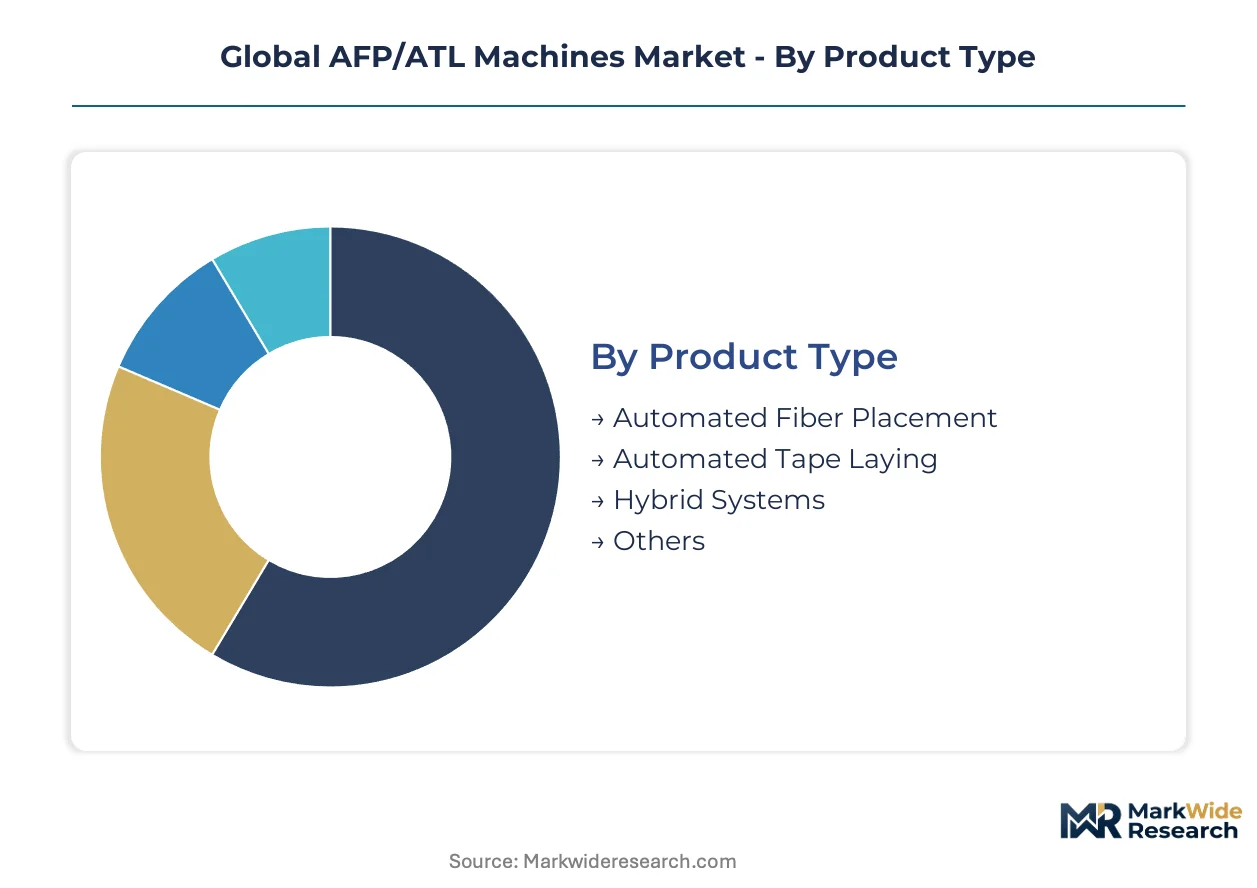
Equipment buyers in the AFP/ATL market face divergent capital allocation logic based on production scale, geometry complexity, and material chemistry. Segmentation reveals how suppliers align gantry specifications, heat control architectures, and software modules to distinct manufacturing workflows across aerospace, automotive, and adjacent verticals.
Product Type:
Buyers differentiate by part complexity tolerance and throughput requirements rather than budget tiers alone.
- Automated Fiber Placement:Multi-axis robotic heads deposit narrow tows onto double-curved molds with sub-millimeter precision. Demand concentrates in fuselage sections and inlet ducts for commercial aircraft programs in Germany and the United States, where FAA and EASA certification protocols mandate process traceability.
- Automated Tape Laying:Wide-tape deposition systems excel in flat-to-moderately-curved wing skins and control surfaces. Automotive battery enclosure manufacturers in China are adopting adapted ATL platforms for high-volume thermoplastic processing, driven by MIIT new energy vehicle production quotas.
- Hybrid Systems:Configurable platforms switch between AFP and ATL modes within single production cells. Space-launch vehicle producers in the United States pilot these for satellite bus manufacturing.
- Others:Specialized gantry configurations for wind turbine blade root sections and rail car body shells.
Automated Fiber Placement leads volumes today; Hybrid Systems are gaining share fastest.
End User:
Customer procurement patterns split between long-cycle aerospace qualification and rapid-scaling automotive deployment.
- Aerospace:Tier-one suppliers to Boeing and Airbus operate the largest installed base, with equipment refresh cycles tied to new aircraft program launches. Hamburg and Munich clusters sustain continuous demand from Airbus-tier Mittelstand tooling specialists.
- Automotive:Electric vehicle platforms drive demand for compact thermoplastic cells capable of battery tray and body-in-white component production. Chinese OEMs are expanding fastest.
- Marine:Yacht hull and superstructure manufacturers in Italy and the Netherlands adopt AFP for large-surface carbon fiber laminates.
- Industrial:Pressure vessel and robotics arm producers represent emerging demand pockets with shorter qualification timelines.
Aerospace dominates capital deployed; Automotive is expanding most quickly.
Technology:
Material chemistry selection determines heat source architecture, processing cycle duration, and factory certification pathway.
- Thermoplastic:Laser- and ultrasonic-assisted welding enables out-of-autoclave processing with sub-ten-minute cycle times. EU Green Deal carbon footprint mandates favor thermoplastic recycling compatibility in next-generation equipment specifications.
- Thermosetting:Established epoxy and BMI prepreg systems retain dominance in wing and fuselage primary structures. REACH amendments on per- and polyfluoroalkyl substances are restricting release agent chemistries in European operations.
- Continuous Fiber:Unidirectional tape architectures maximize specific strength for primary load-bearing applications.
- Interleaved Fiber:Hybrid tow configurations improve damage tolerance for impact-critical components.
Thermosetting retains the largest installed base; Thermoplastic is climbing the fastest.
Application:
Value capture varies sharply between flight-critical primary structures and non-structural interior components.
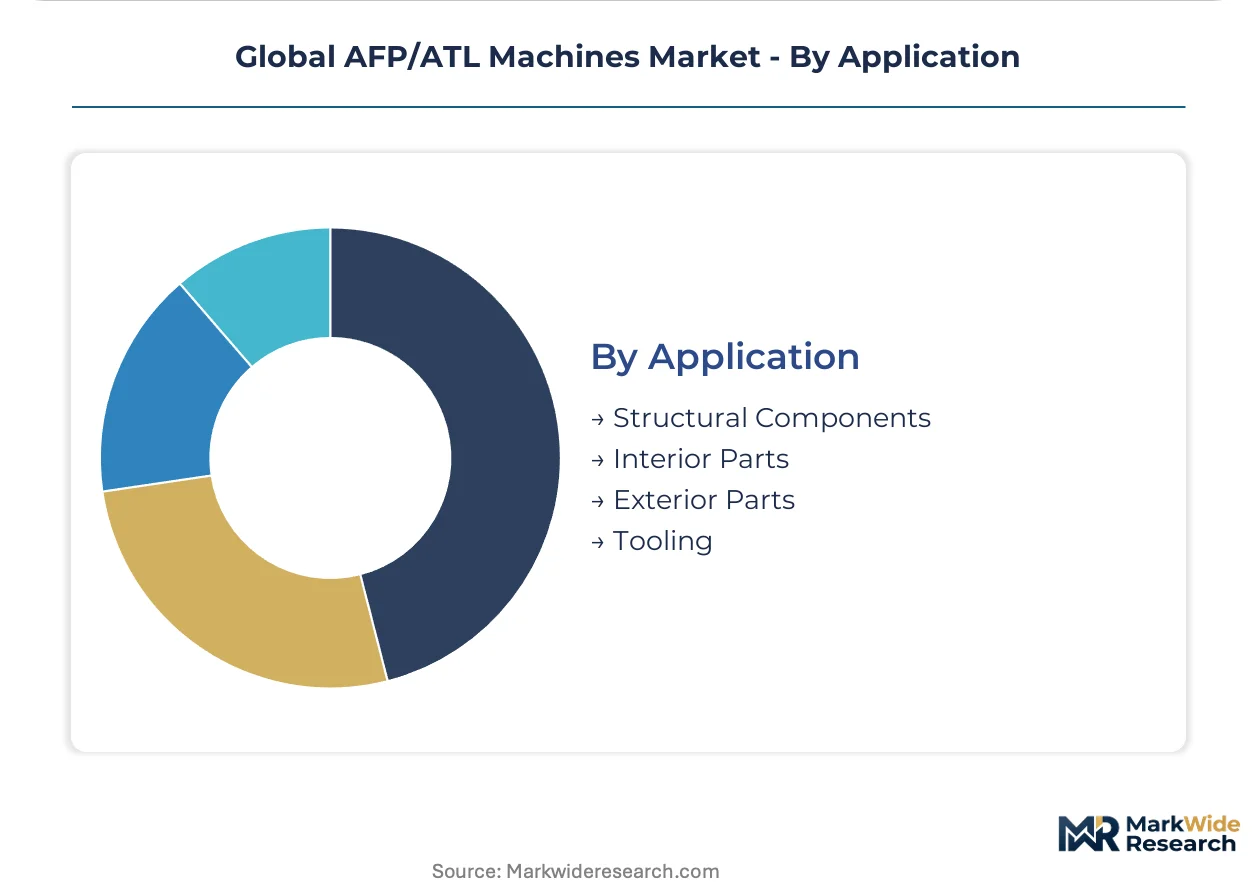
- Structural Components:Wing spars, fuselage barrels, and empennage assemblies command premium equipment specifications with integrated inspection modules. FAA airworthiness directives mandate process traceability for these applications.
- Tooling:Composite layup mandrels and assembly fixtures represent high-margin aftermarket demand with shorter sales cycles.
- Exterior Parts:Fairings, radomes, and access panels utilize mid-tier ATL systems with reduced axis complexity.
- Interior Parts:Sidewall panels, overhead bins, and galley structures tolerate lower-precision deposition with faster payback periods.
Structural Components absorb the majority of new capital; Tooling is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg and Munich anchor the densest concentration of AFP/ATL demand, with Airbus-tier supply chains sustaining continuous equipment refresh cycles among Mittelstand tooling specialists.
United States
Boeing program launches and space-launch vehicle production drive gantry system procurement. FAA airworthiness directives mandate integrated inspection modules for process traceability. Seattle and Charleston clusters host the largest installed base of large-scale wing assembly systems.
Germany
Airbus fuselage programs and automotive battery enclosure manufacturing sustain dual-use equipment demand. EU Green Deal carbon footprint mandates favor thermoplastic recycling compatibility in factory specifications. Hamburg and Munich aerostructures corridors concentrate Mittelstand tooling specialists with continuous capital deployment.
China
Commercial aircraft program ramp-ups and electric vehicle platform scaling compress equipment procurement timelines. MIIT new energy vehicle production quotas accelerate compact thermoplastic cell adoption. Shanghai and Xi'an manufacturing bases expand automated fiber placement capacity for indigenous narrow-body programs.
France
Space-launch vehicle producers and satellite bus manufacturers pilot hybrid AFP/ATL configurations. EASA CS-25 certification requirements extend validation periods for novel thermoplastic bond lines. Toulouse and Bordeaux aerospace clusters sustain demand for compact robotic cells with sub-millimeter precision.
Japan
Industrial robotics arm producers and pressure vessel manufacturers represent emerging demand pockets with shorter qualification timelines. METI advanced manufacturing initiatives support carbon fiber composite adoption in transportation applications. Nagoya and Osaka industrial corridors host precision equipment suppliers integrating AFP with automated inspection.
Global AFP/ATL Machines Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue compact robotic configurations for urban air mobility and satellite manufacturing. The vendor base concentrates among European gantry specialists and North American large-scale system builders, with Asian entrants gaining traction in adapted automotive platforms. Two strategic archetypes dominate: integrated aerospace system suppliers bundling equipment with multi-year service contracts, and modular cell specialists targeting rapid-scaling prototype-to-production workflows. Competitive moves center on risk-sharing arrangements with guaranteed uptime clauses and geographic expansion through local assembly partnerships.
Among European-based fabricators, Mikrosam and Coriolis Composites exemplify contrasting positioning within the integrated supplier archetype. Electroimpact Inc. anchors North American demand through its concentration in large-scale wing assembly configurations. These three occupy positions that reflect the market's bifurcation between gantry-scale aerospace systems and compact robotic cells.
| Leading Market Players |
|---|
| Mikrosam |
| Accudyne Systems, Inc. |
| Electroimpact Inc. |
| Fives Group |
| M.Torres Diseños Industriales S.A.U |
| Ingersoll Machine Tools Inc. |
| Automated Dynamics |
| Coriolis Composites |
| Addcomposites Oy |
| Others |
Supply Flow & Price Mechanics
Carbon fiber prepreg spot price volatility cascades through AFP/ATL equipment supply chains, compressing margins for aerospace-grade tape-dependent operators while amplifying pricing power for integrated thermoplastic system builders in Germany and the United States.
Pricing Analysis
Input-cost pass-through from aerospace-grade carbon fiber prepreg suppliers determines equipment pricing stratification across the market. Three-tier pricing structure across premium, standard, and economy levels separates gantry-scale aerospace systems with integrated inspection modules from compact robotic cells for automotive prototyping. Certification grade under FAA airworthiness directives and EASA CS-25 requirements commands substantial premiums over industrial-grade configurations. Cost compression in mid-tier ATL platforms is intensifying because raw material price swings constrain operator margins. Automotive battery enclosure manufacturers in China exhibit highest price sensitivity, while tier-one Boeing and Airbus suppliers prioritize guaranteed uptime clauses over unit economics.
Supply Chain Analysis
Workforce availability constraints in Stuttgart, Toulouse, and Seattle manufacturing corridors limit production scaling for precision gantry and robotic head assemblies. German and French system builders anchor supply for critical motion control components, while Chinese fabricators expand capacity for adapted automotive thermoplastic cells. Aerospace-grade carbon fiber prepreg, high-precision linear motion systems, and laser-assisted welding modules constitute core input dependencies. Single-source vulnerability pervades European gantry technology, where Mittelstand specialists control proprietary multi-axis path optimization software. Distribution runs through direct equipment sales bundled with multi-year service contracts for aerospace tier-ones, supplemented by regional assembly partnerships for rapid-scaling automotive entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AFP/ATL market functions as a regulatory compounder, where FAA airworthiness directives and EASA certification requirements continuously refresh equipment demand across aerospace supply chains.
For Market Incumbents: Lock in long-term service contracts with guaranteed uptime clauses among Boeing and Airbus tier-one suppliers before emerging modular cell specialists capture urban air mobility prototype-to-production workflows. Deepen backward integration into laser-assisted thermoplastic welding module production to offset European single-source vulnerability in heat control architectures. Prioritize embedded installed base intelligence as the defensive moat against risk-sharing pricing models that concentrate aftermarket revenue with original equipment manufacturers possessing direct operational data feeds. For New Entrants and Emerging Players: Urban air mobility airframe manufacturers in China and the United States represent the most penetrable demand pocket, requiring compact robotic AFP cells for rapid prototype-to-production scaling. Satellite bus manufacturing for space-launch vehicle producers offers secondary white-space entry, where hybrid AFP/ATL configurations pilot novel thermoplastic ring deposition. Pursue go-to-market alignment with automotive battery enclosure specialists in China seeking adapted thermoplastic platforms under MIIT new energy vehicle production quotas. For Investors and Strategic Acquirers: Asymmetric upside sits with modular cell specialists possessing compact robotic configurations and rapid-scaling software architectures for prototype-to-production workflows. Long-term viability hinges on sustained regulatory pressure from FAA and EASA mandating process traceability and thermoplastic welding standardization across commercial aircraft programs. Watch for EASA CS-25 certification timeline compression on novel thermoplastic bond lines as the inflection signal indicating mainstream adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Service Contract Expansion | Bundles preventive maintenance and software updates into per-flight-hour equivalent pricing for Airbus-tier suppliers. |
| Thermoplastic Welding Module Integration | Eliminates autoclave bottlenecks and enables sub-ten-minute cycle times for high-rate single-aisle production. |
| Urban Air Mobility Cell Development | Targets electric vertical take-off vehicle manufacturers in China and the United States with compact deposition systems. |
| Real-time Thermography Capability Addition | Creates premium positioning through in-situ defect detection converging AFP with automated inspection protocols. |
| Local Assembly Partnership Formation | Accelerates geographic expansion into Chinese automotive battery enclosure manufacturing corridors under MIIT quotas. |
Methodological Framework
Direct dialogue with equipment procurement directors at tier-one aerostructures suppliers, aftermarket service heads at gantry system manufacturers, composite process engineers at space-launch vehicle producers, and regulatory compliance officers at EASA and FAA field offices grounded qualitative assessment. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification documentation, ISO 14692 standard evolution records, and customs data on carbon fiber prepreg trade flows. Bottom-up equipment shipment tallies by configuration type and top-down aerospace program capital expenditure tracking were triangulated against supplier revenue disclosures.
Bottom-up modeling segmented the analysis window by product type, end-use vertical, material chemistry, and application criticality, with thermoplastic versus thermosetting technology splits receiving distinct heat-source architecture assumptions. Aerospace program launch timelines, automotive production quota trajectories, and regulatory certification pathway durations informed deployment velocity inputs. CAGRs were derived from equipment replacement cycle analysis tied to airframe program longevity and factory certification timeline compression.
Revisions become necessary when thermoplastic welding standard harmonization accelerates, carbon fiber prepreg supply disruptions materialize, or urban air mobility airframe programs achieve scaled production faster than baseline assumptions. Material deviation in EASA CS-25 validation periods or FAA airworthiness directive scope expansion warrants pause and re-evaluation of installed base refresh velocity projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerospace Superalloys Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market