
 North America Business Jet Market | 2026-2036
North America Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Business Jet Market Analytics
Buyer concentration across North American business aviation is broadening as fractional ownership platforms and charter aggregators fragment what was once a market dominated by traditional full-ownership models. Textron Aviation leverages its Beechcraft and Cessna portfolios to serve this expanding charter-operator segment with light and midsize platforms. Gulfstream Aerospace Corporation anchors the ultra-long-range category through its G700 and G800 programs, sustaining premium positioning with large-cabin interiors and transoceanic range. Bombardier Inc. competes directly in this upper tier with its Global family, differentiating through wing design and cabin altitude systems.
Business jets are fixed-wing turbine aircraft designed for private or corporate transport, typically operating at altitudes above 41,000 feet with pressurized cabins and ranges from 1,500 to 7,500 nautical miles depending on class. Primary commercial purpose centers on time-efficient point-to-point travel for executives, medical teams, and high-net-worth individuals who require schedule autonomy unavailable through commercial aviation. Light Jet and Ultra-Long-Range Jet categories capture divergent demand pools, with light platforms serving cost-sensitive charter operators and ultra-long-range aircraft commanding margin concentration among transcontinental private owners. Heavy Jet demand reflects replacement cycles in the U.S. corporate fleet, where cabin connectivity and fuel-efficient engine technology now dominate procurement criteria.
FAA certification standards under Part 25 airworthiness rules, combined with EPA aircraft engine emission guidelines and IRS bonus depreciation schedules, collectively shape fleet renewal timing and equipment specifications across the United States and Canada. Transport Canada Civil Aviation maintains aligned type certification reciprocity, while Mexico's DGAC operational standards influence cross-border charter economics. Stakeholders must monitor sustainable aviation fuel infrastructure buildout and state-level property tax treatment as these factors will determine operating cost trajectories and base-location decisions.
Market Dynamics
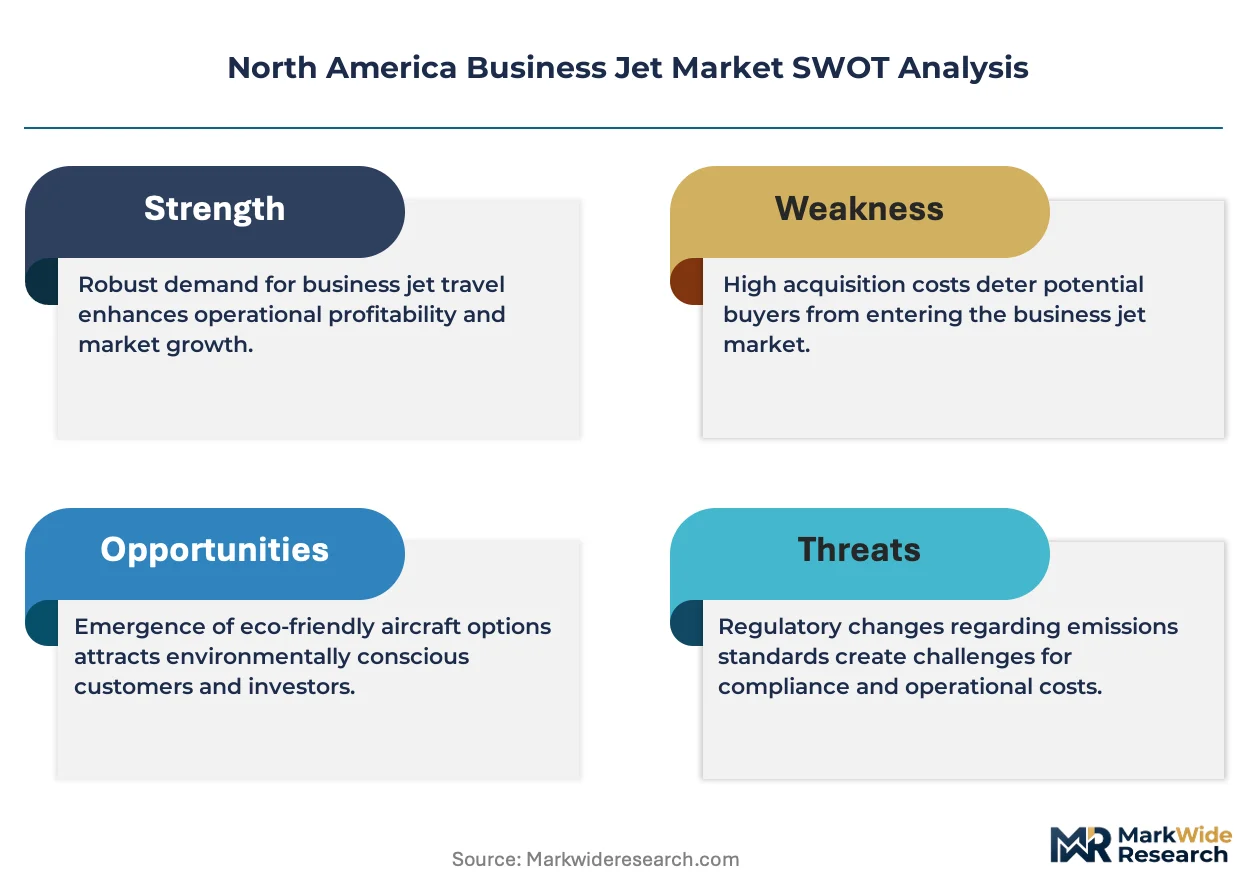
Fractional ownership platforms and charter aggregators are fragmenting traditional full-ownership concentration across North American business aviation, while FAA NextGen mandates and sustainable aviation fuel incentives force simultaneous fleet renewal and infrastructure investment.
Growth Catalysts
- FAA NextGen Mandates:Required avionics upgrades for airspace modernization are compressing replacement cycles for aging corporate fleets across the United States.
- State Tax Arbitrage:Texas and Florida hangar infrastructure combined with property tax exemptions is concentrating high-net-worth buyer registration in these jurisdictions.
- Sustainable Aviation Fuel Incentives:Federal production credits and state-level blending mandates are reshaping fuel procurement strategies for charter operators.
Market Restraints
- Pilot Labor Scarcity:Certified flight crew availability constrains fleet utilization rates for fractional programs and charter operators.
- Airframe Supply Concentration:Three OEMs control ultra-long-range platform production, creating order backlogs extending beyond thirty-six months.
- Jet-A Price Volatility:Refining capacity constraints and geopolitical supply disruptions compress operating margins for high-utilization fleets.
Strategic Opportunities
- Mexico Charter Liberalization:DGAC operational standard harmonization with FAA Part 135 rules enables cross-border fleet deployment from Texas bases.
- Electrified Ground Support:Battery-powered auxiliary power units and tow vehicles converge with airport sustainability mandates to reduce fixed-base operator emissions profiles.
- Empty-Leg Aggregation Platforms:Digital marketplaces for repositioning flights capture latent capacity and expand addressable demand among price-sensitive travelers.
Industry Challenges
- Airworthiness Certification Timelines:FAA Part 25 supplemental type certificate approvals for cabin connectivity retrofits extend project schedules.
- Maintenance Technician Pipeline:Airframe and powerplant certification programs face enrollment gaps relative to fleet age demographics.
- Legacy Avionics Integration:NextGen-compliant flight management systems require structural modifications incompatible with certain airframe vintages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Business Jet Market |
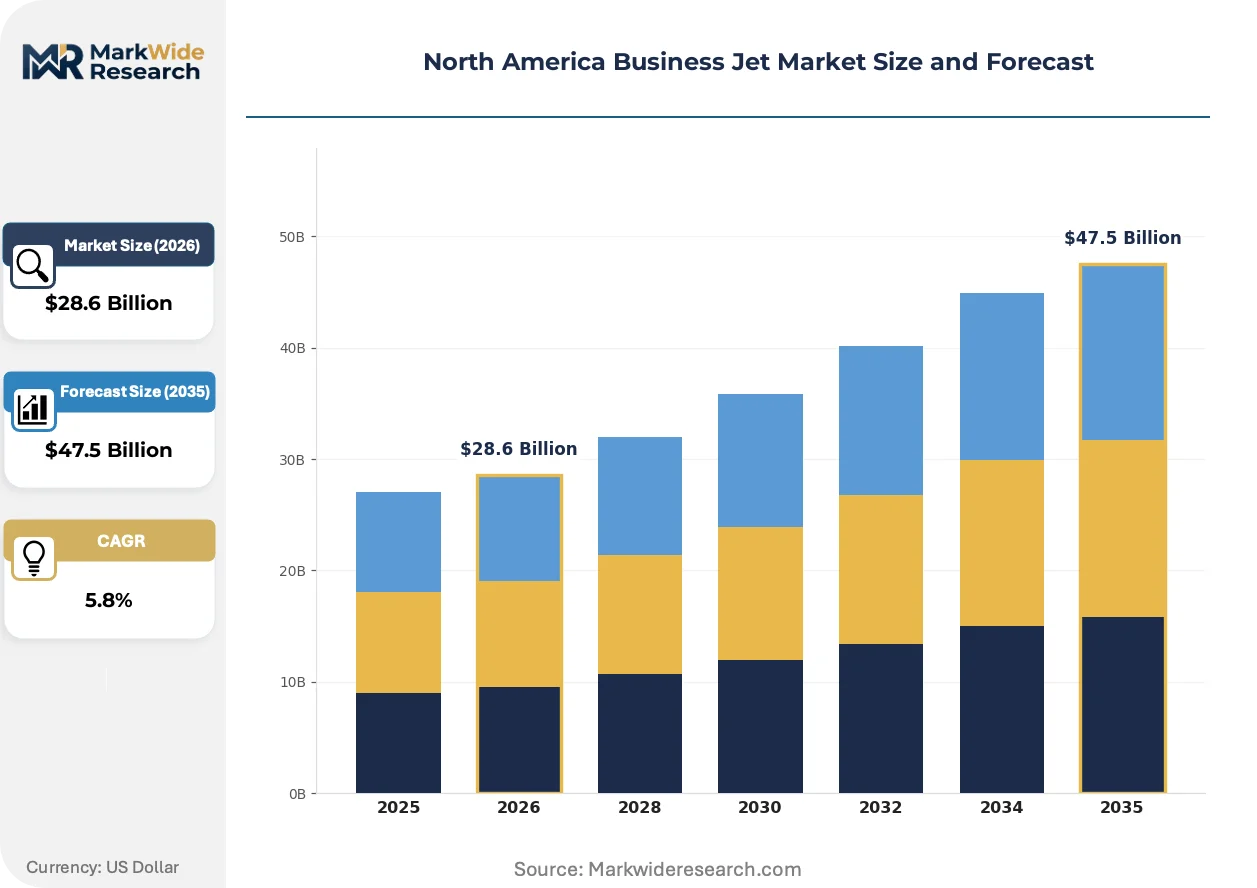
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Jet, Medium Jet, Heavy Jet, Ultra-Long-Range Jet End User: Private Owners, Corporations, Charter Operators, Government Agencies Application: Corporate Travel, Medical Evacuation, Cargo Transport, Personal Travel Technology: Advanced Avionics, Fuel-Efficient Engines, Cabin Connectivity, Safety Systems |
| Companies Covered | Textron Aviation, Gulfstream Aerospace Corporation, Bombardier Inc., Dassault Aviation, Embraer S.A., Cirrus Aircraft, Honda Aircraft Company, Pilatus Aircraft Ltd., Airbus, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Business Jet Market Evolving Landscape
Autonomous flight systems and predictive maintenance algorithms are compressing crew costs and unscheduled downtime, while regulatory pressure on emissions intensifies propulsion research and sustainable fuel infrastructure deployment.
Fly-by-wire flight control systems with envelope protection are automating pilot workload reduction during high-workload phases including approach and landing. Corporate flight departments with safety-sensitive cultures are adopting these platforms faster than owner-operator segments. This automation is compressing insurance premium differentials between experienced and transitioning flight crews.
FAA sustainable aviation fuel blending mandates under the Inflation Reduction Act production credit framework are forcing fuel supplier investments at fixed-base operators. The industrial consequence is geographic concentration of SAF availability at major hubs before regional dispersion. Charter operators with national networks are responding by repositioning aircraft to SAF-capable bases for high-visibility client missions.
Subscription-based access models are displacing traditional aircraft management contracts among mid-cabin users. Charter aggregators and fractional platforms capture demand previously served by wholly owned aircraft with dedicated flight departments. This shift concentrates most visibly in Florida, where seasonal population influxes create demand spikes that asset-light models absorb without year-round fixed costs.
North America Business Jet Market Segmentation
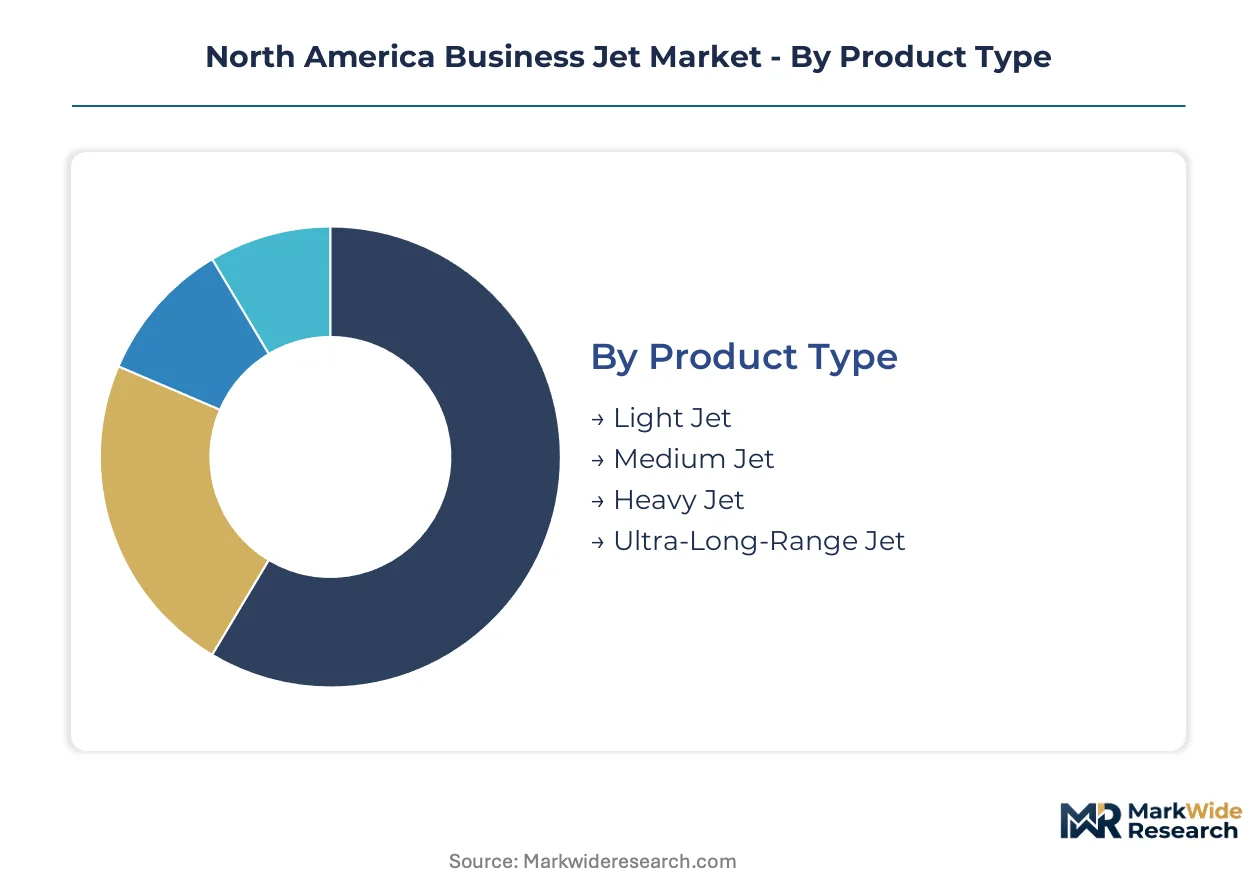
Business jet procurement patterns diverge sharply across aircraft class, operator type, and mission profile, with OEM production slots and hangar infrastructure availability determining effective market boundaries. Understanding these segment dynamics clarifies where FAA NextGen mandates and state tax arbitrage concentrate competitive activity.
Product Type:
Supply concentration in airframe manufacturing creates distinct tiering, with three OEMs controlling ultra-long-range platform output and Textron Aviation dominating light-jet production volumes.
- Light Jet:Single-pilot-certifiable aircraft with maximum takeoff weights below 12,500 pounds and ranges of 1,500 to 2,500 nautical miles. Demand clusters among Texas-based charter operators serving fractional programs, where lower acquisition costs offset high cycle rates. FAA Part 23 certification timelines favor established platforms over clean-sheet designs.
- Ultra-Long-Range Jet:Large-cabin platforms exceeding 6,500 nautical miles range with stand-up cabins and 14+ passenger capacity. Florida-registered corporate flight departments absorb production slots for transoceanic missions, prioritizing cabin altitude systems and satellite connectivity over fuel efficiency metrics.
- Medium Jet:Mid-cabin platforms bridging 2,500 to 3,500 nautical miles with eight-passenger configurations.
- Heavy Jet:Large-cabin aircraft with 4,000 to 6,000 nautical mile range and full galley capabilities.
Heavy Jet absorbs the bulk of installed capacity; Ultra-Long-Range Jet is expanding most quickly.
End User:
Customer type determines utilization intensity, with charter operators achieving 800+ annual flight hours against sub-300 hours for traditional private ownership.
- Corporations:Flight departments managing dedicated aircraft for executive transport with internal cost allocation systems. Procurement concentrates in Texas and Florida, where IRS bonus depreciation schedules and state property tax exemptions align with fleet renewal cycles. FAA Part 91 operational rules permit greater scheduling flexibility than commercial alternatives.
- Charter Operators:Part 135 certificate holders monetizing aircraft through hourly charter revenue. Demand spikes in Florida during seasonal population influxes, where asset-light models absorb demand without year-round fixed costs. Pilot labor scarcity constrains fleet expansion velocity.
- Private Owners:High-net-worth individuals with dedicated flight crews and hangar arrangements.
- Government Agencies:Federal, state, and municipal operators with specialized mission requirements.
Corporations retain the largest installed base; Charter Operators are climbing the fastest.
Application:
Mission profile dictates equipment specification, with point-to-point corporate travel demanding different cabin configurations than time-sensitive medical evacuation.
- Corporate Travel:Scheduled executive transport between headquarters, manufacturing facilities, and client sites. Demand concentrates in Texas energy corridors and Florida wealth enclaves, where highway congestion and limited commercial airport proximity justify private aviation economics. Cabin connectivity and meeting space configurations dominate procurement criteria.
- Medical Evacuation:Air ambulance operations requiring pressurized cabins, stretcher installations, and rapid dispatch capabilities. Florida's retirement demographics sustain dedicated medevac fleets, where response-time contracts with hospital networks determine base location decisions.
- Cargo Transport:Time-critical freight movements utilizing converted passenger configurations.
- Personal Travel:Discretionary leisure missions with flexible scheduling and destination diversity.
Corporate Travel commands the dominant revenue share; Medical Evacuation is gaining share fastest.
Technology:
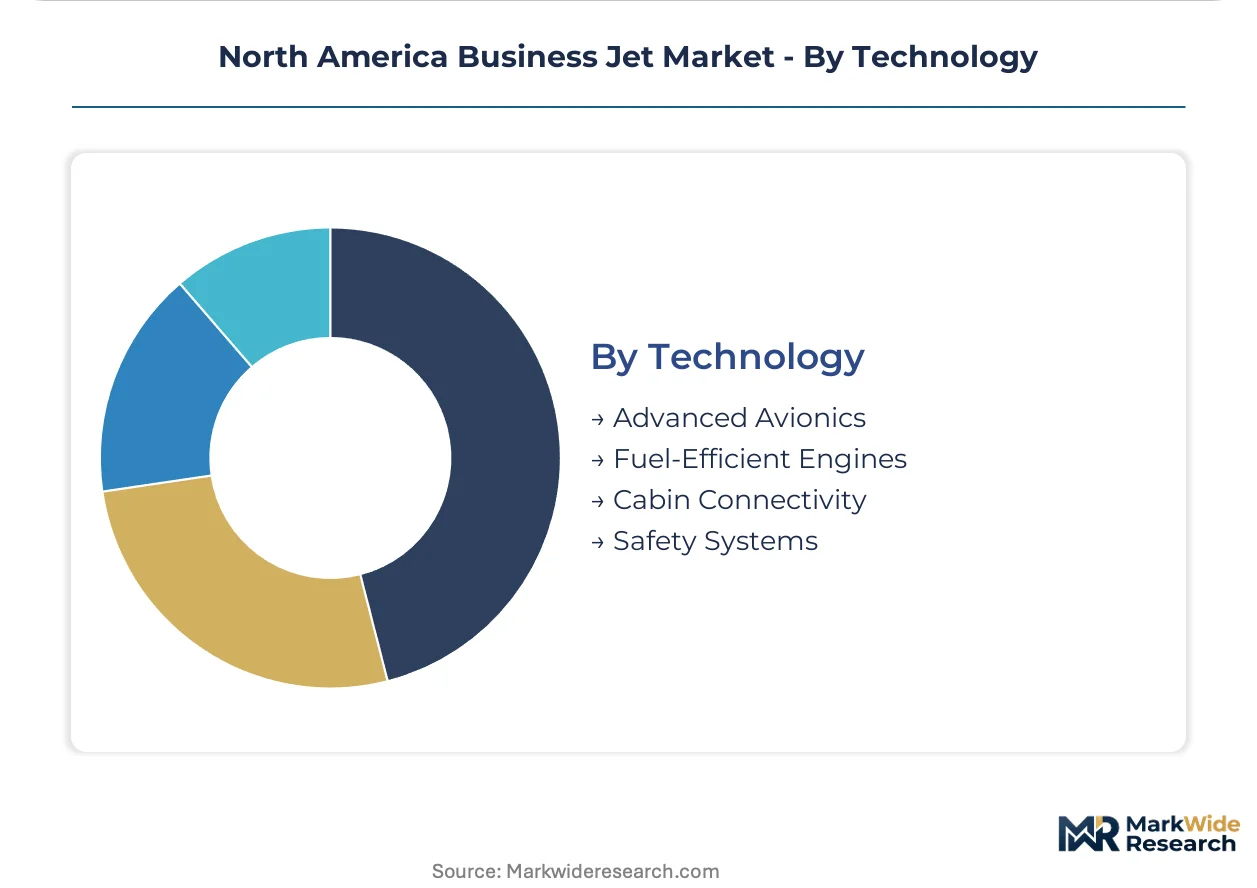
Technology tiering separates premium platforms from value alternatives, with avionics refresh cycles and propulsion efficiency determining residual value trajectories.
- Fuel-Efficient Engines:High-bypass turbofans with 15-20% fuel burn reduction over legacy powerplants. Charter operators in high-utilization fleets prioritize these platforms, where hourly operating cost advantages compound across annual flight volumes. FAA emission guidelines under EPA frameworks accelerate adoption timelines.
- Advanced Avionics:Integrated flight decks with synthetic vision, automated emergency descent, and required navigation performance capabilities. Corporate flight departments with safety-sensitive cultures adopt these platforms faster than owner-operator segments, compressing insurance premium differentials.
- Cabin Connectivity:Satellite broadband and secure communication systems for airborne productivity.
- Safety Systems:Enhanced ground proximity warning, traffic collision avoidance, and flight envelope protection.
Advanced Avionics carries the largest installed penetration; Fuel-Efficient Engines show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Business jet demand concentrates in Texas and Florida, where state tax structures and hangar infrastructure attract high-net-worth buyers and charter operators. FAA NextGen mandates and IRS bonus depreciation schedules compress fleet renewal cycles across the United States. Transport Canada Civil Aviation maintains aligned certification reciprocity with FAA standards.
United States
Corporate flight departments in Texas energy corridors and Florida wealth enclaves drive procurement for ultra-long-range and heavy jet platforms. FAA Part 25 airworthiness rules and Part 91 operational flexibility shape fleet planning for dedicated executive transport. Dallas-Fort Worth and Miami-Opa Locka anchor the nation's densest concentrations of fractional ownership programs and charter certificate holders.
Canada
Resource sector executives in Alberta and Ontario sustain demand for long-range aircraft serving remote mining and energy installations. Transport Canada Civil Aviation maintains type certification reciprocity with FAA standards, streamlining cross-border aircraft registration. Calgary and Toronto Pearson host the dominant fixed-base operator infrastructure for corporate aviation in the country.
Mexico
DGAC operational standards influence charter economics for cross-border fleet deployment from Texas bases into Mexican resort and business destinations. Mexico City International Airport and Monterrey concentrate corporate flight activity serving manufacturing and financial sectors. Regulatory harmonization discussions with FAA Part 135 rules are expanding market access for fractional programs.
California
Technology sector executives and entertainment industry principals generate demand for ultra-long-range aircraft with premium cabin configurations. State-level emissions regulations and airport curfew restrictions at Van Nuys and Burbank influence aircraft selection toward newer, quieter platforms. Sustainable aviation fuel infrastructure investments at Los Angeles International Airport are reshaping fuel procurement strategies for based operators.
Northeast Corridor
Financial services and pharmaceutical headquarters in New York Metro and Greater Boston sustain corporate flight departments with point-to-point requirements to secondary markets. Teterboro Airport and Westchester County Airport face slot constraints that favor larger-cabin aircraft maximizing passenger loads per movement. FAA NextGen implementation in congested northeastern airspace accelerates avionics upgrade timelines for regional operators.
North America Business Jet Market Competitive Landscape
United States producers anchor the light and midsize jet tier; Canadian and European specialists hold positions in the ultra-long-range and heavy segments. Three original equipment manufacturers control ultra-long-range platform production, creating extended order backlogs. Strategic archetypes include diversified aerospace conglomerates with civilian-military portfolios, pure-play business aviation specialists, and regional jet manufacturers extending into executive configurations. Dominant competitive moves center on portfolio diversification across aircraft classes and strategic partnerships for sustainable aviation fuel infrastructure.
Within the diversified conglomerate tier, Textron Aviation and Gulfstream Aerospace Corporation represent established positions spanning light through ultra-long-range categories. Bombardier Inc. exemplifies the pure-play specialist archetype following portfolio restructuring to focus exclusively on business aviation. These three anchors collectively shape competitive dynamics in the North American market through production slot allocation and certification timing.
| Leading Market Players |
|---|
| Textron Aviation |
| Gulfstream Aerospace Corporation |
| Bombardier Inc. |
| Dassault Aviation |
| Embraer S.A. |
| Cirrus Aircraft |
| Honda Aircraft Company |
| Pilatus Aircraft Ltd. |
| Airbus |
| Others |
Value Network & Pricing Analysis
Certified airframe and powerplant technician concentration across the U.S. Gulf Coast and Midwest maintenance hubs widens pricing-tier spreads between premium OEM service programs and independent MRO alternatives. Labor-cost differentials of thirty to forty percent separate factory-authorized facilities from Part 145 repair stations, compressing margins for charter operators running high-utilization fleets while insulating corporate flight departments with captive maintenance infrastructure.
Pricing Analysis
Volume-versus-margin splits sharply across operator archetypes, with charter platforms prioritizing acquisition cost per seat-mile against private owners optimizing residual value trajectories. Three-tier pricing structure across premium OEM, authorized dealer, and independent service levels reflects certification-grade differentiation in avionics and engine overhaul work. Pricing pressure stems from pilot labor scarcity forcing compensation escalation into fixed hourly rates. Charter operators exhibit highest price sensitivity; ultra-long-range private owners demonstrate lowest elasticity, prioritizing schedule certainty over unit economics.
Supply Chain Analysis
Jet engine turbine blade supply rests on U.S., UK, and Japanese precision casting specialists with single-source qualifications for FAA Part 33 certification. Avionics systems draw from Israeli, Canadian, and U.S. software-hardware integrators; composite airframe structures source from Japanese and Italian advanced materials processors. Single-source vulnerability concentrates in next-generation flight management system chipsets subject to export control review. Distribution runs through OEM-owned service centers, authorized dealer networks, and independent FBO parts depots with regional inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with thirty-six-month order backlogs for ultra-long-range platforms propping pricing power across the delivery curve. OEM production slot scarcity insulates incumbent margin structures from demand cyclicality.
For Market Incumbents: Hedge against fractional-platform disintermediation by securing long-term charter operator fleet commitments with embedded service contracts. Build captive MRO capacity in Texas and Florida to capture aftermarket revenue streams threatened by independent repair station expansion. Prioritize sustainable aviation fuel infrastructure partnerships at major hubs before regional dispersion accelerates.
For New Entrants and Emerging Players: Empty-leg aggregation platforms offer the most penetrable digital-channel route into price-sensitive demand segments underserved by traditional charter brokers. Target Texas-based fractional program overflow with dynamic repositioning algorithms. Deploy mobile-app booking interfaces with instant pricing transparency to capture millennial executive travelers.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play business aviation specialists given sustainable aviation fuel infrastructure buildout catalysts. Five-to-ten-year viability favors OEMs with diversified propulsion research portfolios spanning hybrid-electric and hydrogen architectures. Watch FAA Part 25 certification timeline compression as the inflection signal for production slot value appreciation.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Infrastructure Partnership | Fixed-base operators with early Jet-A blending capabilities capture charter operator loyalty at Dallas-Fort Worth and Miami-Opa Locka. |
| Fractional Platform Integration | OEM direct ownership stakes in NetJets-style programs secure production slot commitments through demand visibility. |
| Predictive Maintenance Algorithm Deployment | Flight data analytics partnerships with GE Aviation and Pratt & Whitney reduce unscheduled downtime for high-utilization fleets. |
| Mexico Charter Market Entry | DGAC regulatory harmonization enables cross-border Part 135 certificate utilization from Texas bases. |
| NextGen Avionics Retrofit Program | Supplemental type certificate acceleration for aging heavy jet fleets addresses FAA mandate compliance deadlines. |
Research Methodology
Independent corroboration across OEM production planners, fractional program fleet managers, and Part 135 charter certificate holders underwrites the qualitative findings. Primary interviews with FAA certification engineers, fixed-base operator proprietors, and corporate flight department directors combined with secondary validation from FAA type certificate databases, Transport Canada Civil Aviation reciprocity filings, and DGAC operational bulletins. Bottom-up aircraft delivery tracking and top-down regional demand modeling triangulate volume estimates.
Rate-of-change decomposition across the projection horizon isolates fleet replacement cycles, regulatory mandate compliance waves, and state tax arbitrage migration patterns. Segmentation dimensions span aircraft class, operator type, mission profile, and technology tier with regional production cluster overlays. CAGRs derive from installed base age demographics, order backlog conversion rates, and utilization intensity differentials between charter and private ownership. Forecast inputs incorporate pilot labor pipeline projections and sustainable aviation fuel infrastructure buildout timelines.
The model holds under stable FAA certification timelines and intact state tax incentive structures; deviation in export control expansion or Jet-A refining capacity constraints would shift delivery trajectories. Forecasts reflect these base assumptions with explicit scenario boundaries. A small set of named triggers—NextGen mandate acceleration, SAF blending mandate federalization, and Mexico regulatory harmonization completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Tugs Market
Aircraft
Military Transport Aircraft Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Electric Aircraft Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Commercial Helicopter Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Afterburner Market
Aircraft
Tanker Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market