
 3D Printing for Aerospace Market | 2026-2036
3D Printing for Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing for Aerospace Market Insights
The aerospace additive manufacturing landscape is decoupling into two distinct tiers: flight-critical components demanding full airworthiness certification versus ground-support tooling and prototyping accepting lower qualification thresholds. GE Additive leverages its position across both metal powder production and printing hardware to capture margin at multiple supply chain nodes. EOS GmbH sustains technology leadership in selective laser melting systems for titanium aerospace structures. Stratasys Ltd. competes primarily in polymer-based cabin interiors and non-structural applications where regulatory barriers remain comparatively lower.
3D printing for aerospace encompasses the layer-by-layer fabrication of metallic, polymer, and ceramic components using directed energy deposition, powder bed fusion, or binder jetting processes to achieve complex geometries unattainable through conventional subtractive machining. The primary industrial purpose centers on reducing buy-to-fly ratios in titanium and nickel superalloy components while enabling topology-optimized designs that cut aircraft weight. Selective laser melting dominates current production value for engine components and structural prototypes given its mature qualification pathways with major OEMs. Electron beam melting occupies a specialized niche in high-value titanium aerospace structures where vacuum environments minimize oxidation. Polymer composites within interior cabin parts represent the fastest-expanding material category as airlines pursue weight reduction without full metal certification burdens.
FAA airworthiness directives and EASA's MDR framework govern flight-critical additive manufacturing approvals, with both regulators expanding dedicated AM certification pathways that shape market access timelines. China's NMPA and MIIT coordinate national standards for aerospace additive manufacturing under dual carbon goals that favor material-efficient production methods. Stakeholders must monitor evolving qualification protocols across multiple jurisdictions to align R&D investments with certifiable production routes rather than pursuing technologies that lack regulatory precedent.
Market Dynamics
The aerospace additive manufacturing sector is bifurcating around certification intensity, with flight-critical metal components requiring exhaustive FAA and EASA qualification while polymer cabin parts move through streamlined approval channels. This divergence is reshaping capital allocation across the supply chain.
Growth Catalysts
- FAA Airworthiness Certification Pathways:Streamlined additive manufacturing qualification standards are accelerating production approvals for engine components and structural prototypes in the United States.
- Topology Optimization Demand:Aircraft OEMs are deploying generative design software to produce weight-reduced titanium structures unattainable through conventional machining.
- China's Dual Carbon Goals:NMPA and MIIT coordination of national aerospace AM standards favors material-efficient production methods under Beijing's emissions reduction mandates.
Market Restraints
- Titanium Powder Supply Concentration:Spherical plasma-atomized feedstock production concentrates among a handful of specialty chemical suppliers, creating input cost volatility.
- EASA MDR Framework Friction:Europe's medical device regulation overlap creates ambiguous classification boundaries for patient-monitoring aerospace cabin equipment.
- Electron Beam Melting Throughput Limits:Vacuum chamber size constraints restrict build volumes for large structural components, capping economies of scale.
Strategic Opportunities
- Underpenetrated Defense Aftermarket:Military maintenance depots in Germany and the United States are retrofitting legacy platforms with additively manufactured spare parts.
- Multi-Material Deposition Convergence:Hybrid systems combining directed energy deposition with CNC finishing are opening gradient-alloy component categories.
- India's PLI Scheme Extension:Production-linked incentives for aerospace manufacturing include additive qualification support for tier-2 suppliers near Bangalore and Hyderabad.
Industry Challenges
- Non-Destructive Testing Talent Scarcity:Computed tomography inspection specialists capable of validating internal lattice structures remain critically underrepresented across qualified NDT labs.
- Legacy ERP Integration Friction:Additive workflow data formats lack standardization with incumbent manufacturing execution systems at major OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing for Aerospace Market |
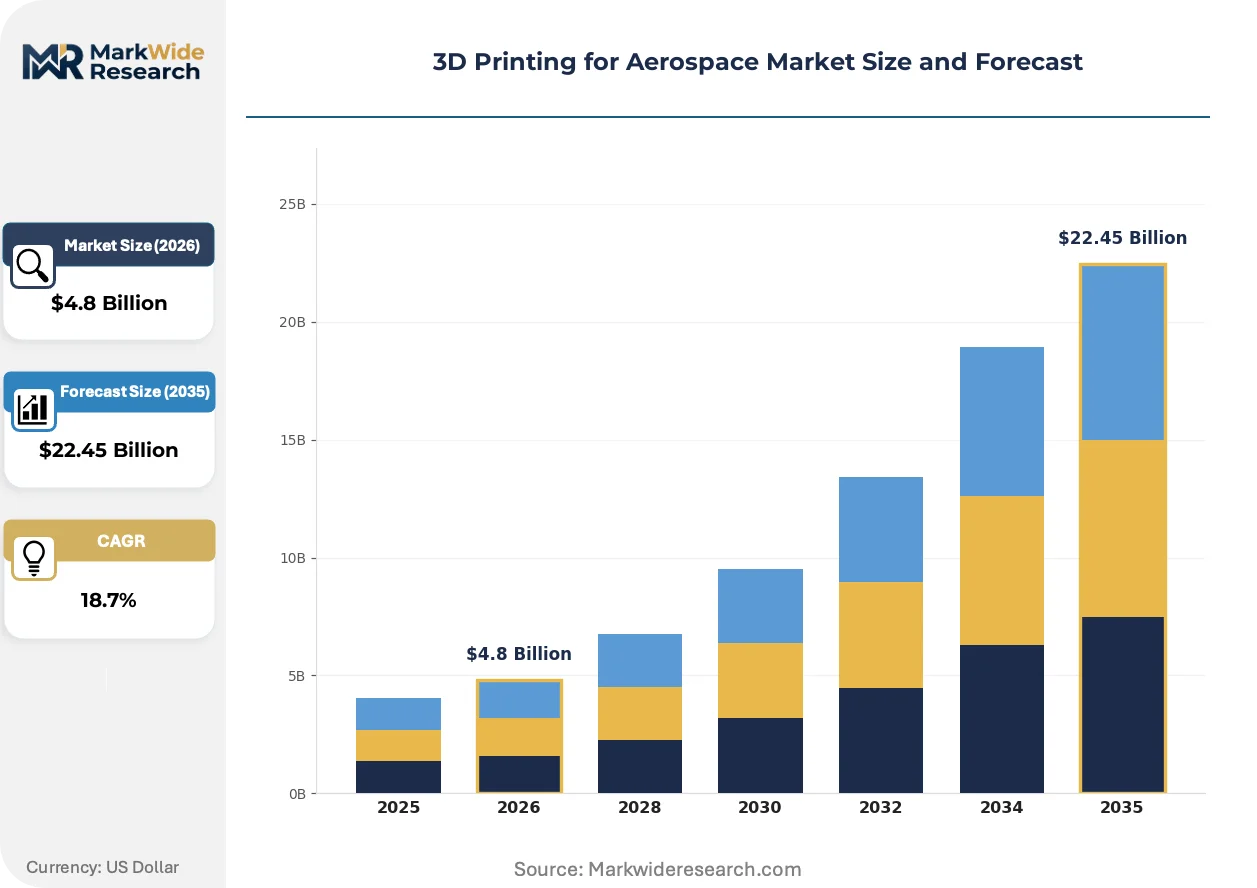
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Selective Laser Melting, Electron Beam Melting, Fused Deposition Modeling, Binder Jetting, Direct Energy Deposition Application: Engine Components, Structural Prototypes, Interior Cabin Parts, Tooling Equipment, Heat Exchangers Material Type: Titanium Alloys, Nickel-Based Superalloys, Aluminum Alloys, Polymer Composites, Ceramic Powders End User: Aircraft Manufacturers, Maintenance Providers, Spacecraft Assemblers, Defense Contractors, Research Institutions |
| Companies Covered | GE Additive, Stratasys Ltd., 3D Systems Corporation, EOS GmbH, Materialise, Norsk Titanium AS, SLM Solutions, Aerojet Rocketdyne, Ultimaker B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing for Aerospace Market Trends and Innovations
Process monitoring systems and in-situ quality assurance are displacing post-build inspection regimes, compressing certification timelines while raising the bar for equipment sophistication. These shifts favor suppliers with embedded sensor capabilities.
Cold spray deposition is rewriting repair economics for turbine blade restoration, enabling localized material rebuilding without heat-affected zones. MRO providers at Singapore and Dubai aerospace clusters are adopting portable systems for on-wing restoration. The technology is compressing turnaround times from weeks to days for high-value rotating components.
REACH substance restrictions on hexavalent chromium surface treatments are forcing conversion to additive-manufactured corrosion-resistant alloys across European supply chains. EASA's expanding AM qualification pathways now explicitly address environmental compliance in material substitution decisions. German engine manufacturers are prioritizing powder bed fusion routes that eliminate hazardous coating requirements.
Airline engineering departments are consolidating procurement authority for cabin interior retrofits, displacing fragmented lessor-driven purchasing. This concentration favors additive suppliers with design-to-certification capabilities over commodity print service bureaus. North American carriers are leading this consolidation, bundling polymer seat components and galley inserts under single-source additive contracts.
3D Printing for Aerospace Market Segmentation
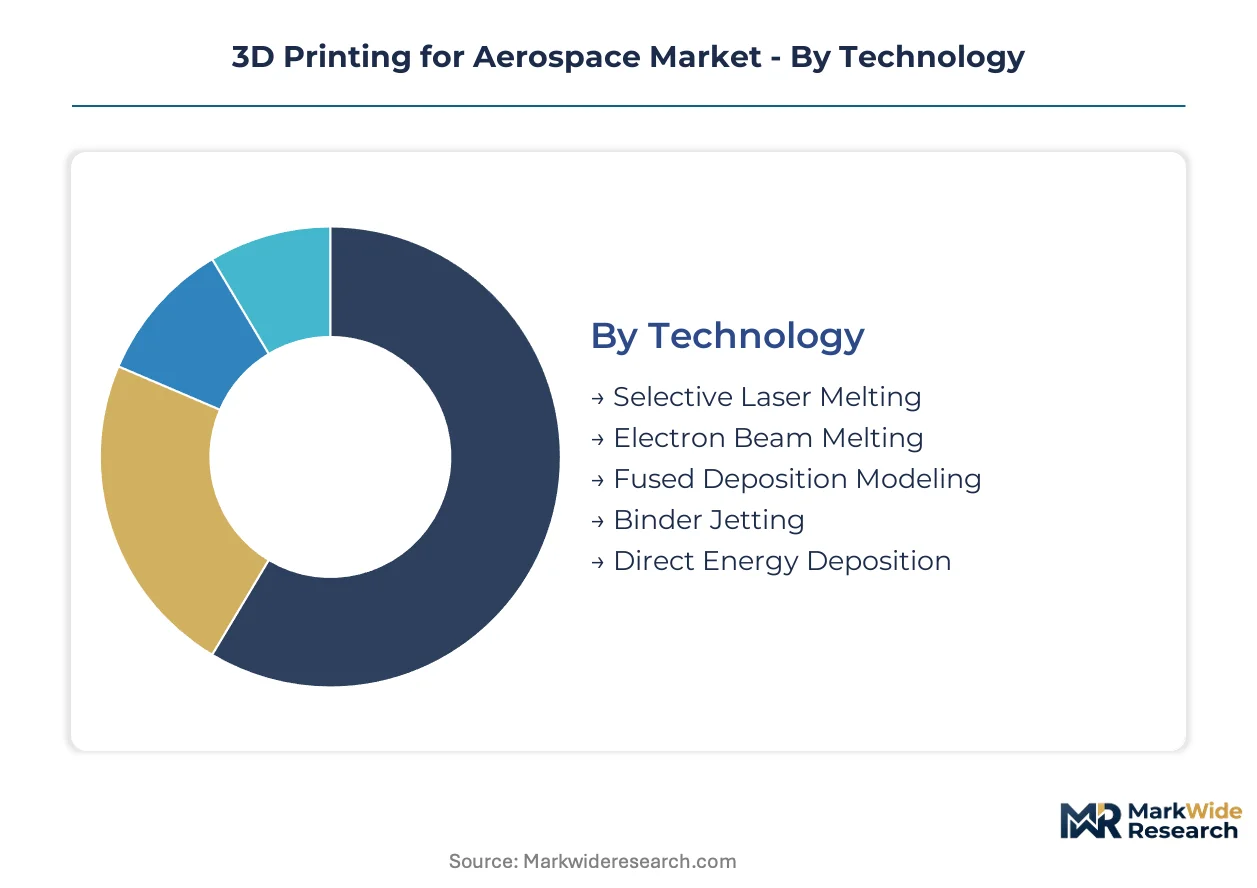
Aerospace additive manufacturing segments diverge sharply around certification burden and production scale. Technology choice locks in qualification pathways, while application type determines regulatory intensity and margin structure.
Technology:
Equipment suppliers concentrate R&D investment where OEM qualification precedent already exists, creating self-reinforcing technology hierarchies.
- Selective Laser Melting:Powder bed fusion using fiber lasers to melt metallic layers with exceptional dimensional accuracy. Boeing and Airbus have established formal qualification pathways for SLM-produced titanium brackets and nickel superalloy turbine hardware, cementing its position in flight-critical production. SLM absorbs the bulk of installed capacity; Binder Jetting is expanding most quickly.
- Electron Beam Melting:Vacuum-based powder bed fusion utilizing high-energy electron beams for pre-heated titanium builds. The technology dominates orthopedic-to-aerospace crossover applications and specialized high-value structural nodes where oxidation sensitivity demands controlled atmospheres. EBM equipment commands premium pricing but remains constrained by chamber size limitations.
- Fused Deposition Modeling:Thermoplastic extrusion systems producing polymer prototypes and non-structural cabin elements. Stratasys and similar suppliers target airline interior retrofit cycles where FAA certification requirements remain comparatively streamlined.
- Binder Jetting:Powder-based printing with liquid binding agents followed by sintering, enabling faster throughput for aluminum and stainless steel tooling. Desktop Metal and HP are pushing aerospace adoption for ground support equipment where mechanical properties meet less stringent thresholds.
- Direct Energy Deposition:Wire or powder-fed laser/welding systems building large structures or repairing existing components. Norsk Titanium has pioneered FAA-approved structural airframe production using DED for titanium fuselage sections.
SLM retains the deepest OEM integration; Binder Jetting is climbing the fastest as suppliers target cost-sensitive tooling applications.
Application:
End-use position in the aircraft architecture dictates everything from material selection to inspection protocols and contract duration.
- Engine Components:Turbine blades, fuel nozzles, and combustion hardware in nickel superalloys and cobalt-chrome. GE Additive has shipped over 100,000 additively manufactured fuel nozzles for LEAP engines, establishing the commercial reference case for flight-critical metal printing. Engine Components command the highest qualification investment; Interior Cabin Parts are gaining share fastest.
- Structural Prototypes:Topology-optimized brackets, pylons, and load-bearing nodes validating generative design methodologies. Airbus and Boom Supersonic utilize printed structural prototypes to compress development timelines for new airframe programs.
- Interior Cabin Parts:Polymer seat frames, overhead bins, and galley inserts where weight reduction drives airline procurement. Diehl Aviation and Safran have consolidated additive sourcing for retrofit programs across European and North American carrier fleets.
- Tooling Equipment:Drill jigs, assembly fixtures, and composite molds produced in aluminum or polymer composites. Boeing's Additive Manufacturing Fabrication Center in Washington state specializes in large-format tooling for 787 and 777X production lines.
- Heat Exchangers:Additively manufactured lattice structures enabling extreme surface-area-to-volume ratios for thermal management. Conflux Technology and similar specialists target satellite and defense applications where conventional manufacturing cannot achieve comparable performance.
Engine Components absorb the bulk of installed capacity; Interior Cabin Parts are expanding most quickly.
Material Type:
Feedstock supply concentration in spherical metal powders shapes cost structures and creates vulnerability to titanium sponge price volatility.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr dominate structural and engine applications where strength-to-weight ratios justify premium processing costs. Carpenter Technology and ATI control substantial plasma-atomized powder capacity serving aerospace-qualified supply chains. Titanium Alloys command the deepest supply chain investment; Polymer Composites are climbing the fastest.
- Nickel-Based Superalloys:Inconel 718 and 625 for high-temperature turbine environments exceeding 700°C. Cannon-Muskegon and Special Metals have developed AM-specific superalloy grades optimized for crack resistance during rapid solidification.
- Aluminum Alloys:Scalmalloy and AlSi10Mg for structural brackets and heat exchangers where corrosion resistance and printability balance. EOS and SLM Solutions have qualified aluminum parameter sets expanding application scope beyond legacy titanium dominance.
- Polymer Composites:ULTEM 9085, PEEK, and carbon-fiber-reinforced nylons for cabin interiors and radomes. Solvay and Victrex supply aerospace-grade feedstock meeting flame-retardant and smoke-toxicity requirements under FAA fireworthiness standards.
- Ceramic Powders:Oxide and non-oxide ceramics for thermal protection systems and investment casting cores. CoorsTek and Saint-Gobain serve niche satellite and hypersonic vehicle applications where extreme temperature resistance outweighs brittleness constraints.
Titanium Alloys absorb the bulk of installed capacity; Polymer Composites are expanding most quickly.
End User:
Procurement authority and technical capability vary enormously across customer categories, fragmenting sales approaches and contract structures.
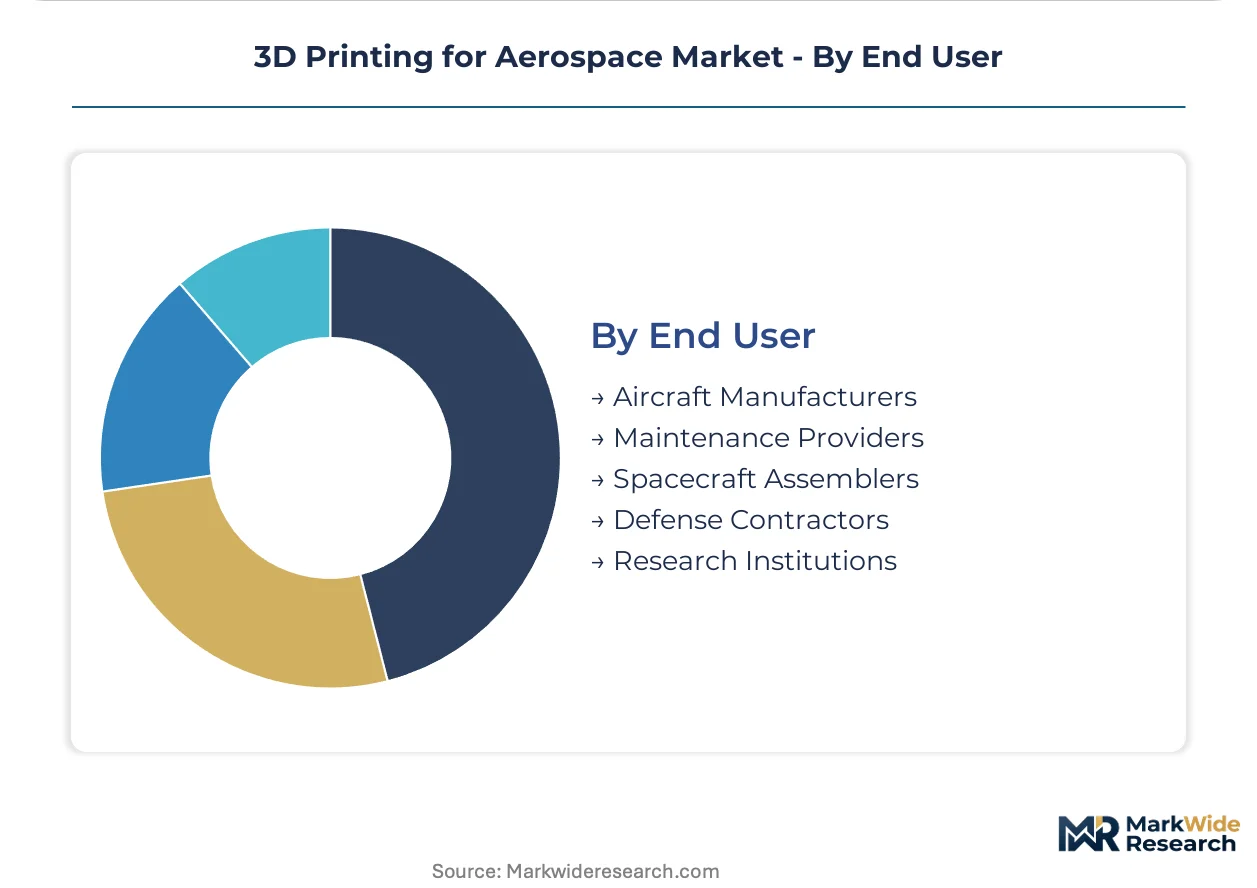
- Aircraft Manufacturers:Boeing, Airbus, and COMAC integrate additive across design, prototyping, and limited production with dedicated AM centers. Airbus's Hamburg and Toulouse facilities have achieved EASA Design Organization Approval for in-house printed parts. Aircraft Manufacturers concentrate the highest value contracts; Defense Contractors are gaining share fastest.
- Maintenance Providers:Lufthansa Technik, ST Engineering, and Delta TechOps explore additive for spare part production and repair services. Singapore's MRO cluster has invested in cold spray and DED capabilities for on-wing turbine restoration.
- Spacecraft Assemblers:SpaceX, Blue Origin, and Relativity Space leverage additive for engine combustion chambers and structural tanks where design flexibility outweighs heritage qualification requirements. Relativity's Terran R rocket targets 95% additive-manufactured mass fraction.
- Defense Contractors:Lockheed Martin, Raytheon, and BAE Systems pursue additive for hypersonic weapons, satellite buses, and field-deployable spare part fabrication. The US Defense Logistics Agency has established formal additive manufacturing qualification programs for supply chain resilience.
- Research Institutions:NASA Glenn, Oak Ridge National Laboratory, and Germany's Fraunhofer Institutes develop process parameters and material databases feeding downstream industrial adoption. FAA's National Center for Advanced Materials Performance collaborates with universities on fatigue life prediction for printed metals.
Aircraft Manufacturers absorb the bulk of installed capacity; Defense Contractors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors aerospace additive manufacturing demand through Boeing's Additive Manufacturing Fabrication Center, where large-format tooling production for 787 and 777X programs concentrates specialized polymer and metal printing capacity.
United States
Defense contractors at Palmdale and Lockheed Martin facilities drive titanium structural component demand for hypersonic weapons and satellite buses. FAA airworthiness certification pathways for additive manufacturing streamline production approvals for flight-critical engine hardware. Cincinnati's GE Additive operations anchor the LEAP fuel nozzle supply chain, having shipped over 100,000 additively manufactured components.
Germany
Airbus Hamburg and Toulouse facilities leverage German process expertise for EASA Design Organization Approval of in-house printed parts. REACH substance restrictions on hexavalent chromium coatings force conversion to powder bed fusion routes eliminating hazardous surface treatments. EOS GmbH in Krailling sustains technology leadership in selective laser melting systems for titanium aerospace structures.
China
COMAC integrates additive manufacturing across C919 development programs with dedicated AM centers in Shanghai. NMPA and MIIT coordination of national aerospace AM standards favors material-efficient production methods under Beijing's dual carbon goals. Xi'an and Chengdu aerospace clusters concentrate defense contractor activity for field-deployable spare part fabrication.
Singapore
ST Engineering and the broader MRO cluster invest in cold spray and directed energy deposition capabilities for on-wing turbine restoration. The country's national aerospace regulator aligns qualification protocols with EASA frameworks to accelerate regional adoption. Seletar Aerospace Park houses specialized additive repair facilities compressing turnaround times from weeks to days.
United Kingdom
BAE Systems pursues additive manufacturing for military aircraft sustainment and next-generation combat air systems. The country's national aerospace regulator maintains close coordination with EASA on additive manufacturing qualification standards. Bristol and Farnborough clusters concentrate research institution activity feeding downstream industrial adoption.
3D Printing for Aerospace Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the aerospace additive manufacturing landscape, with equipment manufacturers maintaining foundry-like control over process parameters while service bureaus operate with minimal fixed asset exposure. The market structures around three tiers: integrated powder-to-print suppliers capturing margin at multiple nodes, pure-play hardware specialists defending technology differentiation, and contract manufacturers scaling through airline interior retrofit consolidation. Dominant competitive moves include strategic partnerships between equipment makers and OEM qualification programs, plus geographic expansion into defense aftermarket depots.
Within the integrated powder-to-print tier, GE Additive exemplifies vertical control spanning metal powder production and printing hardware. EOS GmbH and Stratasys Ltd. anchor opposing technology poles—selective laser melting systems versus polymer-based cabin applications—each representing distinct regulatory intensity strategies. These three entities occupy positions that illustrate how certification pathway depth determines sustainable competitive advantage.
| Leading Market Players |
|---|
| GE Additive |
| Stratasys Ltd. |
| 3D Systems Corporation |
| EOS GmbH |
| Materialise |
| Norsk Titanium AS |
| SLM Solutions |
| Aerojet Rocketdyne |
| Ultimaker B.V. |
| Others |
Pricing and Supply Chain Analysis
Aircraft manufacturers and defense contractors concentrate procurement authority for flight-critical components, locking in value-based pricing tied to airworthiness certification outcomes rather than unit production costs. This buyer concentration enables equipment suppliers to capture premium returns on qualified parameter sets while squeezing commodity print service bureaus competing for non-structural cabin contracts.
Pricing Analysis
Value-based pricing anchored to FAA and EASA certification throughput governs flight-critical metal components, with SLM parameter sets commanding substantial premiums over unqualified alternatives. Price differentiation rests on airworthiness qualification tier and OEM-approved status, with certified titanium engine hardware carrying multiples over ground-support tooling. Pricing pressure stems from binder jetting suppliers targeting cost-sensitive aluminum fixtures where mechanical thresholds permit faster, cheaper production. Defense contractors exhibit lowest price sensitivity given mission-critical requirements and sole-source vulnerability, while airline retrofit programs drive hardest bargains on polymer cabin parts facing fragmented service bureau competition.
Supply Chain Analysis
Domestic-content mandates under China's MIIT directives and India's PLI scheme extension are reshaping sourcing patterns for spherical titanium powder and qualified printing capacity. Supply concentrates in the United States, Germany, and China, with Carpenter Technology and ATI controlling plasma-atomized feedstock production. Raw material dependencies center on titanium sponge, nickel superalloy ingots, and aerospace-grade polymer resin. Single-source vulnerability in spherical powder atomization creates supply chain risk, as vacuum induction melting capacity expansion lags demand growth. Distribution runs through qualified tier-1 suppliers holding OEM-approved parameter sets, with direct sales to aircraft manufacturers and defense contractors displacing distributor channels for flight-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FAA airworthiness certification pathways erect formidable barriers to entry, rewarding players with established qualification precedent and punishing those lacking OEM relationships. EASA's expanding additive manufacturing standards deepen this moat for European-qualified suppliers.
For Market Incumbents: To counter binder jetting suppliers encroaching on aluminum tooling applications, deepen upstream control over spherical powder production and expand captive titanium atomization capacity in Germany or the United States. Prioritize certification investment for multi-material deposition systems combining directed energy deposition with CNC finishing, securing gradient-alloy component categories before competitors achieve qualification.
For New Entrants and Emerging Players: Enter via India's PLI scheme extension for aerospace manufacturing near Bangalore and Hyderabad, where production-linked incentives offset qualification costs for tier-2 suppliers. Target ground-support tooling and polymer cabin interiors as the most penetrable segments, avoiding flight-critical metal components where GE Additive and EOS GmbH hold entrenched positions. Pursue design-to-certification partnerships with consolidated airline engineering departments bundling retrofit procurement.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists spanning powder production through qualified printing capacity, particularly those with established FAA or EASA certification precedent. Acquisition targets should demonstrate embedded sensor capabilities for in-situ quality assurance, as process monitoring systems displace post-build inspection regimes. Watch cold spray deposition adoption rates at Singapore and Dubai MRO clusters as the signal indicating repair economics disruption and on-wing restoration market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Certification Pathway Investment | GE Additive's LEAP fuel nozzle precedent accelerates approval timelines for qualified suppliers. |
| Backward Integration into Powder Production | Captive titanium atomization capacity insulates margins from feedstock price volatility. |
| Multi-Material Deposition Development | Hybrid laser-CNC systems open gradient-alloy categories beyond conventional powder bed fusion. |
| Cold Spray Repair Capability Deployment | Portable on-wing restoration compresses turbine blade turnaround times from weeks to days. |
| Airline Interior Retrofit Consolidation | Single-source additive contracts with North American carriers displace fragmented lessor purchasing. |
Research Methodology
Multi-period observation of FAA certification timeline compression, EASA qualification standard evolution, and OEM additive manufacturing adoption rates anchored the trend analysis, supplemented by interviews with additive manufacturing engineers at major aircraft manufacturers, regulatory affairs specialists at certification bodies, procurement directors at defense contractors, and MRO operations managers at Singapore and Dubai aerospace clusters. Secondary validation drew from FAA airworthiness directives, EASA MDR framework updates, SEC filings of publicly traded equipment suppliers, and customs data on titanium powder imports. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across technology type, application category, material composition, and end-user archetype structured the analytical framework across the analysis window. CAGRs derived from fitted growth curves applied to qualified production capacity expansion and OEM adoption trajectory data. Industry-specific forecast inputs incorporated EASA Design Organization Approval timelines and China's NMPA standard coordination pace under dual carbon mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory pathway delays, titanium powder supply disruptions, or electron beam melting throughput breakthroughs. Forecasts reflect documented assumptions regarding certification timeline standardization and OEM qualification precedent expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market