
 Aerospace Raw Materials Market | 2026-2036
Aerospace Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Raw Materials Market Analysis
Aftermarket service revenue is rewriting margin allocation across the aerospace raw materials value chain. ATI leverages its integrated titanium and nickel alloy production to capture higher-value mill product positions. Toray Industries anchors global carbon fiber prepreg supply for next-generation airframe programs. Hexcel Corporation competes through specialized thermoset formulations that sustain OEM qualification barriers.
Aerospace raw materials encompass engineered substances—titanium alloys, carbon fiber reinforced polymers, aluminum-lithium alloys, and high-temperature superalloys—selected for specific strength-to-weight ratios, fatigue resistance, and thermal stability under operational stresses. These materials undergo vacuum arc remelting, resin transfer molding, or hot isostatic pressing to meet stringent aerospace performance criteria. Composites command premium positioning in wing and fuselage applications where weight reduction directly improves fuel efficiency. Alloys retain dominance in engine and landing gear systems where creep resistance and fracture toughness remain non-negotiable. Aerospace grade material certification creates structural moats that industrial grade suppliers cannot readily cross.
FAA airworthiness standards, EASA Part 21 design organization requirements, and ISO 9100 quality management frameworks collectively govern material qualification, supplier approval, and traceability documentation. China's NMPA and MIIT are implementing GB standards alignment with international aerospace material specifications to support COMAC's global certification ambitions. Stakeholders must monitor evolving REACH chemical restrictions and EU Green Deal embodied carbon accounting rules that threaten to disqualify conventional production pathways without verified low-carbon alternatives.
Market Dynamics
Fleet renewal cycles and sustainable aviation fuel mandates are compressing material qualification timelines while expanding traceability requirements across the aerospace raw materials value chain.
Growth Catalysts
- COMAC Supply Chain Localization:China's MIIT is accelerating domestic titanium and composite certification to reduce import dependency for C919 production ramps.
- REACH Chemical Compliance:ECHA restrictions on hexavalent chromium surface treatments are forcing conversion to compliant alternatives, expanding qualified supplier pools for European OEMs.
- Hot Isostatic Pressing Adoption:Turbine component manufacturers are expanding HIP capacity to achieve near-net-shape nickel superalloy geometries that reduce machining waste.
Market Restraints
- Sponge Price Volatility:Titanium sponge feedstock costs fluctuate with Chinese export quotas and Russian supply disruptions, compressing mill product margins unpredictably.
- Single-Source Carbon Fiber Concentration:Aerospace-grade PAN precursor and oxidation line capacity concentrates among Japanese and US suppliers, creating qualification bottlenecks for new entrants.
- Superalloy Creep Limitations:Current nickel-based alloys approach thermal boundaries in next-generation turbofan architectures, constraining engine efficiency gains without ceramic matrix composite substitution.
Strategic Opportunities
- India Defense Manufacturing Corridors:Tamil Nadu and Karnataka aerospace parks offer PLI-linked incentives for titanium forging and composite layup facilities serving indigenous fighter programs.
- EU Green Deal Embodied Carbon Accounting:Verified low-carbon aluminum-lithium and recycled carbon fiber positions command premium qualification status under emerging sustainable aviation fuel lifecycle rules.
- Additive Manufacturing Convergence:Electron beam melting of titanium aluminide intermetallics is unlocking topology-optimized bracket geometries that displace multi-piece forged assemblies.
Industry Challenges
- Vacuum Metallurgy Skill Scarcity:VAR and ESR melt operators with aerospace alloy certification are retiring faster than apprenticeship pipelines replenish qualified personnel.
- OEM Qualification Timelines:Boeing and Airbus material specification approvals extend 18-36 months, freezing supplier switching decisions regardless of performance differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Raw Materials Market |
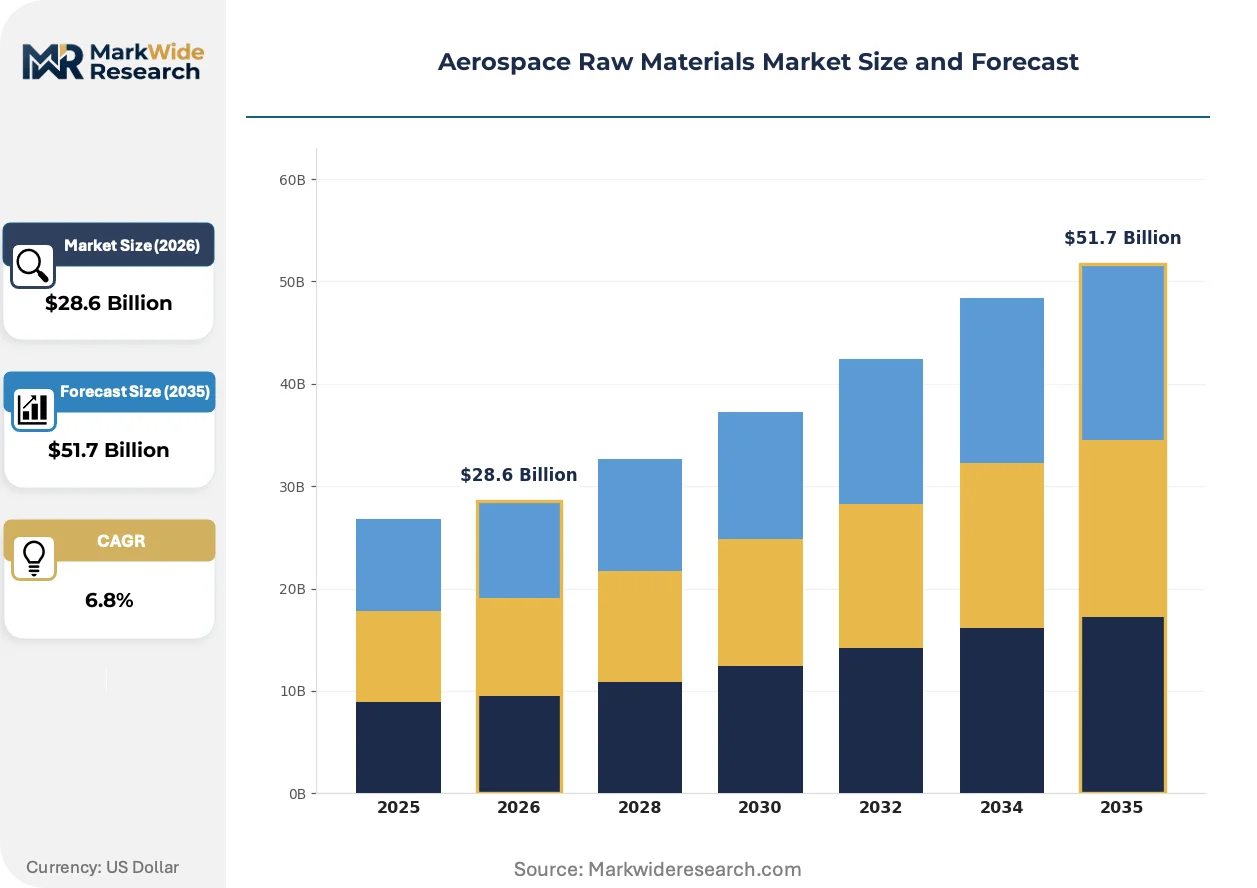
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composites, Alloys, Plastics, Fabrics Application: Aircraft, Spacecraft, Satellite, UAVs Material Grade: Aerospace Grade, Industrial Grade, Military Grade, Commercial Grade Delivery Mode: Direct Supply, Third-Party Logistics, Manufacturer Distribution, Online Sales |
| Companies Covered | ATI, Howmet Aerospace, Toray Industries, SeAH Aerospace & Defense Materials, BASF, Hexcel Corporation, VSMPO-AVISMA, PTC Industries, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Raw Materials Market Emerging Trajectories
Digital thread integration across material certification workflows is compressing design-to-production cycles while embedding traceability at the alloy heat and prepreg batch level.
Blockchain-enabled material pedigree tracking is digitizing supply chain documentation from sponge melt to finished component. Tier-1 aerostructures suppliers are mandating distributed ledger participation for new contract awards. This architecture is digitizing audit trails that previously required manual paper reconciliation across three-tier supply chains.
EASA Part 21 design organization requirements now mandate digital product models for material substitution approvals. European OEMs are restructuring supplier quality agreements to embed continuous compliance monitoring. Thermoplastic composite welding processes face accelerated qualification scrutiny under these revised certification protocols.
Long-term offtake contracting is displacing spot purchasing for carbon fiber prepreg as airframe rate hikes absorb available qualified capacity. Tier-2 fabricators are locking three-year supply agreements with penalty clauses for volume shortfalls. This pattern concentrates procurement leverage among OEMs with committed platform backlogs while marginalizing smaller MRO operations.
Aerospace Raw Materials Market Segmentation
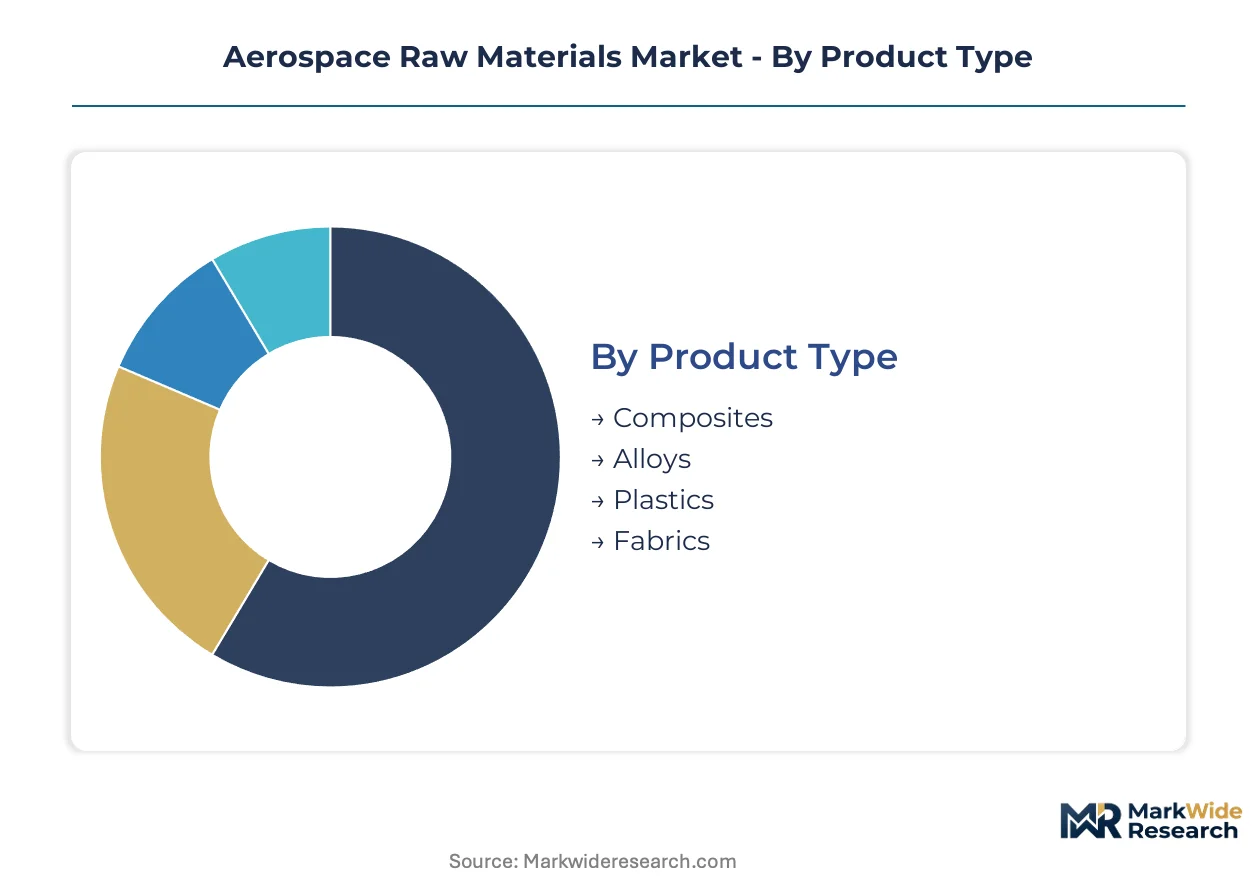
Material segmentation in aerospace raw materials determines qualification pathways, pricing tiers, and aftermarket service intensity. Each category reflects distinct technical specifications, regulatory burdens, and supply chain configurations that shape procurement strategies across OEM and MRO channels.
Product Type:
After-sales service intensity varies sharply across material categories, with composites requiring specialized repair protocols and alloys demanding metallurgical recertification.
- Composites:Carbon fiber reinforced polymers and thermoset prepregs deliver specific strength-to-weight ratios exceeding metallic alternatives. Demand concentrates in wing structures and fuselage panels for next-generation narrowbody programs, where Boeing and Airbus rate hikes absorb qualified prepreg capacity. Qualification timelines extend 24-36 months, embedding supplier lock-in.
- Alloys:Titanium and nickel-based superalloys undergo vacuum arc remelting to achieve aerospace-grade microstructural uniformity. Engine manufacturers in the US and UK dominate consumption for turbine disks and compressor blades, though creep resistance limitations in current formulations constrain thermal efficiency gains.
- Plastics:High-performance thermoplastics serve interior applications and non-structural components with reduced certification overhead.
- Fabrics:Technical textiles including aramid and fiberglass reinforcements occupy secondary structural roles with lower margin profiles.
Alloys hold the largest share; momentum sits with composites.
Application:
Application segmentation tracks platform-specific material specifications, with crewed aviation imposing the most stringent traceability requirements.
- Aircraft:Commercial and military fixed-wing platforms consume the majority of qualified titanium mill products and carbon fiber prepreg. China's COMAC C919 production ramp and India's indigenous fighter programs are reshaping regional supply chain geography.
- Spacecraft:Reusable launch vehicle programs drive demand for thermal protection system ceramics and cryogenic-compatible aluminum-lithium alloys. US and European launch providers specify material pedigree documentation from melt to mission.
- Satellite:Miniaturized satellite constellations prioritize mass efficiency over legacy qualification depth, opening procurement to industrial-grade suppliers with abbreviated testing protocols.
- UAVs:Uncrewed platforms span defense and commercial segments with bifurcated material standards—military specifications versus commercial off-the-shelf availability.
Aircraft applications dominate current procurement volume; UAVs are climbing the fastest as defense budgets expand uncrewed platform acquisition.
Material Grade:
Grade segmentation creates structural moats that industrial suppliers cannot readily cross, with certification costs determining viable participant pools.
- Aerospace Grade:Materials meeting FAA, EASA, and OEM-specific specifications command premium positioning through verified mechanical properties and full traceability documentation. Supplier approval processes extend 18-36 months, freezing switching decisions regardless of price differentiation.
- Military Grade:Defense-specific formulations incorporate additional ballistic and electromagnetic shielding requirements with classified performance thresholds.
- Commercial Grade:Lower-tier materials serve ground support equipment and non-flight-critical applications with reduced documentation burdens.
- Industrial Grade:Standard formulations lack aerospace certification, disqualifying participation in flight-critical supply chains regardless of cost advantage.
Aerospace grade captures the dominant revenue position; military grade is gaining share fastest through Indo-Pacific defense modernization programs.
Delivery Mode:
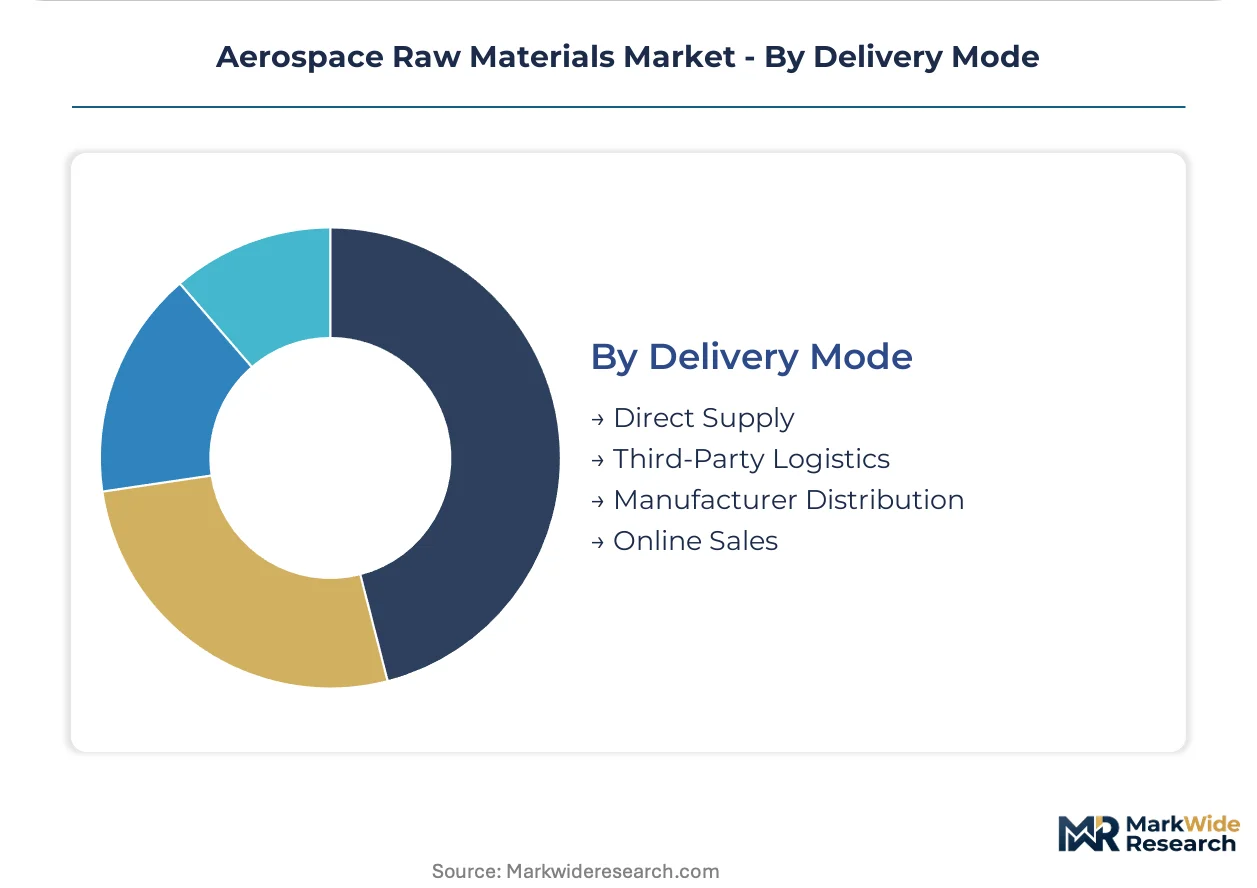
Delivery configuration shapes working capital requirements and inventory risk allocation across tiered supply chains.
- Direct Supply:Mill product manufacturers ship titanium sponge, nickel alloy ingots, and carbon fiber tow directly to Tier-1 aerostructures fabricators. Boeing and Airbus long-term offtake agreements lock capacity with penalty clauses for volume shortfalls.
- Manufacturer Distribution:Integrated producers including ATI maintain captive distribution networks for qualified alloys, capturing margin through value-added processing.
- Third-Party Logistics:Specialized aerospace logistics providers manage temperature-controlled prepreg storage and just-in-time delivery to composite layup facilities.
- Online Sales:Digital procurement platforms serve MRO operations and smaller fabricators with standard-sized mill products, though aerospace-grade materials remain predominantly relationship-contracted.
Direct supply holds the largest share; third-party logistics is expanding most quickly as OEMs outsource inventory management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices exhibit the lowest price elasticity, absorbing titanium sponge volatility without volume reduction. Commercial aviation buyers negotiate aggressively on mill product premiums. Satellite constellation operators source industrial-grade substitutes where qualification depth permits.
United States
Defense aerospace programs drive titanium and nickel superalloy consumption through Pratt & Whitney and GE Aviation turbine contracts. FAA airworthiness directives enforce material traceability from melt to finished component. The Pacific Northwest hosts Boeing-qualified titanium forging clusters serving 737 MAX and 777X production ramps.
China
COMAC C919 production targets are compressing domestic titanium sponge certification timelines. MIIT GB standards alignment with international aerospace specifications accelerates import substitution. The Yangtze River Delta concentrates carbon fiber prepreg facilities serving wing structure localization mandates.
France
Airbus A320neo and A350 rate hikes absorb qualified European titanium mill capacity. EASA Part 21 design organization requirements mandate digital product models for material substitution approvals. The Toulouse aerospace corridor anchors Safran-engineered superalloy demand for LEAP turbofan architectures.
India
Indigenous fighter programs and UAV procurement are expanding titanium forging demand beyond historical import dependency. PLI scheme incentives in Tamil Nadu and Karnataka aerospace parks attract composite layup facility investment. Hindustan Aeronautics Limited's Nashik division qualifies domestic nickel alloy sources for engine disk applications.
Japan
Toray Industries and Mitsubishi Chemical anchor global aerospace-grade PAN precursor supply. METI industrial policy supports oxidation line capacity expansion for next-generation airframe programs. The Chubu region concentrates carbon fiber tow production with Boeing and Airbus long-term offtake lock-ins.
Aerospace Raw Materials Market Vendor Landscape
Capability concentration sits with integrated titanium and superalloy producers; scale advantage sits with carbon fiber prepreg manufacturers with committed OEM backlogs. The market structures around three tiers: captive verticals serving single OEM ecosystems, qualified independents with multi-platform approval, and industrial-grade suppliers excluded from flight-critical chains. Dominant competitive moves include long-term offtake contracting with volume guarantee clauses and additive manufacturing qualification investments for topology-optimized bracket geometries.
Within the integrated metals tier, ATI and Howmet Aerospace exemplify backward control over vacuum metallurgy and near-net-shape forging capabilities. Toray Industries and Hexcel Corporation occupy positions in the composite materials vector, with the former representing Japanese PAN precursor integration and the latter exemplifying specialized thermoset formulation expertise. SeAH Aerospace & Defense Materials and VSMPO-AVISMA sit within the titanium sponge-to-mill-product vertical, anchoring regional supply security for Korean and Russian defense aerospace programs respectively.
| Leading Market Players |
|---|
| ATI |
| Howmet Aerospace |
| Toray Industries |
| SeAH Aerospace & Defense Materials |
| BASF |
| Hexcel Corporation |
| VSMPO-AVISMA |
| PTC Industries |
| Solvay |
| Others |
Supply Flow & Price Mechanics
Qualified carbon fiber prepreg undercapacity across Japan and the United States is driving Boeing and Airbus toward multi-year offtake guarantees with volume penalties, compressing spot-market availability while embedding supplier pricing power through committed platform backlogs.
Pricing Analysis
Aftermarket parts and service revenue streams now determine lifetime value capture across titanium mill products and composite repair networks. Contract-based long-term offtake dominates, with price differentiation hinging on aerospace-grade certification depth and geographic proximity to Boeing and Airbus final assembly lines. Cost compression in titanium sponge feedstock tiers is intensifying because Chinese export quota volatility and Russian supply disruptions squeeze mill product margins unpredictably. Defense procurement offices exhibit the lowest price sensitivity, absorbing volatility without volume reduction, while commercial aviation buyers negotiate aggressively on mill product premiums.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are proliferating among Tier-2 fabricators facing working capital pressure from three-year prepreg lock-ins. Geographic supply concentrates in Japan, the United States, and China, with aerospace-grade PAN precursor and oxidation line capacity anchoring Toray Industries and Mitsubishi Chemical positions. Raw material dependencies rest on titanium sponge, nickel alloy ingots, and carbon fiber tow. Single-source vulnerability in qualified oxidation line capacity creates structural risk. Distribution runs through direct mill-to-fabricator shipments with temperature-controlled third-party logistics for prepreg storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where FAA and EASA qualification timelines create switching costs that freeze supplier decisions regardless of performance differentiation.
For Market Incumbents: Build certification moats by accelerating electron beam melting qualification for titanium aluminide brackets and securing backward integration into vacuum arc remelting capacity. ATI and Howmet Aerospace exemplify this path. Threat substitution from ceramic matrix composites in next-generation turbofans demands preemptive superalloy creep-resistance investment. Channel control through captive distribution networks captures margin through value-added processing. For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu and Karnataka aerospace parks where PLI-linked incentives reduce capital barriers for titanium forging and composite layup facilities. UAV material standards remain the most penetrable segment, with bifurcated military-commercial specifications opening procurement to industrial-grade suppliers with abbreviated testing protocols. A go-to-market angle through digital thread integration for blockchain-enabled material pedigree tracking addresses Tier-1 aerostructures mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing qualification investments and hot isostatic pressing capacity expansion. Long-term viability over a multi-year horizon favors integrated titanium sponge-to-mill-product verticals with captive aerospace-grade certification. Acquisition target archetypes include qualified independents with multi-platform approval stranded by OEM consolidation. The signal to watch is COMAC C919 production ramp acceleration as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks qualified carbon fiber prepreg capacity with Boeing and Airbus penalty clauses for volume shortfalls. |
| Backward Integration | Captures margin through in-house vacuum arc remelting and near-net-shape forging capabilities like ATI's model. |
| Certification Investment | Accelerates FAA and EASA material specification approvals that freeze competitor switching decisions. |
| Capacity Expansion | Adds hot isostatic pressing lines for nickel superalloy turbine components reducing machining waste. |
| Joint Venture | Localizes titanium sponge production for COMAC supply chain security under China's MIIT localization mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with titanium mill product procurement managers, composite layup facility engineers, FAA certification specialists, and Tier-1 aerostructures supply chain directors. Secondary validation drew from FAA airworthiness directive filings, EASA Part 21 design organization documentation, customs trade data for titanium sponge and carbon fiber tow, and SEC 10-K disclosures from integrated producers. Bottom-up and top-down triangulation cross-referenced facility capacity announcements with OEM production rate schedules.
Calibration against historical qualification timelines and OEM production ramp schedules anchored the analytical framework across the analysis window. Segmentation dimensions modeled include material type, application platform, certification grade, and delivery mode. CAGRs were derived from production rate absorption curves and fleet renewal cycle phasing. Forecast inputs incorporated sustainable aviation fuel mandate compliance trajectories and REACH chemical restriction phase-out schedules.
Sensitivities concentrate around COMAC production ramp delays, titanium sponge export quota shocks, and ceramic matrix composite substitution rates in next-generation turbofans. Forecasts reflect documented assumptions on OEM rate hike execution and certification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Coatings Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market