
 Oscilloscope Market | 2026-2036
Oscilloscope Market Size, Share, and Industry Trends Forecast 2026-2036
Oscilloscope Market Intelligence
Gigahertz-class bandwidth tiers is reorganizing competitive positioning in the oscilloscope market. Keysight Technologies leverages in-house semiconductor fabrication to sustain leadership in ultra-high-bandwidth modules. Tektronix anchors its position through deep calibration service networks across North American aerospace clusters. Rohde & Schwarz differentiates via integrated spectrum-analyzer architectures that appeal to European telecommunications laboratories.
An oscilloscope is an electronic test instrument that graphically displays varying signal voltages as a function of time, typically achieving bandwidth specifications from fifty megahertz to over one hundred gigahertz and sample rates exceeding two hundred gigasamples per second for real-time acquisition. Engineers deploy oscilloscopes to characterize signal integrity, debug circuit failures, and validate timing compliance in high-speed digital and radio-frequency systems. Digital oscilloscope architectures now dominate instrument shipments due to their storage depth and automated measurement suites, while mixed-signal variants capture growing share by combining analog channels with digital logic analysis for embedded system development. Handheld oscilloscope demand remains concentrated in field maintenance applications where portability overrides performance ceilings.
FCC equipment authorization rules in the United States shape oscilloscope specifications for electromagnetic interference pre-compliance testing, while CE marking requirements under the EU EMC Directive mandate calibrated measurement uncertainty budgets for instruments sold into European industrial channels. Japan's METI administers measurement law certifications that govern legal traceability for oscilloscopes deployed in commercial calibration chains. Stakeholders must monitor how semiconductor export controls and evolving spectrum allocation policies reshape the addressable instrument base for defense and telecommunications verticals.
Market Dynamics
Automotive electrification programs in Germany and Japan are forcing oscilloscope manufacturers to recalibrate bandwidth-roadmap priorities toward mixed-signal architectures capable of validating wide-bandgap power semiconductors. This demand pull from EV powertrain development is compressing traditional product cycles and reshaping R&D allocation across the supplier base.
Growth Catalysts
- Wide-bandgap semiconductor qualification:Silicon carbide and gallium nitride deployment in EV inverters requires oscilloscopes with enhanced common-mode rejection and floating measurement capabilities.
- FCC Part 15 pre-compliance mandates:Electromagnetic interference testing for consumer electronics and industrial equipment drives recurring instrument refresh cycles in United States contract manufacturing facilities.
- East Asian incoming inspection expansion:Contract manufacturers for consumer electronics and electric vehicles in Taiwan and South Korea operate large-scale calibration laboratories requiring high-channel-count mixed-signal units.
Market Restraints
- Indium phosphide substrate scarcity:Ultra-high-bandwidth oscilloscope front-ends depend on specialized III-V semiconductor materials with concentrated supply from limited foundry capacity.
- Japan METI measurement law compliance costs:Legal traceability certification for commercial calibration chains imposes documentation and audit burdens that elevate total cost of ownership.
- USB-based modular instruments:Lower-cost PC-hosted acquisition modules threaten entry-level and mid-range benchtop oscilloscope segments in price-sensitive education and hobbyist markets.
Strategic Opportunities
- India electronics manufacturing PLI scheme:Production-linked incentives for semiconductor and component assembly create greenfield demand for incoming quality assurance instrumentation in new fabrication and test facilities.
- AI-assisted signal analysis integration:Machine learning algorithms for automated anomaly detection and protocol decoding converge with traditional hardware acquisition to differentiate premium product tiers.
- Cloud-native remote diagnostics:Browser-based instrument control and centralized waveform databases enable subscription revenue models and reduce customer capital expenditure barriers.
Industry Challenges
- RF/microwave signal integrity expertise scarcity:Gigahertz-class calibration and application engineering requires specialized skill sets that outpace university pipeline output in multiple geographies.
- Legacy GPIB infrastructure integration:Automated test systems in aerospace and defense facilities retain decades-old bus architectures that complicate new instrument connectivity and software stack modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oscilloscope Market |
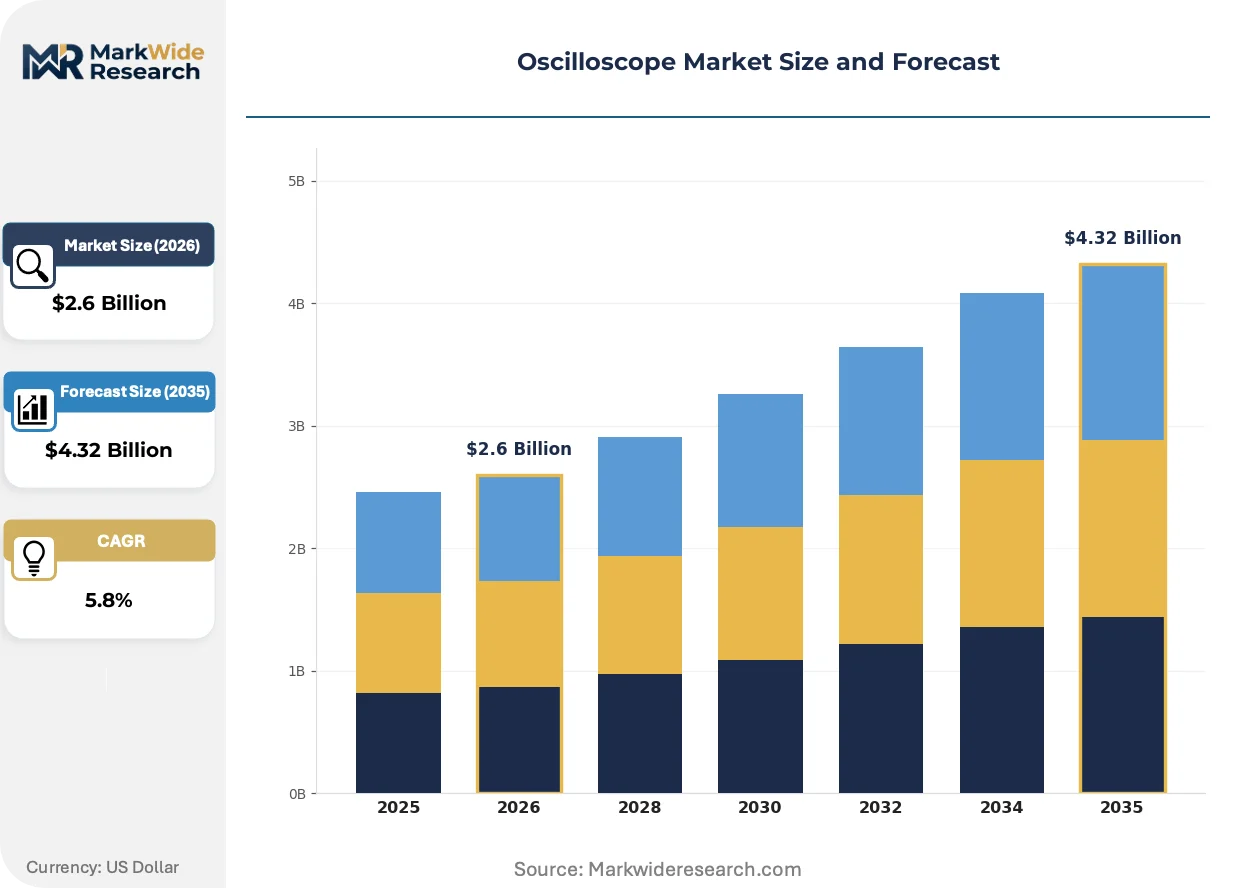
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Oscilloscope, Digital Oscilloscope, Mixed-Signal Oscilloscope, Handheld Oscilloscope End User: Telecommunications, Automotive, Aerospace, Education Technology: Digital Storage, Real-Time, Sampling, Fiber Optic Application: R&D, Manufacturing, Maintenance, Testing |
| Companies Covered | Teledyne LeCroy, Fluke Corporation, Tektronix, Rigol Technologies, National Instruments Corporation, Keysight Technologies, Yokogawa Test & Measurement Corporation, Siglent Technologies, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oscilloscope Market Strategic Shifts & Innovations
Software-defined instrument architectures are dissolving traditional hardware boundaries between oscilloscopes, spectrum analyzers, and protocol analyzers. This convergence is enabling new purchasing models while forcing incumbents to defend installed-base relationships through service-layer differentiation.
Real-time digital signal processing with field-programmable gate arrays is fragmenting the traditional segmentation between entry-level and mid-range oscilloscope tiers. FPGA-based digital down-conversion and serial trigger engines now appear in instruments below ten gigahertz bandwidth, compressing the performance premium historically commanded by higher-tier products. Test engineers in automotive and telecommunications verticals are capturing capabilities once reserved for research laboratories, eroding price stratification.
EU EMC Directive calibration requirements under CE marking mandates are tightening measurement uncertainty documentation for instruments sold into European industrial channels. Manufacturers must maintain accredited calibration laboratories with documented traceability chains to national metrology institutes. German automotive suppliers and French aerospace contractors are demanding extended calibration interval guarantees and audit-ready uncertainty budgets as contractual preconditions.
Subscription-based software licensing for advanced analysis packages is displacing perpetual feature bundles in enterprise procurement negotiations. Large semiconductor manufacturers in South Korea and Taiwan now negotiate site-wide floating licenses for jitter analysis and protocol decoding rather than purchasing instrument-locked options. This unbundling compresses upfront hardware margins while creating recurring revenue streams that alter sales compensation structures and customer lifetime value calculations.
Oscilloscope Market Segmentation
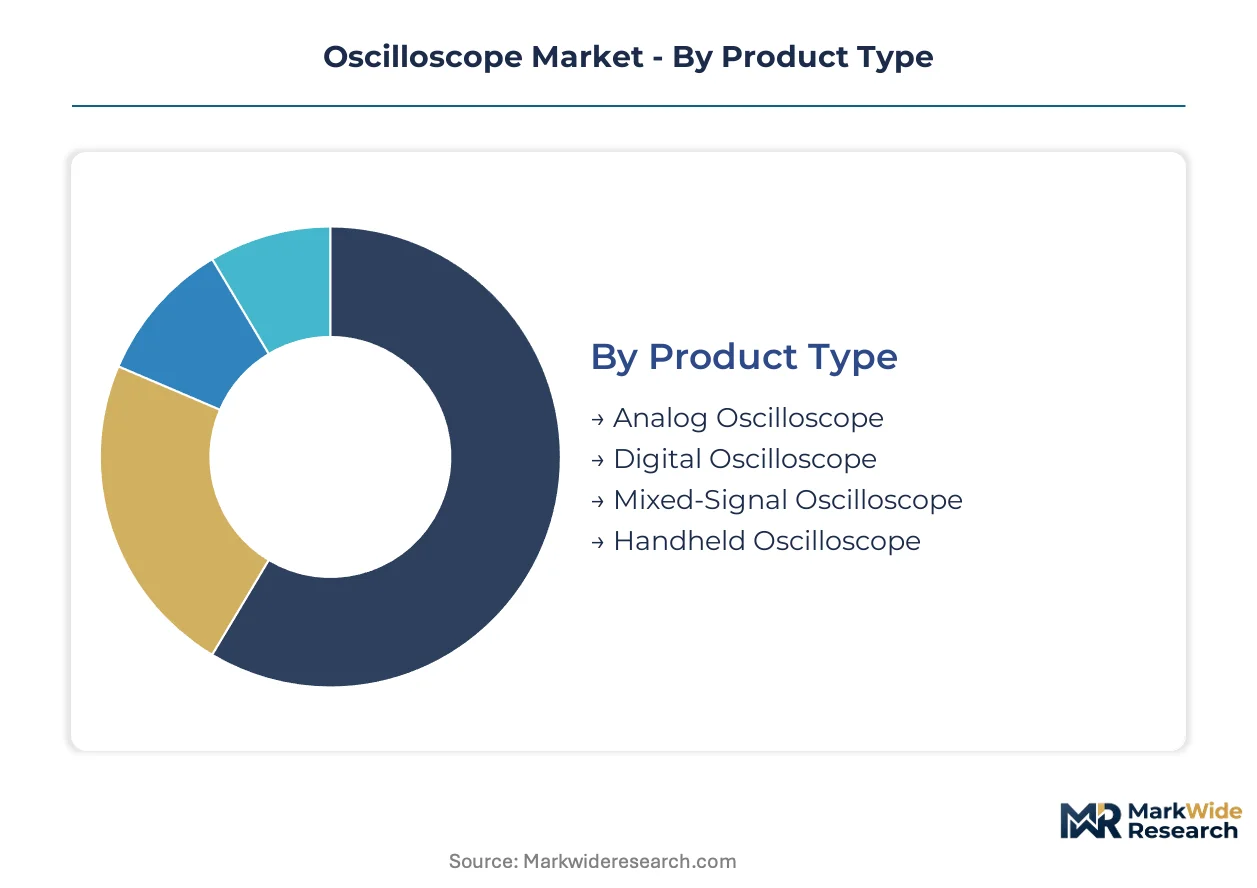
Oscilloscope procurement patterns diverge sharply across product architectures and use-case intensity. Segment boundaries determine pricing power, calibration service attach rates, and replacement cycle velocity for instrument suppliers.
Product Type:
Domestic demand concentrates in benchtop digital architectures for laboratory and production environments, while export-led growth flows through portable and specialized variants serving field maintenance and emerging manufacturing clusters.
- Digital Oscilloscope:These instruments capture waveform data through analog-to-digital conversion with deep memory buffers and automated measurement suites. Manufacturing facilities in Taiwan and South Korea deploy high-channel-count units for incoming inspection of consumer electronics and EV components, driven by compressed validation timelines in contract manufacturing.
- Mixed-Signal Oscilloscope:Combining analog channels with digital logic analysis capabilities, these architectures enable simultaneous validation of embedded system interfaces. German and Japanese automotive electrification programs are expanding procurement for wide-bandgap power semiconductor qualification, where floating measurement and enhanced common-mode rejection prove critical.
- Analog Oscilloscope:Cathode-ray tube-based instruments persist in educational institutions with constrained capital budgets and specific pedagogical requirements for direct waveform visualization.
- Handheld Oscilloscope:Battery-powered units with reduced bandwidth specifications serve field maintenance technicians in industrial and utility applications where portability overrides performance ceilings.
Digital oscilloscopes command the established base. The steepest expansion runs through mixed-signal architectures.
End User:
Cost tier stratification separates capital-intensive validation environments from price-sensitive procurement channels, with premium instrumentation concentrating in safety-critical verticals.
- Automotive:EV powertrain development and autonomous driving sensor validation require gigahertz-class bandwidth for high-speed data bus analysis. German OEMs and Tier-1 suppliers in Stuttgart and Munich operate large-scale electromagnetic compatibility pre-compliance laboratories.
- Telecommunications:5G base station deployment and optical network expansion drive demand for ultra-high-bandwidth real-time acquisition. South Korean network equipment manufacturers in Suwon and Seongnam maintain extensive signal integrity laboratories.
- Aerospace:Defense contractors and satellite manufacturers prioritize calibrated measurement uncertainty budgets and extended calibration interval guarantees for mission-critical avionics testing.
- Education:Universities and technical colleges procure entry-level and USB-based modular instruments for undergraduate laboratory instruction, with procurement cycles tied to academic budgeting calendars.
Telecommunications maintains the premium pricing tier. Automotive is gaining share fastest.
Technology:
Application maturity determines whether customers prioritize real-time acquisition fidelity or equivalent-time sampling for repetitive signals.
- Real-Time:These architectures capture single-shot events at sample rates exceeding two hundred gigasamples per second for transient analysis. Semiconductor failure analysis labs in Hsinchu and Yongin require this capability for debugging integrated circuit timing violations.
- Digital Storage:The dominant architecture for general-purpose test and measurement, combining deep memory with post-acquisition analysis. Manufacturing test floors across East Asia standardize on these instruments for production line monitoring.
- Sampling:Equivalent-time techniques achieve effective sample rates beyond real-time converter limitations for repetitive microwave and millimeter-wave signal characterization.
- Fiber Optic:Specialized front-ends with optical-to-electrical conversion for telecommunications physical layer testing and datacenter interconnect validation.
Digital storage technology anchors volume shipments. Real-time architectures follow the steepest expansion trajectory.
Application:
Customer type differentiation separates capital expenditure-intensive environments from operational expenditure-driven service operations.
- Manufacturing:High-volume production test requires automated pass-fail determination and statistical process control integration. Contract electronics manufacturers in Shenzhen and Penang operate incoming inspection laboratories with instrument counts exceeding fifty units per facility.
- R&D:New product development teams prioritize bandwidth headroom and software extensibility for protocol analysis and jitter decomposition. Integrated device manufacturers in San Jose and Austin maintain dedicated characterization laboratories.
- Testing:Third-party certification laboratories and regulatory compliance facilities require accredited calibration chains and documented measurement uncertainty for FCC Part 15 and CE marking submissions.
- Maintenance:Field service organizations and depot repair facilities emphasize durability, rapid boot times, and simplified user interfaces for technician efficiency.
Manufacturing commands the installed base. R&D is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-bandwidth oscilloscope front-end fabrication concentrates in specialized III-V foundries across the United States, Germany, Japan, and South Korea. This supply concentration shapes procurement patterns for automotive electrification programs and telecommunications infrastructure buildouts.
United States
FCC Part 15 pre-compliance mandates drive recurring instrument refresh cycles in contract manufacturing facilities. The FCC equipment authorization rules shape oscilloscope specifications for electromagnetic interference testing. Semiconductor characterization laboratories in San Jose and Austin maintain dedicated signal integrity facilities for integrated device manufacturers.
Germany
Automotive electrification programs in Stuttgart and Munich are expanding procurement of mixed-signal oscilloscopes for power electronics validation. CE marking requirements under the EU EMC Directive mandate calibrated measurement uncertainty budgets for instruments sold into European industrial channels. German automotive suppliers demand extended calibration interval guarantees and audit-ready uncertainty budgets as contractual preconditions.
Japan
EV powertrain development programs anchor demand for wide-bandgap semiconductor qualification instrumentation. METI administers measurement law certifications that govern legal traceability for oscilloscopes deployed in commercial calibration chains. Yokogawa and other precision instrument manufacturers in Tokyo and Osaka face compliance cost burdens that elevate total cost of ownership.
South Korea
5G base station deployment and optical network expansion drive demand for ultra-high-bandwidth real-time acquisition. Network equipment manufacturers in Suwon and Seongnam maintain extensive signal integrity laboratories. Large semiconductor manufacturers now negotiate site-wide floating licenses for jitter analysis rather than purchasing instrument-locked options.
China
Contract electronics manufacturers in Shenzhen operate incoming inspection laboratories with instrument counts exceeding fifty units per facility. MIIT spectrum allocation policies reshape the addressable instrument base for defense and telecommunications verticals. Semiconductor failure analysis labs in Hsinchu and Yongin require real-time acquisition capabilities for debugging integrated circuit timing violations.
Oscilloscope Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around three strategic archetypes: in-house semiconductor fabricators sustaining ultra-high-bandwidth leadership, deep calibration service network operators anchoring aerospace clusters, and integrated spectrum-analyzer architects targeting telecommunications laboratories. Dominant competitive moves include strategic partnerships for wide-bandgap power semiconductor validation and geographic expansion into East Asian incoming inspection facilities.
Among United States-based instrument manufacturers, Keysight Technologies and Tektronix occupy positions across premium bandwidth tiers. Teledyne LeCroy represents the specialized high-performance acquisition segment. German-based Rohde & Schwarz exemplifies integrated RF test equipment architectures. Chinese manufacturers Rigol Technologies and Siglent Technologies sit within the cost-optimized tier serving education and entry-level industrial markets. Yokogawa Test & Measurement Corporation anchors precision instrumentation demand in Japanese industrial channels.
| Leading Market Players |
|---|
| Teledyne LeCroy |
| Fluke Corporation |
| Tektronix |
| Rigol Technologies |
| National Instruments Corporation |
| Keysight Technologies |
| Yokogawa Test & Measurement Corporation |
| Siglent Technologies |
| Rohde & Schwarz |
| Others |
Cost & Logistics Intelligence
Indium phosphide foundry utilization rates above eighty percent create asymmetric scale advantages for in-house semiconductor fabricators, compressing price floors for ultra-high-bandwidth modules while elevating entry barriers for fabless competitors. This capacity concentration forces tier-two suppliers toward cost-optimized digital storage architectures, fragmenting pricing power across the bandwidth spectrum.
Pricing Analysis
FCC Part 15 equipment authorization rules dictate the pricing tier structure through calibration documentation burdens that stratify instruments across certification-grade levels. Three-tier pricing structure across premium, standard, and economy levels separates metrology-lab validated units from production-floor instruments and educational variants. Cost compression in the economy tier intensifies because USB-based modular instruments erode benchtop demand among price-sensitive education buyers, while aerospace contractors exhibit minimal price sensitivity due to mission-critical traceability requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate for digital storage oscilloscope components, while strategic stockpiling of indium phosphide substrates and III-V semiconductor wafers persists among ultra-high-bandwidth manufacturers. Supply concentrates in the United States, Germany, and Japan for specialized front-end fabrication, with assembly and calibration operations distributed across Taiwan and South Korea. Raw material dependencies include indium phosphide substrates, high-speed ADC dies, and precision attenuator networks. Single-source vulnerability in III-V foundry capacity threatens supply continuity. Distribution runs through authorized distributor networks with certified calibration service attach rates determining downstream profitability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where METI measurement law certification requirements create regulatory entrenchment that locks in incumbent relationships across Japanese commercial calibration chains.
For Market Incumbents: Compound switching cost advantages by embedding cloud-native remote diagnostics into existing installed bases, creating subscription revenue streams that raise replacement friction. Deepen backward integration into III-V semiconductor fabrication to secure indium phosphide substrate allocation against fabless competitors. Prioritize calibration service network density in Stuttgart and Munich automotive clusters where audit-ready uncertainty budgets function as contractual preconditions. For New Entrants and Emerging Players: AI-assisted signal analysis integration represents the primary service-layer gap where incumbents under-serve mid-tier automotive validation teams. Target India's electronics manufacturing PLI scheme corridors for greenfield incoming inspection demand, where production-linked incentive recipients lack established supplier relationships. Deploy browser-based instrument control as the go-to-market angle to reduce capital expenditure barriers among contract manufacturers. For Investors and Strategic Acquirers: FPGA-based digital signal processing specialists with automotive telecommunications vertical expertise represent the priority acquisition archetype for capability consolidation. Long-term viability hinges on software-defined instrument architecture transitions that dissolve hardware boundaries between test equipment categories. Watch for inflection when site-wide floating license negotiations displace instrument-locked option purchases among South Korean semiconductor manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Validation Partnership | Secures preferred supplier status with Stuttgart EV powertrain development programs. |
| Cloud-Native Diagnostics Platform | Enables subscription revenue models that reduce customer capital expenditure barriers. |
| III-V Foundry Capacity Expansion | Captures indium phosphide substrate allocation for ultra-high-bandwidth module leadership. |
| India PLI Corridor Entry | Positions for greenfield demand from semiconductor assembly and test facilities. |
| AI Signal Analysis Integration | Differentiates premium tiers through automated anomaly detection capabilities. |
Research Approach
Initial hypotheses were tested against primary input from test and measurement procurement managers, calibration laboratory directors, automotive validation engineers, and RF application specialists and refined through secondary validation. Primary fieldwork combined structured interviews with semiconductor failure analysis lab directors in Hsinchu and Yongin, signal integrity engineers at Suwon network equipment manufacturers, and metrology compliance officers at German automotive Tier-1 suppliers. Secondary sources included FCC equipment authorization databases, METI measurement law certification registries, EU EMC Directive technical documentation, SEC filings from listed instrument manufacturers, and customs trade data for oscilloscope import flows. Bottom-up channel checks triangulated against top-down market sizing across bandwidth tiers and regional demand clusters.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and technology substitution effects. Segmentation dimensions modeled include product architecture, bandwidth tier, end-use vertical, application intensity, and geographic regulatory cluster. CAGRs derive from instrument replacement cycle velocity, incoming inspection lab expansion rates, and wide-bandgap semiconductor deployment trajectories. Industry-specific forecast inputs incorporate EV powertrain validation timelines and 5G base station deployment schedules.
Underlying assumptions cover sustained indium phosphide foundry capacity utilization, stable FCC Part 15 enforcement intensity, and continued automotive electrification program funding, with deviation risk concentrated in semiconductor export control expansions and III-V substrate supply disruptions. Revision becomes warranted when wide-bandgap semiconductor qualification timelines accelerate beyond modeled parameters or when cloud-native instrument adoption crosses thirty percent penetration in enterprise procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Test Benches Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
RFID Tester Market