
 Melt Flow Tester Market | 2026-2036
Melt Flow Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Melt Flow Tester Market Outlook
Automated data logging and cloud-connected calibration is reconfiguring how melt flow testers integrate into smart factory environments. Instron leverages its universal testing platform architecture to anchor polymer characterization workflows across North American and European laboratories. Dynisco competes through specialized melt pressure instrumentation that extends into inline rheology applications for extrusion processors. ZwickRoell sustains its position via precision servo-drive technology that dominates high-throughput automotive supplier labs in Germany.
A melt flow tester measures the rate of extrusion of thermoplastics through a standardized die under controlled temperature and load conditions, typically reporting results in grams per ten minutes per ASTM D1238 or ISO 1133 protocols. The instrument serves as a critical quality gate for resin batch approval, compound development, and incoming raw material verification across polymer supply chains. Capillary-type instruments occupy the largest installed base due to their alignment with legacy lab infrastructure and broad regulatory acceptance, while automatic configurations represent the fastest-expanding segment as packaging and automotive verticals pursue reduced operator variability. Polyethylene testing generates the highest absolute instrument utilization given the material's dominance in film, blow molding, and pipe applications where melt index directly predicts processability.
ISO 1133 and ASTM D1238 frame the baseline compliance environment for melt flow testing, with FDA 21 CFR Part 11 data integrity requirements shaping instrument software specifications for pharmaceutical packaging suppliers. China's SAMR enforces GB/T 3682 standards for domestic polymer certification, creating localized demand for dual-protocol instruments capable of simultaneous ISO and GB compliance reporting. REACH and RoHS substance restrictions in Europe are elevating the importance of batch-level polymer traceability, directly expanding melt flow verification scope across electronics and consumer goods supply chains. Stakeholders must evaluate whether their instrument portfolios can support evolving multi-standard compliance without redundant capital deployment.
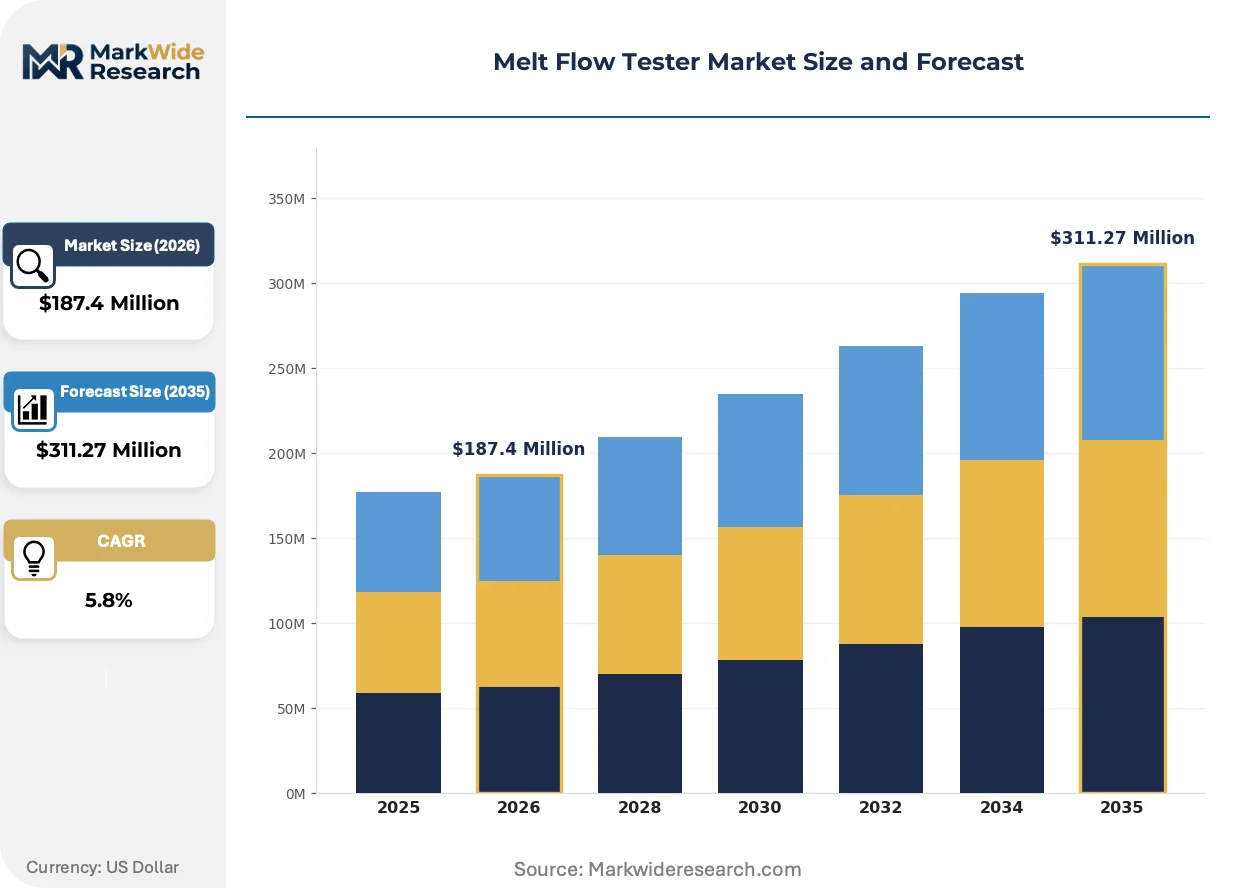
Market Dynamics
Smart factory integration is compressing test cycle times and forcing melt flow instrumentation vendors to embed edge computing directly into capillary rheometer architectures. This structural pressure favors suppliers capable of delivering ISO 1133-compliant data streams into MES and LIMS environments without middleware translation layers.
Growth Catalysts
- China's GB/T 3682 enforcement:SAMR mandates dual-protocol certification for domestic polymer producers, forcing instrument replacement cycles in Shandong and Jiangsu provinces.
- Automotive lightweighting:German OEMs require batch-level melt index verification for every thermoplastic compound entering structural component supply chains.
- Cloud calibration networks:Remote metrology services reduce downtime for high-throughput packaging labs in São Paulo and Mumbai industrial corridors.
Market Restraints
- Platinum thermocouple volatility:Sensor element costs fluctuate with precious metal markets, compressing gross margins on temperature-critical instrument configurations.
- Single-source die manufacturing:Precision carbide extrusion dies concentrate among German and Japanese specialty toolmakers, creating supply vulnerability.
- ISO 1133-2 method complexity:The multi-weight testing protocol demands operator training investments that smaller compounders defer indefinitely.
Strategic Opportunities
- Vietnam's polymer processing expansion:Foreign direct investment into Ho Chi Minh City packaging clusters outpaces local metrology infrastructure, creating first-mover instrument placement potential.
- Recycled resin qualification:Post-consumer polyethylene batch variability demands melt flow characterization at sorting facilities, extending the addressable instrument base beyond traditional resin producers.
- EU CSRD material traceability:Corporate sustainability reporting mandates drive polymer processors to document batch-level rheological properties for scope 3 emissions calculations.
Industry Challenges
- Rheology technician scarcity:Polymer science programs in US Midwest manufacturing regions graduate fewer instrument operators than automotive supplier labs require.
- Legacy LIMS integration:1990s-era laboratory information management systems in European compounders resist API connections to modern melt flow data architectures.
- Multi-standard certification timelines:Simultaneous ISO 1133, ASTM D1238, and GB/T 3682 validation protocols extend new instrument commissioning by four to six weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melt Flow Tester Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary, Rotary, Dual-processor, Automatic Application: Quality Control, Research & Development, Production, Academic Material: Polyethylene, Polypropylene, Polystyrene, Nylon Industry Vertical: Packaging, Automotive, Consumer Goods, Electronics |
| Companies Covered | Instron, Tinius Olsen, Dynisco, ZwickRoell, GÖTTFERT, Qualitest, Industrial Physics, Presto, Karg Industrietechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melt Flow Tester Market Strategic Shifts
Real-time polymer characterization is migrating from quality laboratories onto production floors, compressing the feedback loop between extrusion parameters and material verification. This spatial reconfiguration demands instrument architectures that tolerate vibration, temperature cycling, and operator skill variation without sacrificing ASTM D1238 precision.
Capillary rheometry with embedded edge computing is digitizing how polymer processors correlate melt index measurements to in-line extrusion pressure data. Automotive suppliers in Stuttgart and Detroit deploy these units directly beside compounding lines, eliminating the thirty-to-sixty minute lag between sampling and batch release decisions. The resulting data density enables predictive viscosity models that anticipate screw wear before dimensional drift appears in finished components.
REACH Article 33 substance disclosure requirements are compelling electronics manufacturers to document polymer composition at the batch level, extending melt flow testing scope into supply chain verification workflows. German cable producers now require suppliers to attach ISO 1133 test certificates to every polyethylene delivery, creating instrument demand at converter facilities previously exempt from laboratory capital expenditure. The compliance burden falls heaviest on mid-tier compounders serving multiple OEMs with divergent documentation templates.
Buyer consolidation among North American packaging conglomerates is compressing vendor qualification cycles and unbundling after-sales service contracts from instrument procurement. Procurement teams at Atlanta and Chicago headquarters now negotiate enterprise-wide calibration agreements separate from hardware acquisition, favoring suppliers with national field service networks over regional distributors. This disintermediation threatens traditional dealer margins while rewarding direct manufacturer relationships capable of delivering standardized metrology across dispersed plant footprints.
Melt Flow Tester Market Segmentation
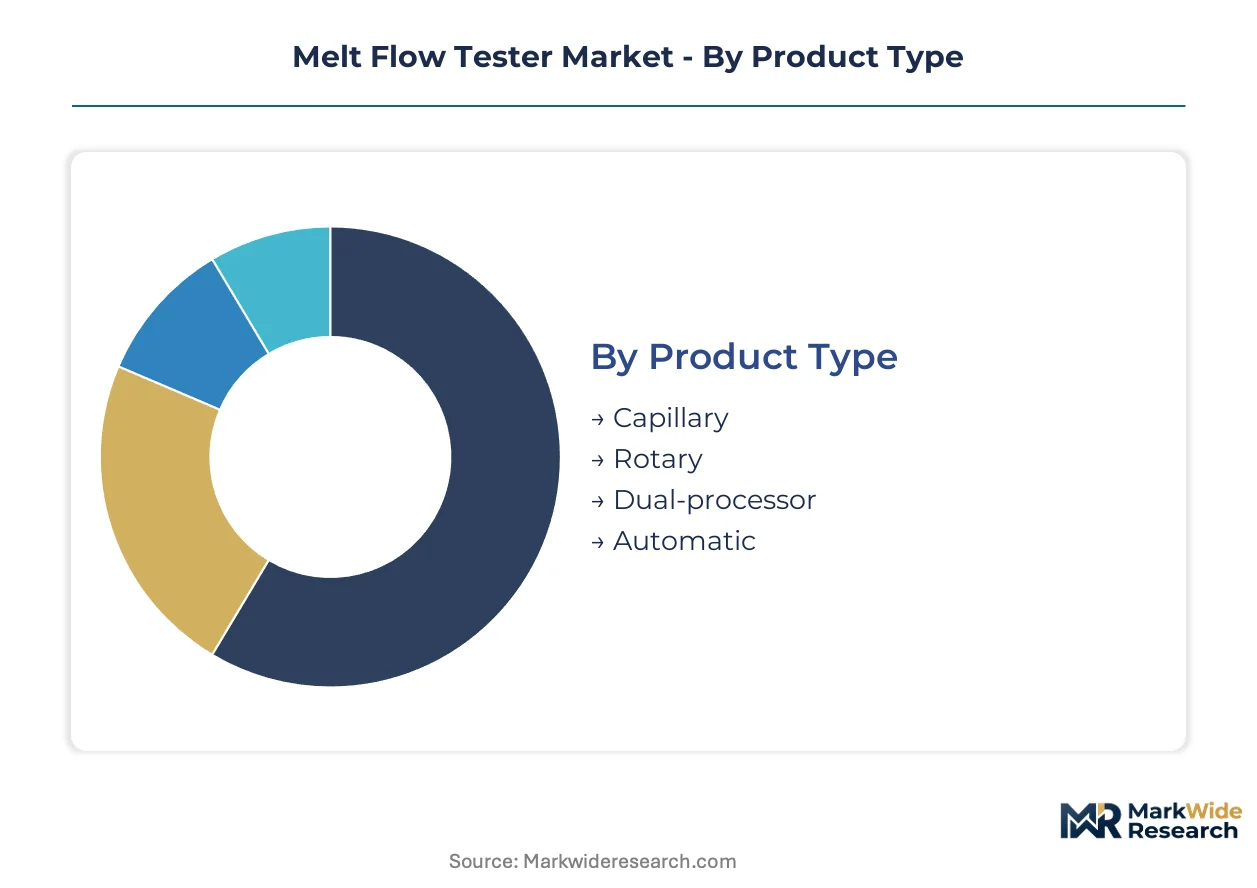
Melt flow tester procurement cycles vary dramatically by segment, with production-floor installations turning over every five to seven years while academic laboratories retain instruments for fifteen years or more. Understanding these replacement rhythms helps vendors align service contracts and upgrade pathways to actual customer behavior.
Product Type:
Capillary instruments command the longest replacement cycles due to their mechanical simplicity and broad standard acceptance, while automatic configurations refresh fastest as packaging labs chase throughput gains.
- Capillary:These instruments rely on precision-bore dies and calibrated piston assemblies to extrude molten polymer under standardized load conditions. German automotive supplier labs in Stuttgart and Wolfsburg maintain extensive capillary fleets for ISO 1133 batch certification, though their conservative upgrade timelines limit near-term revenue potential for vendors.
- Automatic:Servo-driven sample handling and integrated data logging compress test cycle times from twenty minutes to under eight. Demand concentrates in São Paulo and Mumbai packaging corridors where high-throughput film producers require continuous melt index verification without dedicated technician oversight.
- Rotary:Specialized configurations for high-viscosity engineering polymers serve niche compounder requirements.
- Dual-processor:Simultaneous ISO 1133 and GB/T 3682 compliance reporting addresses China's SAMR certification mandates.
Capillary configurations dominate installed base. Automatic configurations concentrate expansion.
Application:
Production applications generate the highest instrument utilization rates with near-continuous operation, while academic deployments sit idle for semester breaks.
- Quality Control:Incoming resin verification and batch release decisions demand rapid turnaround with minimal operator judgment. Chinese polymer producers in Shandong province deploy dedicated QC stations at warehouse receiving docks to enforce SAMR material compliance before compounds enter production.
- Production:Inline or at-line installations beside extrusion lines enable real-time viscosity feedback. Detroit automotive suppliers position melt flow testers adjacent to compounding equipment, eliminating the lag between sampling and screw parameter adjustment.
- Research & Development:Method development and new compound formulation require flexible temperature and load programming.
- Academic:Polymer science curricula in Midwest US universities maintain legacy instruments for instructional laboratories.
Production applications drive replacement velocity. Quality Control anchors revenue stability.
Material:
Polyethylene testing generates the highest absolute instrument wear due to film industry volume, while nylon characterization demands specialized temperature capabilities that extend sales cycles.
- Polyethylene:Low-density and linear-low-density grades dominate film, blow molding, and pipe applications where melt index directly predicts processability. Shenzhen packaging clusters operate dedicated polyethylene testing cells running three shifts to support export-oriented film production.
- Polypropylene:Automotive interior and under-hood applications require melt flow verification for every compound batch. German OEMs mandate polypropylene characterization at Tier-2 suppliers across Bavaria and Lower Saxony.
- Polystyrene:Electronics housings and food service applications drive moderate testing demand.
- Nylon:Engineering polymer applications in automotive and industrial components require elevated temperature configurations.
Polyethylene testing dominates throughput volume. Polypropylene is climbing the fastest.
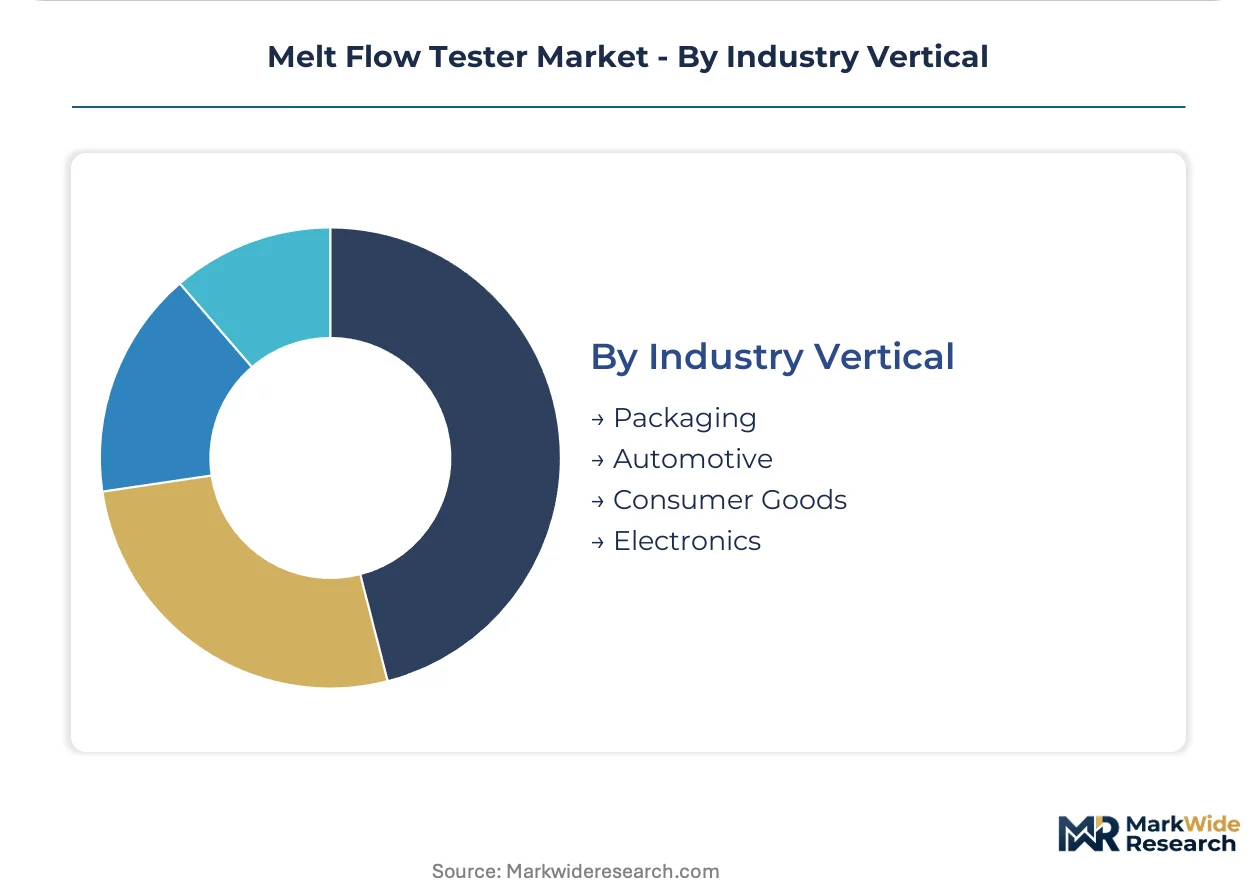
Industry Vertical:
Packaging procurement concentrates purchasing authority at headquarters level, while automotive buying fragments across dispersed supplier parks.
- Packaging:Film extruders and blow molders require high-throughput melt index verification for resin batch approval. Ho Chi Minh City packaging clusters attract foreign direct investment that outpaces local metrology infrastructure, creating placement opportunities for first-mover instrument vendors.
- Automotive:Structural component lightweighting mandates batch-level thermoplastic verification. German OEMs require melt index certificates attached to every compound delivery, extending instrument demand to converter facilities previously exempt from laboratory capital expenditure.
- Consumer Goods:Appliance and furniture applications drive moderate quality control requirements.
- Electronics:REACH Article 33 substance disclosure compels cable and connector manufacturers to document polymer composition.
Packaging vertical concentrates throughput demand. Automotive vertical is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net polymer trade flows concentrate instrument demand in export-oriented manufacturing economies while import-dependent regions maintain smaller replacement markets. Germany and China post substantial polymer processing surpluses that sustain dense metrology infrastructure, whereas deficit markets like India and Brazil absorb instruments primarily through foreign direct investment channels.
Germany
Automotive lightweighting mandates from BMW, Mercedes-Benz, and Volkswagen require batch-level melt index verification for every thermoplastic compound entering structural component supply chains. REACH substance disclosure rules under ECHA enforcement compel cable and connector manufacturers to document polymer composition at delivery. Stuttgart and Wolfsburg industrial corridors host extensive capillary instrument fleets serving Tier-1 and Tier-2 supplier parks.
China
SAMR enforcement of GB/T 3682 standards mandates dual-protocol certification for domestic polymer producers, accelerating instrument replacement cycles in Shandong and Jiangsu provinces. The country's dual carbon goals pressure resin producers to document batch-level rheological properties for emissions calculations. Shanghai and Shenzhen packaging clusters operate dedicated polyethylene testing cells running continuous shifts to support export-oriented film production.
United States
Automotive supplier labs in Detroit and Chicago deploy melt flow testers adjacent to compounding equipment to eliminate lag between sampling and screw parameter adjustment. FDA 21 CFR Part 11 data integrity requirements shape instrument software specifications for pharmaceutical packaging suppliers in the Midwest. Packaging conglomerates headquartered in Atlanta negotiate enterprise-wide calibration agreements separate from hardware acquisition.
India
Bureau of Indian Standards polymer certification requirements create localized demand for ISO 1133-compliant instruments at resin import facilities. Maharashtra and Gujarat industrial corridors attract foreign direct investment into polymer processing that outpaces local metrology infrastructure. Mumbai packaging labs pursue high-throughput automatic configurations to reduce operator variability in film extrusion quality control.
Vietnam
Foreign direct investment into Ho Chi Minh City packaging clusters outpaces local metrology infrastructure, creating first-mover instrument placement potential for vendors with regional service networks. Electronics manufacturers supplying EU markets face REACH Article 33 documentation requirements that extend testing scope to converter facilities. The polymer processing expansion concentrates in export processing zones near the southern industrial corridor.
Melt Flow Tester Market Competitive Environment
On the supply side, the industry is moderately consolidated around precision instrumentation specialists with deep regulatory compliance expertise. European and North American vendors anchor the premium tier through legacy laboratory relationships, while Asian fabricators compete on cost-optimized configurations for emerging market packaging corridors. Two strategic archetypes dominate: universal testing platform providers extending into polymer characterization, and specialized rheology instrument houses with dedicated melt pressure expertise. Competitive moves concentrate on cloud-connected calibration networks and smart factory integration capabilities that compress test cycle times.
Among established European instrumentation houses, Instron and ZwickRoell occupy positions within the universal testing platform archetype, leveraging servo-drive architectures that span multiple materials characterization workflows. Dynisco exemplifies the specialized melt pressure instrumentation tier, with product lines extending into inline rheology applications for extrusion processors. These three companies represent the dominant competitive anchors against which regional and specialty vendors position alternative value propositions.
| Leading Market Players |
|---|
| Instron |
| Tinius Olsen |
| Dynisco |
| ZwickRoell |
| GÖTTFERT |
| Qualitest |
| Industrial Physics |
| Presto |
| Karg Industrietechnik |
| Others |
Value Chain & Pricing Dynamics
Platinum thermocouple volatility compresses gross margins on temperature-critical instrument configurations while simultaneously widening spreads between premium servo-drive architectures and economy piston assemblies. This commodity exposure forces vendors to tier pricing around thermal stability specifications and source precision carbide dies through concentrated German and Japanese specialty toolmakers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 1133 certification grade and after-sales service bundling, with pharmaceutical packaging suppliers in the US Midwest demonstrating lowest price sensitivity due to FDA 21 CFR Part 11 compliance mandates. Pricing pressure stems from buyer consolidation among North American packaging conglomerates unbundling calibration contracts from hardware acquisition. Mid-tier compounders serving multiple automotive OEMs face the steepest cost compression as procurement teams negotiate enterprise-wide metrology agreements.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for precision instrumentation vendors. Manufacturing concentrates in Germany, Japan, and the United States for servo-drive assemblies and carbide extrusion dies. Raw material dependencies span platinum sensor elements, precision-bore tungsten carbide, and high-temperature alloy furnace components. Distribution runs through regional field service networks rather than traditional dealer channels, with direct manufacturer relationships displacing third-party distributors in high-throughput packaging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ISO 1133, ASTM D1238, and GB/T 3682 certification requirements create switching costs that protect incumbent positions across automotive and pharmaceutical verticals.
For Market Incumbents: Pre-empt cloud-connected calibration networks before emerging Asian fabricators capture aftermarket service revenue in Vietnam and India packaging corridors. Backward integration into precision die manufacturing reduces vulnerability to single-source German and Japanese toolmakers. Certification investment in simultaneous multi-standard validation protocols extends commissioning timelines but deepens customer captivity. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City packaging clusters where foreign direct investment outpaces local metrology infrastructure. Target recycled resin qualification workflows at post-consumer polyethylene sorting facilities, an addressable instrument base beyond traditional resin producers. Lead with automatic configurations featuring integrated data logging to reduce operator variability in high-throughput film extrusion environments. For Investors and Strategic Acquirers: EU CSRD material traceability mandates reshape the acquisition landscape by extending melt flow verification scope into scope 3 emissions documentation. Long-term viability favors specialized rheology instrument houses with dedicated melt pressure expertise over universal testing platform providers facing commoditization pressure. Watch for SAMR enforcement intensity in Shandong and Jiangsu provinces as the signal indicating replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Network Deployment | Remote metrology services reduce downtime for São Paulo and Mumbai packaging labs. |
| Dual-Protocol Certification Investment | Simultaneous ISO 1133 and GB/T 3682 compliance captures China's SAMR-mandated replacement cycles. |
| Inline Rheology Integration | Edge-computing capillary architectures serve Detroit automotive suppliers' real-time viscosity feedback requirements. |
| Recycled Resin Qualification Workflows | Post-consumer polyethylene batch variability extends instrument demand to sorting facilities. |
| Precision Die Manufacturing Backward Integration | In-house carbide extrusion die production mitigates single-source vulnerability to German and Japanese toolmakers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ISO certification databases, customs trade data, and SEC instrument manufacturer filings. Conversations with polymer laboratory managers, automotive Tier 1 procurement officers, packaging plant engineers, and aftermarket service technicians informed demand-side validation. Bottom-up instrument shipment analysis triangulates against top-down polymer processing capacity estimates across export-oriented manufacturing economies.
Forecast inputs incorporate product type segmentation across capillary, automatic, and dual-processor configurations; application segmentation spanning quality control, production, and research deployments; and material segmentation weighted by polyethylene and polypropylene testing intensity. CAGRs derive from replacement cycle analysis calibrated to regulatory enforcement timelines and smart factory integration adoption curves. Industry-specific inputs include platinum thermocouple price volatility indices and SAMR certification mandate implementation schedules.
Sensitivities concentrate around SAMR enforcement intensity in Chinese provinces, REACH Article 33 documentation scope expansion, and cloud calibration network adoption rates in emerging market packaging corridors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
DSL Tester Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
RFID Tester Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Scratch Testers Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Creep and Stress Rupture Testers Market