
 Video Test Equipment Market | 2026-2036
Video Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Video Test Equipment Market Analytics
The direct sales channel is narrowing as vendors consolidate relationships with large broadcast groups and telecom operators. Keysight Technologies leverages its precision instrumentation heritage to anchor high-end R&D contracts. Tektronix sustains brand loyalty among broadcast engineers through deep calibration service networks. Rohde & Schwarz competes on RF test integration, extending its footprint in satellite and terrestrial broadcast verification.
Video test equipment comprises instruments that measure, generate, and analyze video signals across parameters including resolution, color accuracy, latency, and signal integrity, serving critical quality assurance functions in content production and distribution infrastructure. Waveform monitors and video analyzers occupy the core of current procurement cycles as facilities validate HDR and wide-color-gamut pipelines. IP technology segments are expanding fastest where broadcasters migrate from baseband SDI to packet-based SMPTE ST 2110 and NMOS architectures. Signal generators retain stable demand in manufacturing test environments, though margin pools have shifted toward software-defined and networked instrumentation platforms.
FCC broadcast spectrum rules, SMPTE engineering standards, and CE marking requirements collectively shape product compliance burdens and refresh cycles for equipment vendors. The EPA Energy Star program and evolving EU Ecodesign regulations are tightening power consumption thresholds for rack-mounted test systems. Stakeholders must weigh capital deployment timing against the accelerating obsolescence of pure-SDI instrument portfolios as IP-native production becomes the default architecture.
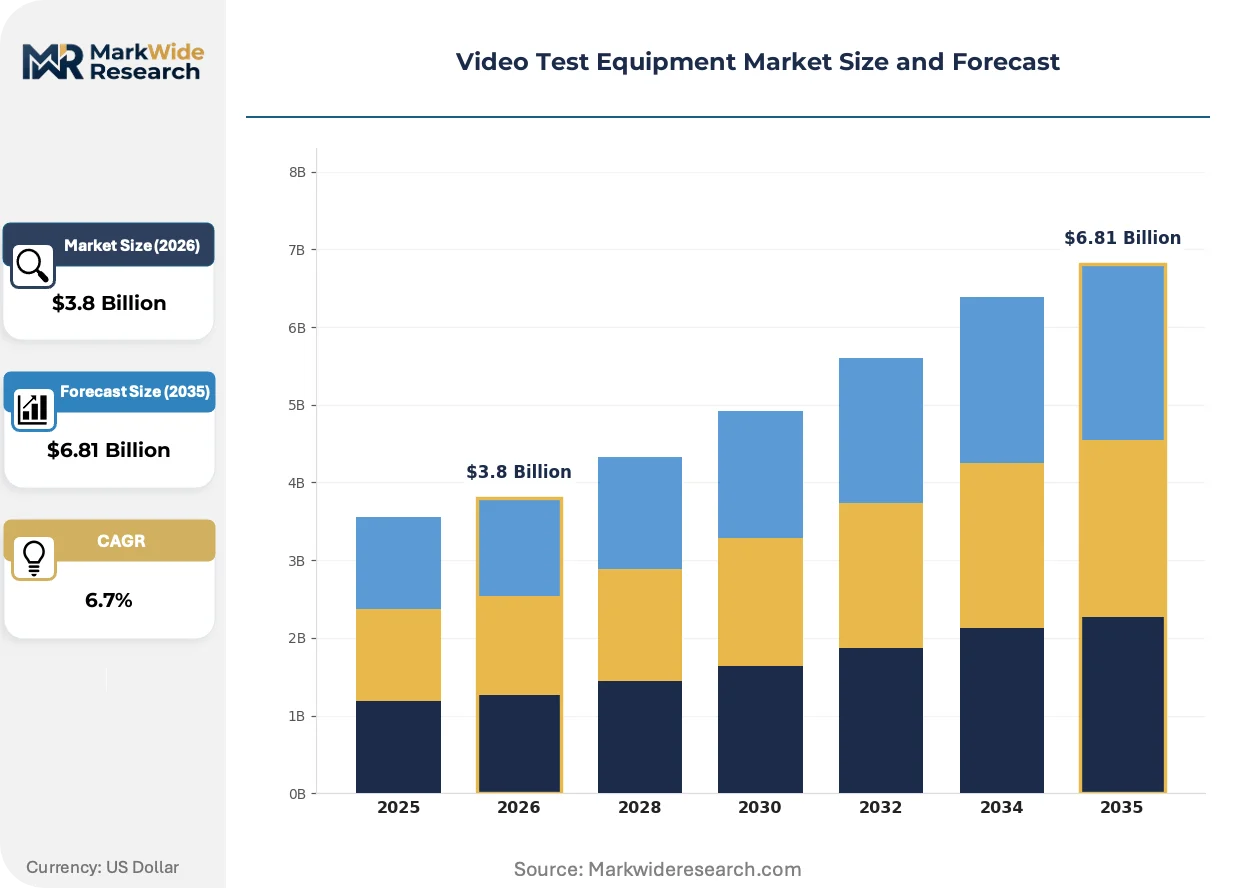
Market Dynamics
The migration from SDI to IP-based SMPTE ST 2110 infrastructure is compressing refresh cycles and forcing vendors to recalibrate hardware-software roadmaps around software-defined architectures.
Growth Catalysts
- Broadcast Infrastructure Modernization:Major networks in the United States are replacing legacy baseband systems with IP-native production chains, triggering synchronized procurement of waveform monitors and packet analyzers.
- SMPTE ST 2110 Standardization:The technical framework is eliminating interoperability friction between equipment vendors, reducing integration costs for facility engineers.
- Streaming Platform Expansion:Direct-to-consumer services are building redundant origination centers that require continuous signal verification across geographically distributed nodes.
Market Restraints
- Capital Intensity of IP Transition:Full facility overhauls demand simultaneous replacement of cameras, routers, and test systems, stretching broadcaster capex budgets across multiple fiscal years.
- Specialized Engineering Talent Scarcity:The shallow pool of technicians fluent in both broadcast video and IP networking protocols is constraining deployment velocity for complex installations.
- Prolonged SDI Asset Lifecycles:Operational 3G-SDI equipment with remaining depreciation schedules is delaying authorization for comprehensive infrastructure replacement.
Strategic Opportunities
- Cloud-Native Production Hubs:Remote production workflows are creating demand for portable, network-attached test instruments that engineers can deploy at temporary event venues.
- Energy Efficiency Mandates:The EPA Energy Star program and EU Ecodesign regulations are incentivizing development of lower-power rack-mounted systems that reduce facility cooling loads.
- Esports and Live Event Verticals:Non-traditional broadcasters operating temporary production environments represent an underpenetrated customer segment with compressed decision cycles.
Industry Challenges
- Multi-Standard Verification Complexity:Engineers must simultaneously validate HDR, wide-color-gamut, and high-frame-rate signals across hybrid SDI-IP facilities, expanding test procedure scope.
- Calibration Service Network Gaps:Precision instrument maintenance requires factory-trained technicians, and geographic coverage holes are extending equipment downtime in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Test Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Signal Generators, Waveform Monitors, Video Analyzers, Distribution Amplifiers Technology: HDMI, SDI, IP, Analog End User: Broadcast, Post-Production, Education, Telecom Application: Quality Assurance, Troubleshooting, Calibration, Content Creation |
| Companies Covered | Keysight Technologies, Tektronix, Rohde & Schwarz, National Instruments Corporation, VIAVI Solutions, Anritsu Corporation, EXFO, Teledyne LeCroy, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Test Equipment Market Evolving Landscape
Software-defined instrumentation is collapsing the distinction between hardware instruments and analytics platforms, enabling remote diagnostics and subscription-based feature activation that alters vendor revenue models.
Packet-based video analysis is digitizing the core function of signal monitoring, converting waveform and vector display processing from dedicated FPGA hardware to GPU-accelerated software running on standard servers. Post-production facilities and mobile production trucks are adopting these virtualized instruments fastest, drawn by reduced rack space and rapid reconfiguration. This shift is digitizing the traditional test equipment supply chain, compressing margins on dedicated hardware while expanding recurring software revenue pools.
The FCC's broadcast spectrum repack and evolving emission standards are tightening RF verification requirements for transmission equipment manufacturers. These rules are extending test protocol duration and demanding more sophisticated adjacent-channel power measurement capabilities. Terrestrial broadcast transmitter vendors in the United States are responding by integrating RF test modules directly into factory calibration lines.
Equipment-as-a-service arrangements are displacing capital purchase models among mid-sized production companies that prioritize operational flexibility over asset ownership. Rental houses and systems integrators are expanding managed service offerings that bundle instruments with calibration and firmware update commitments. This pattern is most pronounced in Germany and the United Kingdom, where broadcast service providers face pressure to reduce balance-sheet weight.
Video Test Equipment Market Segmentation
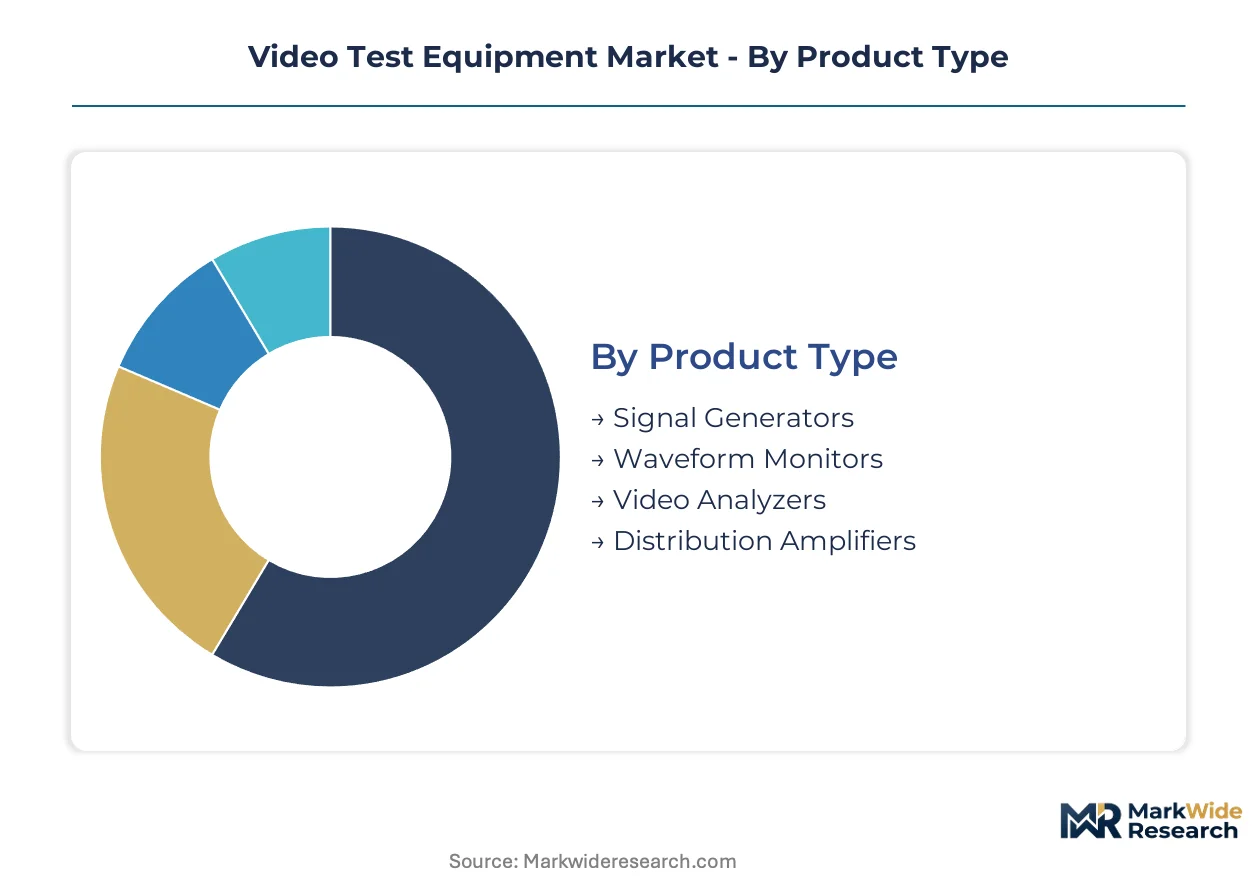
Video test equipment procurement patterns diverge sharply across technical specifications, deployment environments, and operational workflows. Understanding these divisions reveals where capital concentrates and which technology transitions command premium pricing.
Product Type:
Mature hardware categories coexist with emerging software-defined platforms across the product spectrum.
- Waveform Monitors:These instruments visualize luminance and chrominance levels through graphical displays, serving as the primary reference for colorists and broadcast engineers validating HDR pipelines. Facilities in the United States upgrading to 4K and 8K workflows are expanding procurement of IP-enabled waveform monitors with touch-panel interfaces. FCC broadcast spectrum compliance requirements are extending calibration cycles for these precision instruments.
- Video Analyzers:Multi-parameter measurement systems evaluate resolution accuracy, color gamut fidelity, and signal integrity across compressed and uncompressed formats. Post-production houses in Los Angeles and New York are prioritizing analyzers with automated test sequence capabilities to accelerate content validation throughput. The EPA Energy Star program is tightening power consumption thresholds for rack-mounted analyzer systems.
- Signal Generators:Reference pattern sources for manufacturing test environments and facility alignment procedures.
- Distribution Amplifiers:Signal conditioning and replication hardware for multi-point monitoring architectures.
Waveform monitors retain volume leadership; video analyzers hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy infrastructure investments from next-generation platform commitments.
- IP:Packet-based SMPTE ST 2110 and NMOS architectures are displacing baseband transport across greenfield broadcast facilities. Major networks in the United States are synchronizing router and test system procurement around these standards to eliminate interoperability friction. Software-defined instrumentation running on standard servers is collapsing hardware margins while expanding recurring firmware revenue pools.
- SDI:Serial digital interface transport remains entrenched in facilities with remaining depreciation schedules on 3G-SDI infrastructure. Operational equipment lifecycles are delaying comprehensive replacement authorization despite IP migration roadmaps. Calibration service networks for SDI-specific instruments face geographic coverage gaps in secondary United States markets.
- HDMI:Consumer interface technology for prosumer and educational deployment environments.
- Analog:Legacy composite and component signal support for archive restoration and compatibility testing.
SDI retains installed-base dominance; IP platforms are expanding most quickly across new capital deployment.
End User:
Application intensity varies across customer types with diverging technical sophistication and procurement authority.
- Broadcast:National networks and local affiliates operate the most instrument-dense facilities, with redundant signal verification chains across master control and origination centers. Streaming platform operators building geographically distributed nodes are driving demand for network-attached test instruments with remote diagnostic capabilities. SMPTE ST 2110 standardization is reducing integration costs for these large-scale deployments.
- Post-Production:Color grading suites and finishing facilities prioritize compact, high-precision analyzers for HDR and wide-color-gamut pipeline validation. Mobile production trucks are adopting virtualized instruments fastest, drawn by reduced rack space and rapid reconfiguration.
- Telecom:Infrastructure operators verifying video-over-IP service quality across packet networks.
- Education:Training programs and university media labs with constrained capital budgets.
Broadcast commands the highest equipment density per facility; post-production is gaining share fastest through virtualization adoption.
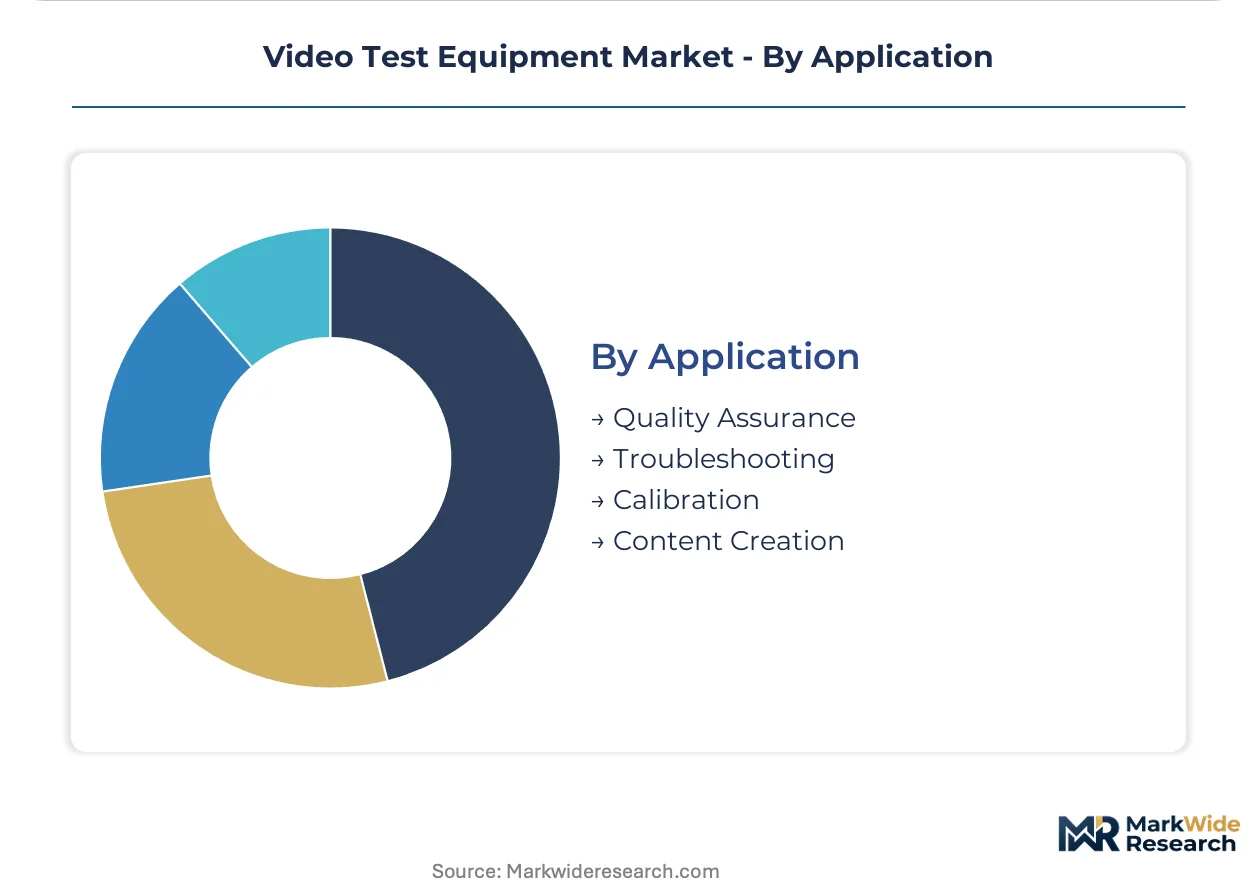
Application:
Margin concentration tracks operational criticality and regulatory exposure across use cases.
- Quality Assurance:Continuous signal monitoring for compliance with FCC emission standards and network carriage agreements. Terrestrial broadcast transmitter vendors in the United States are integrating RF test modules directly into factory calibration lines to satisfy tightening adjacent-channel power measurement requirements.
- Calibration:Precision instrument alignment requiring factory-trained technicians and traceable reference standards. Geographic coverage holes in service networks are extending equipment downtime in secondary markets.
- Troubleshooting:Diagnostic procedures for fault isolation in hybrid SDI-IP facilities.
- Content Creation:Production-phase signal verification for live event and studio capture environments.
Quality assurance retains the highest compliance-driven renewal rates; calibration services are climbing fastest as instrument complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the most instrument-dense broadcast infrastructure globally, with fiber-optic trunk lines connecting major production hubs to distribution networks. National networks and streaming platforms are synchronizing router and test system procurement around SMPTE ST 2110 standards. This infrastructure underwrites sustained demand for IP-native waveform monitors and packet analyzers.
United States
Major broadcast networks and streaming platforms are modernizing master control facilities with redundant signal verification chains. FCC broadcast spectrum repack rules are tightening RF verification requirements for transmitter equipment manufacturers. Los Angeles and New York post-production clusters are prioritizing analyzers with automated test sequences to accelerate HDR pipeline validation.
Germany
Broadcast service providers face pressure to reduce balance-sheet weight through equipment-as-a-service arrangements. EU Ecodesign regulations are tightening power consumption thresholds for rack-mounted test systems. Munich and Cologne production centers are expanding managed service offerings that bundle instruments with calibration commitments.
United Kingdom
Post-production houses are adopting virtualized instruments fastest, drawn by reduced rack space and rapid reconfiguration. CE marking requirements shape product compliance burdens and refresh cycles for equipment vendors. London's Soho district remains the densest concentration of color grading suites requiring compact, high-precision analyzers.
Japan
Manufacturing test environments retain stable demand for signal generators despite margin shifts toward software-defined platforms. METI industrial standards influence precision instrument calibration protocols and traceability requirements. Tokyo and Osaka electronics clusters anchor factory calibration lines for terrestrial broadcast transmitter vendors.
South Korea
Telecom infrastructure operators are verifying video-over-IP service quality across packet networks with expanding scope. The country's national broadcast regulator maintains emission standards that extend test protocol duration for transmission equipment. Seoul's media technology corridor is integrating RF test modules directly into production workflows.
Video Test Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with deep calibration service networks and precision instrumentation heritage. Three archetypes dominate: precision measurement specialists leveraging R&D contracts, broadcast-focused incumbents sustaining brand loyalty through service density, and RF integration leaders extending into satellite verification. Competitive moves concentrate on portfolio diversification toward software-defined architectures and strategic partnerships to bridge SDI-IP hybrid transitions.
Among precision instrumentation specialists, Keysight Technologies and Tektronix exemplify divergent anchoring strategies. Keysight occupies a position tied to high-end R&D contract capture through measurement science credibility. Tektronix sits within the broadcast engineer loyalty tier, sustained by dense calibration service networks. Rohde & Schwarz represents the RF integration archetype, with German GmbH structure signaling engineering-heavy organizational heritage.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix |
| Rohde & Schwarz |
| National Instruments Corporation |
| VIAVI Solutions |
| Anritsu Corporation |
| EXFO |
| Teledyne LeCroy |
| Fluke Corporation |
| Others |
Value Network & Pricing Analysis
Munich and Cologne production centers anchor European manufacturing capacity for precision test instrumentation, concentrating FPGA sourcing and calibration service infrastructure. This geographic clustering grants incumbent vendors pricing power over IP-native waveform monitors while compressing margins on legacy SDI hardware through excess inventory liquidation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation anchored in calibration certification grade and after-sales service bundling. Premium tiers command sustained pricing through factory-traceable alignment protocols and SMPTE ST 2110 compliance validation. Cost compression in standard-tier signal generators is intensifying because software-defined platforms displace dedicated hardware. Post-production houses exhibit highest price sensitivity due to constrained capital budgets, while national broadcast networks prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for FPGA and high-speed ADC components. Manufacturing concentrates in Germany, Japan, and the United States, with precision analog front-ends drawing from Japanese semiconductor foundries. Raw material dependencies span rare-earth magnets for RF shielding, specialized ceramics for connector assemblies, and copper alloys for signal path integrity. Single-source vulnerability persists for radiation-hardened components used in satellite verification equipment. Distribution runs through authorized systems integrators and direct vendor relationships with major broadcast groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The video test equipment market sits at an inflection driven by the FCC broadcast spectrum repack and accelerating SMPTE ST 2110 standardization, compressing refresh cycles and collapsing the hardware-software boundary.
For Market Incumbents: Harden defensive moats by deepening calibration service network density in secondary United States markets where geographic coverage gaps extend competitor equipment downtime. Accelerate software-defined instrumentation roadmaps to capture recurring firmware revenue pools before pure-hardware margins erode further. Prioritize backward integration into FPGA firmware development to reduce dependency on external semiconductor vendors. For New Entrants and Emerging Players: Build out portable, network-attached test instrument portfolios targeting esports and live event verticals where temporary production environments demand rapid deployment and compressed procurement cycles. White-space concentration sits in cloud-native production hubs requiring remote diagnostic capabilities across geographically distributed nodes. Pursue equipment-as-a-service arrangements with mid-sized production companies prioritizing operational flexibility over asset ownership. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because calibration service network density and precision instrumentation heritage constitute defensible intangible assets with high switching costs. Target acquisition archetypes include RF integration specialists with satellite verification footprints and software-defined platform developers with GPU-accelerated signal processing IP. Monitor FCC enforcement patterns on broadcast spectrum compliance as the inflection signal indicating refresh cycle acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Migration | Converts waveform processing from FPGA hardware to GPU-accelerated server software, collapsing rack space requirements. |
| Calibration Service Network Expansion | Closes geographic coverage gaps in secondary markets, reducing equipment downtime and locking in maintenance revenue. |
| IP-Native Instrument Certification | Ensures SMPTE ST 2110 and NMOS interoperability, eliminating integration friction for facility engineers. |
| Equipment-as-a-Service Launch | Addresses balance-sheet reduction pressure among German and UK broadcast service providers through subscription models. |
| Energy Efficiency Redesign | Responds to EPA Energy Star and EU Ecodesign thresholds, reducing facility cooling loads and compliance risk. |
Research Methodology
The analysis maps waveform monitors, video analyzers, signal generators, and IP-based instrumentation platforms, each validated through broadcast engineers, post-production facility managers, systems integrators, and calibration service technicians. Primary interviews with these stakeholders combined with secondary validation from FCC rulemaking dockets, SMPTE engineering standards documentation, EPA Energy Star program specifications, and SEC filings of precision instrumentation vendors. Bottom-up equipment procurement tracking and top-down facility infrastructure surveys provided triangulation across market sizing dimensions.
Assumptions held fixed include SMPTE ST 2110 adoption velocity among major US networks, FCC spectrum repack enforcement timelines, and EU Ecodesign regulatory stringency, while variables tested included software-defined platform penetration rates and equipment-as-a-service model adoption. The analytical framework modeled product type, technology architecture, end-user segment, and application intensity across the projection horizon. CAGRs derived from facility replacement cycle analysis, capital expenditure pipeline tracking, and technology transition elasticity estimates, with inputs from HDR pipeline validation requirements and IP infrastructure deployment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native production hub operators or hyperscaler-backed entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Burst Strength Tester Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Metrology Software Market