
 Industrial X-Ray CT Inspection Systems for Complex Metal Components Market | 2026-2036
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market Insights
Direct sales from OEMs to aerospace and defense contractors is tilting toward bundled service contracts with recurring software upgrades. Nikon Metrology leverages its metrology heritage to anchor high-precision installations across European aerospace clusters. Waygate Technologies sustains broad channel coverage through a hybrid direct-and-distributor model spanning heavy machinery fabricators. Comet Yxlon competes on tube-source vertical integration, controlling critical component supply for high-energy systems.
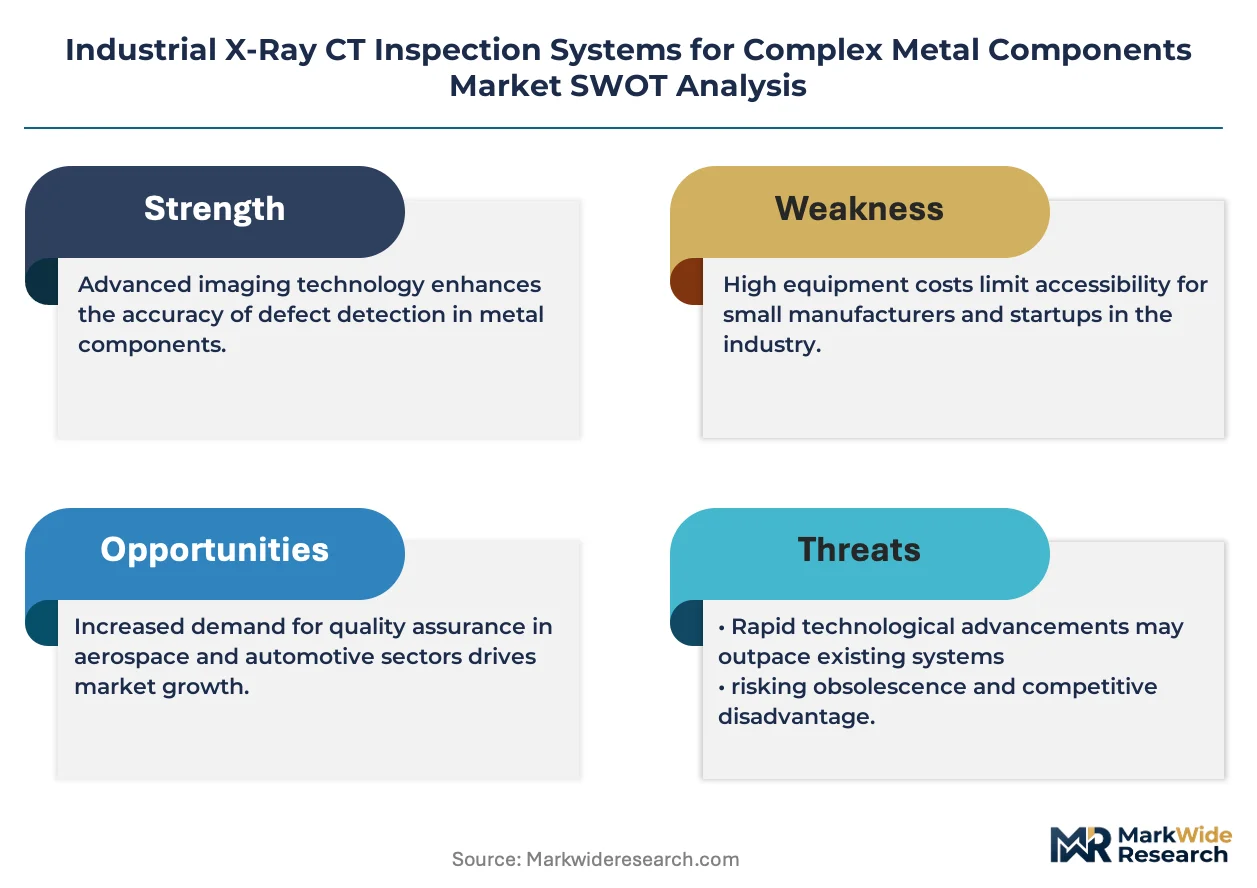
Industrial X-Ray CT inspection systems for complex metal components employ X-ray sources generating penetrating radiation that detectors capture from multiple angles, reconstructing three-dimensional volumetric data through computed tomography algorithms to reveal internal porosity, crack networks, and dimensional deviations without sectioning the part. These systems serve primary industrial purposes in quality assurance workflows where destructive testing would scrap high-value castings, forgings, or additively manufactured aerospace superalloy components. Microfocus CT dominates current installed base value due to its resolution sweet spot for turbine blade cooling channels, while inline CT represents the fastest-expanding segment as automotive Tier-1 suppliers embed real-time validation at production takt rates. High-speed CT occupies a specialized margin pool serving energy equipment suppliers inspecting thick-walled pressure vessel forgings where throughput constraints previously excluded CT methods.
FAA damage tolerance regulations and EASA certification standards for safety-critical metal parts mandate traceable inspection records, directly expanding CT system procurement among aerospace manufacturers and their approved suppliers. The EU AI Act's risk-classification framework for automated defect recognition algorithms shapes R&D priorities for European vendors developing machine-learning-enhanced analysis software. Stakeholders must monitor how NIST measurement traceability requirements for advanced manufacturing evolve, as these standards will determine which CT platforms qualify for defense contractor procurement lists and which analytical capabilities become baseline expectations.
Market Dynamics
The market pivots on additive manufacturing qualification protocols, where aerospace OEMs now mandate volumetric CT validation for every safety-critical metal part before flight clearance. This regulatory-technology nexus compresses inspection cycles from batch sampling to 100% part verification.
Growth Catalysts
- FAA Damage Tolerance Mandates:Updated airworthiness directives require traceable CT records for all turbine disc and blade castings, forcing MRO facilities and prime manufacturers to expand high-energy system capacity.
- Automotive Inline Integration:German powertrain suppliers embed microfocus CT stations at machining line exits, converting quality gates from offline labs to takt-synchronized validation points.
- Additive Manufacturing Porosity Detection:Electron beam and laser powder bed fusion processes generate subsurface void networks invisible to surface methods, making CT the sole viable qualification pathway for flight hardware.
Market Restraints
- Tungsten Target Supply Concentration:High-performance rotating anode production concentrates among three specialized metallurgical suppliers, exposing tube-source OEMs to price volatility and allocation risk.
- Detector Scintillator Lead Times:Cesium iodide and gadolinium oxysulfide crystal growth capacity constraints extend flat-panel detector delivery to 26-32 weeks, throttling system build rates.
- Computational Bottleneck:Reconstruction of multi-gigabyte datasets from high-resolution scans exceeds real-time processing capabilities at production line speeds, limiting inline CT to lower-density alloys.
Strategic Opportunities
- India Defense Industrial Corridor:Indigenization mandates under the country's aerospace manufacturing push create first-mover advantage for vendors establishing local service infrastructure and calibration laboratories.
- AI-Enhanced Defect Recognition:Machine learning classification of porosity morphologies against fatigue life models enables predictive rejection thresholds, differentiating software platforms from commodity hardware.
- Energy Sector Forging Inspection:Thick-walled reactor pressure vessel segments previously excluded from CT protocols now fall within high-speed system penetration ranges, opening nuclear and hydrogen infrastructure qualification workflows.
Industry Challenges
- AS9100D CT Procedure Standardization:Aerospace suppliers struggle to harmonize inspection parameters across customer-specific source requirements, forcing redundant qualification runs and capital duplication.
- Radiation Safety Officer Certification Scarcity:Qualified personnel capable of licensing and operating Class II X-ray installations remain concentrated in established industrial regions, constraining facility expansion into emerging manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial X-Ray CT Inspection Systems for Complex Metal Components Market |
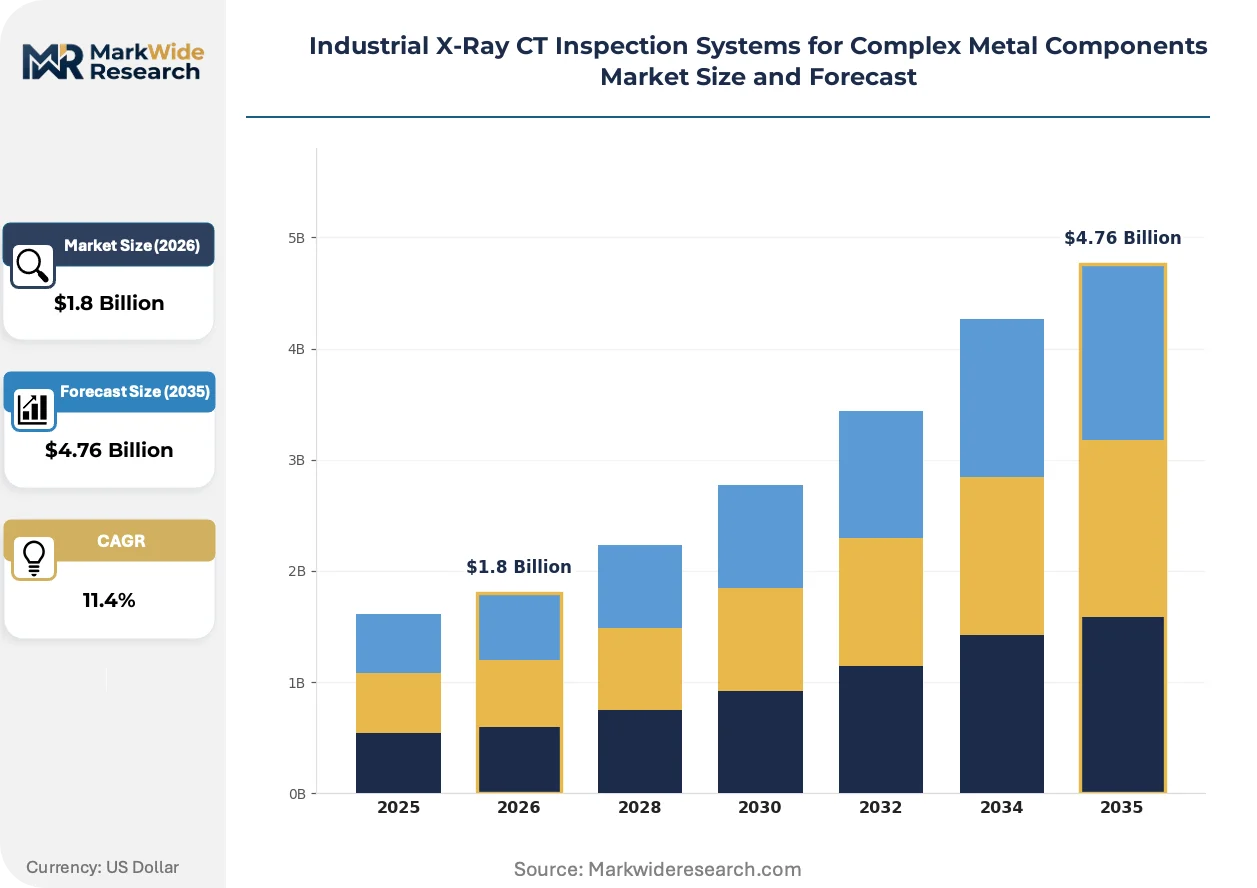
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfocus CT, Nanofocus CT, High-Speed CT, 3D Tomography, Inline CT Technology: Computed Tomography, Digital Radiography, Cone Beam CT, Fan Beam CT, X-Ray Fluoroscopy Application: Defect Detection, Dimensional Measurement, Material Characterization, Assembly Verification, Failure Analysis End User: Aerospace Manufacturers, Defense Contractors, Energy Equipment Suppliers, Heavy Machinery Fabricators, Automotive Tier-1 Suppliers |
| Companies Covered | Nikon Metrology, Waygate Technologies, Comet Yxlon, Nordson, ZEISS, North Star Imaging, VJ Technologies, VisiConsult X-ray Systems & Solutions, WENZEL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market Trends and Innovations
Inspection workflows are converging with digital manufacturing execution systems, creating closed-loop quality architectures where CT data feeds directly into machining compensation algorithms and digital twin models.
Photon-counting detector arrays are digitizing spectral imaging capabilities previously requiring dual-energy scans. Aerospace casting houses in France and the UK adopt these systems to distinguish tungsten inclusions from shrinkage porosity in single acquisition passes. The technology is digitizing material characterization throughput, compressing alloy qualification cycles from weeks to hours.
The EU AI Act's risk classification framework for automated defect recognition algorithms is reshaping software development priorities. European CT vendors now architect explainable AI pipelines where classification decisions trace to specific voxel intensity thresholds, satisfying conformity assessment body documentation requirements. Medical device and aerospace suppliers face the stiffest compliance burden, driving preference for pre-validated analytical modules.
Service contract unbundling is fragmenting traditional hardware-software bundles. Japanese automotive Tier-1 suppliers now procure CT platforms through equipment lessors while subscribing to cloud-based reconstruction and analysis tools from specialized software houses. This bifurcation concentrates in high-volume stamping and casting operations where utilization rates justify operational expenditure models over capital deployment.
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market Segmentation
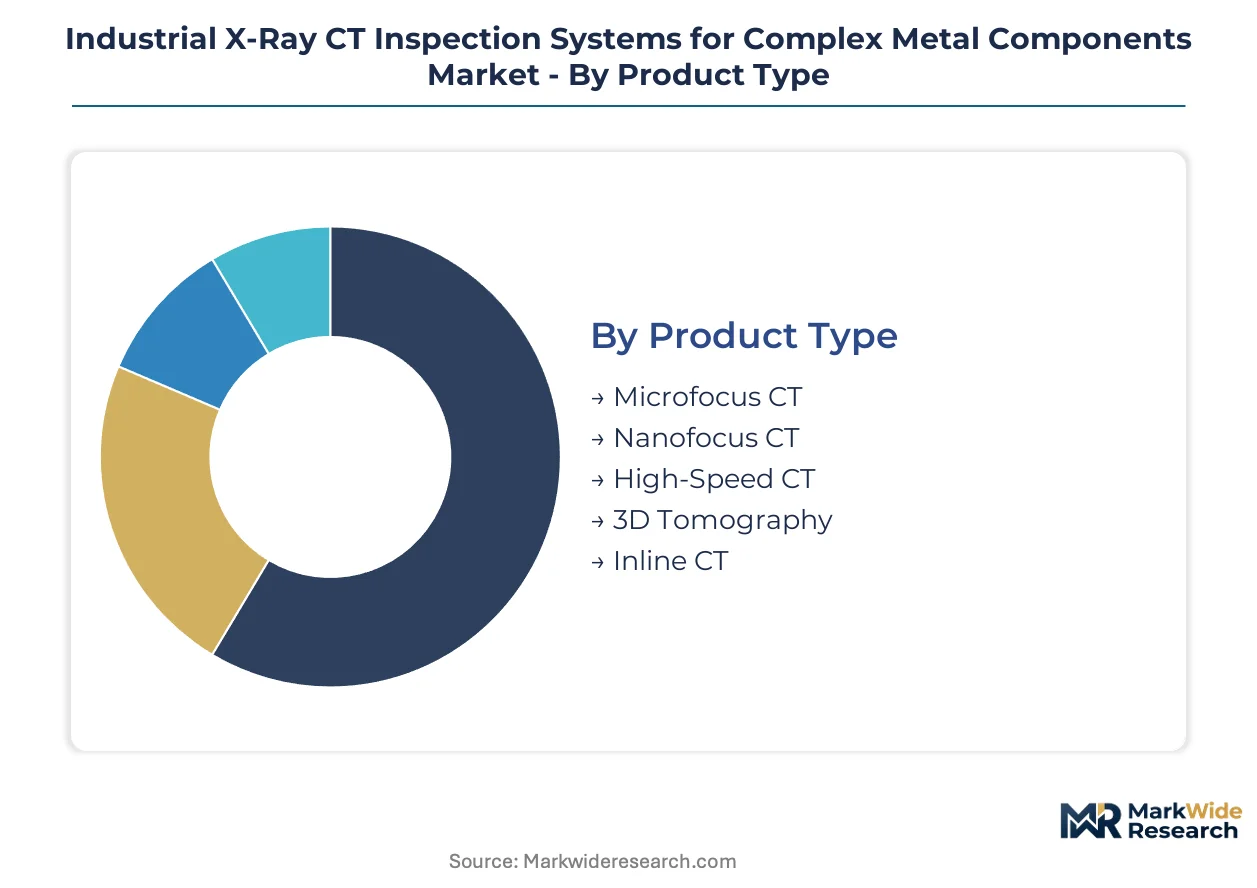
Segmentation in this market tracks how inspection requirements diverge across precision thresholds, throughput demands, and regulatory stringency. Each dimension shapes capital deployment patterns and vendor technology roadmaps differently.
Product Type:
Cost tier stratification separates laboratory-grade precision systems from production-floor throughput equipment, with distinct margin profiles and replacement cycles at each level.
- Microfocus CT:These systems deploy sub-micron focal spot X-ray tubes to resolve cooling channel geometries in single-crystal turbine blades. Aerospace casting houses in Germany and France anchor demand as EASA certification standards mandate 100% volumetric validation for safety-critical superalloy components.
- Inline CT:Real-time reconstruction engines synchronized to machining line takt rates enable part-by-part validation without buffer inventory. German powertrain suppliers embed these stations at transmission housing machining exits, converting quality gates from offline laboratories to production-integrated checkpoints.
- Nanofocus CT:Sub-500nm resolution targets micro-electronics packaging and precision medical device implants.
- High-Speed CT:Optimized for thick-walled pressure vessel forgings where penetration power supersedes resolution requirements.
- 3D Tomography:Legacy reconstruction platforms serving research institutions and failure analysis laboratories.
Microfocus CT commands the established base. The steepest expansion runs through Inline CT.
Technology:
Application context determines which radiation geometry and detector architecture delivers actionable data, with aerospace defect detection favoring different technical approaches than automotive volume inspection.
- Computed Tomography:Full 360-degree rotational acquisition with filtered back-projection reconstruction generates isotropic voxel datasets for quantitative porosity analysis. FAA damage tolerance directives require this modality for traceable turbine disc inspection records, forcing MRO facilities to upgrade from radiographic film.
- Cone Beam CT:Flat-panel detector arrays capture complete volumetric datasets in single rotations without slice-by-slice translation. French and UK aerospace casting houses adopt photon-counting variants to distinguish tungsten inclusions from shrinkage porosity in single acquisition passes.
- Digital Radiography:Two-dimensional projection imaging for rapid screening applications where 3D reconstruction adds unnecessary cycle time.
- Fan Beam CT:Linear detector arrays with collimated X-ray beams optimized for high-density alloy penetration.
- X-Ray Fluoroscopy:Real-time video-rate imaging for assembly verification and dynamic component motion analysis.
Computed Tomography retains the revenue majority. Cone Beam CT gains share fastest where material discrimination drives purchasing decisions.
Application:
Functional purpose shapes system specification more than any other dimension, with defect detection tolerances often an order of magnitude stricter than dimensional measurement requirements.
- Defect Detection:Automated porosity classification algorithms identify subsurface void networks invisible to surface inspection methods. Electron beam and laser powder bed fusion additive manufacturing processes generate these defects unpredictably, making CT the sole viable qualification pathway for flight hardware before FAA clearance.
- Dimensional Measurement:Voxel-based coordinate metrology validates complex internal geometries against CAD nominal without destructive sectioning. Automotive transmission suppliers deploy this capability for helix gear tooth profile verification.
- Material Characterization:Dual-energy and spectral imaging quantify phase fractions and density variations in metal matrix composites.
- Assembly Verification:Post-assembly inspection confirms proper seating of bearings, seals, and press-fit components.
- Failure Analysis:Forensic reconstruction of crack propagation paths in returned field components.
Defect Detection absorbs the largest capital allocation. Dimensional Measurement climbs fastest as digital thread integration demands closed-loop feedback.
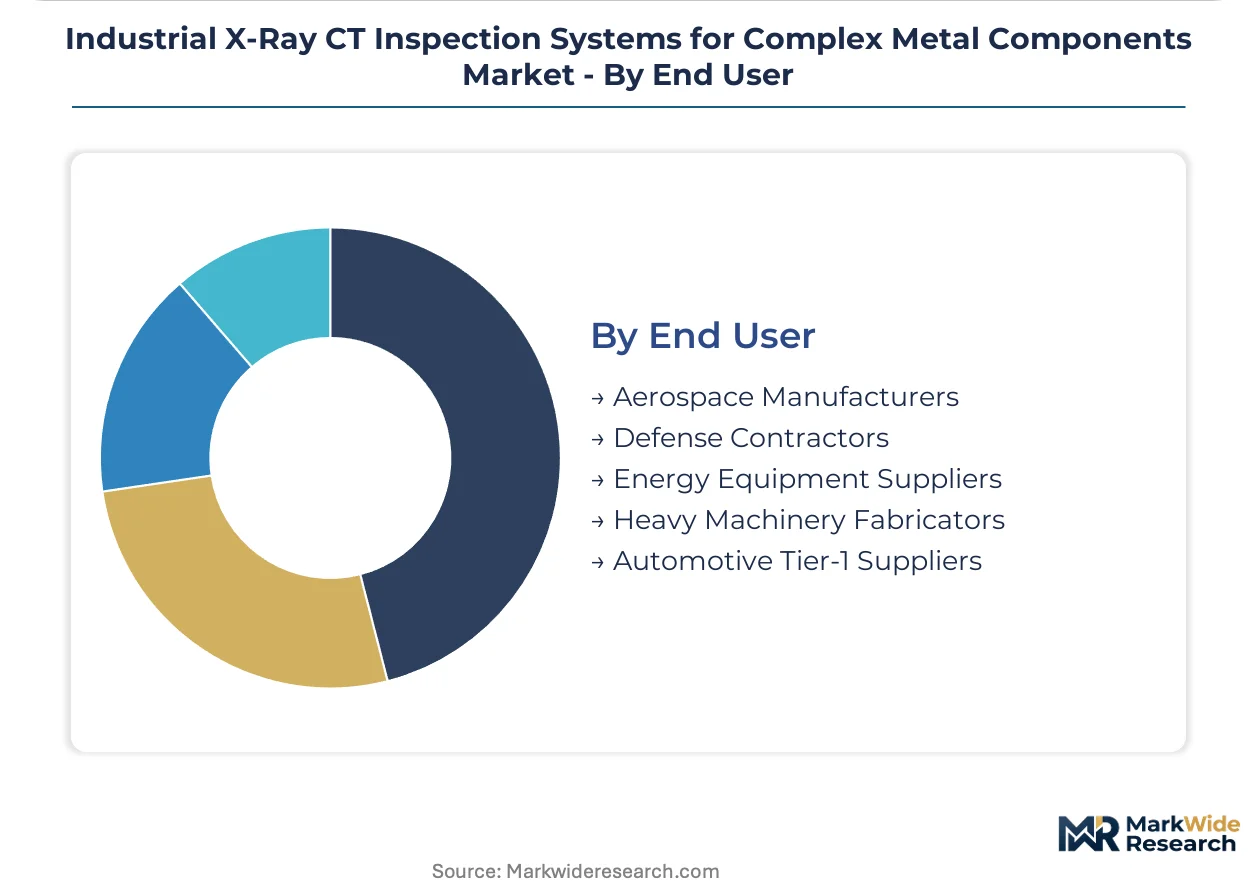
End User:
Customer type concentration follows defense procurement cycles, commercial aerospace production rates, and automotive electrification capital deployment patterns.
- Aerospace Manufacturers:Prime contractors and their approved suppliers operate the most stringent inspection protocols, with additive-manufactured turbine blades now requiring volumetric CT validation for every safety-critical part before flight clearance. This regulatory-technology nexus compresses inspection cycles from batch sampling to 100% part verification.
- Automotive Tier-1 Suppliers:Powertrain and chassis component manufacturers integrate inline CT at machining line exits to eliminate offline laboratory bottlenecks. German suppliers lead this transition, embedding real-time validation at production takt rates.
- Defense Contractors:Classified program requirements and NIST measurement traceability mandates shape procurement specifications.
- Energy Equipment Suppliers:Nuclear and hydrogen infrastructure qualification workflows for thick-walled reactor pressure vessel segments.
- Heavy Machinery Fabricators:Mining and construction equipment casting producers with lower precision tolerances but higher part masses.
Aerospace Manufacturers dominate current installed value. Automotive Tier-1 Suppliers expand capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive Tier-1 suppliers command pricing premiums for inline CT integration that Mexican heavy machinery fabricators cannot replicate, creating a transatlantic margin asymmetry that shapes vendor deployment priorities.
Germany
Powertrain manufacturers in Baden-Württemberg and Bavaria embed microfocus CT stations at machining line exits for transmission housing validation. The KBA enforces type-approval documentation standards that mandate traceable inspection records for safety-critical castings. Stuttgart's automotive cluster leads Europe in takt-synchronized quality gate conversion from offline laboratories to production-integrated checkpoints.
United States
Aerospace OEMs in the Pacific Northwest and Southeast defense corridors expand high-energy system capacity for turbine disc inspection. FAA damage tolerance directives require volumetric CT validation for every additive-manufactured blade before flight clearance. Wichita's aviation manufacturing cluster concentrates MRO facility upgrades driven by updated airworthiness mandates.
China
Domestic aviation programs and nuclear equipment qualification drive demand for thick-walled forging inspection capabilities. SAMR measurement traceability requirements shape procurement specifications for defense contractor supplier lists. Shanghai's aerospace manufacturing base accelerates CT adoption for electron beam powder bed fusion component validation.
India
Defense industrial corridor indigenization mandates create first-mover opportunities for vendors establishing local service infrastructure. CEA radiation safety licensing requirements constrain facility expansion pace in emerging manufacturing clusters. Bengaluru's aerospace and defense supplier ecosystem builds CT qualification capacity for indigenous fighter jet and helicopter programs.
France
Aerospace casting houses adopt photon-counting detector arrays to distinguish tungsten inclusions from shrinkage porosity in single acquisition passes. EASA certification standards for safety-critical superalloy components mandate 100% volumetric validation protocols. Toulouse's aviation manufacturing cluster integrates spectral imaging capabilities for alloy qualification cycle compression.
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market Competitive Landscape
Precision-metrology heritage and tube-source vertical integration split the market into distinct capability camps. The vendor base concentrates among European and Japanese industrial measurement specialists with established aerospace channel relationships. Two strategic archetypes dominate: metrology-platform extenders leveraging coordinate measurement heritage, and radiation-source specialists controlling critical component supply chains. Competitive moves center on service contract unbundling and AI-enhanced software module differentiation.
Within the metrology-platform tier, Nikon Metrology and ZEISS anchor European aerospace cluster penetration through precision-installation expertise. Waygate Technologies occupies a position across heavy machinery fabricators via hybrid channel architecture. Comet Yxlon exemplifies the radiation-source specialist archetype through captive anode tube production.
| Leading Market Players |
|---|
| Nikon Metrology |
| Waygate Technologies |
| Comet Yxlon |
| Nordson |
| ZEISS |
| North Star Imaging |
| VJ Technologies |
| VisiConsult X-ray Systems & Solutions |
| WENZEL Group |
| Others |
Pricing and Supply Chain Analysis
Tungsten target supply concentration among three specialized metallurgical suppliers determines both the premium spread for high-energy CT systems and the geographic shape of component sourcing networks. This single-source dependency forces tube-source OEMs to absorb price volatility or pass through allocation risk, compressing margins at the standard-equipment tier while amplifying premiums for configured-to-order aerospace installations.
Pricing Analysis
Configured-to-order pricing for aerospace-qualified systems commands spreads of 40-60% above standard automotive inline configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with AS9100D-compliant analytical modules and FAA-traceable documentation driving the top tier. Cost compression in the standard-equipment segment intensifies as Chinese detector manufacturers enter the flat-panel market. Automotive Tier-1 suppliers exhibit the highest price sensitivity, prioritizing throughput metrics over resolution specifications, while defense contractors accept premium positioning for NIST-traceable measurement chains.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for detector array procurement. Manufacturing concentration rests on Germany, Japan, and the United States for precision rotation stages and high-voltage power supplies. Raw material dependencies include tungsten-rhenium alloy targets, cesium iodide scintillator crystals, and high-purity aluminum housing castings. Single-source vulnerability in rotating anode metallurgy exposes tube-source OEMs to 26-32 week lead time extensions. Distribution runs through hybrid direct-and-distributor models, with European aerospace clusters favoring factory-direct metrology partnerships and Asian automotive markets channeling through regional equipment lessors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling transforms hardware margins into recurring software and calibration revenue streams expanding faster than system sales. Cloud-based reconstruction subscriptions and AI-enhanced defect recognition modules now represent the fastest-growing revenue layer.
For Market Incumbents: Harden defensive positions by deepening captive supply of rotating anode tubes through backward integration into tungsten-rhenium metallurgy, insulating against allocation risk from the three dominant suppliers. Expand high-touch service infrastructure across India's defense industrial corridor before indigenization mandates lock in local competitors. Certification investment in EU AI Act-compliant explainable AI pipelines will differentiate analytical software from commodity reconstruction engines.
For New Entrants and Emerging Players: India's defense industrial corridor offers the most penetrable geographic white space, with CEA radiation safety licensing requirements creating barriers that favor first-movers establishing calibration laboratories and field service networks. Target the automotive inline segment through equipment-leasing partnerships that convert capital expenditure models to operational expenditure, mirroring Japanese Tier-1 procurement patterns. A software-first go-to-market angle—selling cloud-based reconstruction and AI classification modules independent of hardware—sidesteps detector supply bottlenecks.
For Investors and Strategic Acquirers: The EU AI Act's risk-classification framework for automated defect recognition algorithms reshapes the acquisition landscape, elevating software platforms with pre-validated analytical modules above commodity hardware vendors. Five-to-ten year viability favors targets with installed base density in aerospace clusters, where regulatory mandates ensure replacement demand and service attach rates. The signal to watch is NIST measurement traceability requirement evolution, which will determine which CT platforms qualify for defense contractor procurement lists and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anode Metallurgy | Tungsten-rhenium captive supply insulates Waygate Technologies and Comet Yxlon from allocation risk. |
| AI-Enhanced Defect Recognition Platform Launch | Machine learning porosity classification satisfies EU AI Act documentation requirements for aerospace suppliers. |
| India Defense Corridor Service Infrastructure | Local calibration laboratories capture indigenization mandates before competitor facility establishment. |
| Equipment Leasing Partnership Model | Operational expenditure conversion aligns with Japanese automotive Tier-1 procurement preferences. |
| Photon-Counting Detector Array Integration | Spectral imaging capability distinguishes tungsten inclusions from shrinkage porosity for French casting houses. |
Research Methodology
Operator-level perspectives from CT system operators at aerospace casting houses, automotive powertrain quality engineers, radiation safety officers, and aftermarket service technicians anchored the qualitative base. Primary interview findings combined with secondary validation from FAA airworthiness directives, EASA certification standards, SAMR measurement traceability guidelines, and EU AI Act regulatory texts. Customs data on X-ray tube and flat-panel detector trade flows, alongside SEC filings from industrial measurement OEMs, provided supply-side calibration. Bottom-up equipment deployment counts across German automotive clusters and US defense corridors triangulated against top-down market sizing from capital expenditure disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with optimistic and conservative bounds reflecting additive manufacturing adoption velocity and defense procurement cycle timing. Segmentation dimensions modeled include product type tier, application purpose, end-user industry vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycles, inline CT penetration rates in automotive machining lines, and high-speed system adoption for energy sector forgings. Industry-specific forecast inputs incorporated electron beam powder bed fusion qualification protocol evolution and photon-counting detector cost curves.
Practitioners should monitor tungsten target supply allocation announcements, EU AI Act conformity assessment body guidance releases, and NIST advanced manufacturing measurement traceability updates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
HERG Screening Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Atomic Magnetometers Market