
 Global Leak Test Equipment Market | 2026-2036
Global Leak Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Leak Test Equipment Market Foresight
Software-defined calibration and remote diagnostics is repositioning how OEM manufacturers procure leak test systems. ATEQ Corp. leverages its embedded software architecture to lock in recurring service revenue from automotive tier-one suppliers. INFICON sustains technology leadership in helium mass spectrometry through deep R&D investment in ion source miniaturization. Pfeiffer Vacuum anchors European demand with vacuum pump integration that shortens test cycle times for semiconductor wafer processing.
Leak test equipment comprises instruments that quantify seal integrity by detecting and measuring gas or liquid escape from sealed components, typically resolving leak rates down to 10^-9 mbar·l/s in tracer gas configurations. These systems serve critical quality assurance roles where containment failure risks product contamination, refrigerant loss, or safety hazards in pressurized assemblies. Helium mass spectrometry commands the premium tier due to unmatched sensitivity for aerospace assemblies and semiconductor components, while pressure decay dominates volume sales in HVAC systems and food packaging where throughput economics override extreme sensitivity requirements. Acoustic emission technology is gaining share in consumer electronics as manufacturers seek non-destructive methods for waterproofing validation of smartphones and wearables.
FDA container closure integrity guidance and EMA Annex 1 sterile manufacturing revisions are forcing pharmaceutical producers to validate leak detection at production speeds rather than offline sampling. EPA Section 608 refrigerant management rules and F-Gas Regulation phase-down schedules in Europe are expanding mandatory leak testing scope for HVAC systems and industrial refrigeration circuits. Stakeholders must weigh capital intensity against regulatory exposure when selecting between portable field units and inline production systems.
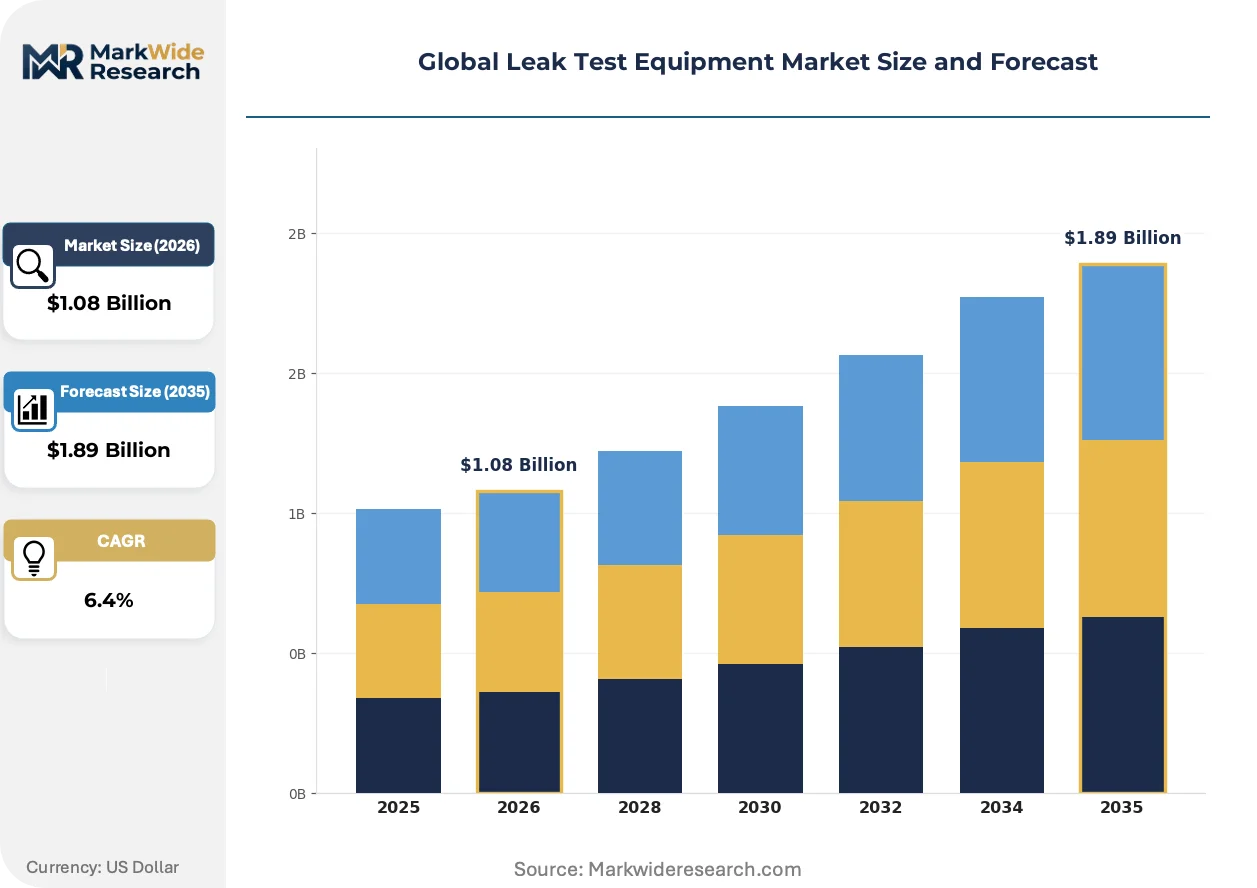
Market Dynamics
Helium mass spectrometry is unifying quality assurance protocols across pharmaceutical sterile manufacturing, compressing test cycle times while forcing legacy pressure decay installations into obsolescence across FDA-inspected facilities in the United States, Germany, and Japan.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:The updated guidance mandates container closure integrity testing at production speeds rather than offline sampling, compelling European pharmaceutical producers to retrofit packaging lines with inline helium detection systems.
- Semiconductor wafer processing expansion:Advanced node fabrication in Taiwan and South Korea requires vacuum-integrated leak detection resolving to 10^-9 mbar·l/s, driving replacement demand for older standalone units.
- Waterproofing validation in consumer electronics:Acoustic emission technology is penetrating smartphone and wearable assembly lines as manufacturers eliminate destructive testing from quality protocols.
Market Restraints
- Helium supply concentration:Global helium refining concentrates in Qatar, Russia, and the United States, exposing equipment operators to price volatility and allocation disruptions that inflate operating costs.
- Capital intensity of inline systems:Semiconductor fabrication-grade helium mass spectrometry installations require seven-figure capital commitments, freezing out mid-tier contract manufacturers from compliance-driven upgrades.
- Technical limitation in high-throughput food packaging:Pressure decay methods face sensitivity ceilings that fail emerging modified atmosphere packaging specifications, trapping processors in equipment replacement cycles.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical manufacturing:CDSCO alignment with FDA container closure integrity standards is creating first-mover advantage for equipment vendors establishing local calibration and service infrastructure.
- Refrigerant management regulatory tailwind:EPA Section 608 enforcement expansion and EU F-Gas Regulation phase-down schedules are mandating leak detection across HVAC service fleets, opening portable device demand.
- Cloud-native remote diagnostics convergence:Embedded software architectures combining edge computing with predictive maintenance algorithms are unlocking recurring revenue streams from automotive tier-one suppliers.
Industry Challenges
- Vacuum pump integration complexity:Semiconductor manufacturers face extended commissioning timelines when mating third-party leak detectors with proprietary wafer handling systems, delaying production ramp schedules.
- Metrology certification bottlenecks:NIST-traceable calibration for pharmaceutical applications requires specialized technician pools that concentrate in Germany, Switzerland, and the United States, constraining deployment velocity elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Leak Test Equipment Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Decay, Helium Mass Spectrometry, Pressure Decay, Bubble Emission, Ultrasonic Leak Detectors, Differential Pressure Technology: Tracer Gas, Acoustic Emission, Mass Spectrometry, Thermal Conductivity, Electrical Conductivity, Optical Inspection Application: Pharmaceuticals, Aerospace Assemblies, Food Packaging, Consumer Electronics, HVAC Systems, Semiconductor Components End User: OEM Manufacturers, Quality Control Laboratories, Contract Testing Providers, Aftermarket Service Centers, Research Institutions, Calibration Facilities |
| Companies Covered | ATEQ Corp., INFICON, Pfeiffer Vacuum, Uson, Vacuum Instruments Corporation, CETA TESTSYSTEME GmbH, LACO Technologies, InterTech Development Company, Cosmo Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Leak Test Equipment Market Shifts & Advancements
Software-defined architectures are compressing hardware differentiation cycles, repositioning competitive advantage toward embedded analytics and predictive service models rather than standalone instrument sensitivity specifications.
Digital twin simulation is unifying offline programming with live production calibration, allowing automotive suppliers to validate test sequences without interrupting assembly line throughput. BMW and Volkswagen manufacturing engineers in Bavaria and Lower Saxony are deploying these virtual commissioning environments to compress new model launch timelines. This capability is unifying equipment procurement decisions around total cost of validation rather than capital expenditure alone.
EMA Annex 1 sterile manufacturing revisions are forcing container closure integrity validation at production speeds, eliminating the historical tolerance for offline statistical sampling. European pharmaceutical producers in Ireland, Switzerland, and Germany are retrofitting blow-fill-seal lines with inline helium mass spectrometry to maintain EMA compliance. Contract packaging organizations are absorbing capital costs to retain qualification for sterile injectable contracts.
Automotive tier-one suppliers are unbundling after-sales service from initial equipment purchases, demanding subscription-based calibration and remote diagnostic access. Continental and Bosch procurement teams in Stuttgart and Hanover are negotiating multi-year service agreements that lock in OEM software update pipelines. This behavioral shift is most visible in German automotive clusters where just-in-sequence manufacturing tolerates zero unplanned downtime.
Global Leak Test Equipment Market Segmentation
Leak test equipment procurement decisions fragment sharply across certification regimes. FDA 21 CFR Part 11 validation requirements govern pharmaceutical installations, while semiconductor fabs demand ISO 14644-1 cleanroom compliance. Equipment vendors must architect product lines around these divergent approval burdens rather than unified performance specifications.
Product Type:
FDA container closure integrity guidance and EMA Annex 1 revisions impose distinct certification loads across detection methodologies. Pharmaceutical sterile manufacturing demands NIST-traceable calibration protocols that pressure decay systems cannot satisfy.
- Helium Mass Spectrometry:Ion source miniaturization has compressed test cycle times to under 30 seconds per vial in blow-fill-seal applications. German and Swiss pharmaceutical producers are retrofitting legacy lines with inline configurations to satisfy EMA Annex 1 production-speed mandates.
- Pressure Decay:Volume displacement measurement dominates HVAC compressor testing and food tray sealing where 10^-3 mbar·l/s sensitivity suffices. EPA Section 608 refrigerant management enforcement is expanding fleet deployment of portable pressure decay units across United States service technicians.
- Vacuum Decay:Non-destructive testing for pre-filled syringes and lyophilized vials.
- Bubble Emission:Visual inspection method for large-volume industrial tanks and pipelines.
- Ultrasonic Leak Detectors:Frequency analysis for pressurized gas systems in chemical processing plants.
- Differential Pressure:Rapid cycle testing for automotive fuel system components.
Pressure Decay sits at the top of the volume ranking, with Helium Mass Spectrometry climbing the fastest.
Technology:
Capital intensity stratifies sharply across detection physics. Mass spectrometry installations demand seven-figure commitments, while acoustic emission systems penetrate at one-tenth the capital threshold.
- Mass Spectrometry:Magnetic sector analyzers resolve to 10^-9 mbar·l/s for semiconductor wafer processing. Taiwan and South Korea fabrication facilities are replacing standalone units with vacuum-integrated configurations to compress test cycle times.
- Tracer Gas:Helium or hydrogen injection methods for hermetic seal validation in aerospace assemblies. Qatar supply concentration exposes operators to allocation volatility that inflates operating costs.
- Acoustic Emission:Structure-borne sound analysis for smartphone and wearable waterproofing validation.
- Thermal Conductivity:Gas-specific detection for refrigerant leak identification.
- Electrical Conductivity:Electrolyte tracer methods for medical device packaging.
- Optical Inspection:Machine vision systems for visible defect detection in transparent containers.
Tracer Gas commands the largest installed base, though Acoustic Emission is expanding most quickly in consumer electronics assembly.
Application:
Regulatory exposure varies dramatically across end-use verticals. Pharmaceutical producers face FDA warning letter risk from container closure failures, while food packagers confront modified atmosphere specification drift.
- Pharmaceuticals:Container closure integrity testing for sterile injectables and biologics. Irish and German contract packaging organizations are absorbing capital costs for inline helium systems to retain EMA qualification.
- Semiconductor Components:Vacuum-integrated leak detection for advanced node wafer processing. Extended commissioning timelines plague manufacturers mating third-party detectors with proprietary wafer handling systems.
- Aerospace Assemblies:Fuel system and propulsion component validation.
- Food Packaging:Modified atmosphere tray sealing and flexible pouch testing.
- Consumer Electronics:IP67 and IP68 waterproofing validation.
- HVAC Systems:Refrigerant circuit testing under EPA and F-Gas Regulation mandates.
Pharmaceuticals sits at the top of the volume ranking, with Semiconductor Components climbing the fastest.
End User:
Procurement authority concentrates differently across organizational types. OEM manufacturers optimize for total cost of validation, while contract testing providers prioritize equipment utilization rates.
- OEM Manufacturers:In-line production integration with just-in-sequence manufacturing tolerances. BMW and Volkswagen procurement teams in Bavaria and Lower Saxony are negotiating multi-year service agreements embedding predictive maintenance algorithms.
- Contract Testing Providers:Third-party validation services for mid-tier pharmaceutical producers lacking capital for captive installations. Metrology certification bottlenecks constrain deployment velocity outside Germany, Switzerland, and the United States.
- Quality Control Laboratories:Offline statistical sampling for batch release testing.
- Aftermarket Service Centers:Portable field units for HVAC and industrial refrigeration maintenance.
- Research Institutions:Custom configurations for materials science and packaging development.
- Calibration Facilities:NIST-traceable reference standards for pharmaceutical applications.
OEM Manufacturers sits at the top of the volume ranking, with Contract Testing Providers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade helium mass spectrometry installations while the United States dominates automotive and HVAC service demand, creating divergent equipment procurement patterns across Atlantic markets.
United States
EPA Section 608 refrigerant management enforcement is expanding portable pressure decay deployment across HVAC service fleets. FDA container closure integrity guidance is retrofitting sterile injectable lines in New Jersey and Massachusetts with inline helium detection. Boston-area biologics manufacturers are absorbing seven-figure capital commitments to maintain FDA inspection readiness.
Germany
EMA Annex 1 sterile manufacturing revisions are compelling Bavarian and Lower Saxony pharmaceutical producers to validate leak detection at production speeds. KBA automotive standards are embedding predictive maintenance algorithms into tier-one supplier procurement contracts. Stuttgart manufacturing clusters are negotiating multi-year service agreements that unbundle calibration from initial equipment purchases.
Japan
PMDA sterile manufacturing standards are displacing pressure decay methods with helium mass spectrometry in Kanto region injectable facilities. METI industrial policy is accelerating semiconductor fabrication expansion in Kyushu, driving vacuum-integrated leak detection demand. Osaka-area electronics assemblers are validating IP67 waterproofing through acoustic emission technology deployment.
China
NMPA pharmaceutical packaging regulations are aligning with FDA container closure integrity protocols in Yangtze River Delta manufacturing zones. MIIT semiconductor self-sufficiency targets are expanding advanced node fabrication in Shanghai and Hefei, requiring 10^-9 mbar·l/s sensitivity systems. Shenzhen consumer electronics clusters are eliminating destructive testing from smartphone assembly quality protocols.
India
CDSCO alignment with FDA standards is creating first-mover advantage for equipment vendors establishing calibration infrastructure in Maharashtra and Gujarat. PLI scheme incentives are expanding pharmaceutical contract manufacturing in Hyderabad and Bangalore. Domestic service technician pools remain concentrated in Western India, constraining deployment velocity elsewhere.
Global Leak Test Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade helium mass spectrometry consolidating around R&D-intensive incumbents while pressure decay fragments across regional fabricators. Three archetypes dominate: vacuum-technology conglomerates with pump integration capabilities, software-defined specialists monetizing recurring service revenue, and precision-instrument heritage players leveraging metrology certification networks. M&A activity concentrates on calibration service networks and embedded software architectures, while geographic expansion targets underpenetrated Indian pharmaceutical manufacturing.
Among European vacuum-technology conglomerates, INFICON and Pfeiffer Vacuum exemplify the R&D-intensive tier, with the former representing ion source miniaturization leadership and the latter anchoring vacuum pump integration advantages that compress semiconductor test cycle times. ATEQ Corp. occupies a distinct position within the software-defined specialist archetype, leveraging embedded architectures to lock in recurring revenue from automotive tier-one suppliers. These three companies collectively span the premium sensitivity and service-contract vectors that are reshaping procurement evaluation criteria.
| Leading Market Players |
|---|
| ATEQ Corp. |
| INFICON |
| Pfeiffer Vacuum |
| Uson |
| Vacuum Instruments Corporation |
| CETA TESTSYSTEME GmbH |
| LACO Technologies |
| InterTech Development Company |
| Cosmo Instruments |
| Others |
Supply & Pricing Matrix
Automotive tier-one suppliers in Stuttgart and Lower Saxony anchor pricing power through multi-year service agreements that unbundle calibration from hardware purchases. This procurement concentration forces equipment vendors toward subscription-based revenue models rather than transactional equipment sales.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for semiconductor-grade helium mass spectrometry systems. Three-tier pricing structure across premium inline configurations, standard standalone units, and economy portable devices stratifies by certification grade and after-sales bundling. Pricing pressure stems from mid-tier contract manufacturers frozen out by seven-figure capital commitments for FDA-validated installations. HVAC service technicians exhibit highest price sensitivity, while pharmaceutical OEMs prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Qatar, Russia, and the United States for helium refining capacity. Ion source miniaturization components draw from German and Swiss precision manufacturing clusters. Vacuum pump assemblies rest on Japanese and German supplier networks. Tariff exposure runs through semiconductor fabrication equipment trade corridors. Distribution runs through authorized service partnerships that concentrate metrology certification in Germany, Switzerland, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors should treat India as a geographic-arbitrage play against saturated German and United States markets, exploiting CDSCO-FDA alignment cost differentials and underdeveloped local calibration infrastructure.
For Market Incumbents: Cement technology leadership through captive ion source manufacturing and predictive maintenance algorithm development. Acquire specialized calibration service networks in Maharashtra and Gujarat before competitors establish NIST-traceable infrastructure. Lock in automotive tier-one suppliers through embedded software architectures that raise switching costs. For New Entrants and Emerging Players: Cloud-native remote diagnostics platforms offer the lowest-friction entry vector into automotive aftermarket services. Target Indian pharmaceutical contract manufacturing in Hyderabad and Bangalore where CDSCO compliance investments outrun local service capacity. Lead with portable pressure decay units for HVAC service fleets under EPA Section 608 enforcement expansion. For Investors and Strategic Acquirers: Vacuum-technology conglomerates are the most active acquirer in this space, consolidating calibration networks and software-defined specialists. Five-to-ten year viability hinges on helium supply diversification and semiconductor fabrication expansion in South Korea and Taiwan. Monitor Qatar helium allocation disruptions as the critical inflection signal for operating cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Acquisition | INFICON and Pfeiffer Vacuum consolidate NIST-traceable service capacity in Germany and Switzerland. |
| Embedded Software Architecture | ATEQ Corp. locks recurring revenue from BMW and Volkswagen procurement teams in Bavaria. |
| Ion Source Miniaturization R&D | Compresses test cycle times below 30 seconds for EMA Annex 1 blow-fill-seal compliance. |
| Indian Service Infrastructure | First-mover vendors establish CDSCO-aligned calibration in Maharashtra and Gujarat. |
| Helium Recycling Technology | Mitigates Qatar supply concentration exposure for pharmaceutical sterile manufacturing operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with pharmaceutical packaging engineers, automotive tier-one procurement managers, semiconductor fabrication technicians, and HVAC service fleet operators combined with secondary validation from FDA warning letter databases, EMA Annex 1 revision texts, EPA Section 608 enforcement records, and SEC filings from listed vacuum technology conglomerates. Bottom-up equipment shipment tracking and top-down end-use demand estimation triangulated market sizing.
Segment-weighting across product type, technology, application, end user, and regional regulatory cluster shaped the analytical framework. Helium mass spectrometry, pressure decay, vacuum decay, and acoustic emission technologies were modeled separately with distinct sensitivity and throughput assumptions. CAGRs were derived from regression analysis against semiconductor wafer processing expansion, pharmaceutical packaging line retrofit cycles, and refrigerant management regulatory enforcement intensity.
Helium supply disruptions, EMA Annex 1 implementation delays, and semiconductor fabrication capital expenditure freezes are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement timelines and equipment replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Pump Testers Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
RFID Tester Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Over-The-Air (OTA) Testing Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Leak Testing Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Digital Weighing Terminal Market