
 AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market | 2026-2036
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market Insights
The capital-intensity divergence between full-suite thermal test platform vendors and point-solution specialists is unwinding competitive dynamics across the sector. inTEST Thermal Solutions leverages deep vertical integration in precision temperature forcing systems to anchor high-margin chip-level engagements. ESPEC sustains dominant positioning in environmental simulation chambers for board-level thermal cycling. Thermotron competes aggressively on delivery speed for custom system integration validation rigs.
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms comprise integrated instrumentation systems that detect, localize, and quantify thermal anomalies in high-performance computing silicon, typically resolving temperature gradients below 0.1°C at spatial resolutions approaching 5 micrometers for advanced packaging nodes. These systems enable predictive thermal design, yield optimization, and reliability qualification across the semiconductor value chain. Infrared cameras and thermal imaging technology lead product and technology segments respectively, capturing the bulk of current procurement value from semiconductor foundries conducting chip-level analysis. Fiber optic sensors represent the fastest-expanding technology category, penetrating board-level testing applications where electromagnetic interference immunity proves decisive. Data acquisition units concentrate margin pools through software-defined analytics layers that lock in recurring service revenue.
The US FCC and EPA jointly shape demand through energy efficiency standards for data center equipment and electromagnetic emissions limits on high-density test instrumentation. The EU AI Act and REACH chemical safety protocols are tightening material disclosure requirements for thermal interface materials deployed in European test labs. Taiwan's national standards body and China's GB standardization regime enforce divergent calibration protocols that fragment cross-border platform certification. Stakeholders must monitor which regulatory jurisdiction's test compliance regime achieves de facto adoption in next-generation co-packaged optics thermal validation protocols.
Market Dynamics
The transition to co-packaged optics and 3D chiplet architectures is compressing thermal validation timelines from months to weeks, forcing foundries to retool metrology workflows around sub-micron resolution requirements.
Growth Catalysts
- Cloud CapEx Surge:Hyperscale operators are expanding AI training infrastructure, creating sustained demand for precision thermal characterization of high-density accelerators during qualification cycles.
- EU AI Act:Energy efficiency disclosure mandates for high-performance computing systems are compelling European labs to upgrade test platforms with calibrated thermal mapping capabilities.
- Advanced Packaging Nodes:TSMC's 3nm and 2nm production ramps in Taiwan are driving procurement of test systems capable of resolving hot spots below 10 micrometers in multi-die configurations.
Market Restraints
- Input Cost Volatility:Indium antimonide and mercury cadmium telluride detector materials face supply constraints from Chinese export controls, inflating infrared camera module costs.
- Geographic Supply Concentration:Precision motion stages and nanopositioning hardware rely heavily on Japanese and German component suppliers, creating single-source vulnerability.
- Calibration Protocol Fragmentation:Divergent national standards between Taiwan's national metrology institute and China's GB regime force redundant certification investments for cross-border platform deployment.
Strategic Opportunities
- India's Semiconductor Mission:PLI scheme incentives for domestic chip fabrication are creating first-mover advantage for test platform vendors establishing local calibration and service infrastructure.
- Co-Packaged Optics Thermal Validation:Emerging protocols for photonic-electronic integration require new metrology approaches combining electrical and optical hot spot detection.
- Edge AI Deployment:Automotive and industrial edge accelerators are opening mid-market demand for portable thermal mapping systems with reduced footprint and simplified operator interfaces.
Industry Challenges
- Multiphysics Simulation Talent Gap:The intersection of thermal, electrical, and mechanical modeling requires specialized expertise scarce in both vendor engineering teams and customer metrology departments.
- Legacy System Integration Friction:New high-resolution platforms must interface with existing semiconductor test cell architectures, complicating data pipeline standardization and slowing deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market |
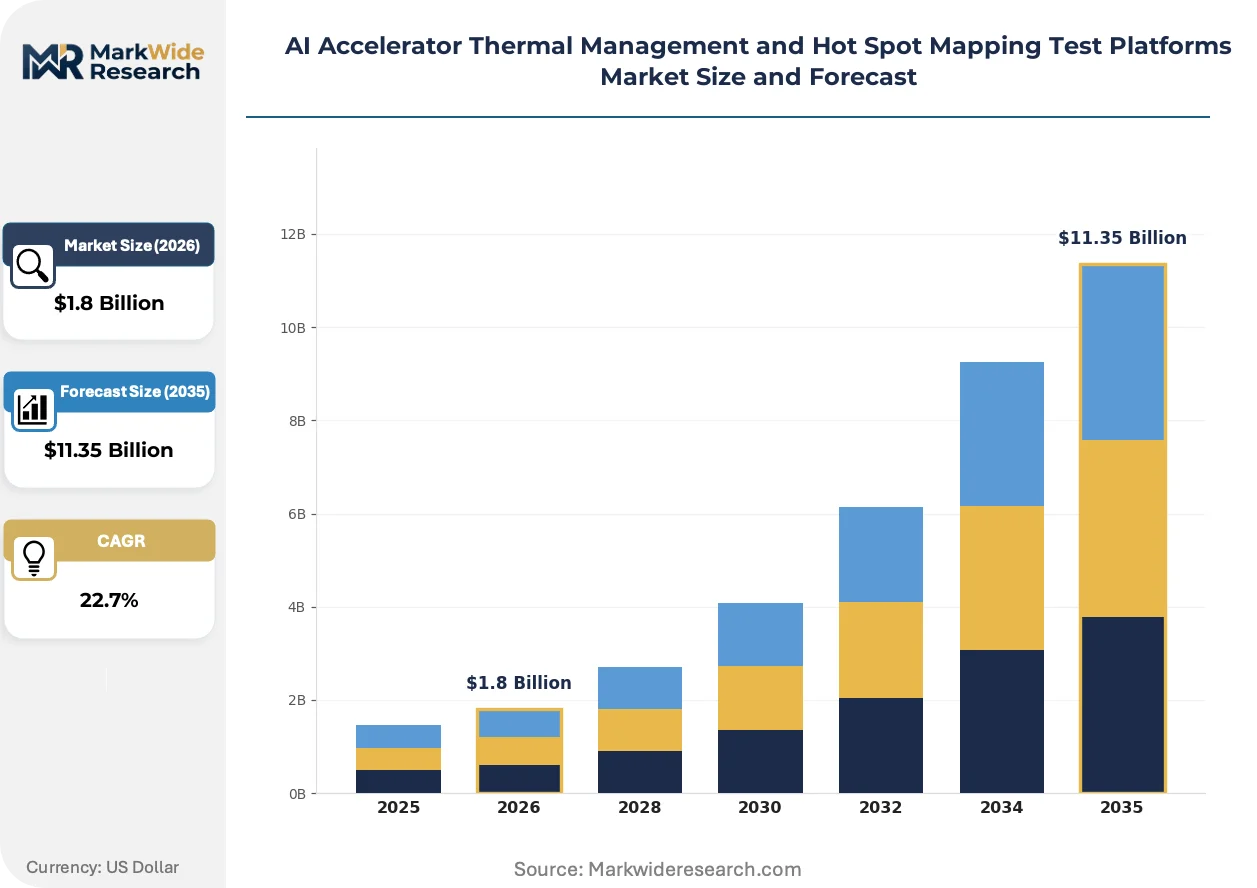
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Infrared Cameras, Thermal Probes, Heat Flux Sensors, Data Acquisition Units Technology: Thermocouples, Thermal Imaging, Fiber Optic Sensors, Microelectromechanical Systems, Acoustic Thermography Application: Chip-Level Analysis, Board-Level Testing, System Integration Validation, Failure Analysis, Quality Assurance End User: Semiconductor Foundries, Electronic Test Labs, Research Institutes, Data Center Operators, System Integrators |
| Companies Covered | inTEST Thermal Solutions, ESPEC, Weiss Technik, Cincinnati Sub-Zero, Thermotron, Watlow, Chroma ATE, Teradyne, Advantest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market Trends and Innovations
Thermal metrology is converging with real-time analytics and predictive modeling, compressing the feedback loop between measurement and design iteration while embedding intelligence directly into test instrumentation.
Fiber optic temperature sensors are displacing thermocouples in electromagnetic-sensitive environments. Automotive radar and 5G baseband chip developers are adopting these probes at accelerating rates. The technology is miniaturizing to sub-millimeter form factors, enabling dense array deployments inside sealed package cavities previously inaccessible to conventional instrumentation.
REACH chemical safety protocols are tightening disclosure requirements for thermal interface materials used in European test labs. Suppliers must now document full substance composition down to 0.1% concentration thresholds. Environmental simulation chamber vendors serving the EU market are reformulating greases and gap pads to maintain compliance without degrading thermal conductivity specifications.
Foundry customers are consolidating vendor relationships around integrated platform providers capable of spanning wafer-level to system-level thermal validation. Discrete point-solution suppliers face margin compression as procurement teams prioritize single-source accountability and unified software environments. Taiwan-based packaging houses are most aggressive in this consolidation, driven by compressed product development schedules for AI accelerators.
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market Segmentation
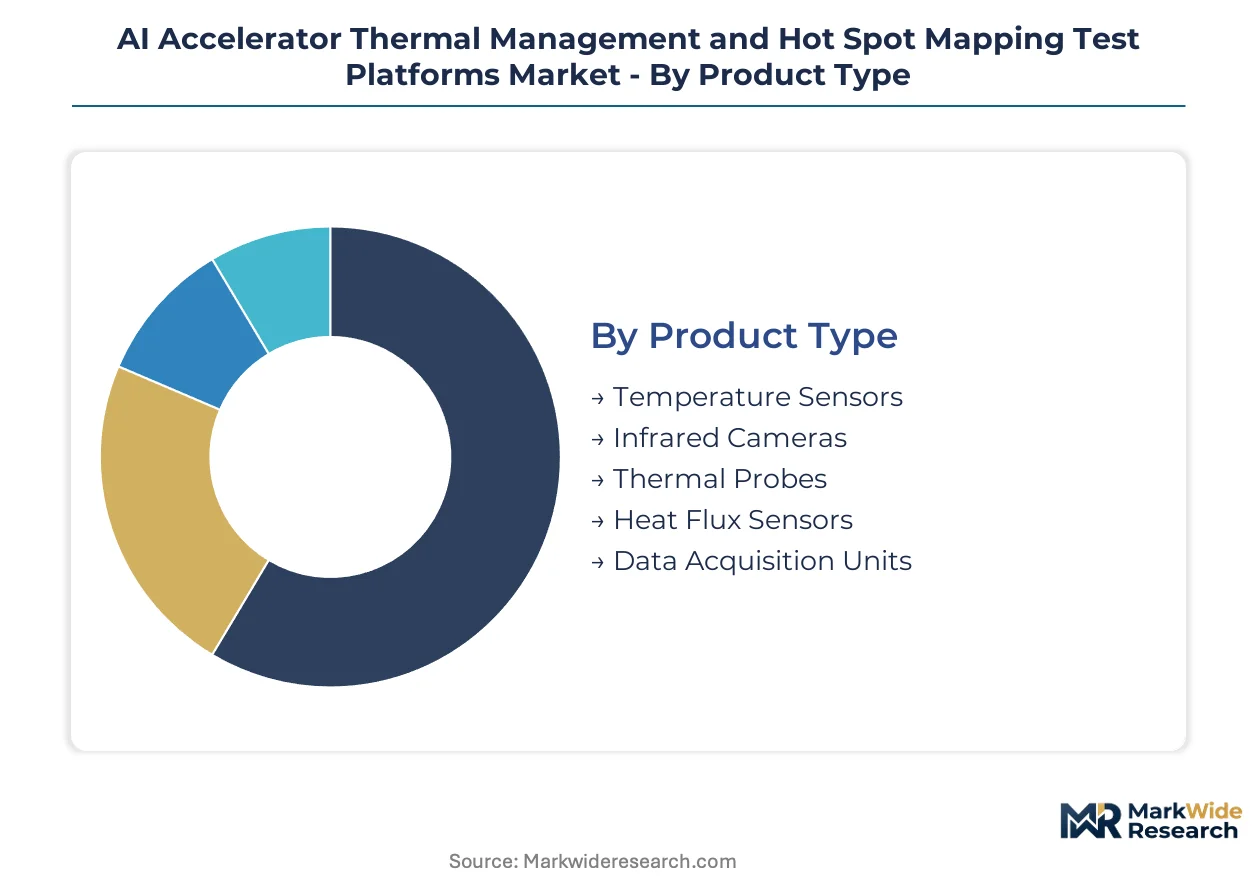
Thermal test platform procurement splits sharply between precision chip-level instrumentation and higher-volume board-level systems, with substitution pressure from emerging fiber optic and MEMS technologies reshaping vendor positioning across each tier.
Product Type:
Infrared cameras face mounting substitution pressure from solid-state alternatives as detector material costs fluctuate and packaging miniaturization demands denser form factors.
- Infrared Cameras:These systems deploy indium antimonide and mercury cadmium telluride focal plane arrays to resolve sub-10-micrometer hot spots in 3D chiplet configurations. TSMC's advanced packaging facilities in Taiwan anchor procurement volume for wafer-level thermal mapping during AI accelerator qualification cycles.
- Data Acquisition Units:Software-defined analytics layers transform raw thermal data into predictive models, embedding recurring service revenue through proprietary algorithm licensing. Cloud service providers expanding AI training clusters drive demand for these units to integrate with existing semiconductor test cell architectures.
- Temperature Sensors:Thermocouple and resistance-based probes serve baseline thermal monitoring in legacy test environments.
- Thermal Probes:Contact-based instruments target failure analysis workflows requiring absolute temperature accuracy.
- Heat Flux Sensors:These quantify thermal transfer rates at material interfaces for thermal interface material validation.
Infrared cameras retain volume leadership; data acquisition units hold the steepest expansion curve.
Technology:
Cost tier stratification separates mature thermocouple deployments from premium fiber optic and MEMS alternatives penetrating electromagnetic-sensitive test environments.
- Fiber Optic Sensors:Gallium arsenide and silicon-based Fabry-Perot interferometers deliver EMI immunity for automotive radar and 5G baseband chip validation. Miniaturization to sub-millimeter form factors enables dense array deployment inside sealed package cavities previously inaccessible to electrical probes.
- Thermal Imaging:Infrared focal plane array technology dominates chip-level analysis through non-contact temperature mapping with spatial resolution approaching 5 micrometers. Semiconductor foundries in Taiwan and South Korea concentrate procurement for advanced node characterization.
- Thermocouples:Type K and T junctions persist in cost-sensitive board-level testing applications.
- Microelectromechanical Systems:MEMS thermal sensors integrate with CMOS fabrication for wafer-scale deployment.
- Acoustic Thermography:Ultrasonic thermal wave detection targets subsurface defect identification in stacked die architectures.
Thermal imaging commands the premium tier; fiber optic sensors are climbing the fastest as EMI immunity requirements harden.
Application:
Customer type concentration drives divergence between foundry-driven chip-level precision requirements and system integrator demand for rapid board-level throughput.
- Chip-Level Analysis:Sub-micron resolution thermal mapping enables hot spot localization in multi-die AI accelerators before packaging completion. TSMC's 3nm and 2nm production ramps in Taiwan force compressed validation timelines from months to weeks.
- System Integration Validation:Full thermal characterization of co-packaged optics and 3D chiplet assemblies requires combined electrical-optical metrology approaches. Data center operators expanding AI infrastructure drive procurement for qualification of high-density accelerator deployments.
- Board-Level Testing:Thermal cycling and steady-state analysis target printed circuit assembly reliability.
- Failure Analysis:Root-cause thermal diagnostics support yield improvement and return material authorization investigations.
- Quality Assurance:Production-line thermal screening ensures outgoing conformance to specification.
Chip-level analysis dominates revenue concentration; system integration validation is gaining share fastest as co-packaged optics protocols mature.
End User:
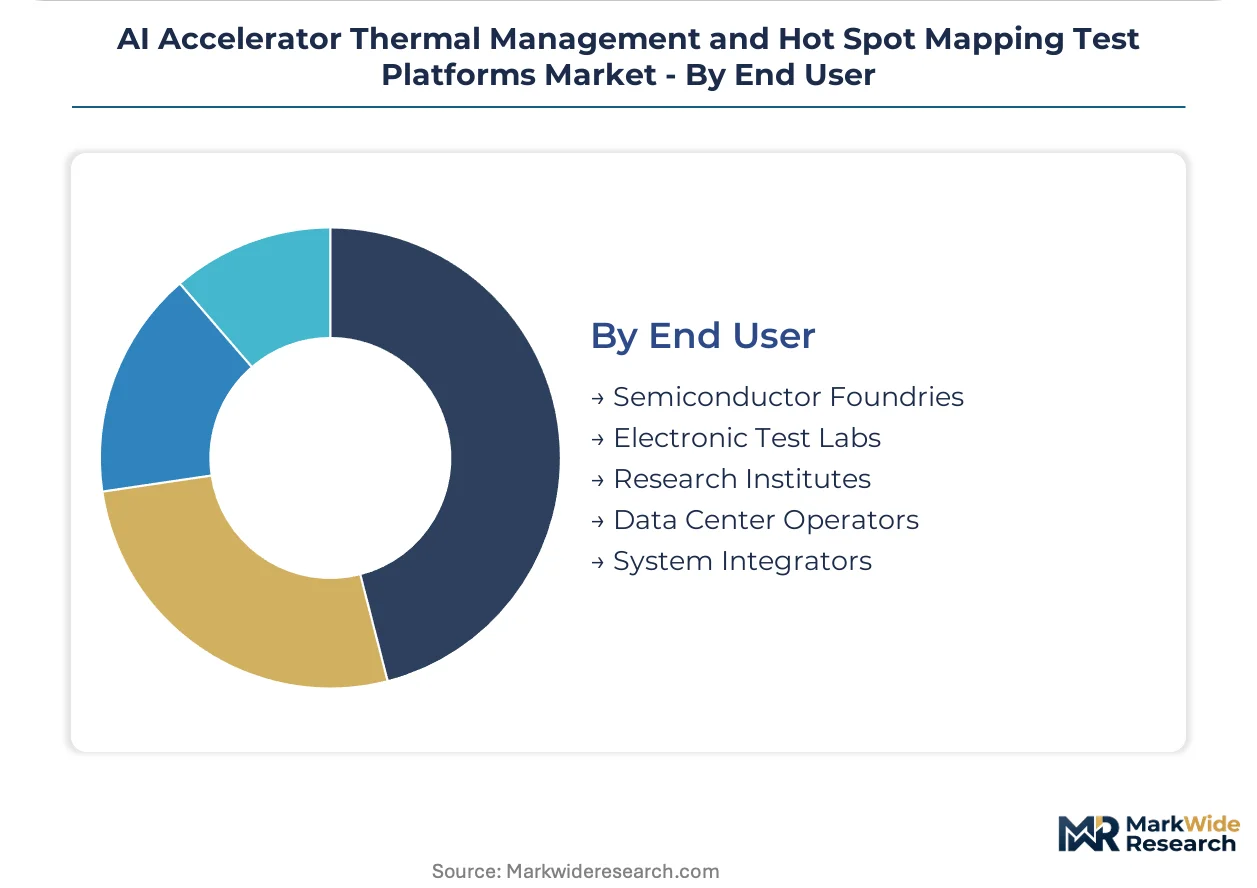
Geographic supply concentration in East Asian foundry clusters concentrates procurement authority for the most advanced thermal characterization platforms.
- Semiconductor Foundries:TSMC, Samsung, and Intel's packaging divisions require sub-10-micrometer resolution for 3D chiplet and co-packaged optics thermal validation. Taiwan's national standards body enforces calibration protocols that shape platform specification for cross-border deployment.
- Electronic Test Labs:Third-party qualification facilities serve fabless AI accelerator designers with ISO 17025 thermal characterization services. REACH chemical safety protocols under ECHA jurisdiction force material disclosure reformulation for thermal interface materials used in European labs.
- Research Institutes:Academic and government laboratories advance thermal metrology for beyond-CMOS architectures.
- Data Center Operators:Hyperscale cloud providers validate thermal design power specifications for deployed AI training infrastructure.
- System Integrators:Server and networking equipment manufacturers conduct incoming inspection and outgoing qualification thermal testing.
Semiconductor foundries retain volume leadership; electronic test labs hold the steepest expansion curve as fabless AI chip design proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance for precision thermal test instrumentation tilts heavily toward East Asian manufacturing clusters, with Taiwan and South Korea running sustained equipment surpluses while the United States and Germany absorb inbound shipments for advanced packaging R&D.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors drive procurement of high-resolution thermal mapping systems for AI accelerator qualification. The FCC and EPA jointly enforce energy efficiency standards and electromagnetic emissions limits that shape platform specifications. Austin and Phoenix semiconductor packaging facilities import precision motion stages from Japanese suppliers to support advanced node thermal validation.
Taiwan
TSMC's 3nm and 2nm production ramps in Hsinchu Science Park generate concentrated demand for sub-10-micrometer resolution hot spot detection systems. The national standards body enforces calibration protocols that effectively set de facto specifications for cross-border platform deployment. Tainan and Taichung packaging houses are consolidating vendor relationships around integrated platform providers capable of spanning wafer-level to system-level thermal validation.
Germany
Automotive radar and 5G baseband chip developers in Munich and Stuttgart adopt fiber optic temperature sensors for electromagnetic-sensitive validation environments. ECHA's REACH chemical safety protocols force thermal interface material reformulation for test lab compliance. Dresden's semiconductor cluster imports infrared camera modules despite indium antimonide supply constraints from Chinese export controls.
South Korea
Samsung's advanced packaging divisions in Pyeongtaek and Yongin require thermal test platforms resolving hot spots in multi-die AI accelerator configurations. The MFDS and national metrology institute coordinate calibration standards that diverge from Taiwan's regime, forcing redundant certification investments. Seongnam test labs serve fabless AI chip designers with ISO 17025 thermal characterization services.
Japan
Precision motion stages and nanopositioning hardware suppliers in Tokyo and Osaka create single-source vulnerability for global test platform assembly. METI's industrial technology policies support domestic detector material production to offset Chinese supply constraints. Yokohama environmental simulation chamber vendors reformulate thermal interface materials to maintain REACH compliance without degrading conductivity specifications.
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market Competitive Landscape
Concentration sits with full-suite platform vendors capable of spanning wafer-level to system-level thermal validation, while point-solution specialists face margin compression from procurement consolidation. The vendor base stratifies across three tiers: integrated platform providers anchoring high-margin foundry engagements, environmental simulation chamber specialists serving board-level cycling requirements, and component suppliers captive to precision motion and detector material inputs. Dominant competitive moves include backward integration into temperature forcing systems and strategic partnerships with advanced packaging houses to lock in qualification workflow design.
Within the integrated platform tier, inTEST Thermal Solutions and ESPEC exemplify divergent specialization vectors—one anchoring chip-level precision temperature forcing, the other dominating environmental simulation chambers for board-level thermal cycling. Thermotron occupies a position on the custom system integration validation vector, competing aggressively on delivery speed for specialized rig configurations. These three companies represent the archetypal positioning that procurement teams prioritize when consolidating vendor relationships around single-source accountability.
| Leading Market Players |
|---|
| inTEST Thermal Solutions |
| ESPEC |
| Weiss Technik |
| Cincinnati Sub-Zero |
| Thermotron |
| Watlow |
| Chroma ATE |
| Teradyne |
| Advantest |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between semiconductor foundries and precision motion stage suppliers lock in supply access while providing price visibility across volatile indium antimonide and mercury cadmium telluride markets. These arrangements insulate TSMC and Samsung from spot market swings in detector materials subject to Chinese export controls.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade calibration under Taiwan's national metrology institute protocols, while economy tiers serve board-level thermal cycling without sub-micron resolution. Pricing pressure stems from fiber optic sensor substitution in EMI-sensitive automotive radar validation. Fabless AI chip designers exhibit highest price sensitivity; foundry procurement teams show lowest sensitivity given compressed qualification timelines.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, while Japan and Germany supply precision motion stages and nanopositioning hardware. Infrared camera modules draw from indium antimonide and mercury cadmium telluride sources concentrated under Chinese export licensing. Single-source vulnerability in Japanese nanopositioning components creates supply chain risk. Distribution runs through direct foundry engagement with integrated platform vendors, bypassing distributor markup for high-resolution chip-level systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as co-packaged optics protocols create first-mover advantage for vendors with combined electrical-optical metrology capabilities. Cloud service provider CapEx surges on AI training infrastructure sustain demand visibility.
For Market Incumbents: Secure backward integration into temperature forcing systems to defend margin pools against fiber optic sensor substitution. Lock in multi-year qualification workflow partnerships with TSMC and Samsung packaging divisions before co-packaged optics standards solidify. Prioritize software-defined analytics layer investments that embed recurring service revenue.
For New Entrants and Emerging Players: Post-sales calibration and certification services represent an under-served layer where incumbents rely on third-party labs. Target India's Semiconductor Mission PLI beneficiaries with portable thermal mapping systems for edge AI validation. Lead with simplified operator interfaces and local service infrastructure rather than resolution specifications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among data acquisition unit vendors with proprietary algorithm licensing. Five-to-ten year viability favors integrated platform providers spanning wafer-level to system-level validation. Monitor which regulatory jurisdiction's test compliance regime achieves de facto adoption in co-packaged optics thermal protocols as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Mitigates Chinese export control exposure on indium antimonide and mercury cadmium telluride. |
| Co-Packaged Optics Metrology Partnership | Locks in qualification workflow design before photonic-electronic integration standards finalize. |
| India Local Service Infrastructure | Captures PLI scheme-driven demand from domestic chip fabrication facilities. |
| Software-Defined Analytics Licensing | Transforms hardware sales into recurring revenue through predictive thermal model subscriptions. |
| REACH-Compliant Material Reformulation | Maintains European test lab access as ECHA tightens thermal interface material disclosure thresholds. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of semiconductor foundry procurement disclosures, EPA and FCC regulatory filings, and trade data on precision motion stage imports. Interviews with thermal test platform engineering directors, foundry metrology managers, and environmental simulation chamber procurement leads informed demand segmentation. Secondary validation drew from SEC filings of hyperscaler cloud providers, EU AI Act implementation guidance, and Taiwan national standards body calibration protocols. Bottom-up equipment unit estimates triangulate against top-down CapEx allocation analysis.
Segmentation dimensions modeled include product type, technology category, application tier, and end-user archetype across the projection horizon. CAGRs derive from equipment procurement cycle analysis and foundry capacity expansion schedules. Industry-specific inputs incorporate TSMC and Samsung advanced packaging node ramps, cloud service provider training cluster deployments, and automotive radar chip validation volume.
Underlying assumptions cover sustained hyperscaler AI infrastructure investment, stable Chinese export control enforcement on detector materials, and gradual co-packaged optics protocol maturation, with deviation risk concentrated in regulatory calibration standard fragmentation and substitute sensor technology cost curves. Recalibration cycles align with material shifts in foundry node transitions and export control policy adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiation Tester Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Metal Testing Equipment Market
Test and Measurement
Pump Testers Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Fogging Tester Market