

Power Semiconductor Wafer-Level Reliability Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Power Semiconductor Wafer-Level Reliability Test Equipment Market Insights
The EU Green Deal is rebalancing procurement priorities across European foundries and OSAT providers toward test equipment that minimizes wafer scrap and energy-intensive rework cycles. Teradyne leverages its installed base in burn-in and thermal cycling systems to sustain service revenue streams across mature 200mm and expanding 300mm lines. Advantest anchors its position through R&D intensity in acoustic microscopy and electrical parametric test cells for wide-bandgap materials. Chroma ATE competes aggressively on cost-adjusted throughput for power module qualification in Greater China and Southeast Asia.
Power semiconductor wafer-level reliability test equipment comprises systems that subject unpackaged dice to accelerated thermal, electrical, mechanical, and optical stress protocols before singulation, typically operating across temperature ranges from -65°C to +175°C with millisecond-level thermal transient capture to predict field failure modes. Thermal cycling testers dominate capital allocation for silicon carbide qualification due to coefficient-of-thermal-expansion mismatch risks between substrate and epitaxial layers. Burn-in testers represent the fastest-growing technology segment as automotive OEMs impose zero-defect reliability mandates for 800V architectures. Electrical testers concentrate margin pools in high-voltage device applications where parametric drift at extreme temperatures determines end-customer acceptance.
The U.S. EPA energy efficiency standards and OSHA workplace safety frameworks shape equipment design for thermal management and chamber exhaust systems in domestic fabrication facilities. Japan's METI semiconductor revitalization policy and JIS standards for reliability test protocols create preferential market access for Tokyo Seimitsu and other domestic vendors serving national champions. Stakeholders must monitor how REACH substance restrictions and evolving EU AI Act documentation requirements for automated inline inspection reshape equipment qualification cycles and aftermarket service obligations.
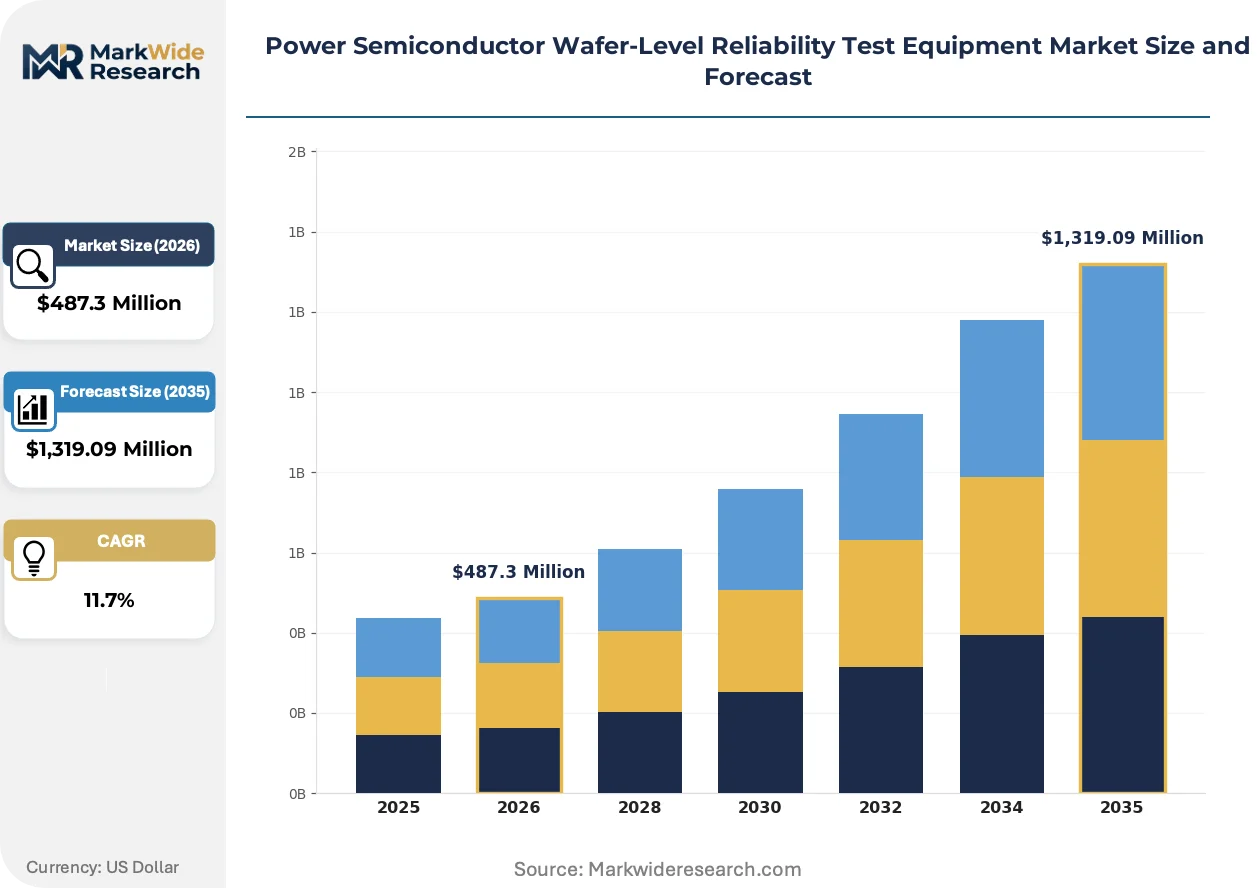
Market Dynamics
Automotive Tier-1 Suppliers are mandating wafer-level reliability screening for silicon carbide power devices destined for 800V traction inverters, compressing qualification timelines and forcing foundries to prioritize inline test platforms over offline batch systems.
Growth Catalysts
- EU Green Deal embedded carbon tracking:Foundries across Germany, France, and the Netherlands are procuring test equipment that reduces wafer scrap and energy-intensive rework cycles to meet Scope 3 reporting obligations.
- Silicon carbide epitaxy expansion:Coefficient-of-thermal-expansion mismatch risks between substrate and epitaxial layers are driving capital allocation toward thermal cycling testers with millisecond-level transient capture.
- Automotive zero-defect mandates:800V architecture qualification requirements from German and Japanese OEMs are accelerating burn-in tester deployment for power module screening.
Market Restraints
- High-voltage chamber material costs:Specialized ceramics and thermal management alloys for extreme temperature cycling create input cost volatility for equipment manufacturers.
- Core component supply concentration:Precision motion stages and high-speed data acquisition modules concentrate among Japanese and German component suppliers, creating single-source vulnerability.
- REACH substance restrictions:ECHA limitations on certain thermal interface materials and chamber coatings are extending equipment redesign cycles and qualification timelines.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic fab construction under the country's production-linked incentive program creates first-mover advantage for reliability test equipment vendors establishing local service infrastructure.
- Acoustic microscopy-electrical parametric convergence:Integration of non-destructive mechanical stress detection with inline electrical testing is opening premium positioning for wide-bandgap material qualification.
- Aftermarket service unbundling:Foundries are separating equipment purchase from predictive maintenance contracts, creating recurring revenue streams for thermal calibration and chamber refurbishment specialists.
Industry Challenges
- Wide-bandgap device physics expertise gap:The shortage of engineers trained in silicon carbide and gallium nitride failure mechanism modeling is slowing test protocol development and customer qualification support.
- Legacy 200mm-300mm integration friction:Mixed-format fabs are struggling to harmonize reliability data formats and thermal profile libraries across incompatible equipment generations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Semiconductor Wafer-Level Reliability Test Equipment Market Trends and Innovations
Test equipment architecture is converging around platforms that compress multiple stress protocols into single inline cells, eliminating wafer handling between thermal, electrical, and mechanical qualification stages.
Multiphysics simulation software is unifying thermal, electrical, and mechanical stress modeling into pre-silicon prediction engines. Bosch and Infineon engineering teams are adopting these platforms to reduce physical test iterations by half. This convergence is compressing equipment procurement cycles as foundries demand test cells validated against simulation benchmarks rather than empirical correlation studies.
Japan's METI semiconductor revitalization policy is channeling national champion procurement toward domestic test equipment vendors. Tokyo Seimitsu and Advantest are securing preferential placement in 300mm expansion projects. European foundries are responding by lobbying Brussels for reciprocity in EU-funded fab equipment tenders.
Automotive OEMs are consolidating supplier qualification around single-source test protocol libraries. Tier-1 power module manufacturers must now demonstrate traceability to OEM-mandated thermal cycling profiles. German and South Korean automotive clusters are most advanced in this standardization push, with Chinese EV manufacturers beginning to mirror the requirement structure.
Power Semiconductor Wafer-Level Reliability Test Equipment Market Segmentation
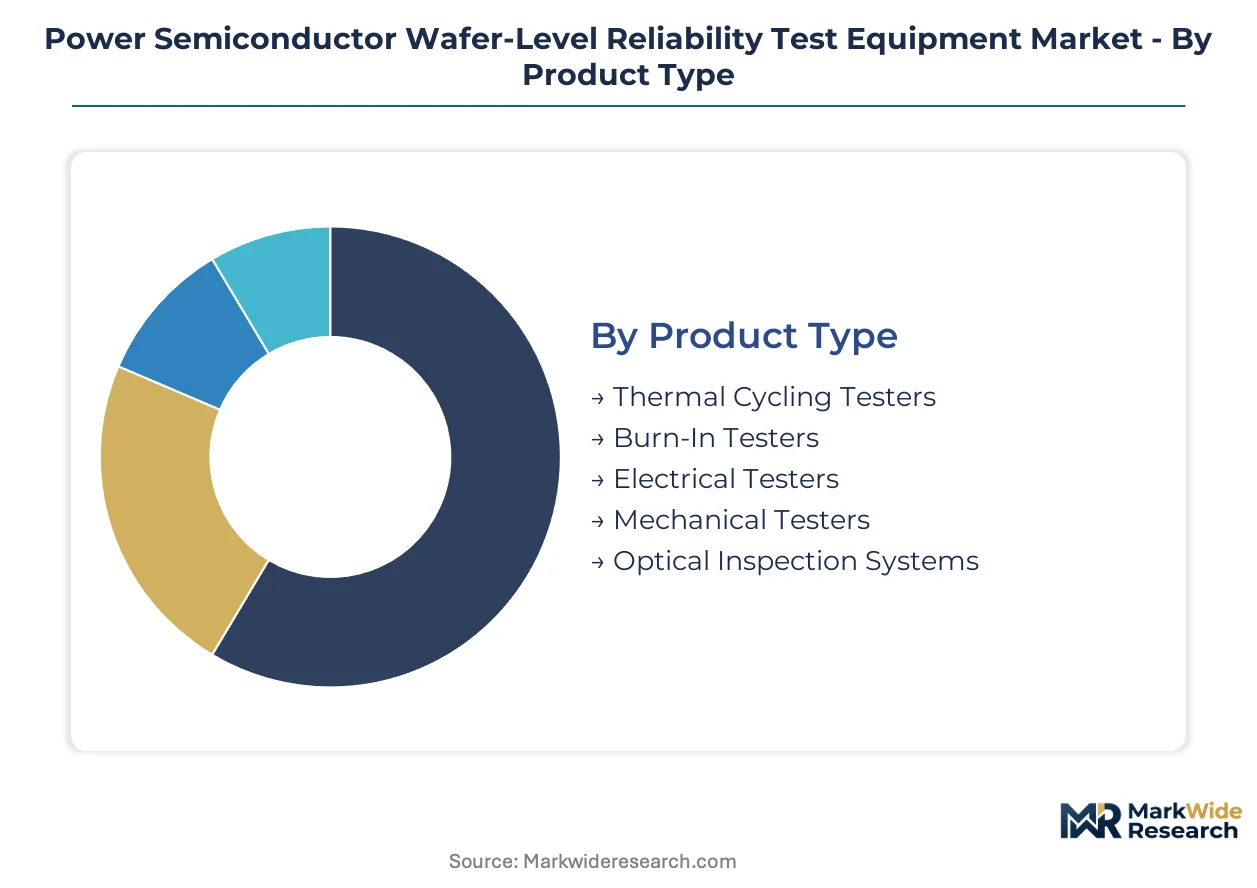
Segmentation in power semiconductor wafer-level reliability test equipment reveals how capital allocation priorities diverge across stress protocol types, automation levels, and customer sophistication tiers. Equipment vendors must calibrate R&D intensity and service infrastructure to the specific thermal, electrical, and mechanical qualification demands of each segment cluster.
Product Type:
Supply concentration for critical thermal management subsystems varies sharply across tester categories, with ceramic chamber manufacturers and precision motion stage vendors exerting pricing leverage on specific product lines.
- Thermal Cycling Testers:These systems subject wafers to rapid temperature transitions between -65°C and +175°C to accelerate failure mechanisms from coefficient-of-thermal-expansion mismatches in silicon carbide epitaxial stacks. German automotive OEM clusters in Stuttgart and Munich are driving qualification volume for 800V traction inverter applications, compressing procurement timelines for systems with millisecond-level transient capture capability.
- Burn-In Testers:Extended-duration electrical stress systems operate at elevated temperatures to precipitate early-life failures before singulation. Japanese automotive Tier-1 suppliers under METI zero-defect mandates are expanding deployment for power module screening, with foundries in Aichi and Hiroshima prefectures prioritizing inline integration over batch processing.
- Electrical Testers:Parametric measurement systems for high-voltage drift characterization at temperature extremes.
- Mechanical Testers:Shear, pull, and vibration stress systems for interconnect reliability validation.
- Optical Inspection Systems:Automated defect detection for surface anomalies and dimensional verification.
Today's leader: Thermal Cycling Testers. Tomorrow's challenger: Burn-In Testers.
Technology:
Automation intensity determines margin structure, with fully automated platforms commanding premium positioning against manual and hybrid alternatives in high-volume manufacturing environments.
- Automated Test Equipment:Fully integrated systems with robotic wafer handling and software-defined test sequencing for 300mm production lines. European foundries in Dresden and Leuven are standardizing on these platforms to meet EU Green Deal carbon tracking requirements by eliminating rework waste from handling damage.
- Inline Test Technology:Continuous-flow systems integrated directly into fabrication process sequences. OSAT providers in Penang and Singapore are adopting this architecture to compress cycle times for automotive qualification programs, though upfront capital requirements limit penetration beyond Tier-1 contract manufacturers.
- Manual Test Systems:Operator-dependent platforms for low-volume R&D and failure analysis applications.
- Hybrid Test Platforms:Semi-automated configurations balancing throughput flexibility with capital efficiency.
- Acoustic Microscopy:Non-destructive mechanical stress detection for void and delamination identification in wide-bandgap materials.
Automated Test Equipment holds installed base dominance. Inline Test Technology is gaining share fastest in automotive-qualified capacity expansions.
Application:
Voltage class and packaging complexity create divergent equipment specifications, with high-voltage applications demanding specialized chamber materials and safety interlocks that extend design cycles.
- High-Voltage Devices:Test cells engineered for 800V+ operation with reinforced isolation and arc containment. Bosch and Infineon engineering teams in Germany are validating these systems against multiphysics simulation benchmarks rather than empirical correlation studies, compressing equipment procurement cycles.
- Power Modules:Integrated qualification platforms for packaged die assemblies. South Korean automotive clusters around Seoul are advancing standardization of thermal cycling profile libraries, forcing Tier-1 suppliers to demonstrate traceability to OEM-mandated protocols.
- Wafer-Level Packaging:Thin-wafer handling and through-silicon via reliability screening.
- Flip Chip Packaging:Underfill and bump interconnect stress validation.
- Chip Scale Packaging:Miniaturized form factor qualification for mobile and IoT power management.
High-Voltage Devices command premium positioning. Power Modules show steepest expansion trajectory from EV platform ramp schedules.
End User:
Customer type dictates service model economics, with foundries and OSAT providers prioritizing throughput metrics while IDMs emphasize protocol flexibility and data traceability.
- Automotive Tier-1 Suppliers:Power module manufacturers with zero-defect reliability mandates and consolidated supplier qualification requirements. These customers are separating equipment purchase from predictive maintenance contracts, creating recurring revenue opportunities for thermal calibration specialists serving facilities in Bavaria and Baden-Württemberg.
- Foundries:Merchant wafer processing facilities with mixed-format 200mm and 300mm lines. Foundries in Taiwan and Japan are struggling to harmonize reliability data formats across incompatible equipment generations, creating aftermarket integration service demand.
- Semiconductor Manufacturers:Integrated device manufacturers with captive qualification capacity.
- OSAT Providers:Outsourced assembly and test specialists competing on cost-adjusted throughput.
- Electronics OEMs:System-level manufacturers with limited in-house wafer-level test capability.
Automotive Tier-1 Suppliers anchor current procurement volume. Foundries represent the most contested expansion segment as merchant silicon carbide capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The power semiconductor wafer-level reliability test equipment industry traces its commercial origins to Japanese precision instrumentation manufacturers in the 1980s, with subsequent scaling through German automotive electronics clusters and American semiconductor test automation vendors during the 1990s and 2000s.
Germany
Bosch and Infineon engineering teams in Stuttgart and Munich are compressing procurement timelines for thermal cycling systems with millisecond-level transient capture capability. The EU Green Deal's embedded carbon tracking requirements are pushing foundries toward inline test platforms that reduce rework waste. Bavarian automotive OEM clusters drive qualification volume for 800V traction inverters, with Baden-Württemberg facilities separating equipment purchase from predictive maintenance contracts.
Japan
METI's semiconductor revitalization policy channels national champion procurement toward domestic test equipment vendors serving captive qualification capacity in Aichi and Hiroshima prefectures. JIS standards for reliability test protocols create preferential market access for precision instrumentation specialists. Foundries under zero-defect mandates are expanding burn-in tester deployment for power module screening, prioritizing inline integration over batch processing.
United States
EPA energy efficiency standards and OSHA workplace safety frameworks shape equipment design for thermal management and chamber exhaust systems in domestic fabrication facilities. Teradyne leverages its installed base across mature 200mm and expanding 300mm lines to sustain service revenue streams. The country's national semiconductor test automation vendors concentrate R&D in acoustic microscopy and electrical parametric test cells for wide-bandgap materials.
China
MIIT dual carbon goals and GB standards for industrial energy efficiency are accelerating domestic fab construction, creating demand for reliability test equipment with reduced wafer scrap profiles. Chroma ATE competes aggressively on cost-adjusted throughput for power module qualification in Greater China and Southeast Asia. Yangtze River Delta foundries are standardizing on automated test equipment to meet carbon reporting obligations.
South Korea
Automotive clusters around Seoul are advancing standardization of thermal cycling profile libraries, forcing Tier-1 suppliers to demonstrate traceability to OEM-mandated protocols. The country's national industrial policy supports 300mm expansion projects with preferential placement for test equipment vendors. Busan-Ulsan OSAT providers are adopting inline test technology to compress cycle times for automotive qualification programs.
Power Semiconductor Wafer-Level Reliability Test Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates around precision instrumentation specialists with captive thermal management subsystem capabilities. The vendor base organizes into three tiers: multinational test automation platforms with full-stack integration, regional specialists competing on cost-adjusted throughput, and precision component suppliers capturing margin pools in motion stages and data acquisition modules. Dominant competitive moves include strategic partnerships between equipment vendors and foundry operators for co-developed qualification protocols, plus geographic expansion through local service infrastructure establishment.
Within the multinational platform tier, Teradyne and Advantest occupy positions anchored by installed base scale and R&D intensity respectively. Chroma ATE exemplifies the regional specialist archetype competing on throughput economics. Tokyo Seimitsu represents the precision component-to-systems integrator model favored under Japan's METI procurement preferences.
| Leading Market Players |
|---|
| Teradyne |
| Advantest |
| SPEA |
| Cohu |
| Chroma ATE |
| Keysight Technologies |
| National Instruments |
| Tokyo Seimitsu |
| Astronics |
| Others |
Pricing and Supply Chain Analysis
Captive integration of precision motion stage production anchors both supply security and pricing leverage for leading thermal cycling tester manufacturers serving German automotive clusters. Equipment vendors with in-house ceramic chamber fabrication command premium positioning against competitors sourcing from Japanese specialists, while foundries under EU Green Deal carbon mandates prioritize suppliers with vertically integrated thermal management subsystem capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies equipment procurement based on automation intensity and protocol certification grade. Premium automated test equipment with millisecond-level transient capture commands substantial markups over manual systems, while volume scale discounts concentrate among Taiwanese foundries expanding 300mm silicon carbide capacity. Pricing pressure stems from REACH substance restrictions extending equipment redesign cycles, with OSAT providers in Southeast Asia exhibiting highest price sensitivity due to compressed automotive qualification margins.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Tokyo, and Penang anchor hub-and-spoke fulfillment patterns for precision instrumentation components. Critical thermal management alloys and high-speed data acquisition modules draw from concentrated Japanese and German component suppliers, creating single-source vulnerability for ceramic chamber manufacturers. Tariff exposure on specialized motion stages imported into European assembly facilities feeds downstream cost volatility, while distribution runs through authorized service partners with thermal calibration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power semiconductor wafer-level reliability test equipment functions as a stable compounder anchored by irreversible automotive electrification mandates. Zero-defect reliability requirements for 800V architectures generate recurring equipment refresh cycles regardless of macroeconomic conditions.
For Market Incumbents: Hedge thermal cycling tester margin erosion by securing captive supply agreements for precision motion stages from Aichi prefecture specialists. Accelerate R&D intensity in acoustic microscopy-electrical parametric convergence to defend against emerging Chinese competitors on cost-adjusted throughput metrics. For New Entrants and Emerging Players: Begin with aftermarket service unbundling for foundries in India PLI scheme construction zones, where local thermal calibration infrastructure remains underdeveloped. Target predictive maintenance contract opportunities separated from equipment purchase in Baden-Württemberg automotive clusters, leveraging OEM-mandated traceability requirements as entry credential. For Investors and Strategic Acquirers: Roll-up economics work for precision component specialists because equipment vendors increasingly outsource ceramic chamber and motion stage production to focus on software-defined test sequencing. Monitor wide-bandgap device physics expertise gaps as inflection indicator—engineering talent scarcity in silicon carbide failure mechanism modeling will drive acquisition premiums for qualified technical teams.| Strategic Initiative | Industry Significance |
|---|---|
| Inline Test Platform Integration | Eliminates wafer handling damage for EU Green Deal carbon compliance in Dresden foundries. |
| Acoustic Microscopy R&D Partnership | Accelerates non-destructive void detection protocols for Bosch Infineon qualification programs. |
| India Local Service Infrastructure | Captures first-mover advantage under PLI scheme domestic fab construction timelines. |
| Predictive Maintenance Contract Unbundling | Creates recurring revenue streams from Bavarian automotive Tier-1 supplier procurement shifts. |
| Wide-Bandgap Simulation Benchmark Validation | Compresses equipment procurement cycles through multiphysics platform correlation. |
Research Methodology
Direct dialogue with equipment engineering directors, foundry procurement leads, automotive Tier-1 supplier quality managers, and thermal calibration service technicians grounded qualitative findings. Secondary validation drew from SEMI equipment market data, EPA energy efficiency filings, METI semiconductor policy documents, and EU ECHA REACH restriction notices. Bottom-up equipment shipment tracking triangulated against top-down foundry capital expenditure disclosures.
Bottom-up modeling segmented across stress protocol type, automation level, voltage class application, and end-user sophistication tier throughout the forecast period. CAGRs derived from equipment replacement cycle analysis and silicon carbide epitaxy capacity expansion pipelines, with cross-reference to automotive OEM 800V platform ramp schedules and EU carbon reporting obligation timelines.
Several conditions sit outside the modeled scope, including potential JIS standard revisions affecting Tokyo Seimitsu market access and unanticipated ECHA substance bans on thermal interface materials. Forecasts reflect documented assumptions around automotive electrification penetration rates and foundry format migration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.