
 RFID Tester Market | 2026-2036
RFID Tester Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Tester Market Analytics
GaN power amplifiers are rebalancing handheld tester economics against legacy silicon LDMOS architectures. Keysight Technologies leverages its microwave instrumentation heritage to dominate high-frequency conformance testing. CISC Semiconductor anchors European RFID protocol development through its Vienna-based certification labs.
An RFID tester is a calibrated measurement instrument that verifies radio frequency identification tag and reader performance against ISO/IEC 18046 and EPCglobal Gen2 protocols, quantifying parameters such as read range sensitivity, backscatter modulation depth, and frequency hopping accuracy. These devices ensure electromagnetic compliance and interoperability across supply chain infrastructure. Handheld units lead field-deployment volumes due to warehouse aisle mobility requirements, while desktop configurations capture margin pools in R&D laboratory settings. Passive technology testing generates the highest unit demand, though NFC segments are accelerating with payment terminal certification mandates.
The European Telecommunications Standards Institute sets UHF air-interface benchmarks that shape product development cycles for equipment sold across EU member states. The FCC's Part 15 rules govern unintentional radiators in the United States, directly constraining transmitter power thresholds that testers must validate. China's MIIT issues radio type-approval certificates that condition market access for imported verification equipment. Stakeholders must monitor evolving frequency allocations in the 860-960 MHz band across multiple jurisdictions to anticipate conformance workload shifts.
Market Dynamics
GaN power amplifiers are compressing handheld tester costs while tightening electromagnetic compatibility thresholds across EU member states force protocol recertification cycles.
Growth Catalysts
- EU Radio Equipment Directive:Tighter electromagnetic compatibility thresholds for UHF readers in member states mandate expanded conformance testing protocols across logistics infrastructure.
- Semiconductor packaging corridors:South Korea's concentration of advanced packaging facilities near Seoul generates concentrated demand for precision tag validation equipment.
- NFC payment terminal mandates:Payment network certification requirements for contactless terminals accelerate tester procurement across financial hardware supply chains.
Market Restraints
- Silicon LDMOS input cost volatility:Legacy amplifier architectures face pricing pressure from gallium nitride substitution, stranding existing tester manufacturing investments.
- Supply concentration in Vienna:European protocol certification dependency on CISC Semiconductor's certification labs creates single-point validation bottlenecks.
- Frequency allocation fragmentation:Divergent 860-960 MHz band assignments across jurisdictions multiply conformance workload without proportional revenue expansion.
Strategic Opportunities
- Automated warehouse tracking:German logistics operators are expanding RFID validation protocols, creating sustained equipment refresh demand.
- ISO/IEC 18046-3 convergence:Harmonization of tag performance test methods across global standards bodies reduces regional customization costs.
- Research laboratory R&D:Desktop configurations capture margin pools in protocol development settings where precision instrumentation commands premium positioning.
Industry Challenges
- Microwave instrumentation talent scarcity:Specialized RF engineering expertise required for high-frequency conformance testing concentrates in legacy instrumentation hubs.
- EPCglobal Gen2 certification timelines:Multi-phase protocol validation extends product qualification cycles, compressing revenue recognition windows.
- Legacy reader integration complexity:Backward compatibility requirements with installed UHF infrastructure constrain next-generation tester architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Tester Market |
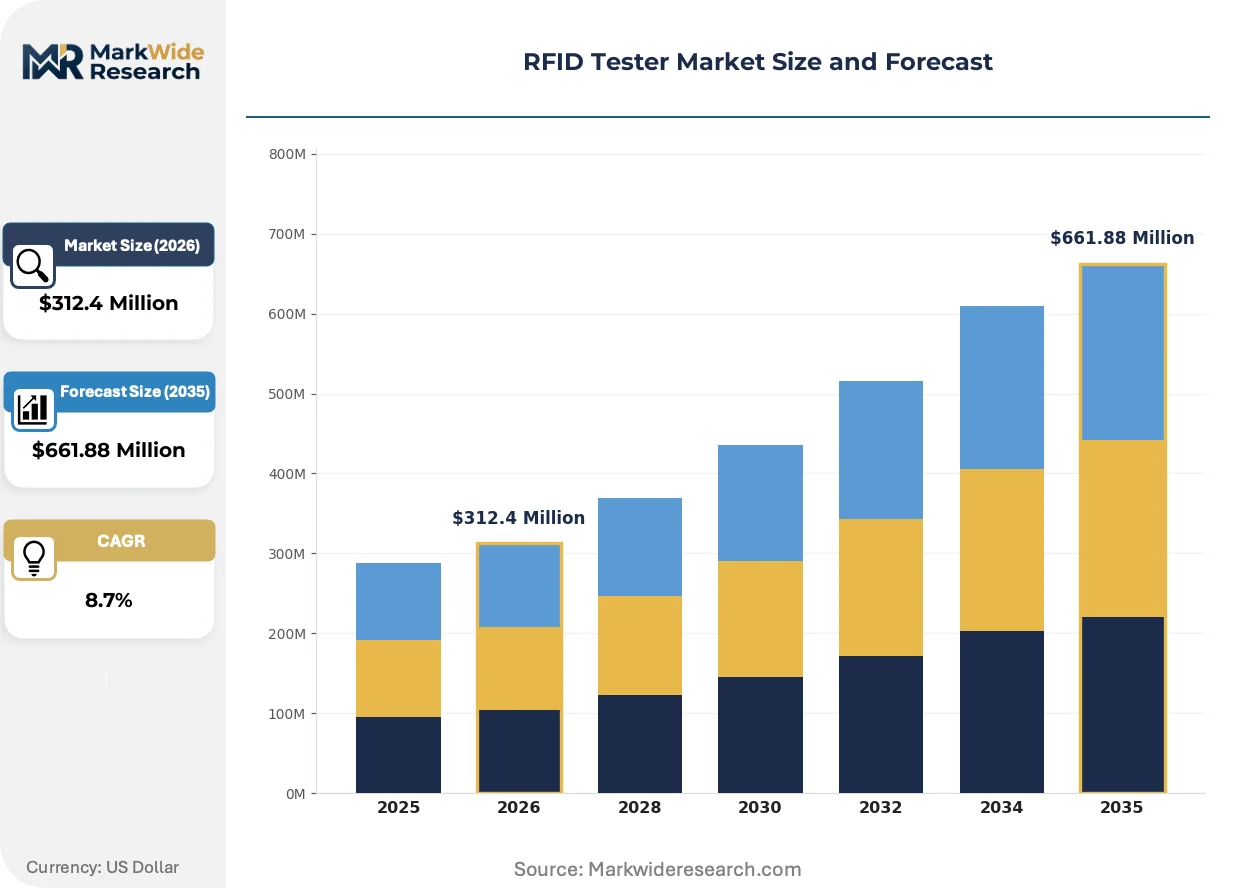
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Mobile, Desktop End User: Logistics, Retail, Manufacturing, Healthcare Technology: Active, Passive, Semi-Passive, NFC Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Keysight Technologies, BGIngénierie, MCS Test Equipment, PERITEC INC., Averna, Concentric Technology Solutions, National Instruments, CISC Semiconductor, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Tester Market Evolving Landscape
Test automation architectures are displacing manual calibration workflows while regulatory fragmentation across frequency bands forces modular hardware designs.
Machine learning-based anomaly detection is automating passive tag sensitivity characterization across warehouse aisle environments. Third-party logistics operators in Germany are deploying these systems at scale. The technology is automating field technician deployment models by reducing manual intervention requirements during routine compliance audits.
The FCC's Part 15 rules governing unintentional radiators constrain transmitter power thresholds that testers must validate for US market entry. Equipment manufacturers face divergent certification paths when simultaneous EU and US compliance is required. High-frequency conformance testing segments absorb disproportionate compliance engineering resources relative to their volume contribution.
Buyer consolidation among contract electronics manufacturers concentrates tester procurement authority at fewer decision nodes. Direct vendor relationships are replacing distributor-mediated equipment acquisition in high-volume validation operations. South Korean semiconductor packaging facilities exhibit this pattern most acutely, with captive procurement teams negotiating enterprise-scale tester deployments.
RFID Tester Market Segmentation
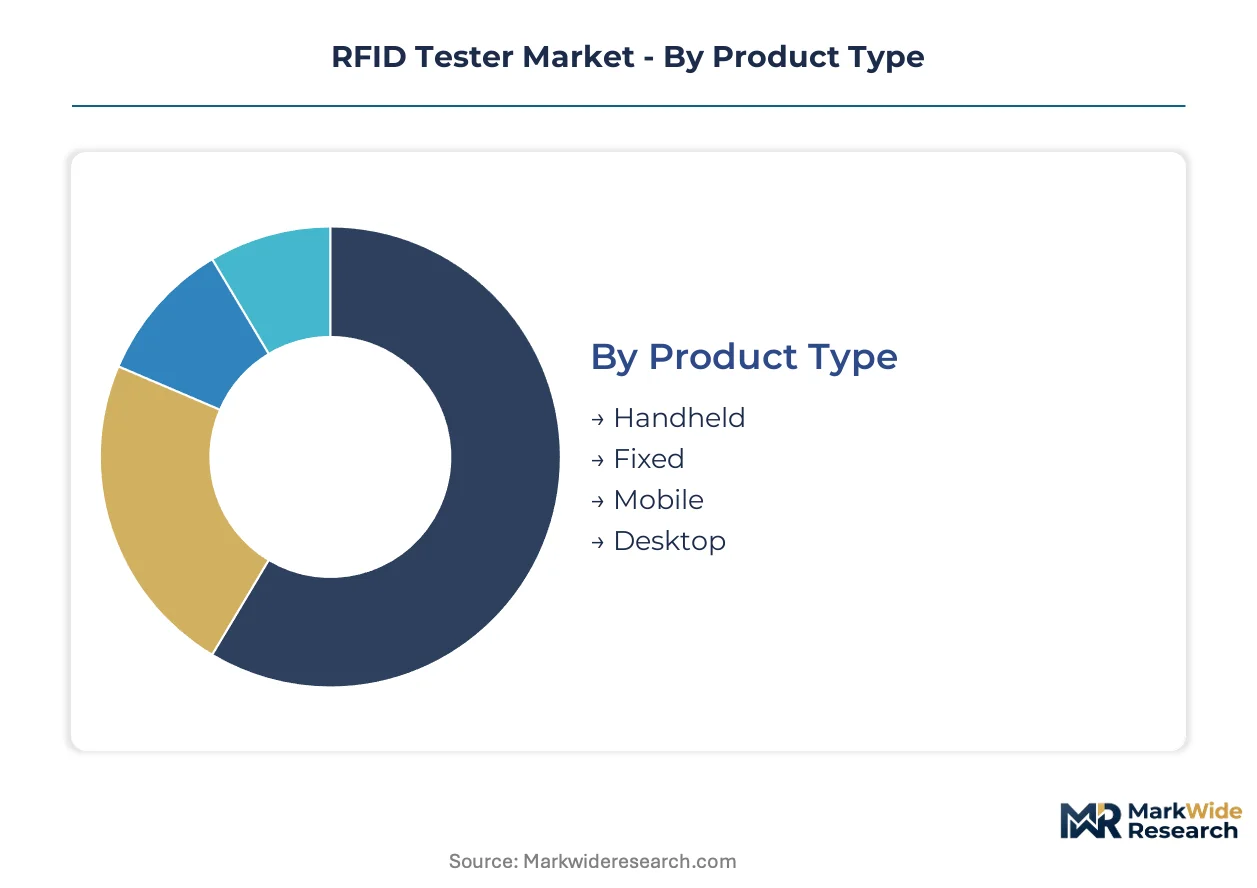
RFID tester procurement patterns diverge sharply across product configurations and end-use environments, with certification requirements varying by deployment scale and frequency band. Equipment specifications must align with ISO/IEC 18046 validation protocols while accommodating jurisdiction-specific electromagnetic compliance thresholds.
Product Type:
Handheld units require FCC Part 15 certification for US logistics deployments, while desktop configurations face ETSI UHF air-interface benchmarks for EU laboratory accreditation. Fixed installations must satisfy both MIIT radio type-approval in China and CE marking for European automated warehouse infrastructure.
- Handheld:Portable battery-powered instruments with integrated antennas enable aisle-by-aisle warehouse validation. German third-party logistics operators deploy these units at scale for routine compliance audits in automated distribution centers. The form factor demands GaN amplifier architectures to balance power efficiency against weight constraints.
- Desktop:Benchtop configurations with precision signal generators and spectrum analyzers support protocol development and R&D certification. South Korean semiconductor packaging facilities near Seoul concentrate procurement of these high-margin units for tag characterization workflows. EPCglobal Gen2 multi-phase validation extends qualification cycles for this segment.
- Fixed:Rack-mounted systems for continuous production-line testing with automated pass-fail reporting.
- Mobile:Vehicle-mounted or cart-based units for large-scale facility surveys and infrastructure commissioning.
Handheld sits at the top of the volume ranking, with Desktop climbing the fastest.
End User:
Cost tier stratification separates enterprise-scale logistics deployments from mid-market retail implementations, with manufacturing and healthcare occupying distinct procurement brackets based on validation throughput requirements.
- Logistics:Automated warehouse operators in Germany drive sustained equipment refresh demand as RFID validation protocols expand across distribution infrastructure. Third-party logistics providers consolidate procurement authority at fewer decision nodes, replacing distributor-mediated acquisition with direct vendor relationships. FCC Part 15 and EU Radio Equipment Directive compliance create dual certification burdens for multinational operators.
- Retail:Payment terminal certification mandates for NFC-enabled point-of-sale hardware accelerate tester procurement across financial hardware supply chains. Contactless transaction volume growth forces recertification cycles for existing infrastructure. Machine learning-based anomaly detection is automating field technician deployment models in this segment.
- Manufacturing:Production-line integration demands real-time tag validation with statistical process control integration.
- Healthcare:Medical device tracking and pharmaceutical supply chain authentication require specialized sterilization-compatible test protocols.
Logistics commands the dominant procurement volume, with Retail expanding most quickly.
Technology:
Application maturity separates established passive UHF testing from emerging NFC certification workloads, with active and semi-passive segments occupying specialized industrial niches.
- Passive:UHF backscatter tag testing generates the highest unit demand across supply chain infrastructure, with ISO/IEC 18046-1 conformance validation required for retail and logistics deployments. The 860-960 MHz frequency band fragmentation across jurisdictions multiplies conformance workload without proportional revenue expansion for equipment vendors. Read range sensitivity and backscatter modulation depth quantification dominate test parameters.
- NFC:Payment network certification requirements for contactless terminals drive accelerating procurement across financial hardware supply chains. EMVCo and payment scheme mandates create standardized test suites distinct from EPCglobal protocols. South Korean packaging corridors exhibit concentrated demand for precision NFC validation equipment.
- Active:Battery-assisted tag testing for real-time location systems in industrial asset tracking.
- Semi-Passive:Sensor-enabled tag validation for cold chain monitoring and environmental condition logging.
Passive technology anchors current volume leadership, with NFC gaining share fastest.
Deployment:
Customer type segmentation distinguishes captive enterprise validation teams from outsourced certification service providers, with hybrid architectures emerging to bridge on-premise control and cloud scalability.
- On-Premise:Localized test execution with data sovereignty requirements satisfies defense and pharmaceutical sector procurement policies. German logistics operators favor this model for automated warehouse tracking infrastructure. Capital expenditure treatment and depreciation schedules align with enterprise asset management frameworks.
- Cloud-Based:Centralized test orchestration with distributed edge execution reduces field technician deployment costs. Contract electronics manufacturers leverage this model to consolidate validation authority across multiple production sites. Machine learning-based anomaly detection integrates natively with cloud analytics pipelines.
- Hybrid:Sensitive test execution remains local while reporting and analytics migrate to cloud infrastructure.
- Others:Managed service and subscription-based equipment access models for variable validation workloads.
On-Premise retains volume dominance, with Cloud-Based showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics corridors anchor regional demand concentration for RFID validation equipment, driven by automated warehouse expansion and electromagnetic compliance tightening across multiple jurisdictions.
United States
FCC Part 15 rules governing unintentional radiators constrain transmitter power thresholds that testers must validate for market entry. Payment terminal certification mandates for NFC-enabled hardware accelerate procurement across financial hardware supply chains. Machine learning-based anomaly detection systems are automating field technician deployment models in automated distribution centers.
Germany
Third-party logistics operators are expanding RFID validation protocols across automated warehouse tracking infrastructure at scale. The EU Radio Equipment Directive tightens electromagnetic compatibility thresholds for UHF readers, mandating expanded conformance testing cycles. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate precision instrumentation procurement for supply chain infrastructure.
South Korea
Advanced semiconductor packaging facilities near Seoul generate concentrated demand for precision tag validation equipment. MFDS radio type-approval certificates condition market access for imported verification equipment. The Seoul Capital Area anchors procurement authority consolidation among captive enterprise validation teams.
China
MIIT issues radio type-approval certificates that condition market access for imported verification equipment. Divergent 860-960 MHz band assignments across jurisdictions multiply conformance workload for equipment vendors. Yangtze River Delta manufacturing corridors exhibit enterprise-scale tester deployment patterns.
Japan
METI standards harmonization efforts shape product development cycles for equipment sold across domestic supply chains. Precision instrumentation demands from automotive and electronics manufacturing drive desktop configuration procurement. Kanto region industrial clusters concentrate R&D laboratory accreditation workflows.
RFID Tester Market Competitive Landscape
Technology licensing dominates the current landscape as specialist firms monetize protocol expertise through certification partnerships. The vendor base organizes around three strategic archetypes: microwave instrumentation heritage players, regional certification specialists, and diversified industrial conglomerates. M&A activity concentrates validation capabilities into fewer decision nodes. Geographic expansion into packaging corridors and logistics hubs represents the second dominant competitive vector.
Within the instrumentation heritage tier, Keysight Technologies and National Instruments occupy positions defined by high-frequency conformance testing capabilities. CISC Semiconductor anchors European protocol development through its Vienna-based certification infrastructure. Honeywell International sits within the diversified industrial conglomerate archetype, leveraging existing supply chain relationships for equipment placement.
| Leading Market Players |
|---|
| Keysight Technologies |
| BGIngénierie |
| MCS Test Equipment |
| PERITEC INC. |
| Averna |
| Concentric Technology Solutions |
| National Instruments |
| CISC Semiconductor |
| Honeywell International |
| Others |
Value Network & Pricing Analysis
EU Radio Equipment Directive electromagnetic compatibility mandates gate qualified supply access and premium-tier pricing for RFID validation equipment across European logistics corridors. Compliance certification costs concentrate in Vienna-based validation infrastructure, forcing tiered pricing stratification between accredited and non-accredited equipment tiers.
Pricing Analysis
GaN power amplifier input-cost pass-through is compressing handheld tester margins while tightening silicon LDMOS legacy architectures. Three-tier pricing structure across precision laboratory, field-deployable, and entry-level validation units separates EPCglobal Gen2 certified equipment from uncertified alternatives. Pricing pressure stems from gallium nitride substitution economics stranding existing manufacturing investments. Third-party logistics operators in Germany exhibit lowest price sensitivity due to compliance mandate rigidity, while mid-market retail procurement teams drive hardest bargain negotiations.
Supply Chain Analysis
China's MIIT radio type-approval local-content requirements are reshaping sourcing patterns for electromagnetic compatibility components across tester manufacturing. Supply concentration centers on South Korean semiconductor packaging corridors, German precision instrumentation clusters, and Chinese component assembly hubs. Critical dependencies include GaN wafers, microwave signal generators, and calibrated antenna arrays. Single-source vulnerability concentrates in Vienna-based protocol certification infrastructure. Distribution runs through direct vendor relationships replacing distributor-mediated channels among high-volume contract electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. German logistics operators are shifting procurement specifications toward EPCglobal Gen2 multi-phase certified equipment, elevating premium-tier demand.
For Market Incumbents: Cement protocol certification authority through captive Vienna lab investments or exclusive CISC Semiconductor partnership structures. Deepen backward integration into GaN amplifier supply chains to neutralize silicon LDMOS cost volatility. Defend against emerging microwave instrumentation specialists by locking long-term service contracts with German third-party logistics operators. For New Entrants and Emerging Players: Cloud-based test orchestration platforms represent the most penetrable buyer archetype currently underserved by legacy desktop-centric vendors. Target contract electronics manufacturers consolidating validation authority across multiple production sites with machine learning-integrated anomaly detection capabilities. Pursue payment terminal certification workflows as the fastest-expanding NFC segment entry point. For Investors and Strategic Acquirers: Roll-up economics work for regional certification specialists because electromagnetic compliance fragmentation across 860-960 MHz band assignments prevents single-vendor dominance. Long-term viability hinges on protocol influence rather than hardware manufacturing scale. Monitor EU Radio Equipment Directive amendment cycles as the critical inflection signal for conformance workload expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Amplifier Integration | Power efficiency gains enable handheld form-factor expansion into warehouse aisle mobility applications. |
| Vienna Lab Partnership | Exclusive CISC Semiconductor certification access locks out competitors from EU Radio Equipment Directive compliance workflows. |
| Machine Learning Test Automation | Anomaly detection algorithms reduce field technician deployment costs for German logistics operators. |
| Cloud-Based Test Orchestration | Centralized validation authority consolidation serves contract electronics manufacturers with multi-site operations. |
| NFC Certification Suite Expansion | EMVCo payment scheme mandates accelerate procurement across financial hardware supply chains. |
Research Methodology
Bottom-up logistics operator deployment modeling reconciled against top-down semiconductor packaging facility tracking forms the analytical core of this study. Primary interviews with RF test engineers, logistics infrastructure procurement managers, semiconductor packaging quality directors, and electromagnetic compliance consultants informed demand-side assumptions. Secondary validation drew from FCC Part 15 rulemaking dockets, ETSI UHF air-interface standards publications, MIIT radio type-approval registries, and SEC filings from microwave instrumentation heritage players.
Historical trendline analysis across ISO/IEC 18046 protocol revision cycles established baseline growth patterns. The projection framework segments by product configuration, end-use environment, technology type, and deployment architecture. CAGRs derive from equipment refresh cycle analysis, regulatory mandate expansion timelines, and substitution elasticity between GaN and silicon LDMOS amplifier technologies. Frequency allocation harmonization progress and payment terminal certification mandate intensity serve as key forecast inputs.
Underlying measurement precision varies by segment; handheld and desktop configurations carry tighter precision than emerging cloud-based deployment models due to established procurement data availability. Forecasts reflect assumptions around EU Radio Equipment Directive enforcement intensity, gallium nitride cost curves, and South Korean packaging corridor expansion rates. Regulatory amendment cycles, amplifier input cost volatility, and certification lab capacity constraints warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Tube Tester Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Oscilloscope Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Battery Testing Market
Test and Measurement
Global Platform Electronic Laboratory Balance Market