
 Sensor Hub Market | 2026-2036
Sensor Hub Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Hub Market Intelligence
The divergence in capital investment between fabless design houses and integrated device manufacturers is reorganizing the competitive landscape for sensor hubs. STMicroelectronics N.V. leverages its in-house manufacturing capabilities to offer integrated solutions for automotive and industrial clients. In contrast, Qualcomm Technologies Inc. specializes in highly integrated SoCs for mobile and IoT, relying on foundry partners. Robert Bosch GmbH differentiates through its deep expertise in MEMS technology, particularly for automotive safety and industrial systems.
A sensor hub is a microcontroller or coprocessor dedicated to aggregating and processing data from an array of sensors, such as accelerometers, gyroscopes, and magnetometers. Its primary purpose is to offload sensor fusion algorithms from a device's main central processing unit, enabling continuous, low-power operation for context-aware applications. Integrated sensor hubs, embedded within application processors, dominate the high-volume consumer electronics space. Smart wearables and robotics represent high-growth application areas, driven by consumer demand and industrial automation initiatives.
Market access is governed by electronic device and component standards, including CE marking requirements in the European Union and FCC regulations in the United States for radio frequency interference. Global directives like RoHS restrict the use of hazardous materials in manufacturing, influencing material selection and supply chain compliance. Stakeholder focus now turns to the integration of on-device AI and machine learning capabilities, which determines the next generation of sensor hub architecture and processing power.
Market Dynamics
The push to embed machine learning capabilities directly onto devices is the central force redefining sensor hub architecture. This shift favors on-device processing to reduce latency and data privacy risks, particularly in context-aware automotive and consumer applications.
Growth Catalysts
- Industrial Automation:Demand from smart factories in Germany and China for predictive maintenance and process control systems requires sophisticated sensor data aggregation, directly fueling sensor hub adoption.
- MEMS Sensor Proliferation:The expanding use of low-cost MEMS accelerometers and gyroscopes in consumer wearables and smart home devices necessitates dedicated processors to manage sensor fusion algorithms efficiently.
- Automotive Safety Mandates:Regulations from bodies like the NHTSA and their European counterparts for advanced driver-assistance systems (ADAS) compel the use of sensor hubs to process data from radar, LiDAR, and cameras.
Market Restraints
- Power Consumption Trade-offs:Integrating advanced AI processing capabilities increases power draw, posing a significant design constraint for battery-dependent devices like smartwatches and remote industrial sensors.
- Semiconductor Bottlenecks:The high concentration of advanced logic and memory fabrication in specific geographies like Taiwan creates supply chain vulnerability and potential input cost volatility for all sensor hub manufacturers.
- High Integration Costs:The non-recurring engineering costs associated with designing and validating complex System-on-Chip (SoC) solutions that embed sensor hubs are prohibitive for smaller device manufacturers.
Strategic Opportunities
- Precision Agriculture:The deployment of sensor hubs in autonomous agricultural drones and ground vehicles for soil moisture monitoring and crop health analysis represents a significant new application vertical.
- Edge AI Convergence:Combining sensor hubs with dedicated neural processing units (NPUs) on a single chip creates opportunities for highly autonomous, real-time decision-making in robotics and industrial inspection.
- Smart City Infrastructure:Government initiatives in nations like India to build smart cities create demand for large-scale networks of environmental and traffic sensors managed by low-power sensor hubs.
Industry Challenges
- System Integration Complexity:Developers face significant hurdles in ensuring interoperability between sensor hubs and a wide array of proprietary legacy industrial control systems and factory automation software.
- Specialized Talent Scarcity:A shortage of engineers skilled in both low-power embedded systems design and machine learning algorithm optimization constrains the pace of product development and innovation.
- Protocol Standardization Gaps:The absence of universal standards for sensor data communication and formatting complicates the design of versatile hubs capable of aggregating data from multi-vendor sensor arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Hub Market |
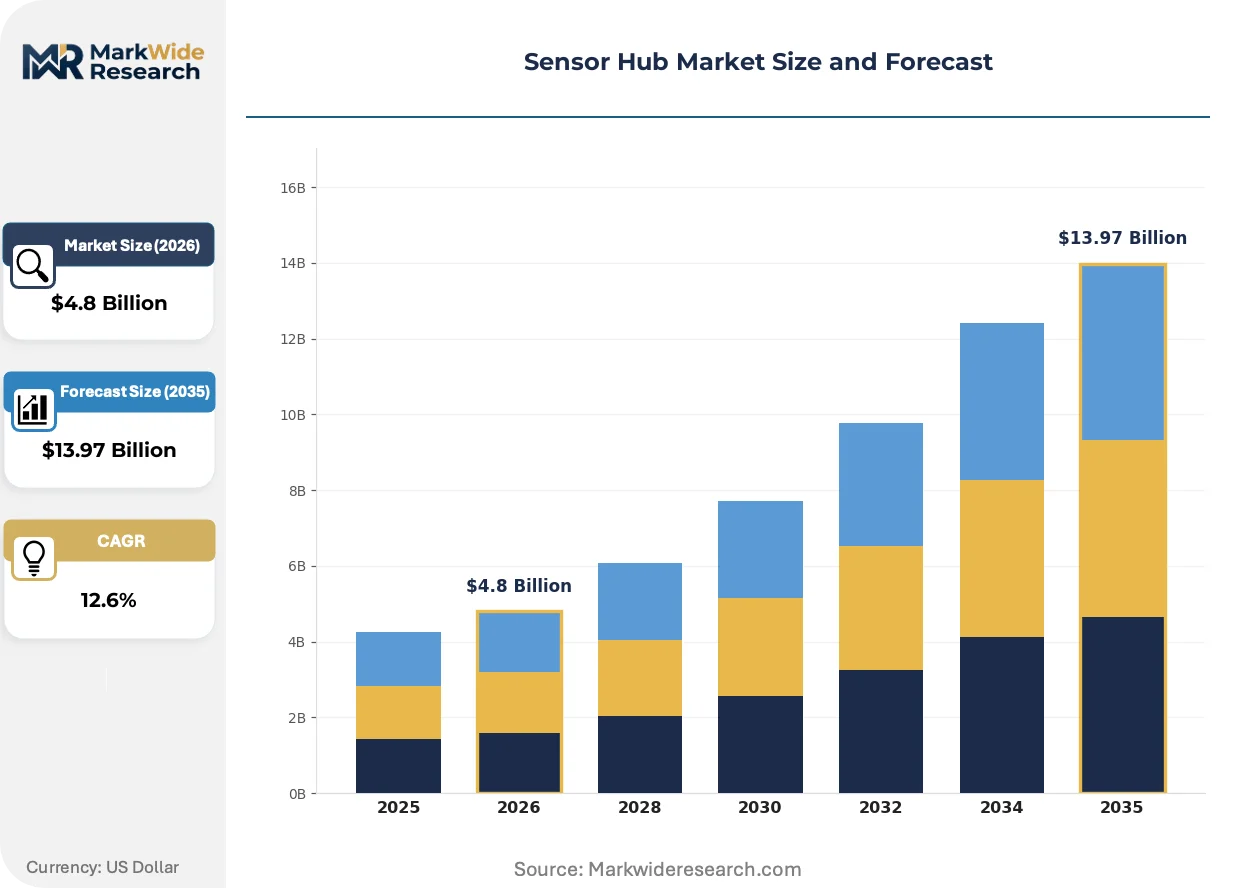
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Sensor Hub, Modular Sensor Hub, Standalone Sensor Hub, Wireless Sensor Hub Technology: MEMS, Optical, Ultrasonic, Capacitive, Piezoelectric, Magnetic Application: Smart Wearables, Industrial Automation, Consumer Electronics, Smart Agriculture, Robotics End User: Smartphone Manufacturers, Electronics OEMs, Industrial Equipment Makers, Agriculture Solution Providers |
| Companies Covered | Texas Instruments, Infineon Technologies AG, Robert Bosch GmbH, Qualcomm Technologies Inc., Bosch Sensortec GmbH, STMicroelectronics N.V., Analog Devices, TDK Corporation, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Hub Market Strategic Shifts & Innovations
Intelligence is rapidly decentralizing from the cloud to the network edge. This movement toward on-device computation reshapes sensor hub design priorities, emphasizing local processing power, energy efficiency, and data security over simple data aggregation and transmission.
The integration of dedicated neural processing units (NPUs) directly within sensor hub microcontrollers is a defining product evolution. This technology enables on-device execution of machine learning models for tasks like keyword spotting or activity recognition. Adoption is accelerating in premium wearables and automotive infotainment, and this integration of localized machine learning is fragmenting the traditional cloud-dependent model for data analysis.
Data privacy mandates, particularly the EU's General Data Protection Regulation (GDPR), are influencing system architecture. This regulation incentivizes processing sensitive information locally to minimize data transfer and enhance user privacy compliance. The consumer health and wellness sector is most affected, driving demand for sensor hubs capable of performing biometric analysis directly on-device without exposing raw data.
A preference for comprehensive software support is altering procurement patterns for sensor hubs. End-users are shifting from purchasing discrete hardware components to selecting vendors that provide robust software development kits (SDKs), pre-validated algorithms, and reference designs. This change is most prominent in the competitive robotics and IoT startup ecosystem, where faster development cycles are critical.
Sensor Hub Market Segmentation
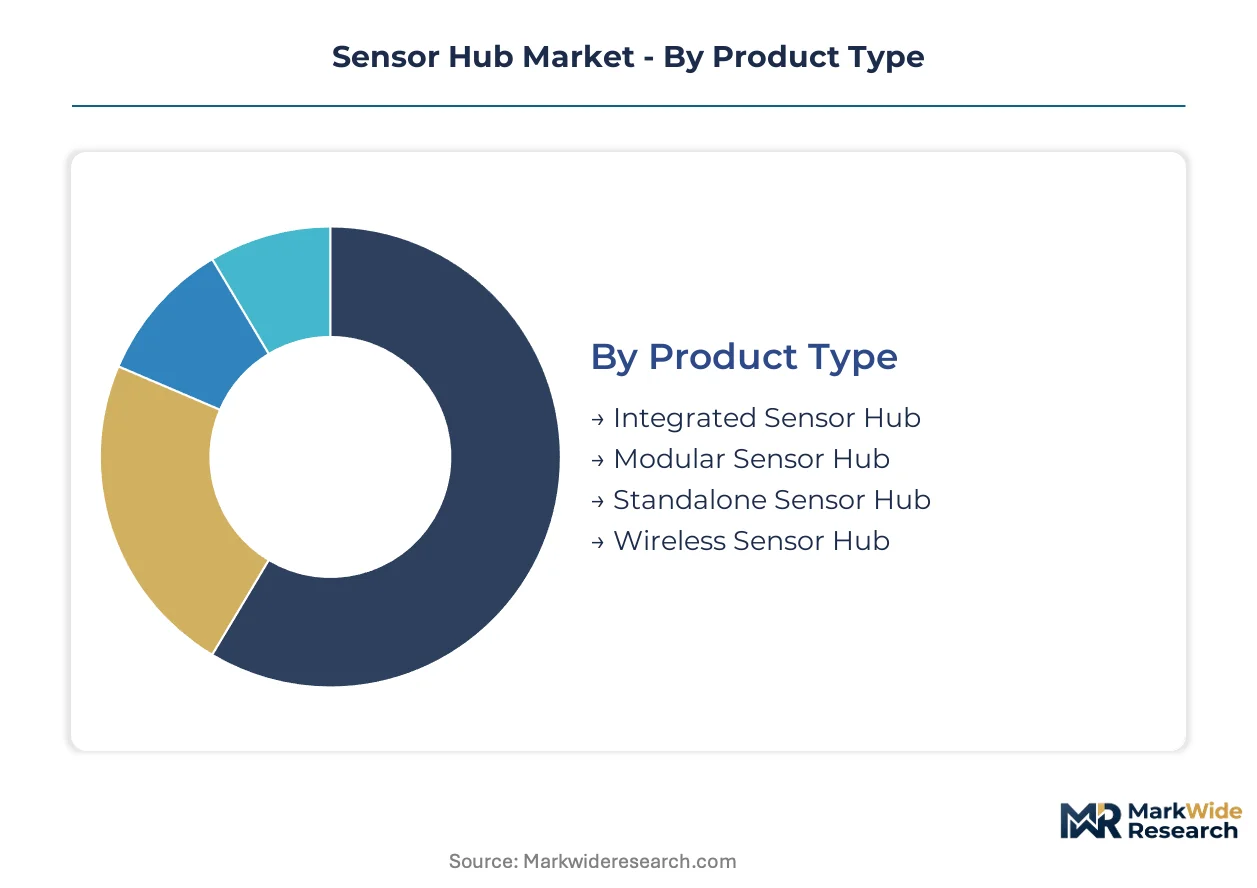
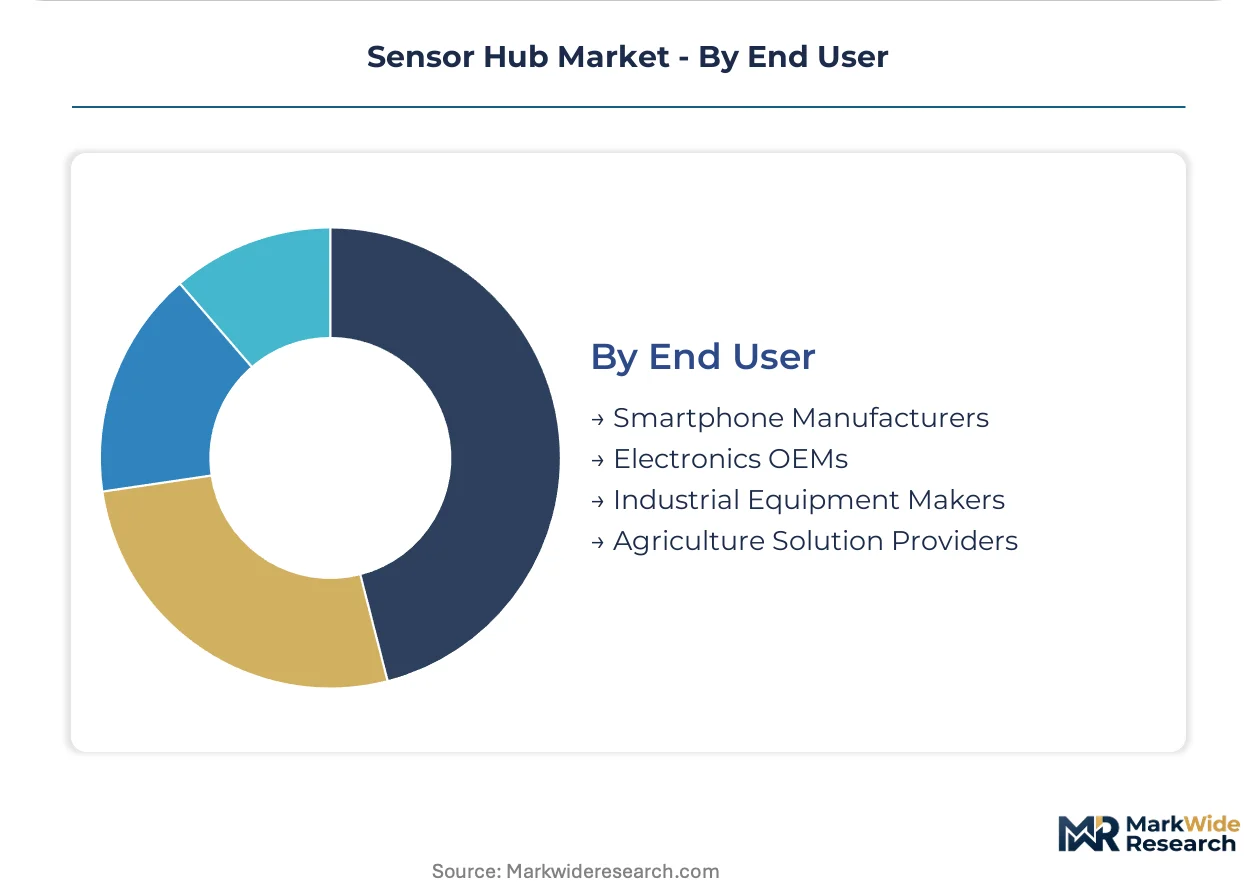
The Sensor Hub market segmentation provides a granular view of product types, underlying technologies, diverse applications, and key end-user groups. Understanding these distinctions reveals how technological advancements and shifting demand patterns influence market dynamics. This detailed breakdown helps identify areas of concentrated growth and emerging opportunities for stakeholders.
Product Type:
The product type segment faces intense substitution pressure, particularly as integrated solutions increasingly displace standalone components in compact devices.
- Integrated Sensor Hub:These are microcontrollers or coprocessors embedded directly within a device's main application processor, offering seamless data flow and optimized power efficiency. Demand concentrates in high-volume consumer electronics and mobile devices, driven by the need for continuous context awareness.
- Wireless Sensor Hub:Demand accelerates in industrial IoT deployments and remote monitoring across Germany and China, facilitating distributed data collection. These devices integrate sensor aggregation with wireless communication capabilities, often using Bluetooth Low Energy or Wi-Fi.
- Modular Sensor Hub:Configurable units allow for flexible integration into various systems, providing adaptability for specific industrial or specialized applications.
- Standalone Sensor Hub:Dedicated chips manage sensor fusion tasks independently, critical for CPU offload in performance-sensitive systems.
Integrated Sensor Hub retains volume leadership; Wireless Sensor Hub holds the steepest expansion curve.
Technology:
The technology segment reflects varying cost tiers and performance capabilities, with each type optimized for distinct sensing requirements and integration challenges.
- MEMS:Micro-Electro-Mechanical Systems sensors are miniaturized devices offering high precision and low power for accelerometers and gyroscopes. Widespread adoption in smart wearables and mobile phones across South Korea and China drives significant sensor hub integration.
- Optical:Optical sensors utilize light to detect physical quantities, ranging from ambient light detection to advanced LiDAR systems for distance and object recognition. Demand is concentrating in automotive ADAS systems, where they enable critical safety functions and environmental perception.
- Ultrasonic:Ultrasonic sensors emit high-frequency sound waves to measure distance or detect objects, common in automotive parking assistance.
- Capacitive:Capacitive sensors detect changes in electrical capacitance, used for touch interfaces, proximity sensing, and material property analysis in consumer devices.
- Piezoelectric:Piezoelectric elements generate an electrical charge under mechanical stress, ideal for pressure sensing, vibration monitoring, and energy harvesting.
- Magnetic:Magnetic sensors detect magnetic fields, crucial for compass functions in navigation systems and position sensing in industrial machinery.
MEMS technology maintains its foundational role in sensor hubs, while optical sensing is gaining significant traction in high-value automotive applications.
Application:
The application segment exhibits diverse volume requirements and performance demands, from high-throughput industrial processes to low-power consumer interactions.
- Industrial Automation:Sensor hubs in industrial settings aggregate data from various production line sensors for real-time monitoring, predictive maintenance, and process control. Demand is particularly strong in smart factories across Germany and China, supporting advanced manufacturing initiatives.
- Smart Wearables:These applications require ultra-low power sensor hubs to process biometric data, activity tracking, and gesture recognition for fitness bands and smartwatches. Consumer demand for health monitoring and convenience drives their integration into compact, battery-dependent devices.
- Consumer Electronics:This broad category includes smartphones, tablets, and smart home devices, where sensor hubs enable context awareness and gesture control.
- Smart Agriculture:Sensor hubs in agriculture support autonomous drones and vehicles for soil analysis, crop health, and precision farming.
- Robotics:Sensor hubs provide critical environmental perception and motion control for autonomous robots, enabling navigation and interaction in complex environments.
Industrial Automation drives significant sensor hub consumption, with Smart Wearables showing rapid expansion.
End User:
The end user segment reflects distinct customer types, each with unique procurement patterns, technical specifications, and volume requirements for sensor hub integration.
- Smartphone Manufacturers:These companies integrate sensor hubs into high-volume mobile devices, prioritizing compact size, low power consumption, and advanced context-aware features. Their demand dictates significant market volumes and drives innovation in integrated SoC solutions.
- Electronics OEMs:Original Equipment Manufacturers across various sectors, from white goods to medical devices, procure sensor hubs for diverse product lines. They seek flexible, cost-effective solutions that can be customized for specific application requirements and scales.
- Industrial Equipment Makers:These manufacturers integrate robust sensor hubs into machinery for factory automation, process control, and predictive maintenance in demanding environments.
- Agriculture Solution Providers:Agriculture solution providers utilize sensor hubs for environmental monitoring and robotic control in precision farming tools.
Smartphone Manufacturers dictate the largest market share, as general Electronics OEMs diversify demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for sensor hubs varies significantly across applications, with consumer electronics exhibiting higher price sensitivity compared to industrial automation and automotive sectors. These latter segments prioritize reliability and performance, driving investment in advanced sensor hub technologies in key manufacturing economies. Geographic concentration of advanced manufacturing capabilities shapes regional demand patterns for these specialized components.
Germany
Industrial automation and the robust automotive sector drive significant sensor hub consumption in Germany. Regulations like CE marking and KBA mandates for vehicle safety systems compel the integration of advanced sensor fusion. The Stuttgart region, home to major automotive and industrial technology firms, remains a critical hub for sensor hub development and deployment.
China
China's rapid expansion in smart factories and industrial IoT fuels strong demand for sensor hubs for process control and predictive maintenance. Government initiatives, including GB standards for electronic components, influence product specifications and market access. The Yangtze River Delta region, with its extensive electronics manufacturing base, sees high adoption of integrated sensor solutions.
South Korea
The proliferation of MEMS-based sensors in smart wearables and high-volume consumer electronics underpins sensor hub demand in South Korea. The MFDS regulations for health-related devices encourage on-device processing capabilities for privacy and efficiency. The Seoul Capital Area, a center for consumer electronics innovation, drives continuous advancement in compact, low-power sensor hubs.
United States
The United States sees strong sensor hub demand from automotive safety mandates by NHTSA for ADAS systems and from the burgeoning robotics sector. FCC regulations for wireless devices also impact sensor hub design for connected applications. Silicon Valley, a global technology hub, continues to innovate in advanced sensor fusion algorithms and embedded AI for diverse applications.
India
India's smart city initiatives and growing precision agriculture sector create new opportunities for low-power sensor hubs in large-scale environmental monitoring and autonomous vehicles. The BIS standards for electronic products guide market entry and quality assurance. Bengaluru, a prominent tech hub, is witnessing increased R&D and deployment of sensor-driven solutions for urban and agricultural intelligence.
Sensor Hub Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the sensor hub market. The competitive landscape is characterized by a mix of vertically integrated device manufacturers and specialized fabless design houses. Strategic partnerships between sensor manufacturers and software developers are becoming crucial for delivering comprehensive, pre-validated solutions to end-users.
Specialists in highly integrated System-on-Chip (SoC) solutions, such as Qualcomm Technologies Inc., leverage foundry partners for mobile and IoT applications. STMicroelectronics N.V. exemplifies an integrated device manufacturer, utilizing in-house capabilities to offer comprehensive solutions for automotive and industrial clients. Robert Bosch GmbH occupies a position as a leader in MEMS technology, particularly for automotive safety and industrial systems, anchoring its competitive stance through deep domain expertise.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| Qualcomm Technologies Inc. |
| Bosch Sensortec GmbH |
| STMicroelectronics N.V. |
| Analog Devices |
| TDK Corporation |
| NXP Semiconductors N.V. |
| Others |
Cost & Logistics Intelligence
CE marking requirements in the European Union and FCC regulations in the United States gate both component supply qualification and influence price differentiation for sensor hubs. These frameworks command a premium for compliant and certified solutions.
Pricing Analysis
After-sales software and service licensing drives significant lifetime value for sensor hub providers, particularly for complex integrated solutions. The dominant pricing model remains per-unit transactional for hardware, often complemented by licensing for proprietary software, algorithms, and development kits. Price differentiation stems from certification levels, the degree of customization, and the breadth of software ecosystem support. Pricing pressure intensifies in high-volume consumer electronics due to component commoditization. Industrial and automotive sectors exhibit lower price sensitivity, prioritizing reliability and long-term support over upfront cost.
Supply Chain Analysis
Taiwan and South Korea anchor advanced logic and MEMS fabrication, forming critical nodes in the sensor hub supply chain. The market draws from core dependencies on specialized silicon wafers, advanced packaging materials, and precision MEMS components. Semiconductor bottlenecks, particularly for leading-edge process nodes, pose a structural supply chain risk, leading to potential input cost volatility. Downstream distribution runs through direct sales channels to large OEMs and a network of specialized electronics distributors for smaller enterprises and modular solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sensor Hub market is inflecting towards platform economics, driven by the need for seamless interoperability between diverse sensor arrays and on-device AI processing ecosystems. This shift redefines value creation beyond discrete hardware components.
For Market Incumbents:Consolidate market share by investing heavily in proprietary embedded AI/ML intellectual property and expanding integrated System-on-Chip (SoC) offerings tailored for key industrial and automotive verticals. This strategy counters the threat from specialized NPU firms and generic ASIC providers entering the edge processing space. Leverage existing in-house manufacturing capabilities to control costs and ensure supply, reinforcing a competitive advantage against fabless competitors.
For New Entrants and Emerging Players:Differentiate on specialized low-power AI processing for niche applications, such as remote environmental monitoring in precision agriculture or complex sensor fusion for autonomous robotics. The robotics and IoT startup ecosystem represents a highly penetrable segment due to its demand for rapid development cycles and customized solutions. A compelling go-to-market angle involves providing comprehensive software development kits, pre-validated algorithms, and robust reference designs to accelerate customer integration.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the integrated sensor hub sub-segment, driven by escalating R&D for embedded AI and advanced process node requirements. Long-term viability favors firms with strong intellectual property in on-device machine learning and robust software ecosystems. Acquisition targets should be fabless design houses with unique AI acceleration IP or deep expertise in specific sensor fusion algorithms. A key signal is the accelerating adoption of dedicated Neural Processing Units (NPUs) in premium consumer electronics and ADAS.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-Enabled Sensor Hubs | Introduces next-generation products with on-device machine learning capabilities for enhanced context awareness. |
| Develop Comprehensive Software Ecosystems | Attracts developers and accelerates integration, reducing time-to-market for end-user applications. |
| Form Strategic Partnerships with AI Specialists | Accesses cutting-edge AI algorithms and optimizes sensor fusion for specific high-growth applications. |
| Acquire Niche Sensor Fusion IP Firms | Expands intellectual property portfolio and strengthens differentiation in specialized, performance-critical domains. |
| Expand Geographic Focus on Smart Factories | Captures demand in advanced manufacturing economies like Germany and China for industrial automation. |
Research Approach
Operator-level perspectives from CTOs of electronics OEMs, industrial automation engineers, automotive ADAS architects, and smart city planners anchored the qualitative base of this study. Primary interviews with these industry stakeholders were rigorously combined with secondary validation from SEC filings of semiconductor firms, industry association reports, and academic research on embedded AI. Bottom-up and top-down triangulation ensured data consistency.
Sensitivity analysis formed the core of the forecasting framework, modeling various market scenarios across the projection horizon. Segmentation dimensions included product type, technology, application, end user, and regional regulatory compliance. CAGRs were derived from historical trends and projected technological adoption curves. Key forecast inputs included MEMS sensor cost trends and NPU integration rates.
Material uncertainties — including geopolitical semiconductor trade policies and unforeseen technological breakthroughs in quantum sensing — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Refrigeration Gauge Market