
 Creep and Stress Rupture Testers Market | 2026-2036
Creep and Stress Rupture Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Creep and Stress Rupture Testers Market Outlook
Direct sales from original equipment manufacturers to certified testing laboratories is tilting toward bundled service contracts that include calibration and compliance support. Westmoreland Mechanical Testing leverages its Pennsylvania-based metallurgical heritage to dominate high-temperature alloy verification for power generation clients. Applied Test Systems sustains competitive positioning through in-house production of furnace systems that pair with its mechanical load frames. Element Materials Technology operates a decentralized laboratory network that extends geographic reach without sacrificing ASTM E139 traceability.
Creep and stress rupture testers apply sustained tensile or flexural loads to materials at elevated temperatures for extended durations, typically measuring deformation rates to failure under conditions exceeding 1,000 hours at temperatures up to 1,200°C; these instruments certify structural integrity for components operating under thermal-mechanical fatigue in jet engines, nuclear pressure vessels, and petrochemical reactors. Electronic testers capture the fastest-growing share of product type demand because semiconductor strain-gauge resolution enables real-time data logging that reduces technician intervention during thousand-hour runs. Computer-controlled technology segments concentrate margin pools where software-defined test profiles allow unattended overnight operation and automated compliance reporting.
FAA airworthiness directives and ASTM E139 standards govern North American equipment qualification, while EASA Certification Memoranda and the EU AI Act's emerging quality-system requirements shape European procurement specifications. China's GB/T 2039 and NMPA-equivalent material certification protocols create parallel compliance pathways for exporters serving domestic turbine manufacturers. Stakeholders must monitor divergence between regional temperature-calibration standards and decide whether to maintain separate instrument configurations or pursue unified metrology platforms that satisfy multiple jurisdictions simultaneously.
Market Dynamics
Electronic strain-gauge instrumentation is compressing test cycle durations and displacing mechanical lever systems in high-temperature metallurgical verification, forcing equipment suppliers to reconfigure their furnace-load frame architectures around real-time data acquisition capabilities.
Growth Catalysts
- FAA Airworthiness Directives:The FAA's expanded material qualification protocols for turbine blade alloys mandate thousand-hour creep certification cycles, pulling demand for automated electronic testers from aerospace component suppliers.
- Supercritical coal plant retrofits:Utilities in Germany and Japan require re-certification of steam piping under elevated temperature-pressure regimes, sustaining replacement demand for high-capacity rupture testing equipment.
- Semiconductor strain-gauge resolution:Sub-microstrain measurement precision enables unattended overnight operation, reducing laboratory technician costs and expanding test throughput for commercial laboratories.
Market Restraints
- Platinum-rhodium thermocouple supply:Concentration of noble metal refining in South Africa creates input cost volatility for furnace systems operating above 1,000°C.
- Calibration laboratory scarcity:ISO 17025-accredited temperature calibration facilities cluster in Germany, the United States, and Japan, extending lead times for equipment commissioning in peripheral markets.
- Mechanical lever system entrenchment:Legacy dead-weight testers retain preference in nuclear pressure vessel certification due to regulatory familiarity, slowing electronic system penetration.
Strategic Opportunities
- India's PLI scheme for turbine manufacturing:Domestic alloy certification requirements under CEA thermal power guidelines create first-mover positioning for equipment suppliers establishing local service infrastructure.
- Additive manufacturing qualification:Powder-bed fusion components for jet engine brackets require novel creep protocols, opening specialized testing service contracts.
- EU AI Act quality-system requirements:Emerging algorithmic traceability mandates for automated test interpretation favor suppliers with embedded compliance documentation software.
Industry Challenges
- Metallurgical technician specialization:Thousand-hour test supervision requires expertise in ASTM E139 deviation analysis, constraining laboratory expansion.
- Multi-jurisdiction calibration synchronization:Divergent temperature standards between FAA, EASA, and GB/T 2039 protocols force equipment reconfiguration for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creep and Stress Rupture Testers Market |
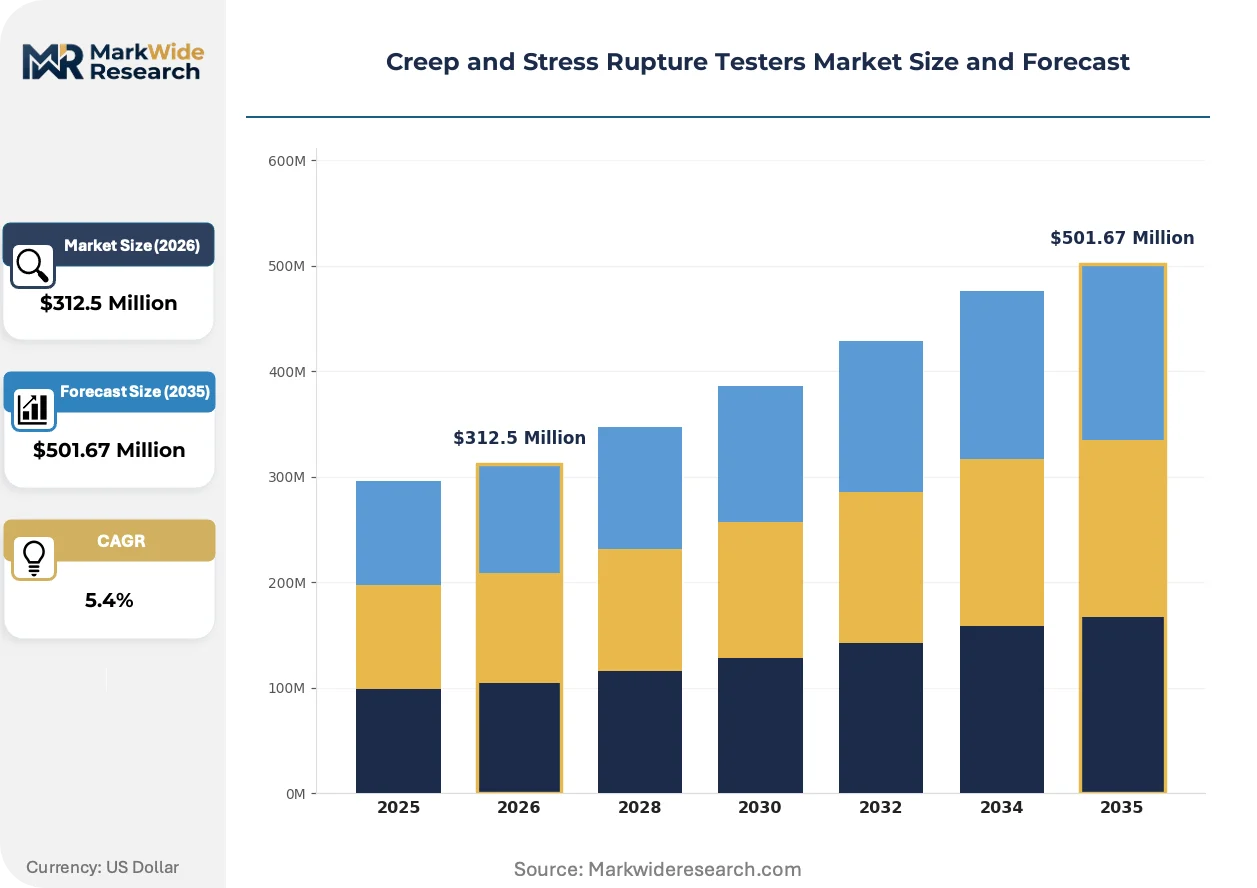
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Testers, Mechanical Testers, Electronic Testers, Universal Testers Technology: Digital, Analog, Computer-controlled, Manual Industry Vertical: Aerospace, Energy, Manufacturing, Automotive Application: Material Testing, Research & Development, Quality Assurance, Product Certification |
| Companies Covered | Westmoreland Mechanical Testing, Qualitest International Inc., Applied Test Systems, IMR Test Labs, Jinan Victory Instrument, Element Materials Technology, WANCE, Raagen, Laboratory Testing, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creep and Stress Rupture Testers Market Strategic Shifts
Digital instrumentation architectures are displacing analog measurement chains across high-temperature materials testing, compressing data latency and enabling predictive failure detection algorithms that reshape laboratory staffing models.
Semiconductor strain-gauge transducers with sub-microstrain resolution are digitizing deformation measurement in creep and stress rupture applications. Aerospace certified testing laboratories in Germany and the United States are retrofitting existing load frames with these sensors to eliminate manual extensometer repositioning during thousand-hour runs. Real-time data streaming is digitizing compliance documentation, collapsing the post-test report generation interval from days to hours.
REACH restrictions on hexavalent chromium surface treatments are forcing furnace component manufacturers to migrate toward alumina-coated heating elements. European equipment suppliers face reformulation costs for retort assemblies and thermocouple protection sheaths previously reliant on chromized steel. The thermal uniformity specification segment is absorbing the transition friction, with EASA-aligned laboratories demanding extended validation protocols for alternative coating chemistries.
After-sales service unbundling is fragmenting buyer-supplier relationships in the commercial laboratory segment. Independent testing houses in Japan are separating calibration contracts from equipment purchase agreements, pressuring original equipment manufacturers to compete with third-party metrology specialists. This disintermediation is most pronounced in turbine blade certification workflows, where specialized thermal calibration providers undercut bundled service pricing.
Creep and Stress Rupture Testers Market Segmentation
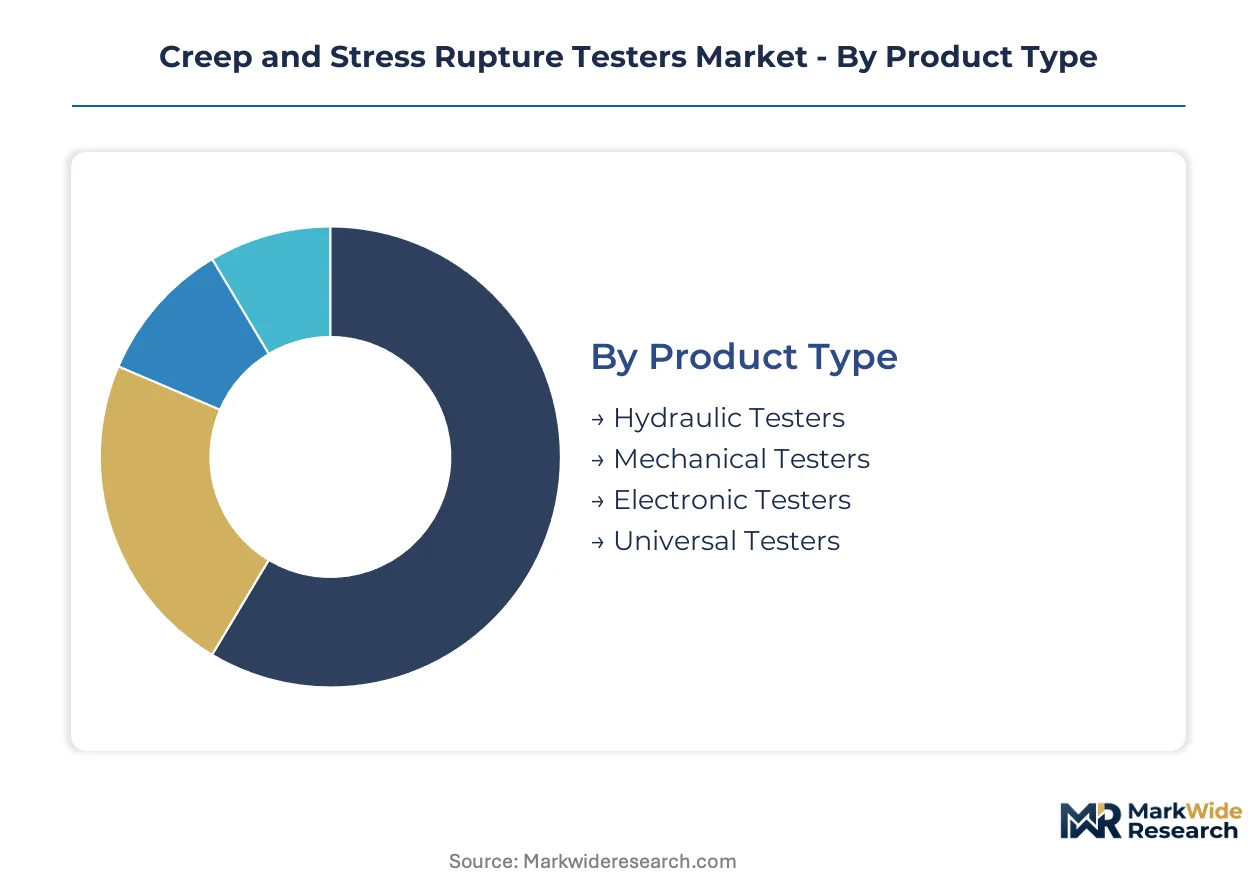
Creep and stress rupture testers serve divergent operational requirements across laboratory environments, from thousand-hour turbine blade certification runs to rapid-turnaround additive manufacturing qualification. Equipment specifications vary sharply by thermal endurance, load precision, and automation depth, creating distinct procurement patterns among aerospace OEMs, commercial testing houses, and research institutions.
Product Type:
Use cases span legacy dead-weight verification for nuclear pressure vessels through semiconductor-equipped electronic systems enabling unattended overnight operation.
- Electronic Testers:Semiconductor strain-gauge transducers deliver sub-microstrain resolution with real-time data streaming to laboratory information management systems. Demand concentrates in Germany and the United States, where FAA and EASA airworthiness directives mandate automated thousand-hour certification cycles for single-crystal turbine blade alloys.
- Hydraulic Testers:Closed-loop servo-hydraulic actuators generate sustained loads up to 300 kN for large-section piping and pressure vessel qualification. Energy sector procurement in Japan sustains replacement demand as utilities re-certify supercritical steam infrastructure under elevated temperature-pressure regimes.
- Mechanical Testers:Lever-arm dead-weight systems retain regulatory preference in nuclear certification workflows due to decades of ASTM E139 precedent.
- Universal Testers:Modular load-frame architectures accommodate interchangeable furnace configurations for multi-material testing programs.
Established volume favors hydraulic testers; emerging adoption favors electronic testers.
Technology:
Cost tiers separate capital-intensive computer-controlled installations from maintenance-heavy analog alternatives.
- Computer-controlled:Software-defined test profiles integrate predictive failure detection algorithms with automated compliance documentation generation. Commercial laboratories in the United States retrofit existing frames with these architectures to collapse post-test report intervals from days to hours.
- Digital:Direct-to-digital strain measurement eliminates analog signal conditioning chains, compressing data latency for real-time deformation tracking.
- Manual:Technician-dependent operation persists in developing markets where calibration infrastructure scarcity extends equipment commissioning timelines.
- Analog:Potentiometric extensometers and chart recorders serve budget-constrained educational institutions with limited test throughput requirements.
Procurement budgets favor digital architectures; regulatory familiarity sustains analog retention.
Industry Vertical:
Customer type determines specification stringency, from aerospace OEM captive laboratories to third-party commercial testing houses.
- Aerospace:Single-crystal superalloy turbine blades require thousand-hour creep rupture certification under FAA airworthiness directives and EASA Certification Memoranda. Component manufacturers in Germany and the United States drive demand for electronic testers with embedded ASTM E139 traceability.
- Energy:Steam piping and nuclear pressure vessel re-certification under elevated thermal-mechanical fatigue conditions sustains hydraulic tester replacement cycles. German utilities retrofitting supercritical coal plants require high-capacity rupture testing for 625°C steam conditions.
- Manufacturing:Additive manufacturing qualification for powder-bed fusion jet engine brackets creates specialized testing service contracts with novel creep protocols.
- Automotive:Turbocharger turbine wheel and exhaust manifold alloy screening requires shorter-duration creep testing at moderate temperatures.
Specification intensity favors aerospace; volume scale favors energy.
Application:
Maturity gradients separate standardized quality assurance workflows from experimental research protocols.
- Quality Assurance:Production lot verification for turbine blade castings follows regimented ASTM E139 protocols with predefined acceptance criteria. Commercial laboratories in Japan operate dedicated creep testing cells for continuous aerospace supplier certification.
- Product Certification:Regulatory submission documentation requires ISO 17025-accredited calibration chains with full metrological traceability.
- Material Testing:Alloy development programs for next-generation thermal barrier coatings explore extended-duration creep behavior under novel temperature-stress combinations.
- Research & Development:Academic institutions investigate deformation mechanisms in additively manufactured nickel superalloys with customized test profiles outside standard certification frameworks.
Standardized throughput favors quality assurance; margin capture favors product certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Alaska Pipeline System and Gulf Coast petrochemical corridor anchor North American thermal-mechanical testing infrastructure. Germany's Ruhr industrial belt and Japan's Pacific coastal manufacturing zone sustain equivalent demand concentrations for high-temperature alloy verification.
United States
FAA airworthiness directives for single-crystal turbine blade certification drive thousand-hour automated testing protocols. The Department of Energy maintains supercritical coal plant re-certification schedules under FERC thermal efficiency mandates. Houston-Gulf Coast petrochemical clusters require continuous rupture testing for 625°C steam piping infrastructure.
Germany
Utility retrofit programs for supercritical coal plants sustain replacement demand for high-capacity hydraulic testers. EASA Certification Memoranda align with REACH restrictions on hexavalent chromium furnace components. Ruhr industrial belt laboratories specialize in nuclear pressure vessel re-certification under elevated thermal-fatigue conditions.
Japan
Domestic turbine manufacturers enforce GB/T 2039-equivalent protocols for alloy export certification to Chinese markets. METI thermal power guidelines mandate steam piping re-certification under elevated pressure-temperature regimes. Nagoya-Osaka manufacturing corridor hosts dedicated creep testing cells for continuous aerospace supplier qualification.
China
NMPA-equivalent material certification protocols create parallel compliance pathways for domestic turbine blade production. MIIT industrial standards for additive manufacturing components require novel creep protocols for powder-bed fusion qualification. Yangtze River Delta testing laboratories expand capacity to serve aviation OEM captive certification programs.
India
PLI scheme incentives for domestic turbine manufacturing generate first-mover equipment demand for alloy verification infrastructure. CEA thermal power guidelines mandate re-certification protocols for supercritical steam piping networks. Gujarat-Maharashtra industrial corridor attracts testing laboratory expansion to serve emerging domestic aerospace component suppliers.
Creep and Stress Rupture Testers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in furnace architecture and calibration services. The vendor base organizes around three strategic archetypes: metallurgical heritage laboratories with captive testing protocols, in-house furnace manufacturers with load-frame integration capabilities, and decentralized laboratory networks with geographic reach. Competitive moves concentrate on bundled service contract expansion and calibration infrastructure proximity to end-user clusters.
Among North American heritage laboratories, Westmoreland Mechanical Testing and Element Materials Technology occupy positions emphasizing geographic proximity to power generation and aerospace clusters. Applied Test Systems exemplifies the integrated manufacturer archetype through in-house furnace production paired with mechanical load frames. Jinan Victory Instrument and WANCE represent Chinese equipment fabricators serving domestic turbine certification demand under GB/T 2039 protocols.
| Leading Market Players |
|---|
| Westmoreland Mechanical Testing |
| Qualitest International Inc. |
| Applied Test Systems |
| IMR Test Labs |
| Jinan Victory Instrument |
| Element Materials Technology |
| WANCE |
| Raagen |
| Laboratory Testing, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Port of Hamburg-Rotterdam corridor shapes logistics cost dynamics for furnace system deliveries from German fabricators to North American aerospace laboratories, compressing margins on mid-tier electronic testers while amplifying price differentiation between ISO 17025-accredited premium systems and unbundled economy configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bundled service contracts with embedded calibration from stripped hardware-only transactions and refurbished legacy installations. Price differentiation hinges on ASTM E139 traceability certification and after-sales service bundling, with commercial laboratories in Japan exhibiting highest sensitivity to upfront capital outlay. Cost compression in the standard tier is intensifying because independent thermal calibration providers undercut OEM service pricing. Aerospace OEM captive laboratories demonstrate least price sensitivity, prioritizing compliance documentation automation over acquisition cost.
Supply Chain Analysis
Platinum-rhodium thermocouple feedstock draws from South African noble metal refining concentration, with alumina-coated heating element substrates sourced from German ceramics specialists and semiconductor strain-gauge transducers anchored in Japanese precision manufacturing. Raw material dependencies encompass noble metal thermocouple wire, high-purity alumina retort assemblies, and sub-microstrain resolution transducers. Single-source vulnerability in South African platinum group metal supply creates furnace system input cost volatility. Distribution runs through original equipment manufacturer direct sales channels and third-party laboratory service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic strain-gauge instrumentation is accelerating test automation adoption, with FAA and EASA airworthiness directive expansion creating regulatory inflection demand for thousand-hour unattended certification protocols.
For Market Incumbents: Pre-empt independent calibration provider encroachment by embedding predictive failure detection algorithms into software-defined test profiles, tightening customer switching costs. Acquire specialized thermal calibration facilities in Germany and the United States to defend service revenue pools against third-party metrology specialists. Deepen in-house furnace production capabilities to maintain margin control amid noble metal input volatility.
For New Entrants and Emerging Players: Build out additive manufacturing qualification service contracts targeting powder-bed fusion jet engine bracket certification, where novel creep protocols lack established incumbent relationships. India's PLI scheme for domestic turbine manufacturing offers penetrable white-space demand for alloy verification infrastructure. Pursue calibration infrastructure partnerships with CEA-aligned laboratories to circumvent ISO 17025 accreditation barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallurgical heritage laboratories with captive ASTM E139 protocols and embedded compliance software architectures. Long-term viability rests on algorithmic traceability capabilities under emerging EU AI Act quality-system requirements. Watch for divergence between FAA, EASA, and GB/T 2039 temperature-calibration standards as signal for unified metrology platform investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | ISO 17025-accredited facility proximity compresses equipment commissioning lead times for peripheral markets. |
| Embedded Compliance Software Development | Automated ASTM E139 documentation generation collapses post-test report intervals from days to hours. |
| Alternative Coating Chemistry Validation | REACH-aligned alumina-coated heating elements satisfy EASA thermal uniformity specifications without chromized steel. |
| Service Contract Bundling | Integrated calibration and compliance support contracts defend margin pools against independent metrology providers. |
| Additive Manufacturing Protocol Development | Specialized creep testing for powder-bed fusion components opens service contracts outside legacy certification frameworks. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with equipment procurement officers at commercial testing laboratories, furnace system engineers at power generation utilities, and regulatory compliance leads at aerospace OEMs; and secondary validation against FAA airworthiness directive filings, EASA Certification Memoranda, ASTM E139 standard revisions, and customs trade data for high-temperature testing equipment. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Forecast inputs encompassed product type migration patterns, technology adoption curves for computer-controlled architectures, and vertical demand intensity across aerospace and energy sectors. Segmentation dimensions modeled include tester product category, control technology tier, industry vertical specification stringency, and application maturity gradient. CAGRs were derived from installed base replacement cycles and greenfield capacity additions across the projection horizon. Industry-specific inputs incorporated supercritical coal plant retrofit schedules and additive manufacturing qualification pipeline expansion.
Stress conditions across platinum-rhodium supply disruption, calibration laboratory scarcity extension, and multi-jurisdiction standard divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Cross-checking against NIST-traceable equipment shipment databases and ISO 17025 accreditation registry growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Network Tester Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
North America Automated Test Equipment Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
United States Borescope Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Simulation and Test Data Management Market