
 Semiconductor Metrology and Inspection Equipment Market | 2026-2036
Semiconductor Metrology and Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Metrology and Inspection Equipment Market Analytics
Subscription-based software-defined metrology is broadening what fabs purchase alongside hardware. KLA Corporation leverages its fleet of installed e-beam and optical systems to sell predictive analytics modules that extend equipment utilization. Applied Materials, Inc. anchors its process control suite through integrated metrology chambers embedded in deposition and etch platforms. ASML competes by bundling lithography-aligned inspection feeds directly into its EUV scanner control loops, reducing overlay correction cycles.
Semiconductor metrology and inspection equipment encompasses systems that measure critical dimensions, film thickness, and defect densities on silicon wafers with sub-nanometer precision, employing electron beams, broadband plasma illumination, or X-ray diffraction to ensure yield in multi-billion-transistor devices. Optical inspection dominates volume shipments for inline defect monitoring, while atomic force microscopy captures the fastest expansion as gate-all-around transistors require three-dimensional profile validation. Machine learning technology sits at the margin pool's center, where algorithm-licensing fees attach recurring revenue to each hardware placement across foundry and memory fabs.
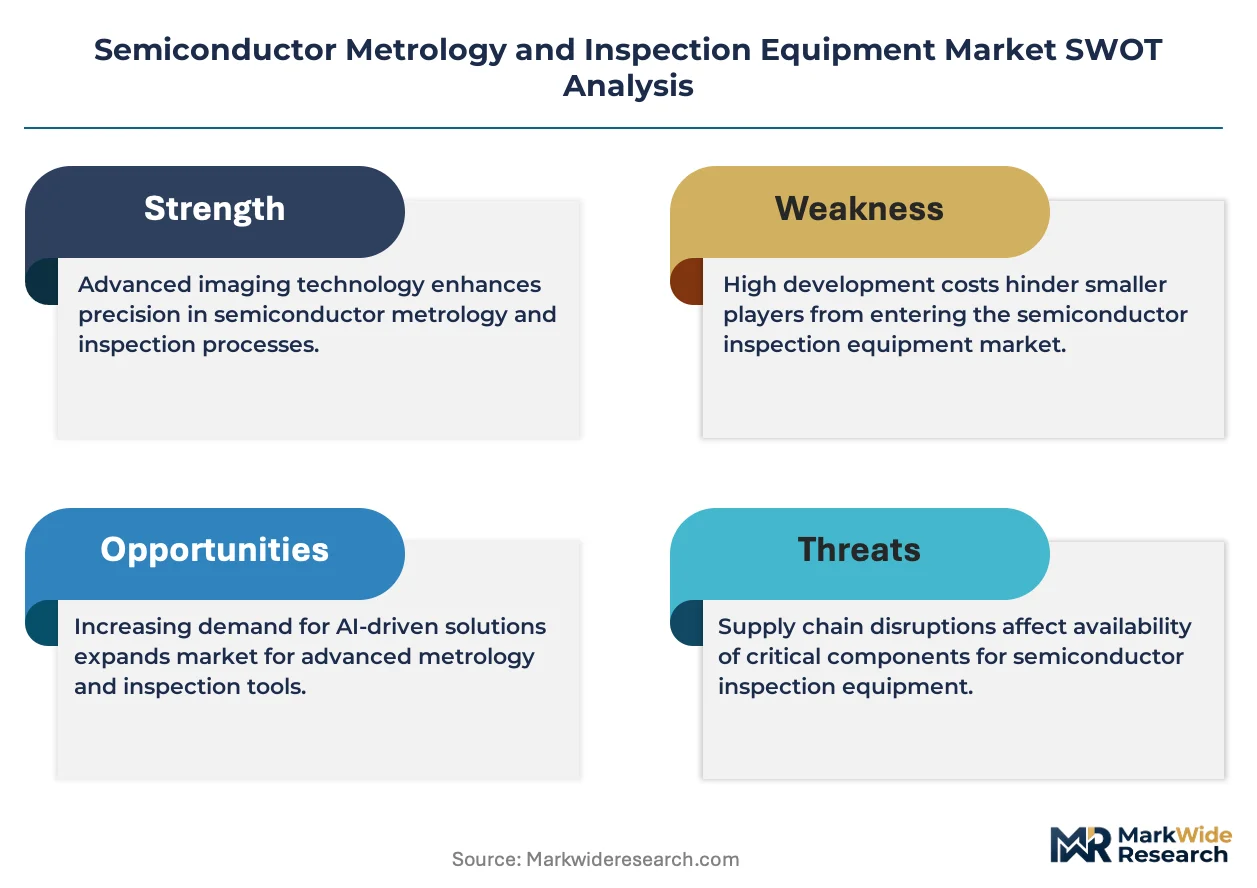
FDA oversight of semiconductor-based medical device components, EPA restrictions on perfluorinated compound emissions from fab processes, and Japan's METI export controls on advanced manufacturing equipment collectively tighten compliance requirements for inspection system vendors. ISO 9001 and SEMI standards further dictate calibration protocols and data interoperability, raising barriers for equipment without certified traceability. Stakeholders must weigh capital intensity against the accelerating replacement cycle driven by each successive node shrink.
Market Dynamics
EUV lithography adoption at the 3nm node and below is compressing defect tolerance windows to atomic-scale precision, forcing fabs to triple metrology sampling density per wafer pass while shrinking cycle times.
Growth Catalysts
- CHIPS Act capital deployment:US fabs receiving federal subsidies must meet domestic content thresholds, accelerating procurement of locally sourced inspection systems for Arizona and Texas greenfield sites.
- HBM memory architectures:South Korean manufacturers expanding 3D NAND and high-bandwidth memory capacity multiply vertical metrology steps per wafer, driving equipment utilization rates upward.
- Gate-all-around transistor transition:Foundries migrating from FinFET to nanosheet geometries require atomic force microscopy validation of three-dimensional profiles, expanding the addressable tool base.
Market Restraints
- Extreme ultraviolet source scarcity:Laser-produced plasma light source availability constrains scanner throughput, creating downstream bottlenecks that idle expensive metrology assets.
- Helium supply concentration:Cryogenic cooling systems in e-beam columns depend on Algerian and Qatari helium exports, exposing tool uptime to geopolitical supply interruptions.
- Sub-0.5nm resolution ceiling:Optical diffraction limits prevent visible-light systems from resolving next-generation transistor features, forcing premature obsolescence of installed base.
Strategic Opportunities
- India's semiconductor mission:Gujarat and Tamil Nadu fab incentives create first-mover advantage for inspection vendors establishing local calibration and service infrastructure.
- Photonics packaging inspection:Silicon photonics co-packaged optics for AI clusters require new metrology protocols for waveguide alignment validation.
- EU AI Act compliance:Automated defect classification systems deployed in European fabs must demonstrate algorithmic traceability, creating premium service tiers for certified AI-enabled tools.
Industry Challenges
- E-beam physicist scarcity:The specialized workforce capable of tuning charged-particle column optics cannot expand at the pace of tool deployment, extending commissioning timelines.
- SEMI S2/S8 certification backlog:Third-party safety and ergonomics validation for new equipment platforms faces 14-month queue times at accredited test facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Metrology and Inspection Equipment Market |
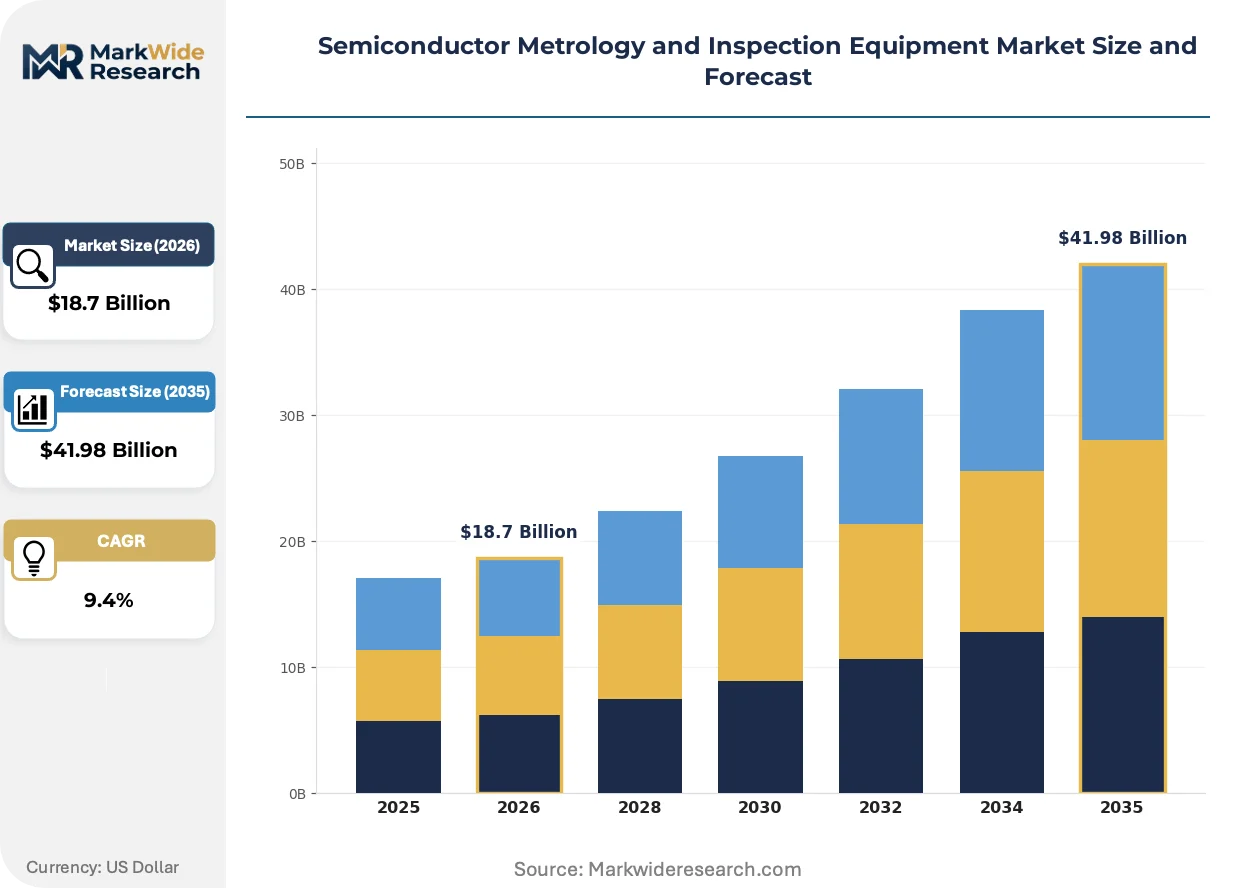
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Inspection, X-Ray Inspection, Atomic Force Microscopy, Spectroscopy Technology: Surface Scanning, 3D Metrology, Adaptive Optics, Machine Learning End User: Foundries, Fabless Companies, Integrated Device Manufacturers, Research Institutions Application: Wafer Manufacturing, Assembly Verification, Quality Control, Defect Detection |
| Companies Covered | KLA Corporation, Applied Materials, Inc., ASML, Hitachi High-Tech Corporation, Onto Innovation, Camtek, Lasertec Corporation, Nova Ltd., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Metrology and Inspection Equipment Market Evolving Landscape
Computational metrology and machine learning inference are collapsing the traditional separation between measurement acquisition and real-time process correction, embedding intelligence directly at the point of inspection.
Multi-beam electron microscopy is overtaking single-column architectures for inline defect review. Memory fabs in South Korea now specify 25-beam systems for HBM die-to-die bonding inspection, compressing throughput bottlenecks that previously forced offline sampling. The technology is overtaking optical methods for critical dimension uniformity mapping at the 2nm node.
Japan's METI export controls on advanced manufacturing equipment are compelling domestic toolmakers to requalify supply chains for EUV-adjacent inspection systems. The policy restricts component sourcing from designated countries, forcing redesign of ion gauge and detector assemblies. Japanese vendors are responding by deepening partnerships with Taiwanese sensor foundries to maintain access to South Korean and US fab customers.
Subscription-based predictive maintenance contracts are displacing traditional break-fix service agreements for installed metrology fleets. Foundry operators in Taiwan now demand uptime guarantees bundled with algorithmic drift compensation, transferring operational risk to equipment vendors. This shift concentrates most visibly among EUV lithography users where unplanned downtime costs exceed tool depreciation.
Semiconductor Metrology and Inspection Equipment Market Segmentation
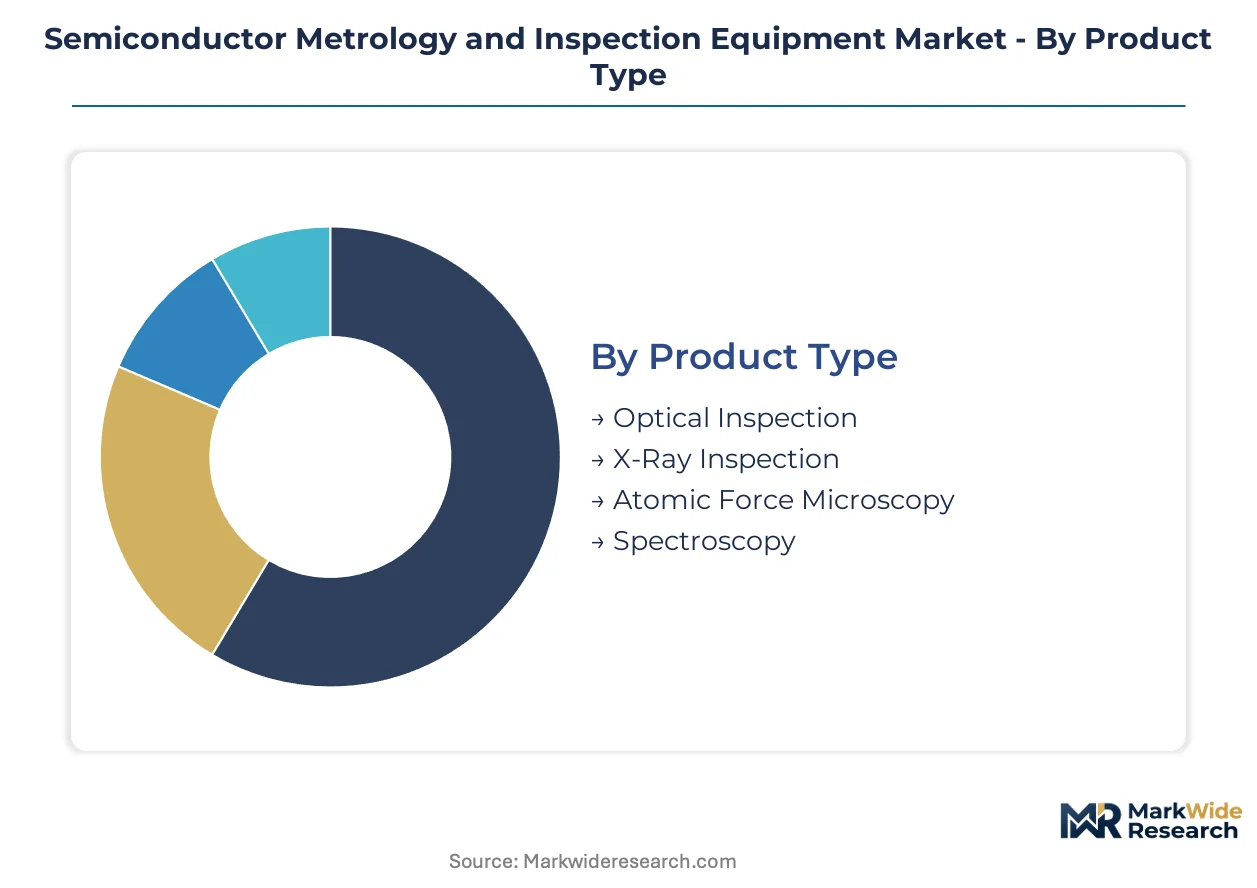
Equipment segmentation in this market tracks the divergence between high-volume optical methods for inline monitoring and precision techniques for advanced node validation. Technology choices cascade through procurement budgets, service contract structures, and workforce specialization requirements.
Product Type:
Optical systems anchor capital deployment in high-throughput fabs, while emerging architectures address atomic-scale measurement gaps at sub-3nm nodes.
- Optical Inspection:Broadband plasma and deep-ultraviolet systems capture sub-100nm defects across full wafer surfaces at production speeds. Taiwan's advanced node foundries deploy these for EUV lithography pattern verification, where scanner throughput demands parallel inspection lanes.
- Atomic Force Microscopy:Cantilever-based profilometry resolves three-dimensional gate profiles with sub-angstrom vertical resolution. South Korean HBM manufacturers specify multi-tip configurations for die-to-die bonding interface characterization, multiplying metrology steps per stacked wafer.
- X-Ray Inspection:X-ray diffraction and fluorescence systems measure buried film thickness and crystallographic stress in 3D NAND architectures. The technique penetrates opaque layers that block optical methods.
- Spectroscopy:Ellipsometry and reflectometry quantify dielectric film properties through polarization analysis. The method integrates into deposition cluster tools for real-time thickness endpoint detection.
Optical Inspection leads on scale; Atomic Force Microscopy leads on momentum.
Technology:
Measurement architectures differentiate through computational intensity and integration depth with process control loops.
- Machine Learning:Neural network classifiers reduce false-positive defect flags by training on historical wafer map databases. The capability shifts vendor revenue toward algorithm-licensing subscriptions attached to hardware placements.
- 3D Metrology:Multi-angle scatterometry and interferometric techniques reconstruct nanosheet transistor profiles from optical signatures. Foundries migrating from FinFET geometries require these for gate-all-around process validation.
- Surface Scanning:Stage-motion and sensor-synchronization protocols determine throughput ceilings for electron-beam and optical platforms. Japanese vendors optimize these subsystems for compatibility with existing fab automation standards.
- Adaptive Optics:Real-time wavefront correction compensates for thermal drift in high-NA EUV projection systems. The technology extends optical resolution toward physical diffraction limits.
Surface Scanning dominates installed base economics; Machine Learning commands premium pricing expansion.
End User:
Customer archetypes separate by captive process control requirements versus outsourced metrology service dependencies.
- Foundries:Taiwan and South Korean contract manufacturers operate the densest metrology fleets, sampling every wafer pass to guarantee yield commitments for fabless clients. Capital intensity concentrates at EUV-capable sites.
- Integrated Device Manufacturers:Texas Instruments and analogous IDMs balance memory and logic production, requiring flexible inspection platforms across heterogeneous product mixes. Their procurement emphasizes tool reuse across node generations.
- Fabless Companies:Design houses without fabrication assets purchase metrology services from foundry partners or third-party labs. Their influence shapes equipment specifications through design-for-manufacturability feedback loops.
- Research Institutions:IMEC and university consortia pilot pre-competitive measurement techniques for next-node insertion. Their procurement volumes are small but determine standardization trajectories.
Foundries lead on capital deployed; Integrated Device Manufacturers lead on tool longevity requirements.
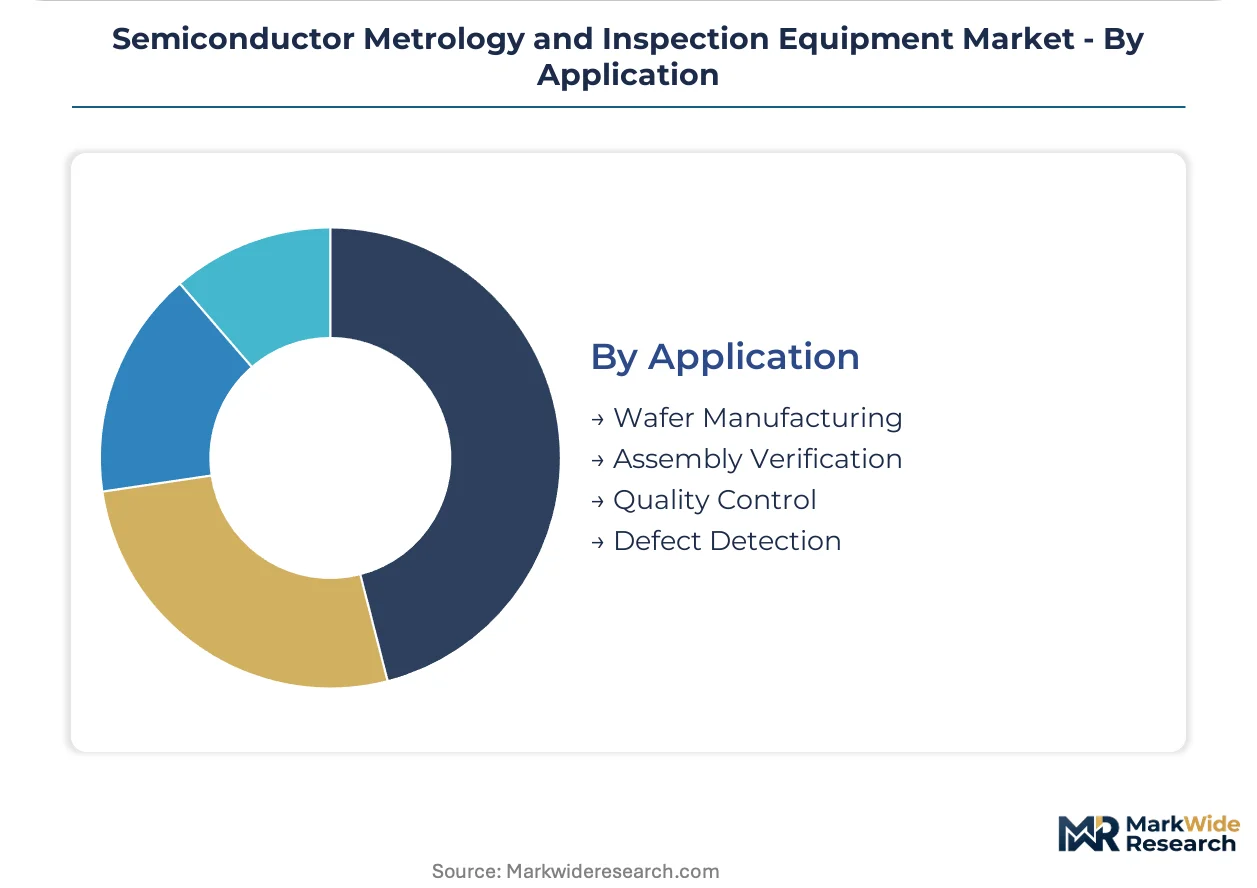
Application:
Process stage determines measurement precision requirements and acceptable cycle time tradeoffs.
- Defect Detection:Patterned and unpatterned wafer inspection identifies killer defects before subsequent process steps amplify yield loss. Optical platforms dominate this stage for speed; e-beam systems address critical layer sampling.
- Wafer Manufacturing:Critical dimension uniformity and overlay metrology feed forward into lithography scanner corrections. The application consumes the highest equipment utilization hours per fab.
- Quality Control:Final electrical and physical verification before die shipment relies on sampling strategies that balance test coverage against throughput. Automotive-grade chips impose stricter sampling densities.
- Assembly Verification:Post-dicing inspection validates bump alignment and substrate integrity for advanced packaging. The segment expands with chiplet architectures and heterogeneous integration.
Wafer Manufacturing leads on equipment density; Assembly Verification leads on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting metrology equipment procurement toward jurisdictions with streamlined export controls and subsidized capital access. The CHIPS Act in the United States and Japan's METI semiconductor incentives have created compliance-cost gaps that favor domestic sourcing over legacy Asian supply chains.
United States
Arizona and Texas greenfield fabs are expanding metrology fleets to satisfy CHIPS Act domestic content thresholds. EPA restrictions on perfluorinated compound emissions from fab processes tighten compliance requirements for inspection system vendors. Intel's Ocotillo campus in Arizona is commissioning EUV-aligned metrology suites for advanced node production.
Taiwan
Advanced node foundries are tripling metrology sampling density per wafer pass as EUV lithography adoption compresses defect tolerance windows. The island's national technology programs channel R&D funding into process control automation. Hsinchu Science Park hosts the densest concentration of inline inspection systems worldwide.
South Korea
HBM memory manufacturers are multiplying vertical metrology steps per stacked wafer, driving equipment utilization rates to capacity limits. MFDS oversight of semiconductor-based medical device components adds certification layers for inspection data traceability. Samsung's Pyeongtaek complex is expanding atomic force microscopy capacity for 3D NAND bonding validation.
Japan
METI export controls on advanced manufacturing equipment are compelling domestic toolmakers to requalify supply chains for EUV-adjacent inspection systems. JIS standards dictate calibration protocols that raise barriers for uncertified equipment imports. Yokohama's precision engineering cluster is deepening partnerships with Taiwanese sensor foundries to maintain South Korean and US fab access.
China
MIIT semiconductor self-sufficiency targets are accelerating procurement of domestically produced metrology platforms despite technology gaps at sub-7nm nodes. GB standards for measurement traceability constrain foreign equipment adoption in state-backed fabs. Shanghai's Zhangjiang Hi-Tech Park is piloting multi-beam electron microscopy for critical dimension uniformity mapping.
Semiconductor Metrology and Inspection Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with lithography-aligned systems consolidating around integrated platform vendors while standalone inspection tools fragment across application-specific niches. The market structure tiers into three archetypes: full-stack lithography-metrology integrators, standalone optical and e-beam specialists, and software-defined analytics providers. M&A activity concentrates on predictive maintenance algorithm acquisitions, while capacity expansion focuses on multi-beam electron microscopy manufacturing scale-up.
Among US-based platform vendors, KLA Corporation and Applied Materials, Inc. exemplify divergent strategic positioning within process control ecosystems. KLA anchors the standalone inspection tier through installed base leverage for subscription analytics, while Applied Materials represents the integrated chamber approach embedding metrology within deposition and etch platforms. ASML occupies a distinctive position bundling lithography-aligned inspection feeds directly into EUV scanner control loops.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials, Inc. |
| ASML |
| Hitachi High-Tech Corporation |
| Onto Innovation |
| Camtek |
| Lasertec Corporation |
| Nova Ltd. |
| Thermo Fisher Scientific Inc. |
| Others |
Value Network & Pricing Analysis
Captive supply of ion gauge and detector assemblies by Japanese vendors anchors both supply security and pricing power in EUV-adjacent inspection systems. METI export controls forced this backward integration, compressing margins for equipment without certified component traceability while elevating premiums for compliant platforms.
Pricing Analysis
Distributor margins for standalone optical inspection systems compress as direct OEM procurement expands. Three-tier pricing structure across premium, standard, and economy levels stratifies by SEMI S2/S8 certification status and algorithmic capability bundling. Pricing pressure stems from South Korean memory fabs demanding uptime guarantees that transfer operational risk to vendors. Fabless design houses exhibit highest price sensitivity; Taiwan foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
SEMI S2/S8 certification gating creates 14-month validation queues that constrain new entrant supply capacity. Component sourcing concentrates in Taiwan for sensor foundry output, Japan for precision motion stages, and Germany for laser interferometry subsystems. Helium supply for cryogenic cooling rests on Algerian and Qatari export flows. Single-source vulnerability sits with laser-produced plasma light sources. Distribution runs through direct fab integration with embedded service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EUV lithography adoption forces fabs toward premium metrology specifications that guarantee atomic-scale precision.
For Market Incumbents: Anchor installed base leverage through predictive maintenance subscriptions that bundle algorithmic drift compensation. Defend against emerging software-defined analytics entrants by deepening EUV scanner integration partnerships. Prioritize SEMI S2/S8 certification investment to maintain access to CHIPS Act-funded fabs. For New Entrants and Emerging Players: Begin with India's Gujarat and Tamil Nadu greenfield sites where calibration infrastructure gaps create first-mover windows. Target photonics packaging inspection for AI cluster waveguide alignment validation. Pursue joint development agreements with IMEC consortium members to establish pre-competitive measurement credibility. For Investors and Strategic Acquirers: Roll-up economics work for specialized e-beam physicist teams because workforce scarcity extends commissioning timelines and inflates acquisition multiples. Five-to-ten year viability favors vendors with multi-beam electron microscopy manufacturing scale. Watch helium supply disruption as inflection indicator for cryogenic cooling system demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Manufacturing Scale-Up | Memory fabs in South Korea now specify 25-beam systems for HBM inspection throughput. |
| Predictive Maintenance Subscription Launch | Taiwan foundries demand uptime guarantees that transfer operational risk to equipment vendors. |
| SEMI S2/S8 Certification Investment | Third-party validation queues stretch 14 months, creating barrier for uncertified competitors. |
| Helium-Free Cryogenic Cooling Development | Algerian and Qatari supply concentration exposes tool uptime to geopolitical interruption. |
| Photonics Packaging Metrology Partnership | Silicon photonics co-packaged optics for AI clusters require new waveguide alignment protocols. |
Research Methodology
Bottom-up foundry and memory fab capital expenditure modeling reconciled against top-down equipment shipment tracking forms the analytical core. Primary interviews with process control engineers, fab operations directors, metrology procurement managers, and e-beam physicist specialists combined with secondary validation from SEMI equipment market data, SEC 10-K filings, and customs import records. Triangulation between bottom-up and top-down approaches ensures consistency across segment estimates.
Input-output matrices map inspection tool deployments against wafer starts, node migration timelines, and metrology sampling density requirements. Segmentation dimensions include product type, technology architecture, end-user archetype, and application stage across the projection horizon. CAGRs derive from equipment replacement cycle compression and EUV lithography adoption curves. Forecast inputs incorporate HBM stacking architecture evolution and gate-all-around transistor transition pacing.
Caveats apply where EUV source availability constraints or helium supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding CHIPS Act capital deployment timelines and METI subsidy disbursement rates. A model refresh is warranted upon material change in advanced node foundry yield targets or export control scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Megohmmeters Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Digital Video Extensometers Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
EMC Testing Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Force Gauge Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Simulation and Test Data Management Market