
 Semiconductor Bond Testing Market | 2026-2036
Semiconductor Bond Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Bond Testing Market Insights
Software-defined test parameter suites are pivoting from perpetual licenses to subscription-based access models, altering how equipment vendors monetize installed bases. Kulicke & Soffa leverages its wire bonding heritage to extend into adjacent test workflows. ASM Pacific Technology anchors Asia-Pacific supply chains through captive service networks. BE Semiconductor Industries specializes in high-accuracy platforms for heterogeneous integration packages.
Semiconductor bond testing evaluates mechanical integrity of wire-to-die and die-to-substrate interconnections through force-displacement measurement, typically resolving shear strengths below 10 grams-force for fine-pitch copper pillars. The technique prevents field failures in automotive-grade devices by screening weak bonds before encapsulation. Pull testing commands the largest installed base among technology segments, though shear testing is capturing margin pools in advanced flip-chip applications. Ball bonding retains volume dominance across test method categories, while ribbon bonding is gaining traction in power module packaging where aluminum strap geometries demand specialized fixturing.
ISO 9001 quality management frameworks and IEC 60749 environmental test standards govern equipment calibration protocols and reproducibility requirements across manufacturing sites. The FDA's quality system regulation for medical device semiconductors and NHTSA reliability expectations for automotive electronics are tightening bond-level traceability mandates. Stakeholders must weigh sovereign subsidy conditions against existing supplier relationships when siting new test capacity.
Market Dynamics
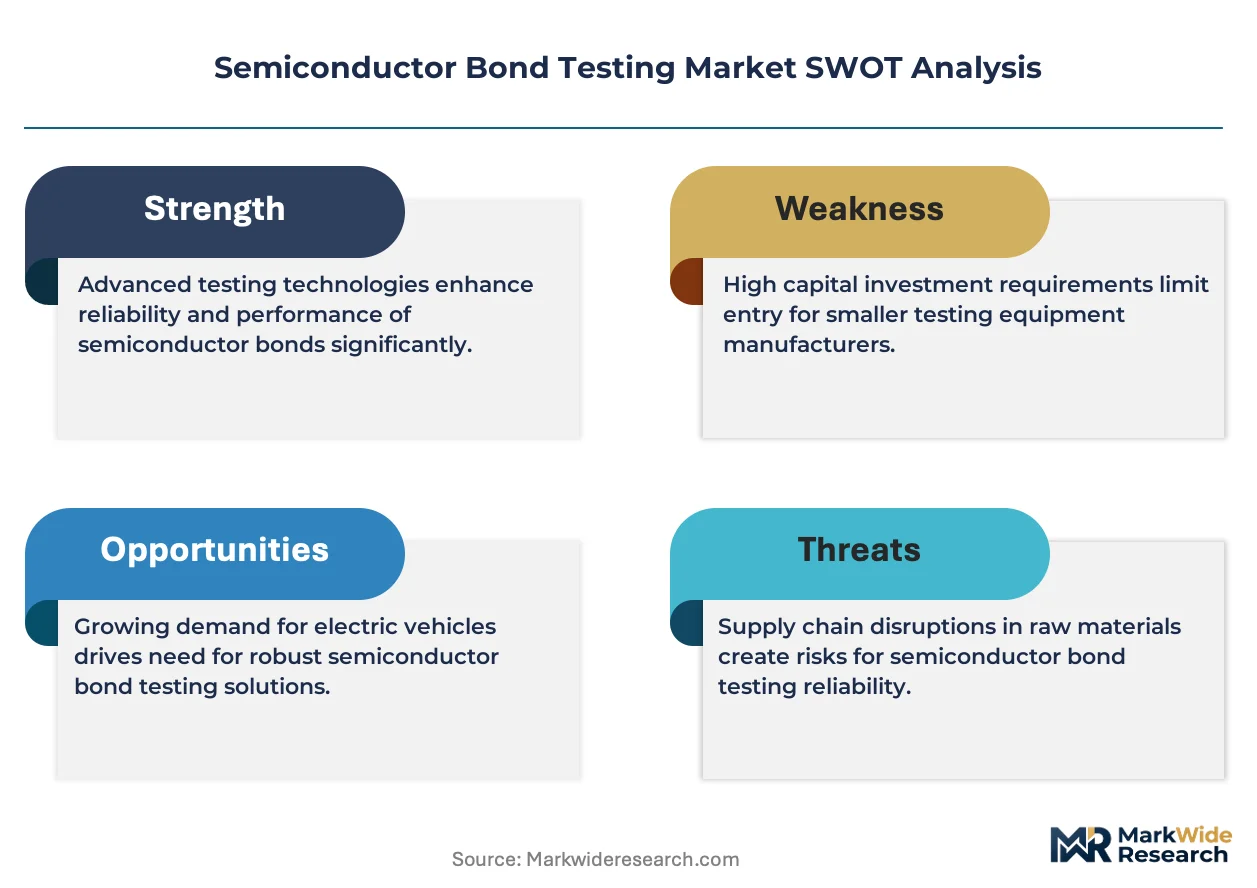
Advanced packaging architectures—particularly heterogeneous integration for AI accelerators and automotive radar modules—are compressing bond pitch tolerances below 20 micrometers, forcing equipment refresh cycles and recalibrating vendor competitive positioning around sub-gram force resolution capabilities.
Growth Catalysts
- EU Chips Act capital allocation:Sovereign subsidy programs in Germany and France are redirecting private investment toward localized packaging and test facilities, expanding captive demand for high-accuracy bond verification equipment.
- Automotive electrification:Tier-1 suppliers in South Korea and Taiwan are qualifying copper-pillar flip-chip interconnects for 800V inverter modules, mandating 100% bond-level screening before encapsulation.
- Fine-pitch copper pillar migration:Die-to-wafer hybrid bonding for 3D NAND and high-bandwidth memory stacks is displacing traditional wire bonds in leading-edge fabs, creating incremental test points per device.
Market Restraints
- Equipment utilization thresholds:Sub-10 gram-force test heads require tungsten carbide probe tips and piezoelectric load cells, concentrating supply among Japanese and German precision component vendors.
- Calibration protocol fragmentation:Divergent traceability requirements between NHTSA automotive reliability mandates and FDA medical device quality systems extend equipment qualification timelines by 4-6 months for multi-sector vendors.
- Gold wire substitution:Copper and silver-alloy bonding wire formulations are narrowing the failure-mode differentiation that bond testing equipment was originally designed to detect, compressing value capture per test cycle.
Strategic Opportunities
- India semiconductor manufacturing:PLI scheme disbursements for outsourced semiconductor assembly and test facilities in Gujarat and Karnataka are creating first-mover advantages for equipment vendors establishing local service infrastructure.
- Ribbon bonding for power modules:Aluminum strap geometries in silicon carbide traction inverters demand specialized shear test fixturing, opening adjacent revenue pools beyond traditional ball-bond applications.
- Subscription-based software access:Equipment vendors are migrating from perpetual test-parameter licenses to recurring revenue models, deepening customer switching costs and smoothing revenue volatility.
Industry Challenges
- Metrology technician scarcity:Force-displacement calibration expertise for sub-gram resolution systems concentrates among aging specialists in Japan and Germany, constraining field service expansion.
- Multi-site standardization:ISO 9001 and IEC 60749 compliance across Taiwan, South Korea, and German manufacturing footprints requires harmonized equipment configurations that conflict with site-specific substrate formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Bond Testing Market |
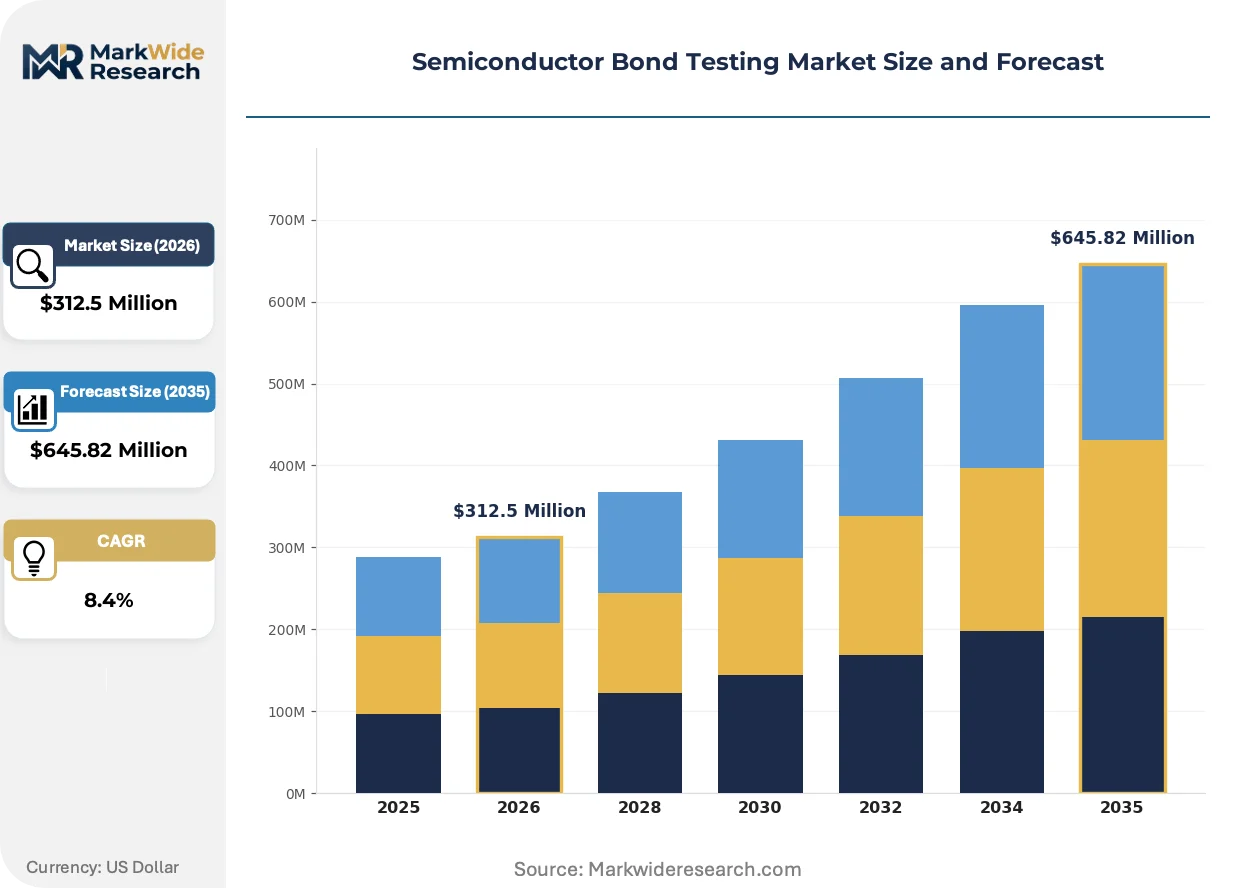
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Ball Bonding, Wedge Bonding, Ribbon Bonding, Ultrasonic Bonding End User: Consumer Electronics, Telecommunications, Automotive Components, Industrial Applications Technology: Thermal Cycle Testing, Pull Testing, Shear Testing, Environmental Testing Device Type: Integrated Circuits, MEMS, Discrete Components, Sensors |
| Companies Covered | Kulicke & Soffa, ASM Pacific Technology, BE Semiconductor Industries, Palomar Technologies, SUSS MicroTec, EV Group, Shinkawa Ltd, Panasonic, WestBond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Bond Testing Market Trends and Innovations
Test equipment architectures are pivoting from discrete hardware platforms to software-defined measurement systems, enabling remote parameter updates and predictive maintenance while compressing capital deployment timelines for new packaging formats.
Laser-assisted bond inspection is overtaking contact-based mechanical testing for fine-pitch copper pillar arrays in high-bandwidth memory production. Samsung and SK Hynix fabs in South Korea are deploying hybrid optical-force systems at 40% of new bond test stations. The technology is compressing test cycle times by eliminating mechanical probe contact for non-critical interconnects.
REACH substance restrictions on hexavalent chromium plating are forcing probe needle material transitions to titanium nitride coatings, extending calibration intervals but increasing unit consumables cost by 15-20%. German equipment vendors are qualifying alternative surface treatments ahead of 2026 enforcement deadlines. Medical device semiconductor subcontractors in Switzerland and Ireland face the steepest compliance cost escalation due to smaller procurement volumes.
Automotive OEMs are consolidating bond test specification authority from tier-2 packaging houses to in-house reliability engineering teams, compressing supplier qualification cycles and unbundling equipment purchase decisions from assembly line contracts. This concentration is most visible among German and US electric vehicle programs, where NHTSA traceability mandates require direct audit access to raw force-displacement curves rather than pass-fail summaries.
Semiconductor Bond Testing Market Segmentation
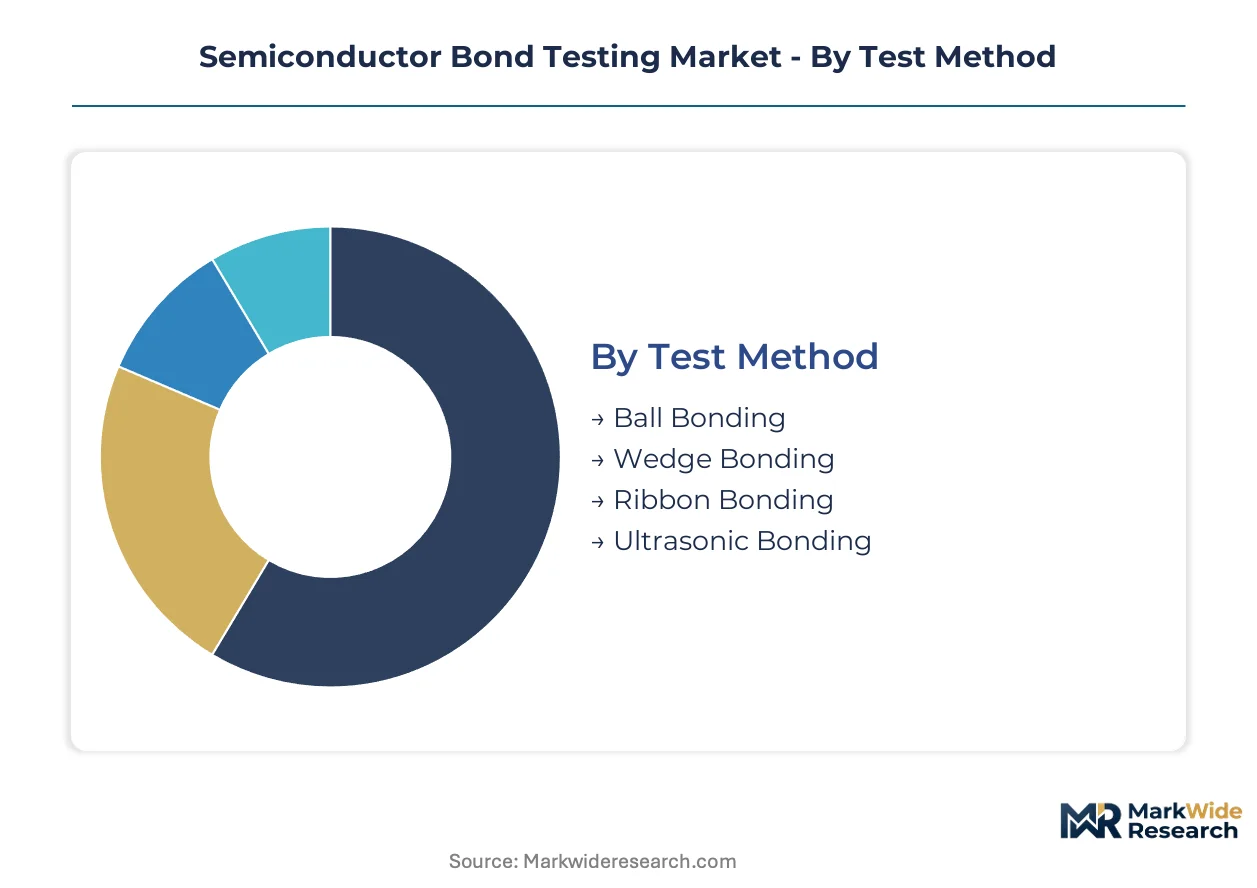
Semiconductor bond testing equipment serves distinct process workflows across packaging formats, with test method selection determining fixturing complexity and throughput economics. End-user reliability mandates from automotive and telecommunications sectors are fragmenting equipment specifications beyond traditional one-size-fits-all platforms.
Test Method:
Ball bonding dominates standalone test station deployments, while wedge and ribbon configurations increasingly embed into continuous assembly lines.
- Ball Bonding:Gold and copper wire interconnects in wire-bonded packages require pull-and-shear verification at bond heel and wedge locations. Consumer electronics packaging houses in Taiwan and South Korea maintain the largest installed base of dedicated ball bond testers for memory and logic devices.
- Wedge Bonding:Aluminum heavy-wire geometries in power modules demand specialized shear fixturing with force resolution below 5 gram-force. Automotive inverter manufacturers in Germany are qualifying wedge bond test protocols for silicon carbide traction modules under NHTSA reliability mandates.
- Ribbon Bonding:Aluminum strap interconnects in high-current power electronics require custom anvil geometries to accommodate rectangular cross-sections. Equipment vendors are developing modular test heads that swap between round-wire and ribbon configurations without full station recalibration.
- Ultrasonic Bonding:Thermosonic and ultrasonic wedge processes for copper ribbon in solar module interconnects are expanding test point requirements.
Volume placements concentrate in Ball Bonding; the faster expansion belongs to Ribbon Bonding.
End User:
Automotive qualification timelines stretch equipment payback periods compared to consumer electronics, shifting vendor prioritization toward high-mix, low-volume contract packaging houses.
- Automotive Components:800V inverter modules and lidar sensor packages require 100% bond-level screening with full force-displacement curve traceability. Tier-1 suppliers in South Korea are consolidating test specification authority in-house, bypassing traditional tier-2 packaging house relationships.
- Telecommunications:5G baseband and millimeter-wave RF modules drive fine-pitch copper pillar verification for flip-chip interconnects. Base station OEMs in Germany are mandating IEC 60749 environmental preconditioning before mechanical bond testing.
- Consumer Electronics:Smartphone AP and memory package volumes sustain high-throughput test cell economics.
- Industrial Applications:Motor drive and power supply modules in factory automation equipment require extended temperature cycling before bond verification.
Revenue concentration sits with Automotive Components; share gains are steepest in Telecommunications.
Technology:
Pull testing retains the broadest installed base, though shear and environmental protocols are capturing premium pricing in heterogeneous integration workflows.
- Pull Testing:Wire pull to failure remains the default screening method for gold and copper ball bonds, with hook geometries standardized per MIL-STD-883. Memory packaging facilities in Taiwan run pull test cells at cycle times below 2 seconds per bond site.
- Shear Testing:Copper pillar and solder bump interconnects in flip-chip packages require horizontal shear to evaluate intermetallic fracture modes. AI accelerator packaging lines in South Korea are converting pull-dominant stations to hybrid pull-shear configurations.
- Thermal Cycle Testing:Preconditioning protocols per JEDEC standards stress bonds before mechanical verification.
- Environmental Testing:Temperature-humidity bias and high-temperature storage conditioning extend qualification timelines for automotive-grade devices.
Equipment shipments skew toward Pull Testing; the steepest expansion trajectory belongs to Shear Testing.
Device Type:
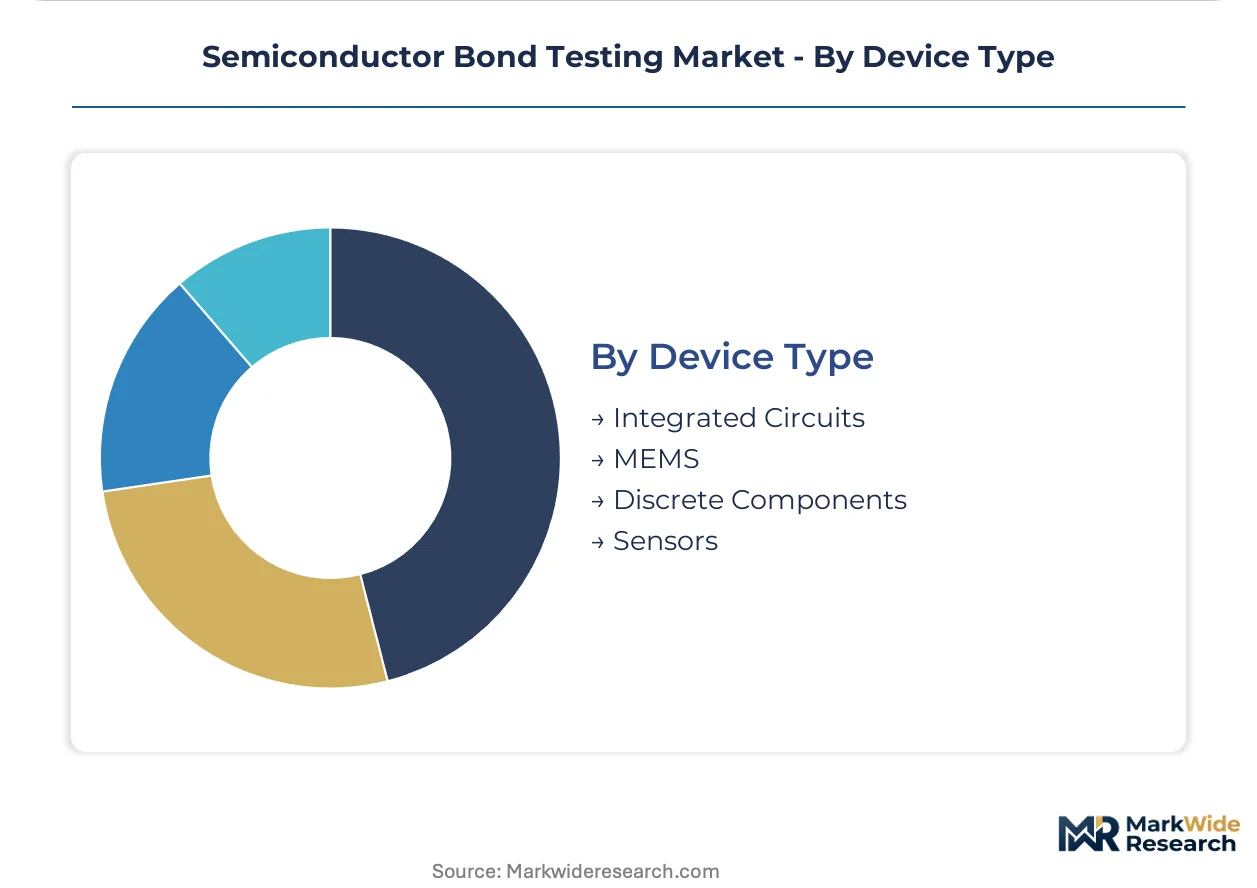
Integrated circuit packaging generates test cell density, while MEMS and sensor formats demand specialized handling and non-contact pre-screening.
- Integrated Circuits:Logic and memory die in BGA, QFN, and CSP packages constitute the volume base for bond testing equipment, with multi-site test heads addressing 100+ bond sites per device. Leading-edge foundries in Taiwan are deploying in-line test cells between wire bonders and mold compound dispense stations.
- MEMS:Microelectromechanical systems for automotive pressure and inertial sensors require low-stress handling during bond verification to prevent proof mass damage. Packaging subcontractors in Germany are qualifying automated optical inspection as a pre-filter to reduce mechanical probe contact.
- Sensors:Image sensor and environmental sensor packages with exposed die surfaces need contamination-controlled test environments.
- Discrete Components:Power diodes and transistors in TO and DPAK packages sustain simpler pull-test-only configurations.
Capital deployment concentrates in Integrated Circuits; MEMS is climbing the fastest as a share of new equipment orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption concentrates in Taiwan and South Korea while Germany builds indigenous test capacity. Production of sub-gram force resolution systems remains concentrated among Japanese and German component specialists.
Taiwan
Leading-edge foundries and OSATs drive demand for high-throughput ball bond test cells. The National Development Council subsidizes advanced packaging infrastructure in Hsinchu Science Park. Taichung packaging clusters deploy in-line test stations between wire bonders and mold compound dispense operations.
South Korea
SK Hynix and Samsung fabs qualify hybrid optical-force systems for high-bandwidth memory production. MFDS traceability requirements extend to automotive-grade device subcontractors. Pyeongtaek semiconductor complexes convert pull-dominant stations to hybrid pull-shear configurations for AI accelerators.
Germany
Automotive OEMs consolidate bond test specification authority in-house under NHTSA reliability mandates. The EU Chips Act directs capital toward Dresden and Bavaria packaging facilities. Ingolstadt and Stuttgart electric vehicle programs require direct audit access to raw force-displacement curves.
United States
Silicon Valley fabless designers source bond verification from Taiwan-based OSATs while domestic packaging remains limited. FDA quality system regulations govern medical device semiconductor subcontractors. Arizona fabs under construction will require localized test capacity by 2026.
Japan
Piezoelectric load cell and tungsten carbide probe tip supply concentrates among precision component vendors. METI funding supports heterogeneous integration research for 3D NAND applications. Kyoto and Nagoya industrial clusters house aging metrology technician expertise for sub-gram calibration.
Semiconductor Bond Testing Market Competitive Landscape
Top-tier vendors anchor the precision component supply base, while mid-tier equipment assemblers compete on regional service density. The market structures around three distinct tiers: Japanese and German precision specialists controlling probe and sensor supply, Asia-Pacific equipment integrators dominating volume shipments, and European niche players capturing automotive qualification workflows. Strategic moves concentrate on captive service network expansion and software-defined test parameter monetization.
Within the precision-component tier, Kulicke & Soffa and ASM Pacific Technology exemplify vendors extending wire bonding heritage into adjacent test workflows. BE Semiconductor Industries occupies a position among European specialists targeting high-accuracy platforms for heterogeneous integration packages. These three names represent divergent geographic and technological anchoring strategies visible across the vendor landscape.
| Leading Market Players |
|---|
| Kulicke & Soffa |
| ASM Pacific Technology |
| BE Semiconductor Industries |
| Palomar Technologies |
| SUSS MicroTec |
| EV Group |
| Shinkawa Ltd |
| Panasonic |
| WestBond |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM consolidation of bond test specification authority in Germany and South Korea forces equipment vendors to absorb extended qualification timelines and NHTSA traceability mandates, compressing margins while concentrating procurement leverage among fewer buyers with non-negotiable compliance requirements.
Pricing Analysis
Margin tightening in standard-tier equipment reflects copper and silver-alloy wire substitution narrowing failure-mode differentiation that bond testers were designed to detect. Three-tier pricing structure across premium, standard, and economy levels stratifies by force resolution capability and calibration protocol bundling. Premium systems with sub-gram resolution and full IEC 60749 traceability command sustained pricing power. Consumer electronics packaging houses in Taiwan exhibit highest price sensitivity, while automotive tier-1 suppliers in Germany prioritize compliance over unit cost.
Supply Chain Analysis
Probe tip refurbishment and tungsten carbide component remanufacturing flows concentrate in Kyoto and Nagoya industrial clusters, extending effective supply availability for precision metrology components. Equipment production draws from Japanese piezoelectric load cell specialists and German precision mechanics vendors. Raw material dependencies span tungsten carbide for probe tips, titanium nitride coatings for REACH compliance, and high-purity ceramics for test fixtures. Single-source vulnerability concentrates in sub-gram force resolution component supply. Distribution runs through captive service networks anchored by ASM Pacific Technology in Asia-Pacific and BE Semiconductor Industries in European automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor bond testing market sits in a technology-transition phase as laser-assisted optical inspection displaces mechanical probe contact for fine-pitch copper pillar arrays in high-bandwidth memory production.
For Market Incumbents: Deploy software-defined test parameter suites to deepen customer switching costs and capture recurring revenue streams. Extend captive service network density in Gujarat and Karnataka ahead of India PLI scheme disbursements. Defend against hybrid optical-force system displacement by integrating predictive maintenance capabilities that laser-based alternatives cannot match. For New Entrants and Emerging Players: Launch via specialized shear test fixturing for aluminum strap geometries in silicon carbide traction inverters, bypassing saturated ball-bond test station competition. Target ribbon bonding applications in power module packaging where incumbent tooling requires full recalibration for rectangular cross-sections. Pursue automotive qualification workflow partnerships in Ingolstadt and Stuttgart where NHTSA mandates create specification authority consolidation. For Investors and Strategic Acquirers: The window for entry favors precision component specialists with tungsten carbide probe tip or piezoelectric load cell capabilities. Long-term viability rests on equipment vendors controlling sub-gram force resolution calibration expertise as metrology technician scarcity intensifies. Monitor EU Chips Act capital disbursement velocity in Dresden and Bavaria as inflection indicator for localized test capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Software Migration | Recurring revenue models deepen switching costs for Taiwan OSAT customers. |
| Captive Service Network Expansion | Local calibration expertise addresses metrology technician scarcity in Germany. |
| Hybrid Optical-Force System Development | Samsung and SK Hynix fabs in South Korea already deploy at 40% of new stations. |
| India Manufacturing Footprint Establishment | PLI scheme disbursements in Gujarat create first-mover service infrastructure advantages. |
| REACH-Compliant Coating Qualification | Titanium nitride surface treatments ahead of 2026 enforcement deadlines protect European market access. |
Research Methodology
Multi-period observation of equipment refresh cycles, sovereign subsidy disbursements, and probe tip material transitions anchored the trend analysis, supplemented by interviews with test equipment procurement managers at Taiwan OSATs, metrology calibration specialists in Kyoto, automotive reliability engineers in Stuttgart, and packaging R&D directors in Hsinchu. Secondary validation drew from NHTSA reliability guidance documents, IEC 60749 environmental test standards, EU Chips Act capital allocation disclosures, and SEC filings of publicly traded equipment vendors. Bottom-up unit economics triangulated against top-down semiconductor capital expenditure forecasts.
Input-output matrices mapped test method adoption rates against packaging format migrations, device type complexity curves, and end-user qualification timelines across the projection horizon. Segmentation dimensions modeled include test method category, end-user industry vertical, force resolution tier, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories weighted by average selling price evolution and software attach rates. Forecast inputs incorporated 3D NAND layer count expansion, high-bandwidth memory stack height growth, and automotive electrification content per inverter module.
The model assumes a particular technology adoption path; alternative pathways for laser-assisted bond inspection would alter the outlook if optical systems capture share beyond high-bandwidth memory into general flip-chip applications. Forecasts reflect assumptions about EU Chips Act execution pace, REACH enforcement timelines, and NHTSA traceability mandate harmonization. Practitioners should monitor hybrid optical-force system penetration rates, titanium nitride coating qualification progress, and India PLI scheme beneficiary announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
RFID Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Dosimeter Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
ESG Sensor Data Quality and Validation Test Platforms Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Digital Weighing Machine Market