
 Digital Oscilloscope Market | 2026-2036
Digital Oscilloscope Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oscilloscope Market Analysis
Gigahertz-class bandwidth specification is redrawing competitive boundaries in digital oscilloscope procurement. Keysight Technologies leverages in-house ASIC fabrication to sustain margin structures at the high-performance tier. Tektronix anchors its position through deep calibration service networks that extend instrument lifecycle value. Rohde & Schwarz differentiates via integrated RF and digital test portfolios that compete for aerospace and defense validation budgets.
A digital oscilloscope captures, digitizes, and displays time-varying electrical signals with defined vertical resolution and real-time sampling rates exceeding multiple gigasamples per second, serving engineers who debug circuit behavior and validate signal integrity across embedded designs. Bench top configurations retain the dominant revenue position due to laboratory and manufacturing floor permanence, while modular formats are gaining fastest in automated test equipment racks where density and programmability command premium positioning. Handheld variants occupy a narrower margin pool focused on field service technicians requiring portability over bandwidth depth.
FCC equipment authorization rules in the United States and CE marking requirements under the EU's Radio Equipment Directive shape product compliance pathways, with EMC testing mandates directly expanding oscilloscope utilization in pre-certification workflows. Japan's METI energy efficiency standards and China's GB electromagnetic compatibility regulations add parallel certification layers for instruments sold into those markets. Stakeholders must monitor how automotive Ethernet and MIPI protocol proliferation reshapes bandwidth requirements before committing to next-generation platform architectures.
Market Dynamics
Automotive Ethernet migration toward 10Gbps+ signaling is compressing oscilloscope refresh cycles as validation labs confront protocol-specific jitter budgets that exceed legacy instrument capabilities.
Growth Catalysts
- USB-C Power Delivery 3.1:The EU's Radio Equipment Directive mandates signal integrity verification for 240W charging profiles, forcing test houses to acquire multi-gigahertz bandwidth units.
- EV inverter switching:Silicon carbide adoption in traction drives requires sub-nanosecond rise-time capture, pulling 8+ GHz instruments into automotive EMC suites.
- MIPI D-PHY proliferation:Camera module validation for ADAS stacks concentrates procurement in Stuttgart and Munich corridor facilities.
Market Restraints
- Front-end ASIC concentration:Three foundry sources in East Asia control indium phosphide process nodes essential for >20 GHz amplifiers.
- Calibration infrastructure:NIST-traceable 50 GHz standards require capital outlays exceeding $2 million per metrology lab, freezing mid-tier vendor expansion.
- Probe ecosystem lock-in:Proprietary accessory interfaces from incumbent vendors create switching costs that extend replacement cycles.
Strategic Opportunities
- India BIS certification:Mandatory EMI testing for telecom infrastructure under 2024 technical regulations opens instrument placement in Bengaluru and Hyderabad labs.
- Modular PXI integration:Convergence of vector signal analyzers with digitizer modules enables single-chassis RF-digital correlation for 5G baseband verification.
- Cloud-native analytics:Browser-based measurement collaboration is displacing site-bound software licenses in distributed engineering teams.
Industry Challenges
- Signal integrity expertise gap:Universities produce fewer analog designers capable of interpreting TDR impedance profiles, forcing vendors to embed automated measurement assistants.
- Multi-domain calibration coordination:Synchronizing RF, power, and digital channel calibrations across firmware revisions consumes 15-20% of field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oscilloscope Market |
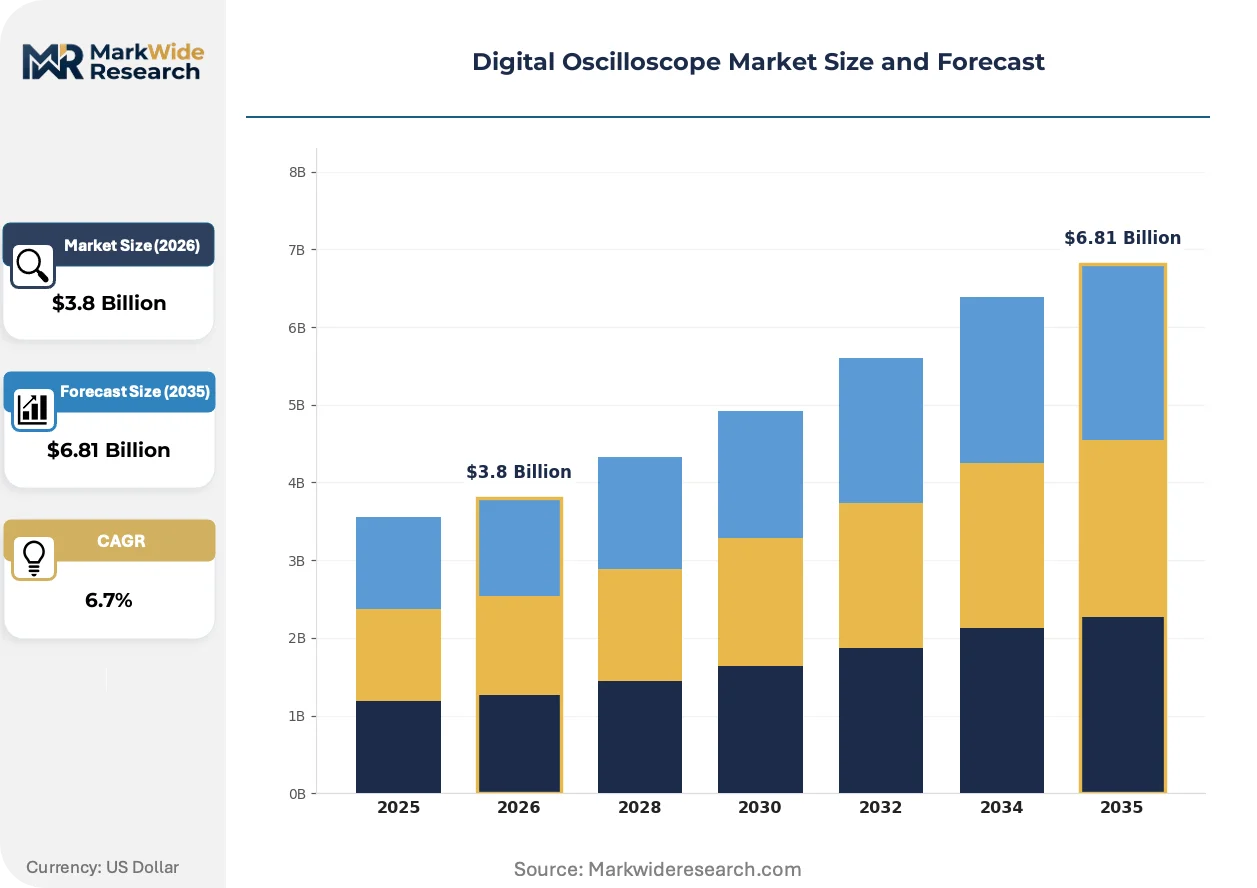
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Bench Top, Modular, Portable Technology: Analog, Digital, Mixed Signal, Sampling End User: Electronics, Automotive, Telecommunications, Education Application: Signal Analysis, Debugging, Communications, Embedded Systems |
| Companies Covered | Keysight Technologies, Tektronix, Rohde & Schwarz, Teledyne LeCroy, Yokogawa Test & Measurement Corporation, Rigol Technologies, Fluke Corporation, Good Will Instrument Co. Ltd., Siglent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oscilloscope Market Emerging Trajectories
Instrumentation architecture is fragmenting between bench permanence and rack density as end-users split between deep characterization and high-throughput manufacturing test.
GaN-based front-end amplification is miniaturizing 1 GHz-class acquisition channels into handheld form factors without sacrificing noise floor performance. Field service technicians in utility and industrial maintenance segments are adopting these units for substation and plant-floor diagnostics. The form factor compression is forcing bench vendors to defend position through software differentiation rather than hardware specifications alone.
CE marking requirements under the EU's Radio Equipment Directive now explicitly reference conducted emissions measurement bandwidths that obsolete pre-2020 instrument inventories. Test houses in Germany and France are retiring 500 MHz units ahead of depreciation schedules. The regulatory compression is accelerating replacement demand in European EMC service bureaus.
Leasing and subscription access models are displacing capital purchase for mid-tier bandwidth tiers among startup semiconductor firms. Instrument-as-a-service providers in North America and East Asia now bundle calibration and firmware updates into per-month pricing. The consumption-pattern shift is most visible in fabless design houses facing irregular validation workloads.
Digital Oscilloscope Market Segmentation
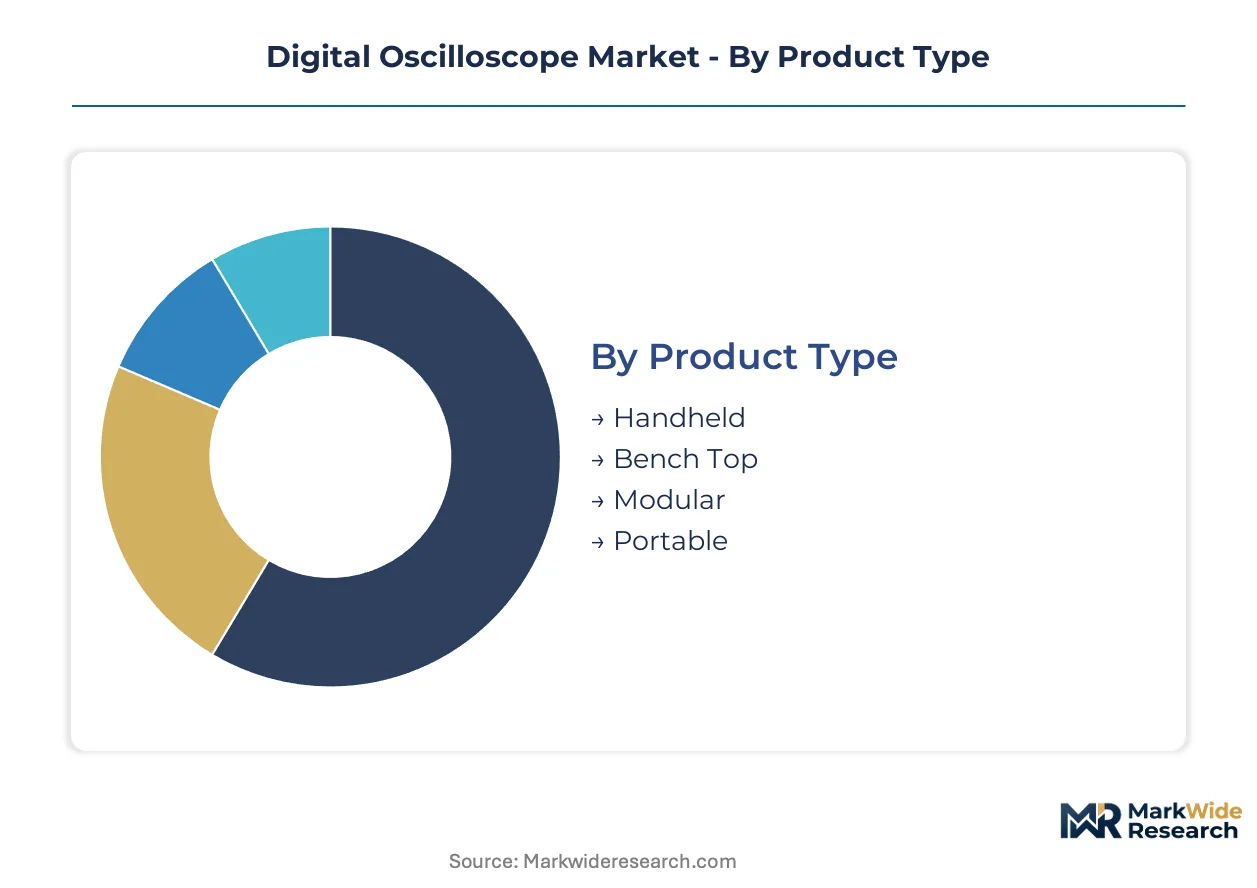
Bandwidth requirements fragment the oscilloscope market into distinct procurement tiers. Engineers select instruments based on signal fidelity needs, deployment environment, and protocol-specific validation demands.
Product Type:
Bench top configurations dominate domestic manufacturing and laboratory permanence, while handheld and modular formats serve export-led field service and automated test integration.
- Bench Top:Permanent laboratory installations with deep memory depth and multi-channel synchronization anchor electronics design workflows. Germany's automotive testing corridor around Stuttgart and Munich concentrates procurement for ADAS validation suites.
- Handheld:Battery-operated units with GaN-based front-end amplification deliver 1 GHz-class performance for utility substation diagnostics. Field service technicians in industrial maintenance segments drive replacement cycles.
- Modular:PXI and AXIe form factors integrate into automated test equipment racks for high-throughput manufacturing floors. Density and programmability command premium positioning in 5G baseband verification.
- Portable:Lightweight transportable units bridge bench and field applications with reduced specifications. Education and training facilities favor these for student laboratory access.
Bench top holds the largest share; momentum sits with modular formats.
Technology:
Cost tiers separate legacy analog architectures from digital acquisition engines with real-time sampling rates exceeding multiple gigasamples per second.
- Digital:Real-time digitization with defined vertical resolution captures time-varying electrical signals for signal integrity validation. USB-C Power Delivery 3.1 compliance testing in European test houses drives multi-gigahertz bandwidth procurement.
- Mixed Signal:Integrated analog and digital channel acquisition enables embedded system debugging across microcontroller interfaces. MIPI D-PHY protocol proliferation for camera modules concentrates demand in automotive electronics development.
- Analog:Direct voltage-versus-time display without digitization retains niche applications for continuous waveform observation. Budget-constrained education laboratories sustain residual demand.
- Sampling:Equivalent-time acquisition techniques extend effective bandwidth for repetitive signal analysis. RF component characterization in aerospace and defense validation budgets supports specialized procurement.
Digital commands the premium tier; mixed signal is climbing the fastest.
End User:
Application maturity separates established electronics manufacturing from emerging automotive Ethernet validation requirements.
- Electronics:Semiconductor design houses and contract manufacturers utilize oscilloscopes for PCB bring-up and component qualification. Fabless startups in North America and East Asia are shifting toward instrument-as-a-service leasing models.
- Automotive:Silicon carbide inverter switching analysis requires sub-nanosecond rise-time capture for traction drive validation. EV charging standard compliance under EU Radio Equipment Directive mandates signal integrity verification.
- Telecommunications:5G baseband and mmWave frontend development drives vector signal analyzer integration with digitizer modules. India's BIS certification for telecom infrastructure under 2024 technical regulations opens instrument placement in Bengaluru labs.
- Education:University laboratories train analog designers on impedance profile interpretation and TDR measurements. Automated measurement assistants embedded in firmware address expertise gaps in emerging engineering programs.
Electronics maintains volume leadership; automotive exhibits steepest expansion trajectory.
Application:
Customer workflow differentiation separates deep characterization tasks from high-throughput manufacturing test.
- Signal Analysis:Frequency-domain decomposition and jitter decomposition for high-speed serial links. CE marking conducted emissions measurement bandwidths obsolete pre-2020 instrument inventories in European EMC service bureaus.
- Debugging:Trigger qualification and protocol decode for embedded firmware development. Cloud-native analytics displace site-bound software licenses in distributed engineering teams.
- Communications:Eye diagram and mask testing for Ethernet and MIPI physical layers. Calibration infrastructure requirements freeze mid-tier vendor expansion due to NIST-traceable 50 GHz standard capital outlays.
- Embedded Systems:Multi-domain correlation across power, RF, and digital channels. Multi-domain calibration coordination consumes 15-20% of field service capacity across firmware revisions.
Signal analysis represents the dominant use case; debugging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide foundry capacity for amplifier fabrication concentrates in East Asian process nodes, while instrument demand clusters around automotive electronics corridors and EMC certification hubs across three continents.
Germany
Automotive Ethernet validation for 10Gbps+ signaling and silicon carbide inverter testing drive procurement in the Stuttgart-Munich corridor. CE marking under the EU Radio Equipment Directive mandates conducted emissions measurement bandwidths that obsolete pre-2020 instrument inventories. EMC service bureaus in Baden-Württemberg and Bavaria are retiring 500 MHz units ahead of depreciation schedules.
United States
FCC equipment authorization rules expand oscilloscope utilization in pre-certification workflows for 5G baseband and mmWave frontend development. NIST-traceable calibration standards anchor metrology infrastructure, though capital outlays exceeding $2 million per lab freeze mid-tier vendor expansion. Fabless semiconductor startups in Silicon Valley and Austin are shifting toward instrument-as-a-service leasing models.
China
GB electromagnetic compatibility regulations add parallel certification layers for instruments sold into domestic markets, while MIIT oversight shapes telecom infrastructure testing protocols. Yangtze River Delta electronics manufacturing clusters and Pearl River Delta contract manufacturers sustain volume demand for bench top configurations. Domestic vendors are gaining share in sub-1 GHz education and industrial maintenance segments.
India
BIS certification mandates under 2024 technical regulations for telecom infrastructure EMI testing open instrument placement in Bengaluru and Hyderabad labs. The PLI scheme for electronics manufacturing is attracting contract manufacturers who require validation equipment for PCB bring-up. Field service technicians in utility substations are adopting GaN-based handheld units for plant-floor diagnostics.
Japan
METI energy efficiency standards influence instrument design requirements for domestic sale, while JIS calibration protocols maintain premium positioning for high-bandwidth units. Automotive electronics development around Nagoya and Tokyo sustains demand for mixed-signal acquisition systems. Camera module validation for ADAS stacks pulls MIPI D-PHY protocol testing into regional validation facilities.
Digital Oscilloscope Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where ASIC fabrication depth separates premium bandwidth vendors from mid-tier competitors. The market consolidates around three strategic groupings: in-house semiconductor foundry operators with captive amplifier supply, calibration service network builders extending instrument lifecycle value, and integrated RF-digital portfolio providers competing for aerospace validation budgets. Dominant competitive moves include strategic partnerships for probe ecosystem lock-in and geographic expansion through localized calibration infrastructure.
Within the premium-tier vector, Keysight Technologies and Tektronix anchor positions through differentiated hardware-software integration, while Rohde & Schwarz occupies a position exemplifying integrated portfolio breadth. These three entities represent the archetype of full-stack instrumentation vendors competing for multi-domain validation contracts. Mid-tier procurement concentrates among Asia-Pacific-based specialists and modular format providers serving automated test equipment integration.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix |
| Rohde & Schwarz |
| Teledyne LeCroy |
| Yokogawa Test & Measurement Corporation |
| Rigol Technologies |
| Fluke Corporation |
| Good Will Instrument Co. Ltd. |
| Siglent Technologies |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at indium phosphide foundries in Taiwan and South Korea anchors cost structures across bandwidth tiers, concentrating supply-side leverage among three East Asian process nodes while compressing price floors for mid-tier competitors lacking captive amplifier fabrication.
Pricing Analysis
CE marking under the EU Radio Equipment Directive dictates the pricing tier structure for European procurement, stratifying instruments across premium multi-gigahertz, standard mid-bandwidth, and economy education-laboratory levels. Price differentiation rests on calibration traceability depth and firmware update entitlements rather than hardware specifications alone. Pricing pressure intensifies in the handheld segment as GaN amplification commoditizes 1 GHz-class acquisition channels. Fabless semiconductor startups exhibit highest price sensitivity, while aerospace validation labs prioritize specification compliance over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for indium phosphide amplifiers that enable sub-nanosecond rise-time capture, while Japan and the United States concentrate probe assembly and precision metrology equipment. Raw material dependencies span gallium nitride substrates, high-purity ceramics for hybrid circuits, and specialized coaxial cable assemblies. Single-source vulnerability concentrates in East Asian foundry capacity for front-end ASICs exceeding 20 GHz. Distribution runs through authorized channel partners with NIST-traceable calibration capabilities, extending replacement cycles through service contract attach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-as-a-service revenue layers are expanding faster than hardware shipments as European EMC bureaus and automotive validation labs prioritize NIST-traceable uptime over capital ownership.
For Market Incumbents: Secure probe ecosystem lock-in through proprietary accessory interfaces that extend switching costs and replacement cycles. Deepen backward integration into indium phosphide process nodes to defend margin structures against mid-tier competitors. Capacity addition in German calibration infrastructure anchors automotive corridor relationships. For New Entrants and Emerging Players: Lead with modular PXI format penetration in 5G baseband verification where density and programmability command premium positioning. White-space concentrates in India's BIS certification laboratories under 2024 technical regulations and utility substation diagnostics with GaN-based handheld units. Cloud-native analytics partnerships displace site-bound software licenses in distributed engineering teams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrument-as-a-service providers bundling calibration and firmware updates into per-month pricing. Long-term viability favors vendors with metrology lab networks extending instrument lifecycle value. Acquisition target archetypes include modular format specialists with automated test equipment integration capabilities. The signal to monitor is leasing penetration rates among fabless semiconductor startups facing irregular validation workloads.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | NIST-traceable 50 GHz standards in Germany's Stuttgart-Munich corridor anchor automotive validation relationships. |
| ASIC Fabrication Backward Integration | In-house indium phosphide process nodes defend margin structures at the multi-gigahertz performance tier. |
| Cloud-Native Analytics Platform Launch | Browser-based measurement collaboration displaces site-bound software licenses in distributed engineering teams. |
| Modular PXI Format Development | Single-chassis RF-digital correlation enables 5G baseband verification with density and programmability premiums. |
| Instrument-as-a-Service Model Rollout | Per-month pricing with bundled calibration captures fabless startups facing irregular validation workloads. |
Methodological Framework
A standing panel of validation laboratory directors, automotive EMC test engineers, semiconductor procurement managers, and field service technicians provided ongoing calibration against market developments. Primary interviews combined with secondary validation from FCC equipment authorization databases, EU CE marking registries, METI energy efficiency filings, and BIS technical regulation notices. Bottom-up instrument shipment tracking triangulated against top-down electronics manufacturing investment flows.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, automotive OEM R&D expenditure patterns, and contract manufacturer equipment procurement records. Segmentation dimensions spanned product type, bandwidth tier, end-use vertical, and regional regulatory cluster. CAGRs derived from instrument replacement cycle compression analysis and protocol-specific bandwidth requirement trajectories. Forecast inputs incorporated silicon carbide inverter adoption curves and MIPI D-PHY proliferation rates in ADAS development.
The analysis sits within stated boundaries; outcomes outside sustained automotive Ethernet migration toward 10Gbps+ signaling or disruption to East Asian foundry capacity would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and certification mandate adoption. Recalibration cycles align with material shifts in EV charging standard revisions and probe interface standardization efforts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Automated Optical Inspection (AOI) System Market
Test and Measurement
Circuit Tracer Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Radio Frequency Test Equipment Market