
 Microwave Power Meters Market | 2026-2036
Microwave Power Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Power Meters Market Analysis
The microwave power meter market is decoupling into two distinct tiers: laboratory-grade benchtop systems with sub-nanosecond resolution versus field-deployable handheld units optimized for quick verification. Keysight Technologies leverages its calibration laboratory network to sustain premium positioning in aerospace and defense accounts. Rohde & Schwarz GmbH & Co. KG anchors European demand through deep integration with 5G base station test protocols. Boonton Electronics competes on thermal sensor architectures that occupy niche applications in pulsed radar measurement.
Microwave power meters are precision instruments that quantify electromagnetic power in the RF and microwave spectrum, typically spanning frequencies from 10 MHz to 110 GHz with dynamic ranges exceeding 80 dB depending on sensor architecture; thermal-based designs employ thermoelectric elements for true-average measurement while diode sensors exploit semiconductor junctions for fast response in peak detection scenarios. Benchtop configurations still dominate revenue concentration due to their integration with automated test equipment in semiconductor wafer probe stations and satellite payload verification. Handheld units represent the fastest-expanding category as field technicians in telecommunications deploy them for tower-mounted amplifier validation without transporting rack-based systems.
The FCC enforces Part 15 and Part 18 rules that mandate precise power emission documentation, compelling meter manufacturers to embed NIST-traceable calibration certificates as standard. ETSI harmonizes test methods across member states through EN 302 567 and related standards, while the EU AI Act introduces documentation burdens for autonomous RF systems that self-optimize transmit power. Buyers must weigh sensor interchangeability against vendor lock-in as modular PXIe formats gain traction in software-defined test architectures.
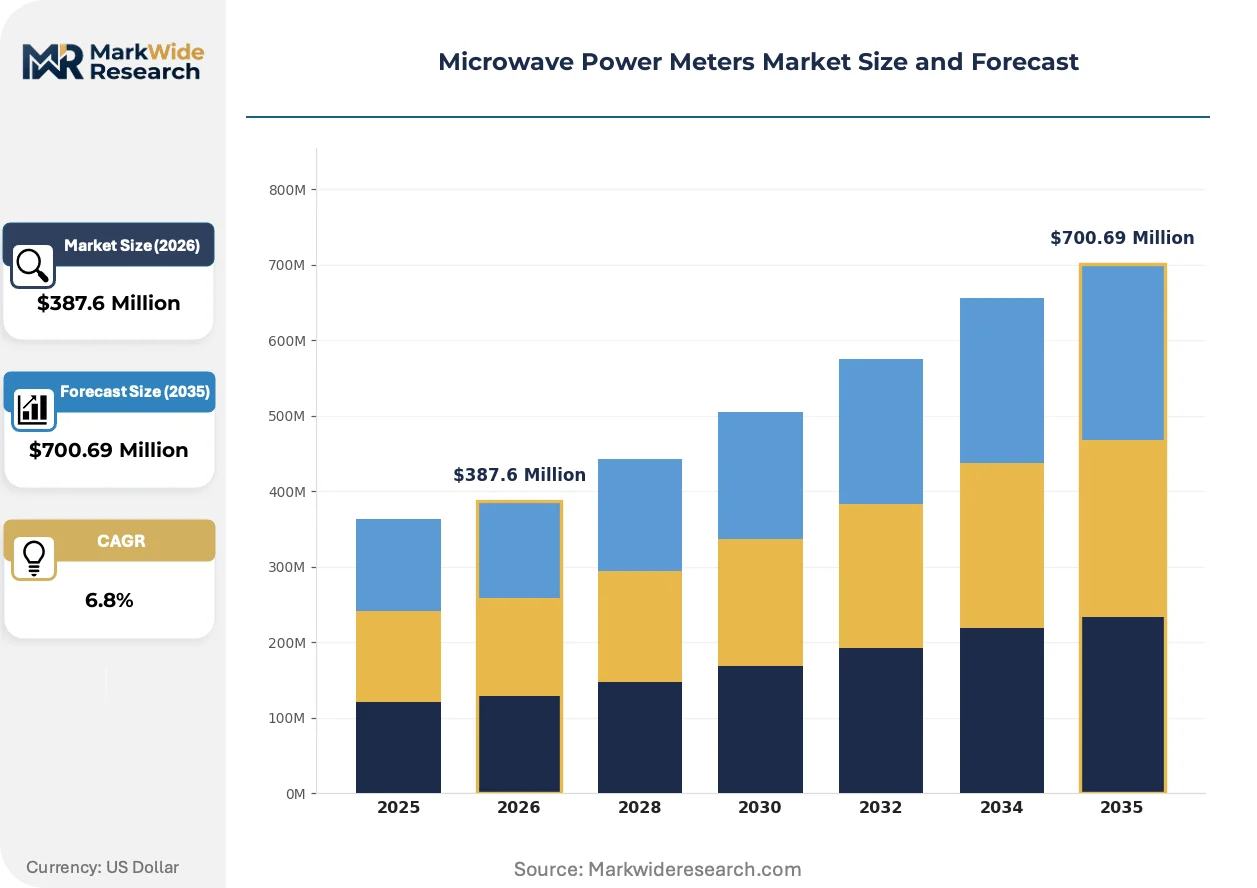
Market Dynamics
The microwave power meter market is bifurcating around sensor architecture choices as thermal-based designs face displacement by wideband diode sensors capable of capturing nanosecond-scale pulse envelopes demanded by 5G massive MIMO and phased-array radar verification.
Growth Catalysts
- 5G Base Station Deployment:Massive MIMO antenna arrays require calibrated power verification at every sector, driving procurement of handheld meters with USB-C sensor interfaces for tower crews.
- FCC Part 15 Enforcement:Tightened spurious emission documentation mandates compel manufacturers to bundle NIST-traceable calibration certificates with every unit shipped.
- GaN Amplifier Proliferation:Gallium nitride RF power amplifiers in radar and electronic warfare systems operate at higher voltages and pulse densities, necessitating specialized peak power sensors.
Market Restraints
- Sensor Interchangeability Lock-in:Proprietary sensor interfaces from dominant vendors fragment the installed base and elevate lifetime ownership costs for multi-site operations.
- Precision Component Supply Concentration:Thermoelectric elements and zero-bias Schottky diodes concentrate sourcing in East Asian foundries, exposing lead times to geopolitical friction.
- Calibration Infrastructure Scarcity:Accredited laboratories capable of traceable power reference standards above 50 GHz remain limited to fewer than twelve facilities worldwide.
Strategic Opportunities
- India Telecom Expansion:Reliance Jio and Bharti Airtel 5G rollouts create demand for cost-optimized handheld meters with localized Hindi-language interfaces.
- EU AI Act Documentation:Autonomous RF systems that self-optimize transmit power must maintain audit trails, opening embedded logging and blockchain-verified calibration records.
- PXIe Modular Convergence:Software-defined test architectures integrating power measurement into PXIe chassis displace standalone benchtop units in semiconductor wafer probe applications.
Industry Challenges
- Millimeter-Wave Calibration Expertise:Technicians proficient in WR-15 and WR-10 waveguide interfacing and thermal drift compensation remain scarce outside defense contractor ecosystems.
- Legacy GPIB Integration Burden:Aerospace and defense test racks running decades-old IEEE-488.2 command sets resist migration to USBTMC or LAN-based alternatives, complicating new meter deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Power Meters Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Benchtop, Rack-mounted, Modular Technology: Thermal, Diode, Peak Power, Average Power End User: Aerospace, Telecommunications, Medical, Research Laboratories Application: RF Testing, Signal Processing, Equipment Calibration, Antenna Measurement |
| Companies Covered | Keysight Technologies, Inc., Rohde & Schwarz GmbH & Co. KG, Anritsu Corporation, Tektronix, Inc., Boonton Electronics, Giga-tronics Incorporated, Vaunix Technology Corporation, LadyBug Technologies LLC, Advantest Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Power Meters Market Emerging Trajectories
Sensor miniaturization and embedded intelligence are compressing the traditional boundary between laboratory-grade and field-deployable instrumentation, enabling new deployment models in distributed antenna systems and satellite ground segments.
Wideband diode sensor technology with true-RMS detection and crest factor measurement is expanding into semiconductor wafer probe stations where thermal sensors previously dominated due to accuracy advantages. Fabless RF component manufacturers in Austin, Texas and Hsinchu now specify sub-100 nanosecond rise time capability as standard for production test. This expansion is compressing the price-performance gap between thermal and diode architectures.
The EU AI Act's documentation requirements for autonomous RF systems are forcing meter manufacturers to embed tamper-evident calibration logging and digital certificate chains. Equipment vendors must now architect firmware with immutable audit trails or risk exclusion from European telecommunications and defense procurement. The benchtop segment faces the heaviest compliance burden as these units anchor regulatory filing workflows.
Telecommunications operators are unbundling after-sales calibration from hardware purchase, treating metrology as a subscription service managed by third-party accreditation bodies. Tower maintenance contractors in Germany now lease sensor pools with automatic replacement upon drift detection rather than owning depreciating assets. This consumption-pattern shift pressures traditional vendors to restructure revenue recognition around recurring service attachments.
Microwave Power Meters Market Segmentation
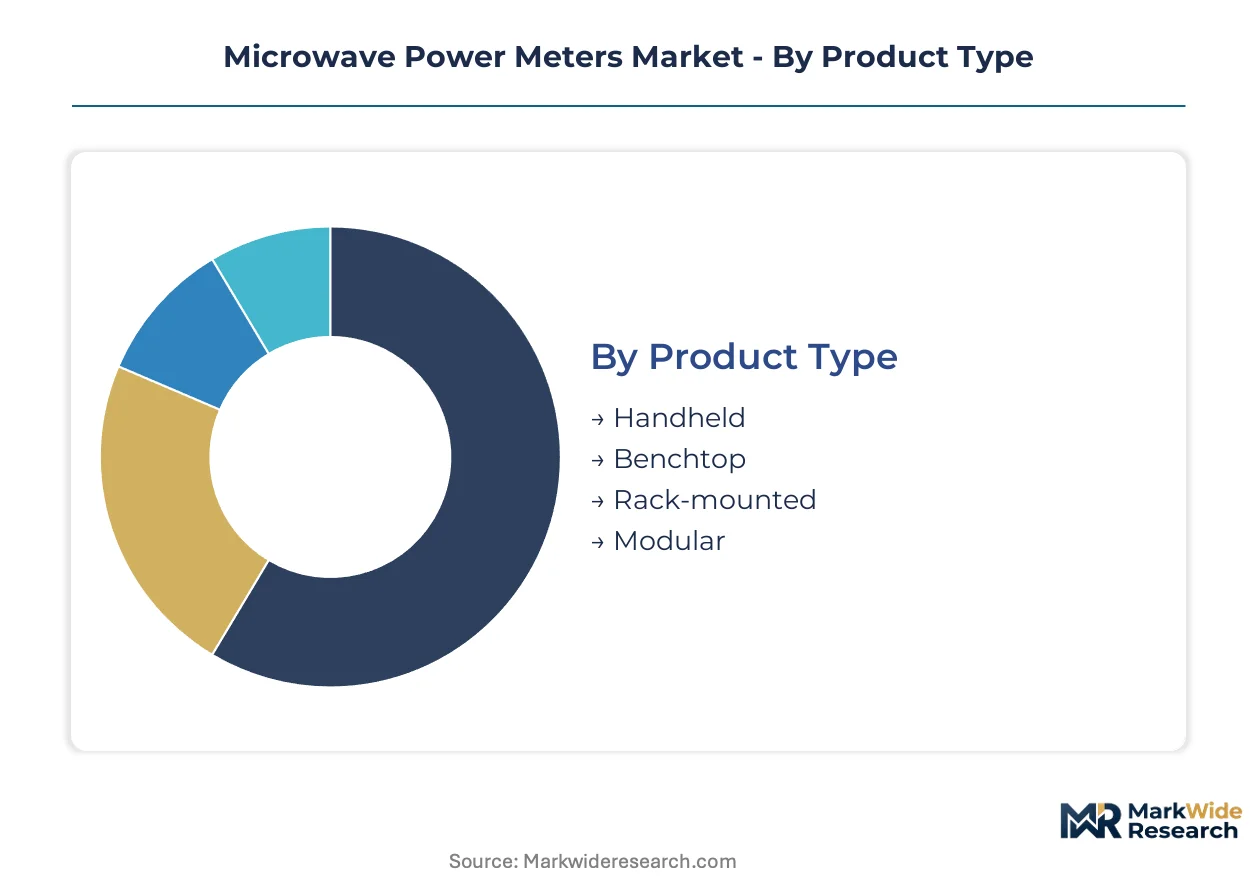
Microwave power meter segmentation reflects divergent certification burdens across deployment contexts. Benchtop systems for semiconductor wafer probe stations carry NIST-traceable calibration mandates under FCC Part 15, while handheld units for tower crews face lighter documentation loads but stricter environmental sealing requirements.
Product Type:
Certification intensity varies sharply across form factors, with benchtop systems requiring the most extensive metrology documentation and modular formats the least.
- Handheld:Compact battery-powered units with USB-C sensor interfaces dominate telecommunications tower maintenance. Reliance Jio and Bharti Airtel procurement in India specifies Hindi-language firmware and IP67 environmental sealing for monsoon exposure.
- Benchtop:Laboratory-grade instruments with sub-nanosecond resolution anchor semiconductor wafer probe stations and satellite payload verification workflows. FCC Part 15 enforcement compiles NIST-traceable calibration certificates as standard bundle elements.
- Rack-mounted:IEEE-488.2 GPIB command compatibility persists in aerospace test racks despite decades-old architecture. Migration resistance to USBTMC or LAN alternatives complicates new unit deployment.
- Modular:PXIe chassis integration formats gain traction in software-defined test architectures. Sensor interchangeability advantages reduce vendor lock-in exposure for multi-site operations.
Benchtop sits at the top of the volume ranking, with handheld climbing the fastest.
Technology:
Sensor architecture selection determines cost tier positioning, with thermal designs commanding premium pricing and diode sensors penetrating cost-optimized segments.
- Thermal:Thermoelectric elements deliver true-average measurement accuracy for metrology-grade applications. East Asian foundry concentration for thermoelectric components exposes supply chains to geopolitical friction.
- Diode:Wideband semiconductor junctions capture nanosecond-scale pulse envelopes for 5G massive MIMO verification. Fabless RF manufacturers in Austin and Hsinchu now specify sub-100 nanosecond rise time as production test standard.
- Peak Power:Specialized sensors address gallium nitride amplifier pulse densities in radar and electronic warfare systems. Higher voltage tolerance requirements differentiate this tier from average-power alternatives.
- Average Power:Simplified detection circuits serve routine maintenance verification where crest factor measurement is unnecessary. Telecommunications operators unbundle calibration services, treating metrology as subscription rather than hardware attachment.
Thermal technology captures the highest margin tier, with diode architectures expanding most quickly.
End User:
Customer type segmentation maps directly to procurement sophistication, with defense contractors demanding full audit trails and medical buyers prioritizing electromagnetic compatibility documentation.
- Aerospace:Defense contractors in the United States expand calibrated RF test equipment procurement for radar and electronic warfare systems. Legacy GPIB integration burdens complicate meter deployment in decades-old test racks.
- Telecommunications:5G base station deployment drives sector-level power verification at every massive MIMO antenna array. Tower crews require portable instrumentation without rack-based system transport.
- Medical:MRI and diathermy equipment manufacturers require precise power emission documentation under FDA electromagnetic compatibility guidelines. Calibration infrastructure scarcity above 50 GHz limits accredited laboratory options.
- Research Laboratories:Academic and government facilities anchor demand for highest-precision thermal sensors. Millimeter-wave calibration expertise scarcity constrains operational capability outside defense contractor ecosystems.
Aerospace commands the largest contract values, with telecommunications expanding fastest.
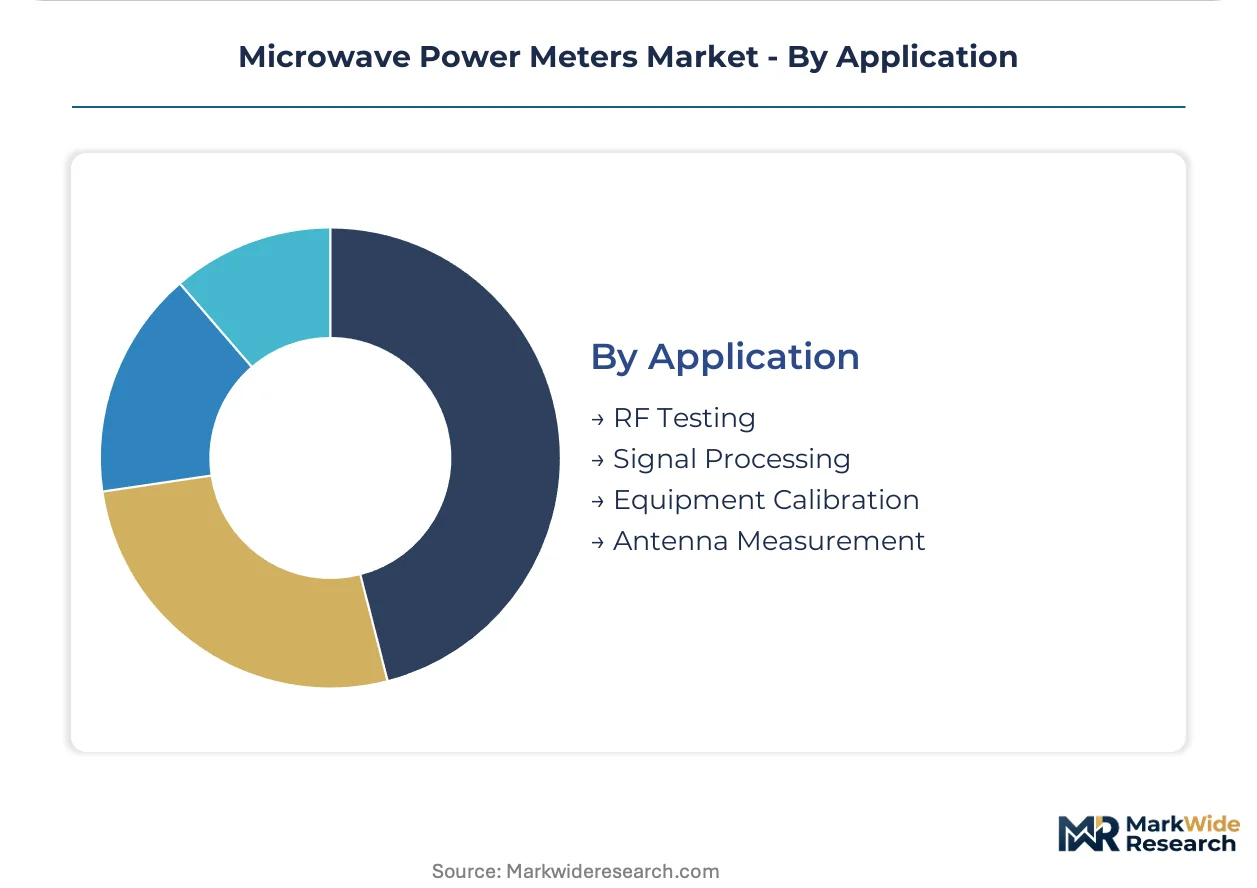
Application:
Application segmentation reveals maturity gradients, with RF testing as established practice and antenna measurement as emerging precision discipline.
- RF Testing:Core power verification function spans all frequency bands and deployment contexts. ETSI EN 302 567 harmonization standardizes test methods across European member states.
- Signal Processing:Real-time envelope tracking for pulsed radar and communications systems demands specialized sensor response characteristics. EU AI Act documentation requirements impose embedded logging and blockchain-verified calibration records.
- Equipment Calibration:Metrology service unbundling transforms hardware vendors toward recurring revenue attachments. German tower maintenance contractors now lease sensor pools with automatic replacement upon drift detection.
- Antenna Measurement:Phased-array characterization for 5G and satellite applications requires distributed multi-point power sensing. Sensor miniaturization enables new deployment models in distributed antenna systems.
RF Testing holds the largest installed base, with antenna measurement gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration engineers and millimeter-wave technicians concentrate in defense contractor ecosystems around Boston and Munich, anchoring regional demand clusters for precision RF instrumentation.
United States
Defense contractors in Massachusetts and California expand procurement of calibrated RF test equipment for radar and electronic warfare systems. The FCC enforces Part 15 and Part 18 rules mandating precise power emission documentation. The Boston metropolitan area hosts concentrated aerospace test facilities requiring NIST-traceable calibration infrastructure.
Germany
Rohde & Schwarz anchors European demand through deep integration with 5G base station test protocols. The EU AI Act introduces documentation burdens for autonomous RF systems that self-optimize transmit power. Precision instrumentation clusters in Munich and Stuttgart support automotive radar verification workflows for Tier-1 suppliers.
Japan
Anritsu Corporation and Advantest Corporation leverage domestic semiconductor equipment relationships to supply wafer probe stations. METI promotes 5G and Beyond 5G infrastructure investment through R&D subsidies. The Yokohama-Tokyo corridor concentrates fabless RF component manufacturers specifying sub-100 nanosecond rise time capability.
India
Reliance Jio and Bharti Airtel 5G rollouts create demand for cost-optimized handheld meters with localized Hindi-language interfaces. TRAI mandates electromagnetic field exposure compliance documentation for tower installations. Bengaluru and Hyderabad host telecommunications equipment manufacturing zones requiring field-deployable verification tools.
China
MIIT spectrum efficiency mandates accelerate base station deployment across provincial telecom networks. GB standards harmonize test methods for domestic 5G massive MIMO equipment certification. The Yangtze River Delta concentrates semiconductor foundries importing thermal sensor architectures for production test integration.
Microwave Power Meters Market Vendor Landscape
Top-tier vendors anchor the premium calibration tier, while mid-scale specialists occupy niche sensor architecture segments. The vendor base stratifies around three competitive vectors: laboratory-grade benchtop systems, field-deployable handheld units, and modular PXIe formats for software-defined test. Two strategic archetypes dominate—full-spectrum metrology houses with calibration laboratory networks, and fabless sensor specialists competing on thermal or diode architectures. Competitive moves concentrate on sensor interchangeability standardization and geographic expansion through localized firmware interfaces.
Among US-based instrumentation houses, Keysight Technologies, Inc. exemplifies the full-spectrum metrology archetype with extensive calibration infrastructure. Boonton Electronics occupies a position within the specialized sensor tier, competing on thermal architectures for pulsed radar measurement. Rohde & Schwarz GmbH & Co. KG anchors European supply through precision instrumentation clusters integrated with regional 5G test protocols.
| Leading Market Players |
|---|
| Keysight Technologies, Inc. |
| Rohde & Schwarz GmbH & Co. KG |
| Anritsu Corporation |
| Tektronix, Inc. |
| Boonton Electronics |
| Giga-tronics Incorporated |
| Vaunix Technology Corporation |
| LadyBug Technologies LLC |
| Advantest Corporation |
| Others |
Supply Flow & Price Mechanics
Defense contractors in the United States anchor procurement volume and enforce bundled calibration service contracts, creating a two-tier pricing structure where NIST-traceable certificate bundles command premium positioning against unbundled hardware sales to commercial telecommunications buyers.
Pricing Analysis
Calibration bundling versus hardware-only unbundling splits the pricing landscape. Three-tier pricing structure across premium metrology-grade, standard industrial-grade, and economy field-grade levels separates aerospace procurement from telecommunications tower maintenance. Cost compression in handheld units intensifies because Indian and Chinese manufacturers introduce localized alternatives with Hindi and Mandarin firmware. Telecommunications operators exhibit highest price sensitivity through subscription-based metrology service adoption, while defense contractors remain least sensitive due to mission-critical traceability mandates.
Supply Chain Analysis
Dual-sourcing requirements from prime defense contractors mandate qualified secondary suppliers for thermoelectric elements and zero-bias Schottky diodes. Manufacturing concentrates in Japan, Germany, and the United States for precision sensor assembly, while East Asian foundries in Taiwan and South Korea dominate semiconductor junction fabrication. Raw material dependencies include bismuth telluride thermoelectric compounds, gallium arsenide substrates, and precision waveguide aluminum alloys. Single-source vulnerability concentrates in millimeter-wave calibration standards above 50 GHz, where fewer than twelve accredited laboratories worldwide maintain traceability. Distribution runs through authorized distributor networks with factory-direct relationships for defense accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European calibration infrastructure scarcity and EU AI Act documentation burdens create margin expansion opportunities against cost-optimized Asian manufacturing.
For Market Incumbents: Hedge against modular PXIe format displacement by deepening calibration laboratory network coverage in India and Southeast Asia. Counter emerging fabless sensor specialists through captive thermoelectric element sourcing or strategic foundry partnerships. Certification investment in EU AI Act-compliant embedded logging firmware defends aerospace and European telecommunications procurement eligibility. For New Entrants and Emerging Players: Wideband diode sensor miniaturization offers the most penetrable wedge into semiconductor wafer probe station applications previously dominated by thermal architectures. Target India's 5G tower maintenance segment with cost-optimized handheld units featuring TRAI-mandated electromagnetic field documentation and Hindi-language interfaces. Pursue channel partnerships with German precision instrumentation clusters for automotive radar verification access. For Investors and Strategic Acquirers: Defense electronics prime contractors represent the most active acquirer in this space, seeking captive metrology capabilities for radar and electronic warfare program security. Long-term viability centers on sensor interchangeability standardization and software-defined test architecture integration. Watch for PXIe modular format adoption inflection in semiconductor capital equipment procurement as signal of benchtop displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Keysight and Rohde & Schwarz extend NIST-traceable infrastructure into India and Southeast Asia defense corridors. |
| EU AI Act Firmware Compliance | Tamper-evident embedded logging and blockchain-verified calibration records unlock European telecommunications procurement. |
| Wideband Diode Sensor Miniaturization | Sub-100 nanosecond rise time capability penetrates semiconductor wafer probe stations from thermal incumbents. |
| Localized Firmware Development | Hindi and Mandarin interfaces capture Reliance Jio, Bharti Airtel, and MIIT-mandated domestic certification workflows. |
| PXIe Modular Format Integration | Software-defined test architectures displace standalone benchtop units in multi-site semiconductor operations. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged RF test equipment product managers, defense contractor procurement officers, telecommunications tower maintenance supervisors, semiconductor wafer probe station engineers, and accredited calibration laboratory directors. Secondary validation drew from FCC Part 15 enforcement databases, ETSI EN 302 567 harmonization documents, EU AI Act regulatory filings, and METI 5G infrastructure subsidy disclosures. Bottom-up sensor shipment aggregation and top-down test equipment capital expenditure analysis provided cross-verification.
Comparable-period anchoring linked projection assumptions to historical defense procurement cycles and 5G base station deployment trajectories across the analysis window. Segmentation modeling spanned form factor tiers, sensor architecture types, end-user verticals, and regional regulatory clusters. CAGRs derived from unit shipment elasticity against capital equipment spending indices and spectrum allocation timelines. Industry-specific inputs included GaN amplifier pulse density specifications and millimeter-wave calibration infrastructure capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction in East Asian thermoelectric component sourcing and EU AI Act enforcement evolution. Forecasts reflect documented assumptions regarding 5G massive MIMO deployment velocity and defense electronics budget allocation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Structure Tester Market
Test and Measurement
Roughness Tester Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
LCR Meter Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
LTE Testing Equipment Market