
 Europe NDT Equipment Market | 2026-2036
Europe NDT Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe NDT Equipment Market Foresight
Software-defined inspection platforms with subscription-based analytics modules is expanding how European NDT vendors monetize hardware deployments. Waygate Technologies GmbH leverages its industrial CT portfolio to anchor high-value contracts across German automotive foundries. Eddyfi specializes in portable phased-array systems that extend reach into offshore wind maintenance workflows across the North Sea basin. Bureau Veritas competes through its inspection-service bundling, which controls channel access for equipment vendors seeking certified end-user adoption.
Europe NDT Equipment encompasses non-destructive testing instruments that evaluate material integrity without altering the subject component, utilizing ultrasonic pulse-echo methods with frequencies typically ranging from 0.5 to 25 MHz to detect subsurface discontinuities in metals and composites. These systems serve critical safety verification across infrastructure, transport, and energy assets where structural failure carries catastrophic liability. Ultrasonic product lines command the deepest installed base due to their versatility across weld inspection and corrosion mapping, while radiographic segments face structural pressure from F-Gas phasedowns that elevate operating costs for film and digital detector systems reliant on consumable gases. Automated technology deployments are capturing the fastest expansion as European manufacturers integrate robotic scanning cells to reduce cycle times and standardize defect documentation for regulatory traceability.
EMA airworthiness directives and the EU F-Gas Regulation together reshape equipment specifications, with the former mandating traceable inspection records for aerospace suppliers and the latter restricting fluorinated greenhouse gases used in certain radiographic processes. CE marking under the Machinery Directive and Pressure Equipment Directive establishes baseline safety and performance thresholds that all marketed NDT systems must satisfy before European commercial deployment. Stakeholders must monitor how EASA's evolving additive manufacturing certification guidelines redefine acceptable defect criteria for powder-bed fusion components, as this will determine which inspection modalities gain preferred status in next-generation aerospace supply chains.
Market Dynamics
The EU F-Gas Regulation is forcing radiographic inspection houses across Germany and France to retire consumable-based systems ahead of 2030 phase-down deadlines, compressing replacement cycles and redirecting capital toward ultrasonic and electromagnetic alternatives.
Growth Catalysts
- EASA Airworthiness Directives:Traceable inspection record mandates for aerospace suppliers in Germany and France are expanding automated scanning cell deployments.
- Offshore Wind Expansion:North Sea turbine maintenance protocols are standardizing portable phased-array ultrasonic systems for subsea weld verification.
- Automotive Foundry Modernization:Industrial CT adoption is accelerating across German OEM supply chains to detect porosity in aluminum castings.
Market Restraints
- Helium Supply Concentration:Radiographic detector cooling depends on helium imports concentrated in Algerian and Qatari sources, creating input cost volatility.
- Phased-Array Skill Scarcity:Interpretation of ultrasonic imaging data requires certified technicians, and training pipeline capacity lags hardware deployment.
- CE Marking Complexity:Machinery Directive compliance timelines for robotic scanning cells extend commercialization by 8-14 months versus legacy systems.
Strategic Opportunities
- Polish Manufacturing Corridor:Automotive and energy infrastructure buildout in Silesia and Lower Silesia remains underpenetrated by automated NDT service providers.
- AI-Assisted Defect Classification:Machine learning convergence with ultrasonic signal processing is reducing false-call rates in aerospace weld inspection.
- Subscription Analytics Modules:Software-defined platforms are opening recurring revenue streams through cloud-based defect trending and predictive maintenance dashboards.
Industry Challenges
- EN ISO 9712 Certification Bottlenecks:European qualification bodies face 6-9 month backlogs for Level II ultrasonic and radiographic inspector certifications.
- Legacy System Integration:Robotic scanning cells must interface with 1990s-era manufacturing execution systems common in German Mittelstand foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe NDT Equipment Market |
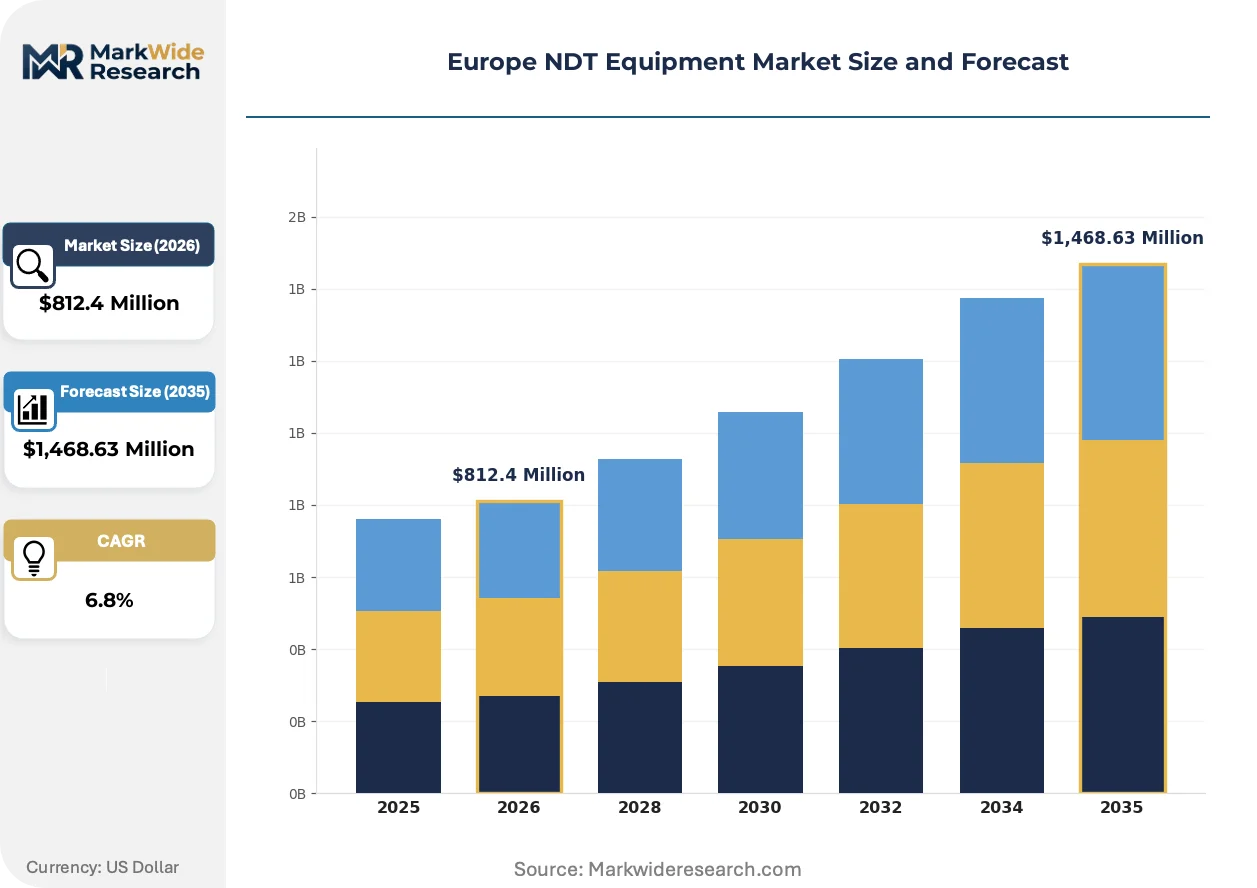
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Radiographic, Magnetic Particle, Eddy Current Application: Aerospace, Automotive, Oil & Gas, Power Generation Technology: Digital, Automated, Conventional, Portable End User: Manufacturing, Construction, Transportation, Energy |
| Companies Covered | Nikon Metrology NV, Intertek Group PLC, Waygate Technologies GmbH, Bureau Veritas, Applus+, YXLON International GmbH, Eddyfi, Comet Group, Evident Europe GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe NDT Equipment Market Shifts & Advancements
Inspection modality preferences are rotating away from radiographic methods toward electromagnetic and ultrasonic alternatives as regulatory pressure compounds total cost-of-ownership disadvantages.
Robotic phased-array ultrasonic scanning is automating weld inspection in German automotive assembly plants. BMW and Volkswagen Group suppliers are deploying gantry-mounted systems for battery tray seam verification. This automation is compressing cycle times from 45 minutes to 8 minutes per component while standardizing defect documentation for EASA traceability requirements.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon use in radiographic film processing and digital detector cooling systems by 2030. German inspection service providers face accelerated equipment write-downs and are redirecting capital toward electromagnetic acoustic transducer alternatives. Aerospace tier-one suppliers in Hamburg and Toulouse are pre-emptively excluding radiographic methods from new contract bids.
Asset operators are unbundling hardware ownership from inspection analytics through subscription-based software modules. Offshore wind farm operators across the Danish and German North Sea coasts are purchasing inspection outcomes rather than equipment, with vendors retaining system ownership and delivering cloud-based defect trending. This consumption-pattern shift is visible most acutely in offshore energy, where mobilization costs favor service-based procurement over capital deployment.
Europe NDT Equipment Market Segmentation
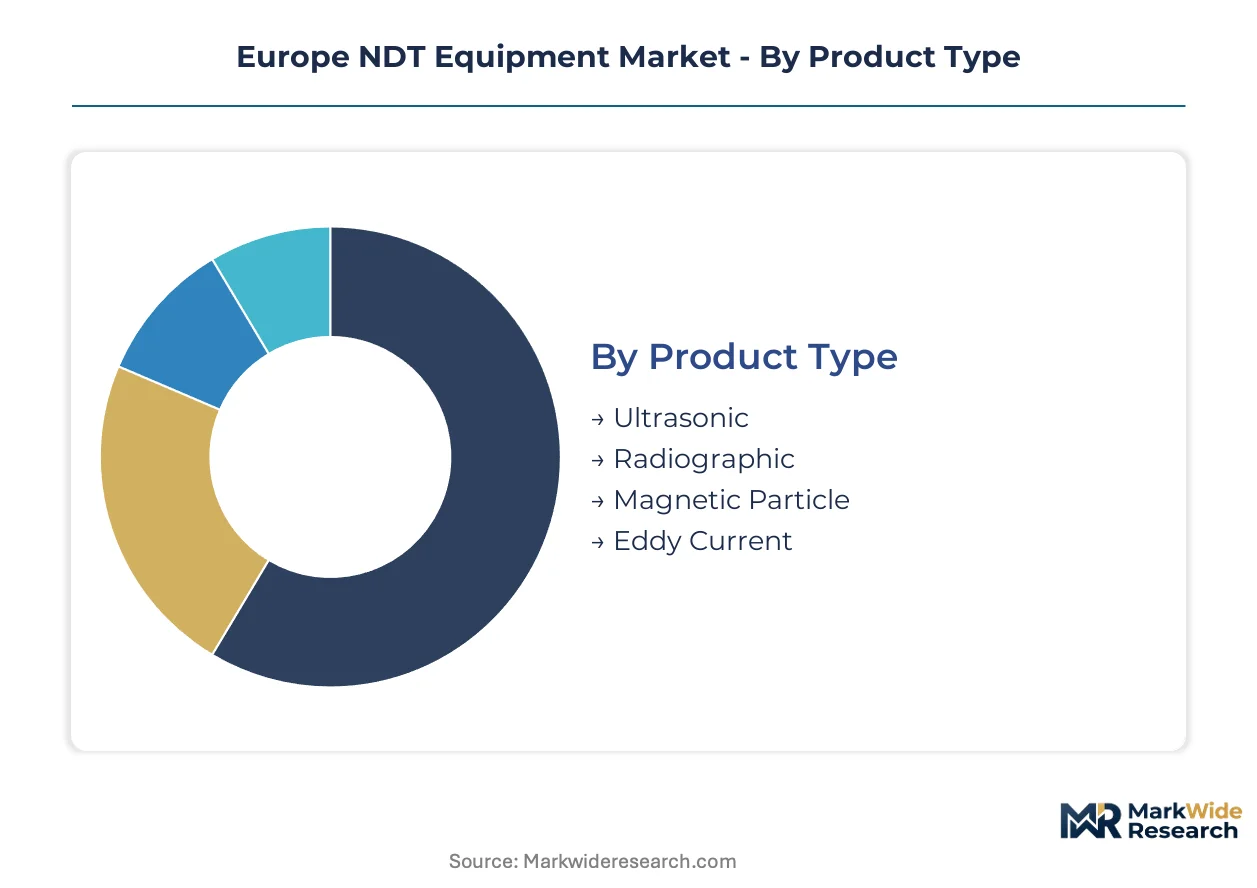
Segmentation reveals how regulatory pressure and end-use specialization concentrate equipment procurement across distinct technical tiers. European buyers select modalities based on traceability mandates, consumable restrictions, and automation integration requirements.
Product Type:
Supply concentrates in ultrasonic platforms as radiographic systems face accelerated replacement cycles under F-Gas phase-down deadlines.
- Ultrasonic:Pulse-echo and phased-array systems operate across 0.5-25 MHz frequency ranges for subsurface discontinuity detection in welds and composites. German automotive foundries and French aerospace suppliers deploy these for EASA-mandated traceability records, with gantry-mounted automation compressing inspection cycles dramatically.
- Radiographic:Film-based and digital detector systems rely on consumable gases and cooling helium imports concentrated in Algerian and Qatari sources. Inspection houses across Hamburg and Toulouse are pre-emptively excluding these methods from new contract bids ahead of 2030 operating restrictions.
- Magnetic Particle:Surface-breaking defect detection for ferromagnetic components in German steel fabrication and pipeline construction.
- Eddy Current:Conductivity-based crack detection deployed in heat exchanger tube inspection across North Sea offshore platforms.
Ultrasonic equipment absorbs the bulk of installed capacity; automated phased-array configurations are expanding most quickly.
Application:
Cost tier differentiation separates aerospace-grade certification requirements from volume-driven automotive procurement patterns.
- Aerospace:EASA airworthiness directives mandate automated scanning cells with standardized defect documentation for powder-bed fusion components and critical structural welds. Hamburg and Toulouse tier-one suppliers drive specification setting for traceable inspection protocols.
- Automotive:Industrial CT adoption accelerates across German OEM supply chains for aluminum casting porosity detection, with BMW and Volkswagen Group suppliers deploying robotic verification for battery tray seams.
- Oil & Gas:Pipeline integrity management and refinery turnaround inspection across Rotterdam and Antwerp energy corridors.
- Power Generation:Turbine blade and pressure vessel verification for utilities operating under Pressure Equipment Directive compliance.
Aerospace absorbs the bulk of high-value system deployments; automotive applications are climbing the fastest as electrification reshapes casting inspection requirements.
Technology:
Volume concentration favors digital signal processing platforms over legacy analog architectures as software-defined inspection gains procurement preference.
- Digital:Software-defined platforms with cloud-connected analytics modules enable subscription-based defect trending and predictive maintenance dashboards. North Sea offshore wind operators purchase inspection outcomes rather than hardware ownership.
- Automated:Robotic scanning cells integrate with manufacturing execution systems for standardized documentation, though CE marking under the Machinery Directive extends commercialization timelines.
- Conventional:Operator-dependent manual inspection persists in Mittelstand foundries with 1990s-era system integration requirements.
- Portable:Battery-powered phased-array units for offshore wind maintenance workflows across Danish and German North Sea coasts.
Digital platforms absorb the bulk of new capital allocation; automated configurations are gaining share fastest as labor scarcity drives robotics integration.
End User:
Customer type determines procurement modality, with energy and transportation operators favoring service-based contracts over capital deployment.
- Manufacturing:German automotive foundries and aerospace tier-one suppliers deploy in-house automated scanning cells for cycle time compression and regulatory traceability.
- Energy:Offshore wind farm operators across the North Sea basin purchase inspection outcomes through vendor-retained equipment models, with mobilization costs favoring service procurement.
- Construction:Infrastructure weld verification for bridge and tunnel projects under national building codes.
- Transportation:Rail and maritime asset integrity programs across European maintenance depots.
Manufacturing absorbs the bulk of equipment ownership; energy end users are shifting fastest toward outcome-based procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates equipment manufacturing capacity, while France and the United Kingdom absorb disproportionate demand from aerospace and energy infrastructure. Southern and Eastern European markets remain underpenetrated by automated inspection service providers.
Germany
Automotive OEMs and Mittelstand foundries drive ultrasonic system procurement for aluminum casting verification. The F-Gas Regulation accelerates radiographic system retirements ahead of 2030 deadlines. Bavaria's industrial corridor hosts the continent's densest deployment of robotic scanning cells for battery tray seam inspection.
France
Aerospace tier-one suppliers in Toulouse mandate automated scanning cells with EASA-traceable documentation for powder-bed fusion components. CE marking under the Machinery Directive extends commercialization timelines for robotic systems. The Hauts-de-France region concentrates industrial CT adoption for aerospace supply chain verification.
United Kingdom
North Sea offshore wind operators purchase inspection outcomes through vendor-retained equipment models rather than capital deployment. The Pressure Equipment Directive governs turbine blade verification protocols. Scottish ports standardize portable phased-array systems for subsea weld maintenance workflows.
Poland
Automotive and energy infrastructure buildout in Silesia and Lower Silesia attracts first-mover automated NDT service providers. EU cohesion funds support manufacturing modernization in these voivodeships. Katowice-based inspection houses upgrade from manual to digital ultrasonic platforms for supply chain integration.
Netherlands
Rotterdam and Antwerp energy corridors demand pipeline integrity management systems for refinery turnaround inspection. The EU Green Deal accelerates hydrogen infrastructure buildout requiring specialized NDT protocols. Eindhoven's high-tech ecosystem incubates AI-assisted defect classification startups for aerospace applications.
Europe NDT Equipment Market Competitive Landscape
Top-tier vendors anchor premium-tier automated systems, while mid-tier specialists occupy portable and service-based segments. The vendor base stratifies across three tiers: integrated technology conglomerates with industrial CT portfolios, inspection-service bundlers controlling certified channel access, and portable equipment specialists targeting offshore energy workflows. Consolidation pressure concentrates among radiographic-dependent players facing F-Gas accelerated replacement cycles. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion into underpenetrated Eastern European manufacturing corridors.
Within the technology conglomerate tier, Waygate Technologies GmbH and Nikon Metrology NV exemplify integrated platform providers combining hardware ownership with subscription analytics modules. Eddyfi occupies a specialist position in portable phased-array systems for North Sea offshore wind maintenance. Bureau Veritas represents the inspection-service bundling archetype, controlling certified end-user adoption channels that equipment vendors must navigate for market access.
| Leading Market Players |
|---|
| Nikon Metrology NV |
| Intertek Group PLC |
| Waygate Technologies GmbH |
| Bureau Veritas |
| Applus+ |
| YXLON International GmbH |
| Eddyfi |
| Comet Group |
| Evident Europe GmbH |
| Others |
Supply & Pricing Matrix
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access, as inspection houses must certify equipment compatibility with phased-down consumables before bidding on EASA-mandated aerospace contracts. This environmental mandate stratifies vendors into compliance-verified tiers, with certified automated scanning cells commanding substantial premiums over legacy radiographic systems facing accelerated depreciation.
Pricing Analysis
Margin tightening in radiographic equipment reflects accelerated write-down schedules ahead of 2030 operating restrictions. Three-tier pricing structure across premium automated scanning cells, standard phased-array platforms, and economy portable units separates EASA-traceable systems from general industrial grade. Cost compression runs through radiographic-dependent service providers as helium import volatility and consumable phase-downs erode residual value. Automotive OEM procurement teams exhibit highest price sensitivity, while aerospace tier-one suppliers prioritize traceability certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Algerian and Qatari helium suppliers, whose concentrated output feeds radiographic detector cooling systems across German and French inspection houses. Manufacturing concentrates in Germany, Japan, and the United States for precision transducer arrays and signal processing hardware. Raw material dependencies include piezoelectric ceramics, rare-earth magnetic components, and high-purity helium for cryogenic cooling. Tariff exposure on Chinese-sourced electronic subassemblies threatens cost structures for mid-tier portable equipment. Distribution runs through certified inspection service bundlers who control channel access for equipment vendors seeking Bureau Veritas-adjacent adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with sensor manufacturing and cloud analytics development representing the decisive upstream and downstream levers for competitive positioning.
For Market Incumbents: Hedge radiographic portfolio exposure through accelerated electromagnetic acoustic transducer R&D and backward integration into piezoelectric ceramic production. Consolidate position in Polish manufacturing corridors before EU cohesion fund deployment peaks. Channel control through certified inspection service partnerships remains the critical defensive moat against portable equipment specialists. For New Entrants and Emerging Players: Launch via subscription-based analytics modules targeting North Sea offshore wind operators who prefer outcome procurement over capital deployment. Polish Silesian automotive foundries and Lower Silesian energy infrastructure buildout represent the most penetrable geography. AI-assisted defect classification for aerospace weld inspection offers the strongest go-to-market angle against entrenched automated scanning cell providers. For Investors and Strategic Acquirers: EASA additive manufacturing certification guideline releases are the leading indicator that powder-bed fusion inspection modalities will capture preferred supplier status. Long-term viability over the coming decade hinges on software-defined platform ownership rather than hardware manufacturing scale. Acquisition targets should display captive sensor supply or established cloud analytics subscriber bases. EN ISO 9712 certification body backlogs signal technician scarcity that favors automated interpretation technology investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive piezoelectric ceramic supply insulates margin structures against rare-earth price volatility. |
| Cloud Analytics Platform Development | Subscription defect trending converts transactional hardware sales into recurring revenue from North Sea operators. |
| CE Marking Acceleration Pathway | Machinery Directive compliance compression unlocks 8-14 month commercialization advantage for robotic scanning cells. |
| Polish Manufacturing Corridor Expansion | EU cohesion fund alignment in Silesia and Lower Silesia secures first-mover automated service positioning. |
| AI-Assisted Defect Classification Investment | Machine learning convergence with ultrasonic signal processing reduces false-call rates for EASA-mandated aerospace welds. |
Research Methodology
Independent corroboration across equipment vendor technical directors, EASA certification specialists, and automotive foundry quality managers underwrites the qualitative findings in this study. Primary fieldwork with inspection service bundlers, offshore wind maintenance coordinators, and EN ISO 9712 qualification body administrators captured operational constraints and procurement pattern shifts. Secondary validation drew from Machinery Directive guidance documents, EASA airworthiness directive archives, and EU F-Gas Regulation implementation timelines. Bottom-up equipment deployment estimates triangulated against top-down industrial automation spending projections.
Comparable-period anchoring to historical inspection technology replacement cycles established baseline assumptions across the projection horizon. Segmentation modeling incorporated product type, application vertical, technology tier, and end-user procurement modality dimensions. CAGRs were derived from installed base evolution and capital expenditure intention surveys. Industry-specific forecast inputs included EASA additive manufacturing certification timeline assumptions and EU cohesion fund disbursement schedules for Eastern European manufacturing modernization.
Regulatory enforcement variance, helium supply disruption events, and EN ISO 9712 certification pipeline capacity constraints are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about EASA mandate implementation pacing and F-Gas Regulation phase-down adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Battery Testing Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Digital Comparators Market
Test and Measurement
Digital Multimeter Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market