
 Natural Colorants Market | 2026-2036
Natural Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Colorants Market Analysis
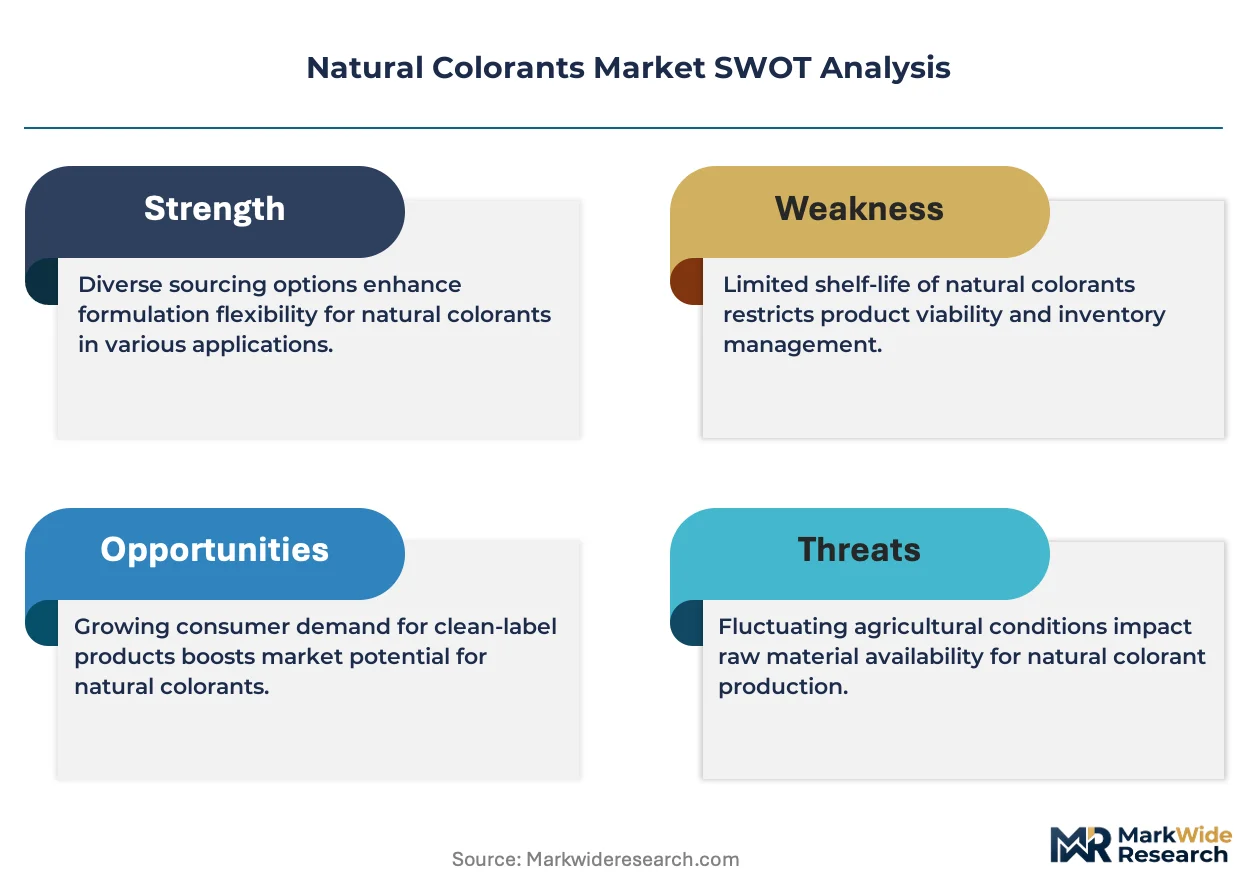
Multi-source botanical procurement is pivoting toward vertically integrated extraction models as buyers seek supply security. Chr. Hansen Holding A/S leverages fermentation-based pigment platforms to sustain consistent batch quality across dairy and confectionery accounts. GNT Group B.V. anchors its position through controlled agricultural partnerships for beetroot and spirulina raw material. Döhler Group competes by extending beverage-specific color systems that integrate stabilization technology with pigment supply.
Natural colorants comprise pigments, dyes, and lakes extracted from plant, animal, or microbial sources through aqueous, solvent, or supercritical CO2 methods, typically standardized to specific color intensity measured in EBC or ICUMSA units for industrial consistency. These compounds serve primarily to replace synthetic dyes in consumer-facing products where visual appeal drives purchase intent while satisfying clean-label requirements. Plant-derived categories including spirulina and turmeric extracts command premium positioning in beverage applications due to thermal stability limitations that constrain cheaper fruit and vegetable alternatives. Powder and liquid forms split demand by manufacturing context, with high-volume food processors favoring concentrated powders for freight efficiency while cosmetics formulators specify liquid dispersions for batch uniformity.
EU REACH and the FDA color additive regulations jointly restrict synthetic azo dye approvals while creating favorable pathways for specified botanical extracts in food contact applications. EFSA's ongoing re-evaluations of titanium dioxide and certain artificial colors accelerate reformulation timelines across European packaged food portfolios. Stakeholders must monitor regulatory divergence between FDA and EMA approval lists for novel microbial pigments, as asynchronous clearances will fragment product launch strategies and regional inventory requirements.
Market Dynamics
Clean-label mandates from major retailers are compressing synthetic dye tolerance windows while extraction technology advances reduce botanical pigment cost premiums. This regulatory-commercial squeeze is forcing processors to requalify entire product lines around plant-derived alternatives.
Growth Catalysts
- EU REACH restrictions:The framework's tightening approval pathways for azo dyes redirect formulation budgets toward exempt botanical sources in food contact applications.
- Spirulina extraction advances:Supercritical CO2 methods now yield phycocyanin concentrates stable enough for UHT beverage processing, opening premium positioning in dairy alternatives.
- India's processing expansion:Domestic turmeric and annatto extraction capacity additions reduce import dependence for Southeast Asian confectionery manufacturers.
Market Restraints
- Agricultural input volatility:Beetroot and spirulina harvest yields fluctuate with climate patterns, creating batch-to-batch color intensity variance that exceeds synthetic dye tolerance bands.
- Extraction equipment concentration:Supercritical CO2 system fabrication concentrates among German and Italian engineering firms, extending lead times for capacity expansion.
- Thermal stability ceilings:Anthocyanin degradation above 85°C limits deployment in retorted sauces and baked goods where caramel and paprika oleoresin substitutes dominate.
Strategic Opportunities
- Brazilian regulatory alignment:ANVISA's pending clean-label guidance for processed foods creates first-mover positioning for FSSAI-certified Indian extractors seeking Latin American offtake agreements.
- Microbial pigment platforms:Fermentation-derived beta-carotene from non-GMO yeast strains bypasses agricultural weather risk while satisfying kosher and halal certification requirements.
- Direct-to-formulator distribution:Bypassing traditional ingredient distributors through technical service partnerships with mid-sized cosmetics compounders captures margin previously absorbed by layered wholesale markups.
Industry Challenges
- Colorist technical shortage:Formulation chemists trained in synthetic dye stabilization require retraining in pH-dependent botanical pigment behavior, extending product development cycles.
- Dual certification burden:Simultaneous FDA and EFSA novel ingredient approvals for microbial pigments fragment inventory requirements and delay unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Colorants Market |
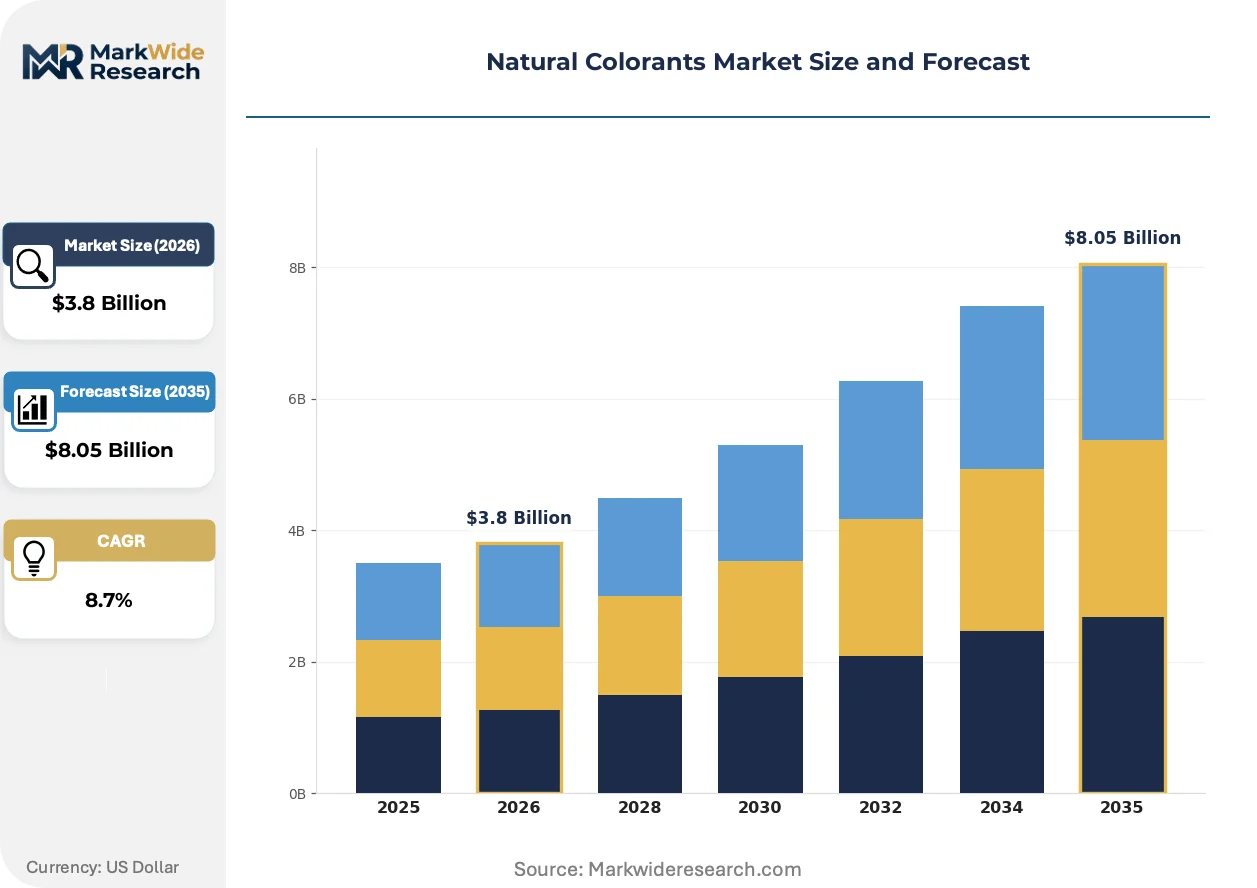
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Spices, Plant Extracts Application: Food, Beverages, Cosmetics, Textiles Form: Liquid, Powder, Granule, Paste Customer Type: Manufacturers, Retailers, Distributors, End Users |
| Companies Covered | Sensient Technologies Corporation, Archer Daniels Midland Company, Chr. Hansen Holding A/S, GNT Group B.V., Döhler Group, FMC Corporation, DDW The Color House, Kerry Group plc, Givaudan S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Colorants Market Emerging Trajectories
Fermentation-based pigment production is collapsing the traditional agricultural supply chain while regulatory divergence between FDA and EFSA accelerates regional formulation specialization. These forces are compressing the competitive window for conventional extraction-dependent suppliers.
Precision fermentation for phycocyanin and astaxanthin is electrifying the economics of high-value blue and orange colorants. Dairy alternative manufacturers in Germany and the Netherlands are adopting these inputs at commercial scale. The technology is electrifying margin structures previously unattainable with outdoor spirulina cultivation, enabling price parity with synthetic Brilliant Blue in beverage applications.
EFSA's ongoing titanium dioxide re-evaluation is accelerating reformulation timelines across European confectionery and chewing gum portfolios. Manufacturers face compressed windows to qualify calcium carbonate and starch-based alternatives without sensory degradation. The coating and glazing segment is responding with accelerated stability testing protocols to maintain shelf appearance through the 2025-2026 transition period.
Confectionery and beverage procurement teams are consolidating supplier relationships around vertically integrated extractors offering technical stabilization support. Traditional distributors with limited application laboratories are losing share to direct partnerships with GNT Group and Chr. Hansen technical service teams. This consolidation is most visible in Nordic markets where retail private-label specifications now mandate single-source pigment accountability.
Natural Colorants Market Segmentation
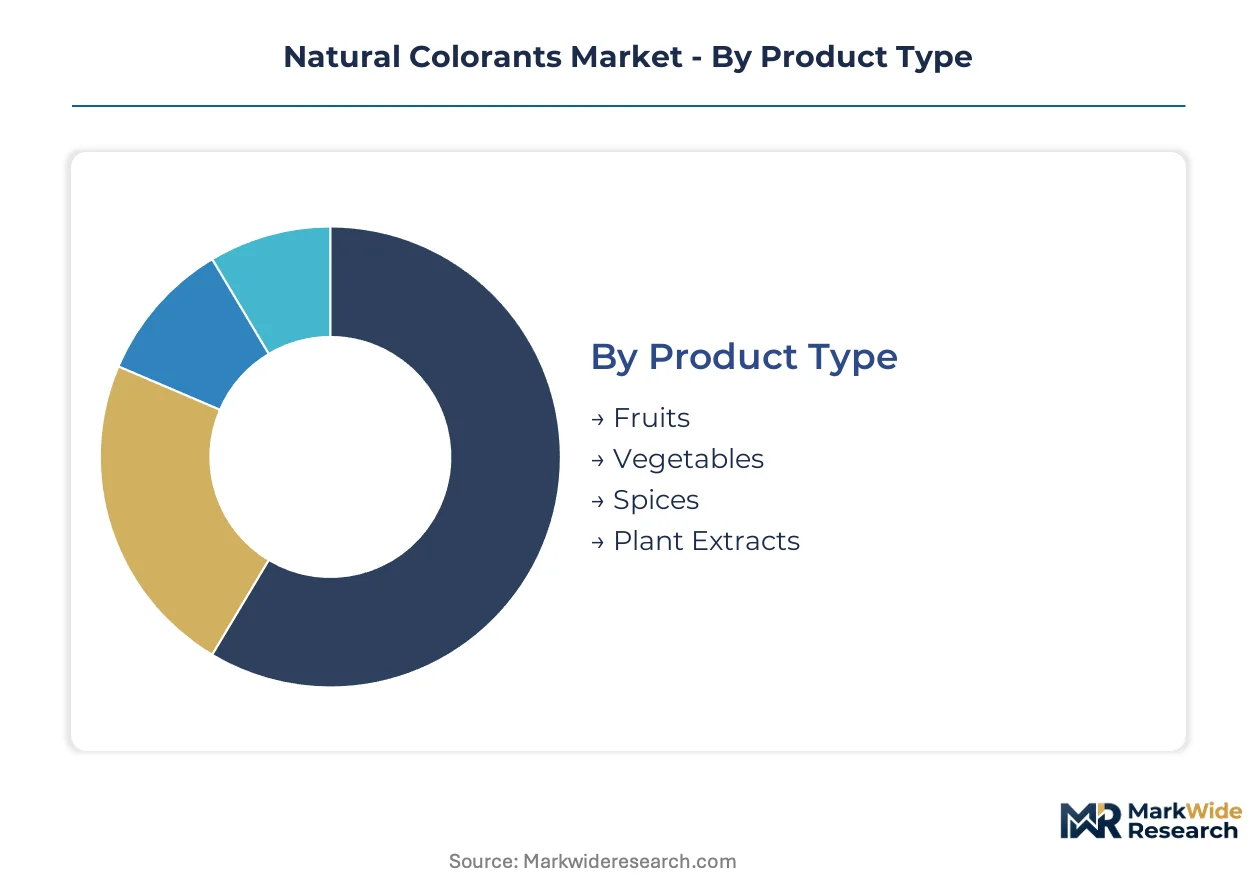
Natural colorant suppliers must align production configurations with divergent technical requirements across extraction source, end-use stability demands, and customer procurement scale. Segmentation discipline separates commodity pigment traders from technical service providers capable of co-developing formulation solutions.
Product Type:
Capital intensity concentrates in extraction infrastructure for complex botanical matrices, with supercritical CO2 systems and fermentation platforms demanding the steepest upfront investment.
- Plant Extracts:Supercritical CO2 and solvent extraction of spirulina, beetroot, and annatto concentrates requires seven-figure equipment commitments. German and Dutch dairy alternative manufacturers now specify phycocyanin concentrates stable through UHT processing, compressing qualification timelines for extractors with in-house stabilization R&D.
- Spices:Turmeric and paprika oleoresin extraction relies on hexane or ethanol solvent systems with lower capital barriers but higher regulatory compliance costs for residual solvent testing. Indian processors are expanding capacity to serve Southeast Asian confectionery accounts seeking FSSAI-certified alternatives to synthetic dyes.
- Fruits:Anthocyanin concentrates from grape, elderberry, and blackcurrant sources face thermal degradation above 85°C, restricting deployment to ambient-fill beverages and refrigerated applications.
- Vegetables:Chlorophyll and carotenoid extracts from spinach, kale, and carrots command premium positioning in clean-label cosmetics where EU REACH exemptions for botanical sources apply.
Most installed capacity flows through Plant Extracts. Expansion is steepest in Spices.
Application:
Margin structures diverge sharply by end-use, with beverage and cosmetics specifications tolerating price premiums that food manufacturers resist.
- Beverages:UHT-stable phycocyanin and turmeric extracts command the highest pigment prices per unit color intensity. German oat milk and coconut water brands now mandate batch-to-batch Delta E consistency below 2.0, forcing suppliers to invest in spectrophotometric quality control systems.
- Cosmetics:Halal-certified and COSMOS-standard botanical pigments for skincare and color cosmetics carry 3-4x markups over food-grade equivalents. Formulators in France and the Netherlands specify liquid dispersions for batch uniformity in emulsion systems.
- Food:Bakery and confectionery applications dominate volume but squeeze margins through commodity procurement practices and synthetic dye substitution economics.
- Textiles:Natural dye uptake for organic cotton and linen remains niche, constrained by poor wash fastness and the absence of standardized color measurement protocols equivalent to EBC or ICUMSA units.
Cosmetics generates the highest margin per kilogram. Food captures the greatest absolute volume.
Form:
Freight economics and handling characteristics split demand between concentrated solids and dispersion-ready liquids.
- Powder:Spray-dried concentrates dominate high-volume food manufacturing where ocean freight efficiency outweighs reconstitution costs. Indian turmeric and annatto powders serve Southeast Asian confectionery processors through bulk container shipments.
- Liquid:Glycerin or propylene glycol dispersions specify into cosmetics batching systems requiring pumpable viscosity and immediate incorporation. Dutch formulators favor liquid spirulina extracts for dairy alternative color consistency.
- Paste:High-solids concentrates for industrial bakery applications reduce water activity and extend shelf stability without refrigeration.
- Granule:Dust-free handling formats for large-scale dry mix operations in beverage powder compounding.
Powder commands the largest share of shipping volume. Liquid is expanding most quickly in premium applications.
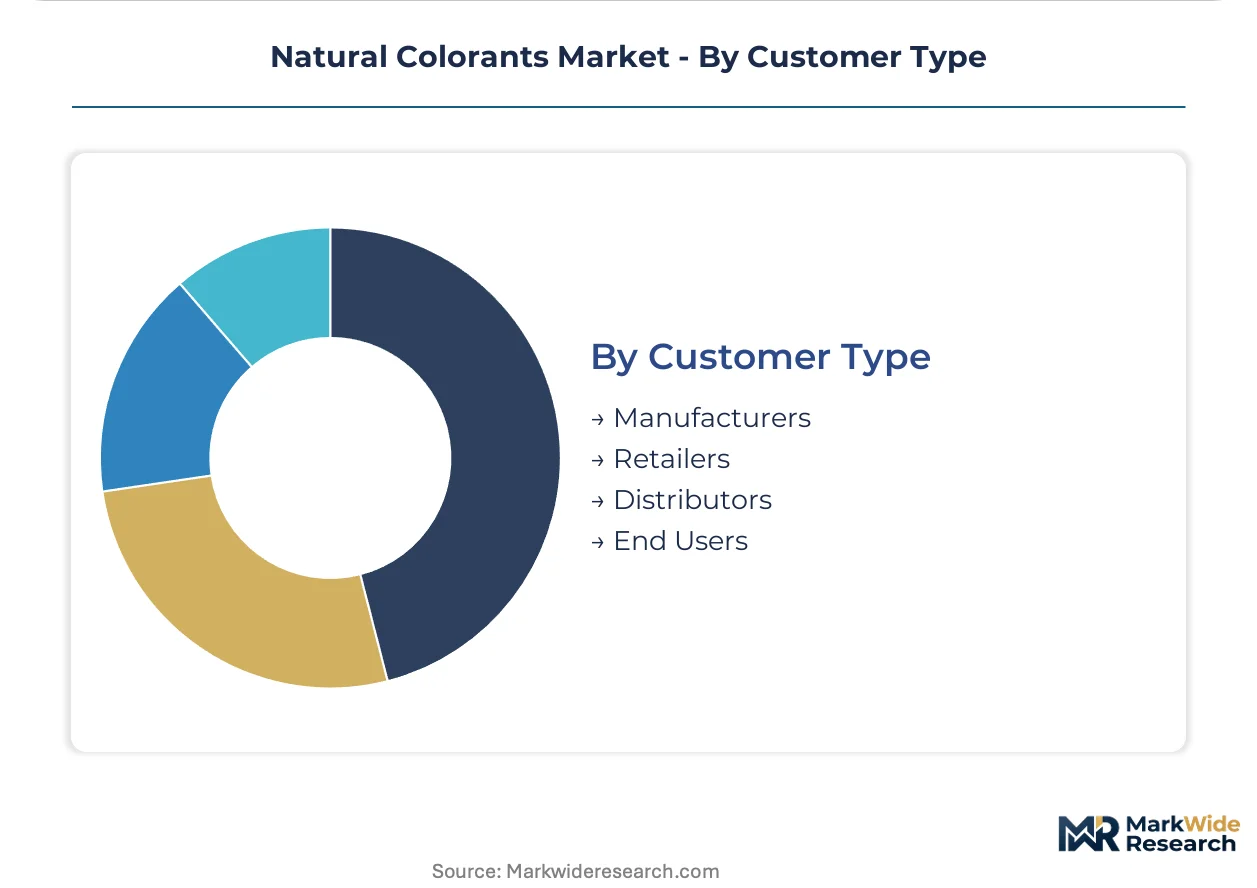
Customer Type:
Procurement sophistication separates direct manufacturing relationships from distributor-mediated transactions.
- Manufacturers:Chr. Hansen and GNT Group technical service partnerships with mid-sized food and cosmetics compounders bypass traditional ingredient distributors, capturing margin previously absorbed by layered wholesale markups.
- Distributors:Traditional traders with limited application laboratories are losing share in Nordic markets where retail private-label specifications now mandate single-source pigment accountability.
- Retailers:Clean-label mandates from major European and North American grocery chains compress synthetic dye tolerance windows and redirect formulation budgets toward exempt botanical sources.
- End Users:Artisan and small-batch cosmetics formulators purchase through specialty chemical distributors with minimum order quantities below direct manufacturer thresholds.
Direct manufacturer relationships concentrate the highest-value accounts. Distributor channels retain price-sensitive volume segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting extraction capacity toward jurisdictions with streamlined botanical approval pathways and lower compliance burdens. India and Brazil attract investment from European processors seeking cost-advantaged feedstock security outside REACH jurisdiction.
United States
Clean-label procurement mandates from Kroger, Whole Foods, and Target compress synthetic dye tolerance windows across private-label portfolios. FDA color additive regulations maintain stricter novel ingredient pathways than EFSA, delaying microbial pigment launches by 12-18 months. California's Bay Area clusters fermentation-based pigment startups supplying dairy alternative brands.
Germany
EFSA's titanium dioxide re-evaluation accelerates confectionery reformulation timelines through 2025-2026. REACH registration requirements for imported botanical extracts elevate compliance costs for non-EU suppliers. Bavaria's Ingolstadt corridor hosts Chr. Hansen technical service laboratories supporting Central European dairy accounts.
India
FSSAI certification expansion for turmeric and annatto extracts reduces Southeast Asian import dependence on European processors. Domestic extraction capacity additions in Gujarat and Maharashtra target confectionery manufacturers in Thailand and Indonesia. Telangana's Hyderabad biotechnology cluster incubates precision fermentation ventures for phycocyanin production.
Brazil
ANVISA's pending clean-label guidance for processed foods creates first-mover positioning for FSSAI-certified Indian extractors seeking Latin American offtake agreements. São Paulo's food manufacturing belt drives demand for annatto and paprika oleoresins in meat and dairy applications. Minas Gerais agricultural cooperatives expand beetroot cultivation for natural red pigment extraction.
Netherlands
German and Dutch dairy alternative manufacturers specify UHT-stable phycocyanin concentrates with batch-to-batch Delta E consistency below 2.0. EFSA novel food approvals for microbial pigments proceed faster than FDA equivalents, enabling earlier commercial deployment. Wageningen University's food technology campus anchors stabilization R&D partnerships with GNT Group.
Natural Colorants Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-based platforms and direct-to-formulator distribution models. The supplier base stratifies between vertically integrated agricultural operators and technology-driven microbial pigment developers. Three archetypes dominate: extraction-dependent botanical specialists, fermentation-platform biotech ventures, and integrated food ingredient conglomerates with colorant divisions. Capacity expansion and backward integration into captive agricultural supply constitute the primary competitive vectors.
Within the extraction-specialist tier, GNT Group B.V. and Döhler Group occupy positions anchored by controlled agricultural partnerships and beverage-specific stabilization systems respectively. Chr. Hansen Holding A/S exemplifies the fermentation-platform archetype through microbial pigment development. These three entities represent distinct strategic postures: agricultural supply security, application-technical integration, and biotechnology-driven cost reduction.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Chr. Hansen Holding A/S |
| GNT Group B.V. |
| Döhler Group |
| FMC Corporation |
| DDW The Color House |
| Kerry Group plc |
| Givaudan S.A. |
| Others |
Supply Flow & Price Mechanics
Spirulina biomass costs cascade through three pricing tiers as extractors in India and Germany convert agricultural feedstock into UHT-stable phycocyanin concentrates. Supercritical CO2 energy inputs and FSSAI certification premiums separate premium pharmaceutical-grade extracts from commodity food-grade powders.
Pricing Analysis
Input-cost pass-through from agricultural yield volatility dominates pricing negotiations between Indian turmeric processors and Southeast Asian confectionery buyers. Three-tier pricing structure across premium, standard, and economy levels separates COSMOS-certified cosmetic dispersions from bulk food-grade powders. Pricing pressure stems from synthetic dye substitution economics in high-volume bakery applications. Food manufacturers exhibit highest price sensitivity; cosmetics formulators tolerate 3-4x markups for halal-certified liquid dispersions.
Supply Chain Analysis
Workforce availability constraints in German and Italian supercritical CO2 equipment fabrication extend lead times for extraction capacity expansion. Supply concentrates in India, Germany, and the Netherlands for botanical processing and fermentation platforms. Raw material dependencies include Gujarat turmeric harvests, Telangana spirulina cultivation, and Bavarian beetroot cooperatives. Single-source vulnerability concentrates in German engineering firms for high-pressure extraction systems. Distribution runs through direct technical service partnerships with mid-sized compounders bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FSSAI-certified Indian extraction capacity and REACH-regulated European formulation demand, with regulatory compliance cost differentials creating margin capture opportunities for cross-border suppliers.
For Market Incumbents: Extend fermentation-based pigment platforms to bypass agricultural weather risk while synthetic dye bans tighten across EU member states. Deepen backward integration into captive spirulina cultivation in Telangana and annatto orchards in Brazil to secure feedstock against climate-driven harvest variance. Prioritize EFSA novel food approval investments over FDA pathways to accelerate European commercial deployment. For New Entrants and Emerging Players: Launch via direct-to-formulator distribution partnerships with mid-sized Dutch and German cosmetics compounders seeking technical stabilization support. Target Brazilian meat and dairy processors ahead of ANVISA clean-label guidance finalization. White-space exists in microbial-derived beta-carotene for kosher and halal-certified applications where agricultural supply chains face certification gaps. For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation ventures because capital intensity barriers and regulatory approval timelines deter fragmented competition. Five-to-ten-year viability hinges on microbial pigment platforms achieving price parity with synthetic alternatives in beverage applications. Acquisition targets include FSSAI-certified Indian extractors with established Southeast Asian offtake relationships. Watch EFSA-FDA approval asynchrony for microbial pigments as inflection indicator for regional inventory fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | GNT Group's controlled agricultural partnerships for beetroot and spirulina secure supply against climate volatility. |
| Precision Fermentation Platform Scale-Up | Chr. Hansen's microbial pigment production collapses traditional agricultural supply chain cost structures. |
| Direct Technical Service Partnerships | Bypassing distributors captures margin from mid-sized cosmetics compounders in Nordic private-label markets. |
| FSSAI Certification Expansion | Indian processors reduce Southeast Asian confectionery import dependence on European REACH-regulated suppliers. |
| EFSA Novel Food Approval Prioritization | Faster regulatory pathways in the Netherlands enable earlier commercial deployment than FDA-equivalent timelines. |
Methodological Framework
Bottom-up beverage and cosmetics formulation modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with extraction plant managers, cosmetics formulators, FSSAI regulatory affairs leads, and Dutch dairy alternative procurement officers combined with secondary validation from EU REACH registration databases, FDA color additive filings, FSSAI certification records, and Indian customs export data. Triangulation between supply-side capacity announcements and demand-side procurement specifications ensures consistency.
Input-output matrix framing connects spirulina biomass availability, supercritical CO2 equipment installation rates, and end-use formulation demand across product type, application, and customer type dimensions. CAGRs derive from segment-level volume trajectories calibrated against historical substitution patterns from synthetic to natural colorants. Industry-specific forecast inputs include EFSA re-evaluation timelines for titanium dioxide and ANVISA clean-label guidance progression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under asynchronous FDA-EFSA microbial pigment approvals and extreme climate events affecting Indian turmeric harvests. Forecasts reflect documented assumptions regarding regulatory pathway timelines and extraction technology cost curves. Material deviation in EFSA titanium dioxide prohibition enforcement or German supercritical CO2 equipment lead times warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market