
 Middle East and Africa Hair Colorants Market | 2026-2036
Middle East and Africa Hair Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hair Colorants Market Foresight
The gap between salon-grade permanent color and mass-market temporary rinses is realigning how manufacturers allocate formulation budgets and distribution resources. L'Oréal S.A. anchors its regional position through professional education programs that lock in stylist loyalty across Moroccan and Egyptian salon networks. Henkel AG & Co. KGaA competes aggressively on ammonia-free permanent lines that command shelf space in Saudi Arabian hypermarkets.
Hair colorants are oxidative or direct dye systems formulated with alkalizing agents, coupling intermediates, and conditioning polymers that deposit or lift pigment within the hair cortex. Permanent formulations rely on ammonia or MEA to swell cuticles and enable developer penetration, while temporary variants coat the shaft without altering internal structure. Semi-permanent color types capture expanding share among first-time users seeking lower commitment, whereas salon professionals drive volume for permanent products that require technical application expertise. Sachet packaging dominates rural and price-sensitive segments across East Africa, contrasting with bottle formats preferred by urban retailers stocking premium fashion shades.
South Africa's national cosmetics regulator and Saudi Arabia's SFDA enforce divergent ingredient disclosure standards that force reformulation for cross-border brands. Egypt's health ministry maintains separate import licensing for oxidative dyes containing paraphenylenediamine above threshold concentrations. Stakeholders must track how Gulf standardization initiatives reshape compliance costs versus the fragmented national regimes that currently protect local manufacturers.
Market Dynamics
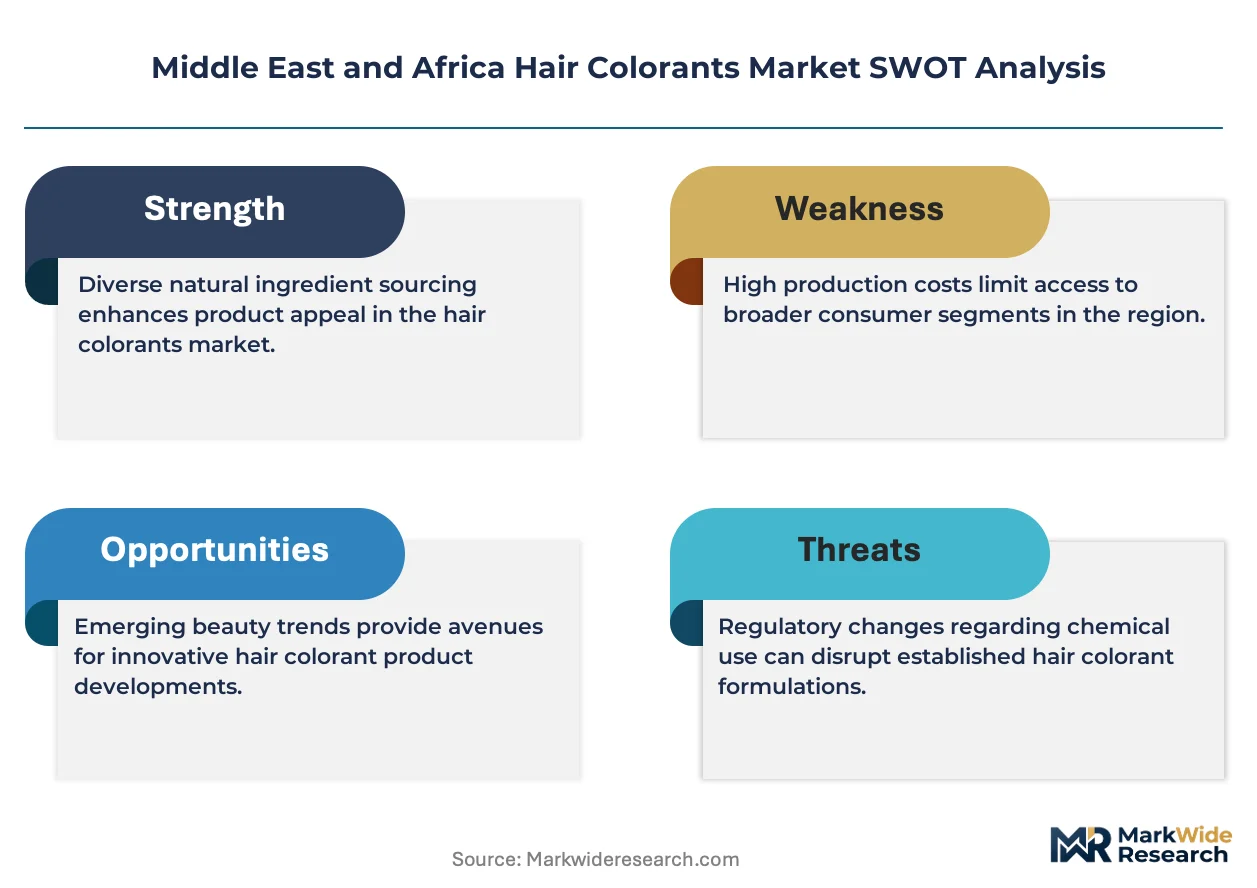
Ammonia-free formulation chemistry is redrawing competitive boundaries across Middle East and Africa hair colorants, forcing manufacturers to rebuild alkalizing agent supply chains while salon chains rewrite service protocols around gentler oxidative systems.
Growth Catalysts
- SFDA Ingredient Disclosure Mandates:Saudi Arabia's stricter labeling requirements for paraphenylenediamine concentrations are accelerating reformulation investments that favor established suppliers with regulatory affairs capabilities.
- Urban Salon Density:Lagos and Nairobi professional color service expansion is creating concentrated demand nodes for permanent oxidative systems requiring technical application training.
- MEA-Based Alkalizing Chemistry:Monoethanolamine (MEA) substitution programs are expanding manufacturing capacity for ammonia-free permanent colorants across Moroccan production facilities.
Market Restraints
- Coupling Intermediate Cost Volatility:Resorcinol and m-phenylenediamine price fluctuations from Asian bulk chemical suppliers compress margin structures for regional formulators.
- Import Licensing Fragmentation:Egypt's separate Ministry of Health import permits for high-PPD oxidative dyes create cross-border shipment delays that advantage local Egyptian manufacturers.
- Water-Based Temporary Rinse Substitution:Low-commitment direct dyes threaten semi-permanent oxidative volume among first-time color users in price-sensitive East African segments.
Strategic Opportunities
- Ethiopian Urban Penetration:Addis Ababa's underserved professional salon channel offers white space for ammonia-free permanent lines with localized shade palettes targeting Afro-textured hair.
- UAE Green Building Codes:Dubai's sustainable procurement guidelines for hospitality sector spas are creating regulatory tailwinds for plant-derived direct dye systems in professional settings.
- Sachet-to-Bottle Channel Migration:Kenyan retail networks are experimenting with premium bottle formats for fashion shades, displacing rural sachet dominance in Nairobi and Mombasa.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists trained in oxidative dye coupling chemistry limits regional R&D capacity for custom shade development.
- SFDA-Egypt MOH Regulatory Divergence:Incompatible ingredient threshold standards force dual stock-keeping units that complicate inventory planning for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hair Colorants Market |
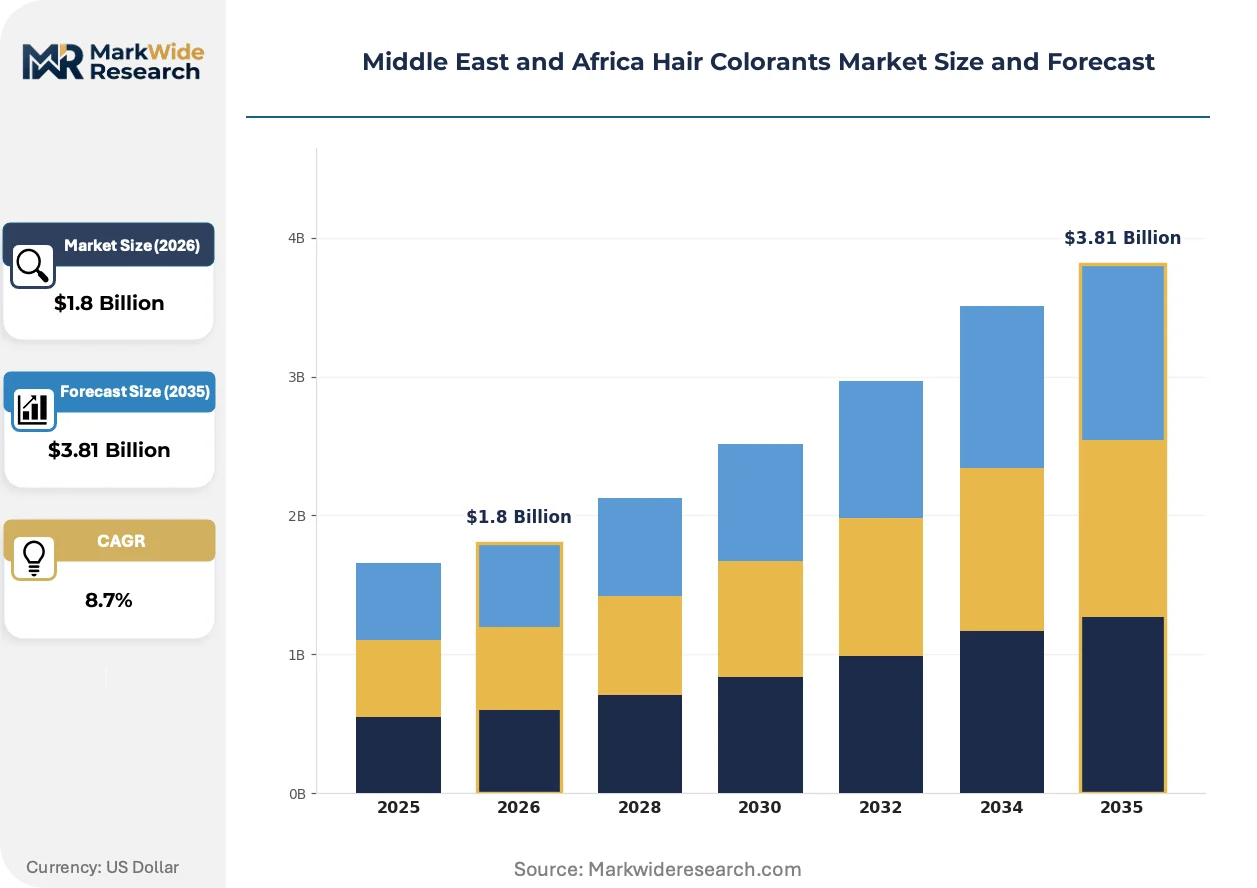
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Semi-Permanent, Temporary, Hair Mascaras Packaging Type: Tubes, Bottles, Sachets, Jars End User: Individuals, Salons, Retailers, Professionals Color Type: Natural, Fashion, Shades, Highlights |
| Companies Covered | L'Oréal S.A., Henkel AG & Co. KGaA, Kao Corporation, Coty Inc., Revlon, Inc., Avon Products, Inc., Hoyu Co., Ltd., Unilever PLC, Procter & Gamble Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hair Colorants Market Shifts & Advancements
Reformulation chemistry and distribution infrastructure are simultaneously reshaping how colorant manufacturers access professional and retail buyers across the Middle East and Africa, with regulatory compliance emerging as a technical differentiator rather than a cost center.
Ammonia-free permanent color technology is expanding into professional salon networks as Moroccan and Egyptian training academies prioritize MEA-based systems that reduce scalp irritation during lift procedures. Stylists in Casablanca and Cairo are completing manufacturer-sponsored certification programs at accelerating rates. This capability transfer is expanding into mid-tier salon chains that previously relied on temporary or semi-permanent services, compressing the addressable market for direct dye-only suppliers.
South Africa's updated Consumer Protection Act cosmetics labeling standards are forcing reformulation cycles for oxidative dyes containing sensitizing intermediates, with the national cosmetics regulator now requiring quantitative disclosure of paraphenylenediamine percentages above 0.1% concentration. Manufacturers serving both South African and Saudi Arabian markets face parallel but non-identical disclosure thresholds. Professional-only brands are responding by segmenting retail and salon SKUs with divergent ingredient decks, while mass-market players consolidate around the strictest common denominator.
Salon chain procurement consolidation is compressing supplier relationships in Nigeria's urban corridors, with Lagos-based multi-location operators centralizing colorant purchasing through designated technical distributors. Independent stylists in Ibadan and Abuja are losing direct manufacturer access as volume aggregates toward certified salon networks. This concentration pattern is most visible in permanent color categories where technical support and shade-mixing training create switching costs that lock in supplier relationships across 12-24 month contract cycles.
Middle East and Africa Hair Colorants Market Segmentation
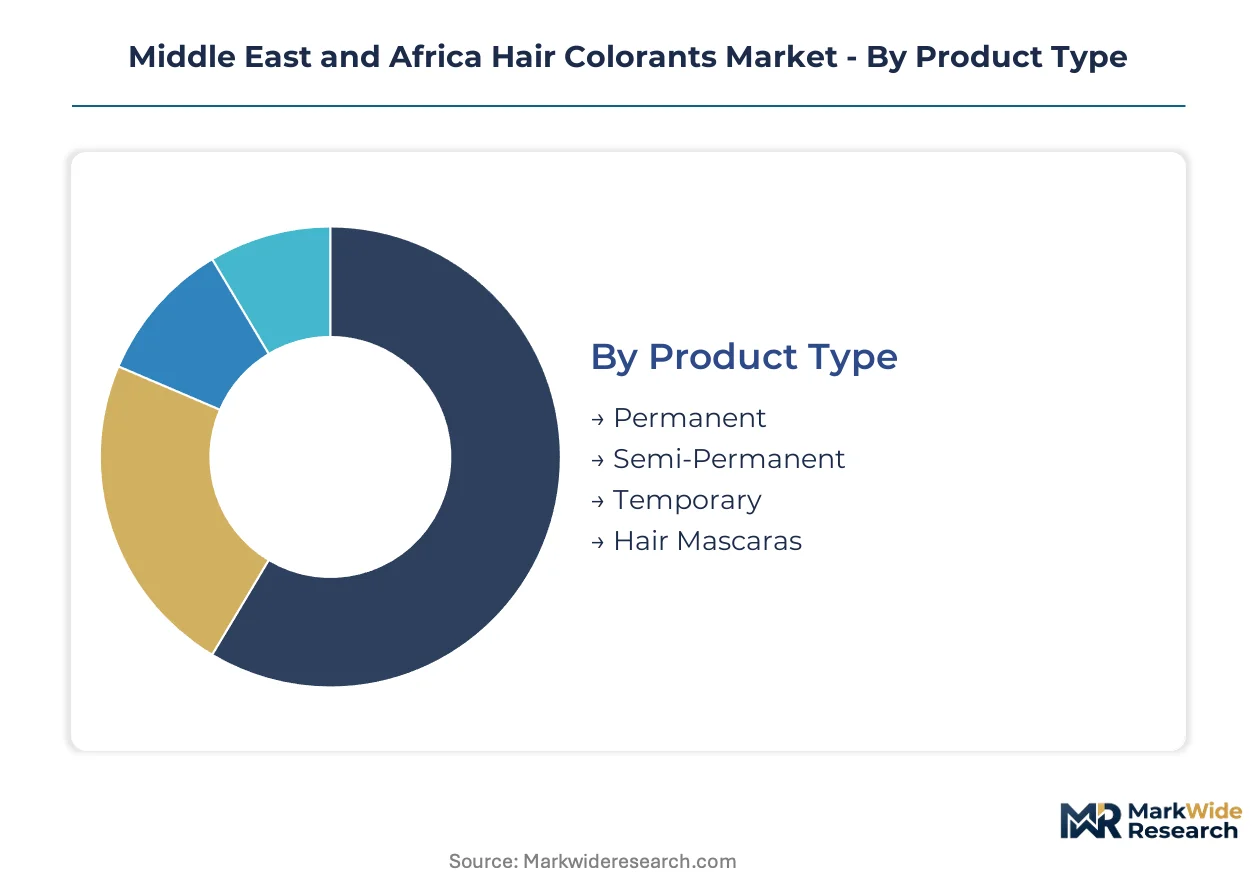
Hair colorant manufacturers in the Middle East and Africa allocate R&D budgets across formulation permanence levels and packaging formats that match divergent purchasing power between urban salon networks and rural retail channels. Segment-level profitability hinges on alkalizing agent chemistry choices and regulatory compliance investments that vary sharply across national borders.
Product Type:
Volume concentrates in permanent oxidative systems that command premium pricing through technical application requirements, while semi-permanent variants capture first-time users seeking lower commitment thresholds.
- Permanent:Ammonia or MEA-based formulations swell hair cuticles to enable developer penetration and lasting pigment deposition within the cortex. Lagos and Nairobi salon chains drive concentrated demand for these systems as they expand technical color service menus and require manufacturer-backed stylist certification programs.
- Semi-Permanent:Direct dye systems coat the hair shaft without internal structural alteration, offering 4-12 week color retention. Younger demographics in Nigeria's urban centers experiment with fashion color palettes through these lower-commitment options, displacing some permanent volume among entry-level users.
- Temporary:Surface-coating rinses that wash out in 1-3 shampoos dominate price-sensitive East African rural segments distributed through sachet packaging.
- Hair Mascaras:Precision applicator formats target root touch-up and streak applications for special occasion use in Gulf urban markets.
Mature deployment sits with Permanent formulations. Newer deployment is concentrated in Semi-Permanent variants.
Packaging Type:
Format selection tracks channel infrastructure maturity and per-capita purchasing power across the region's fragmented retail landscape.
- Tubes:Squeeze formats dominate professional salon backbars where precise portion control matters for custom shade mixing. Moroccan and Egyptian training academies specify tube formats for MEA-based permanent lines.
- Bottles:Flip-cap and pump dispensers anchor urban retail shelves in Nairobi and Mombasa as Kenyan networks experiment with premium fashion shade positioning.
- Sachets:Single-use foil packets capture rural East African volume through price points accessible to informal retail channels.
- Jars:Wide-mouth containers serve professional colorists requiring bulk access to lightening powders and developer creams.
Volume leadership belongs to Sachets. Premium positioning is climbing fastest in Bottles.
End User:
Customer type determines technical support requirements and contract structures that reshape manufacturer distribution investments.
- Individuals:Home application consumers purchasing through mass retail and e-commerce channels. South Africa's updated Consumer Protection Act labeling mandates force these buyers toward quantitative PPD disclosure awareness.
- Salons:Professional service providers in Casablanca and Cairo completing manufacturer-sponsored MEA-system certification at accelerating rates. These entities lock in 12-24 month supply contracts with technical distributors.
- Retailers:Hypermarket and pharmacy chains in Saudi Arabia stocking ammonia-free permanent lines for self-selection by informed consumers.
- Professionals:Freelance stylists losing direct manufacturer access as Lagos-based multi-location operators centralize procurement through designated distributors.
Contract concentration is shifting toward Salons. Direct manufacturer access is fragmenting fastest among Professionals.
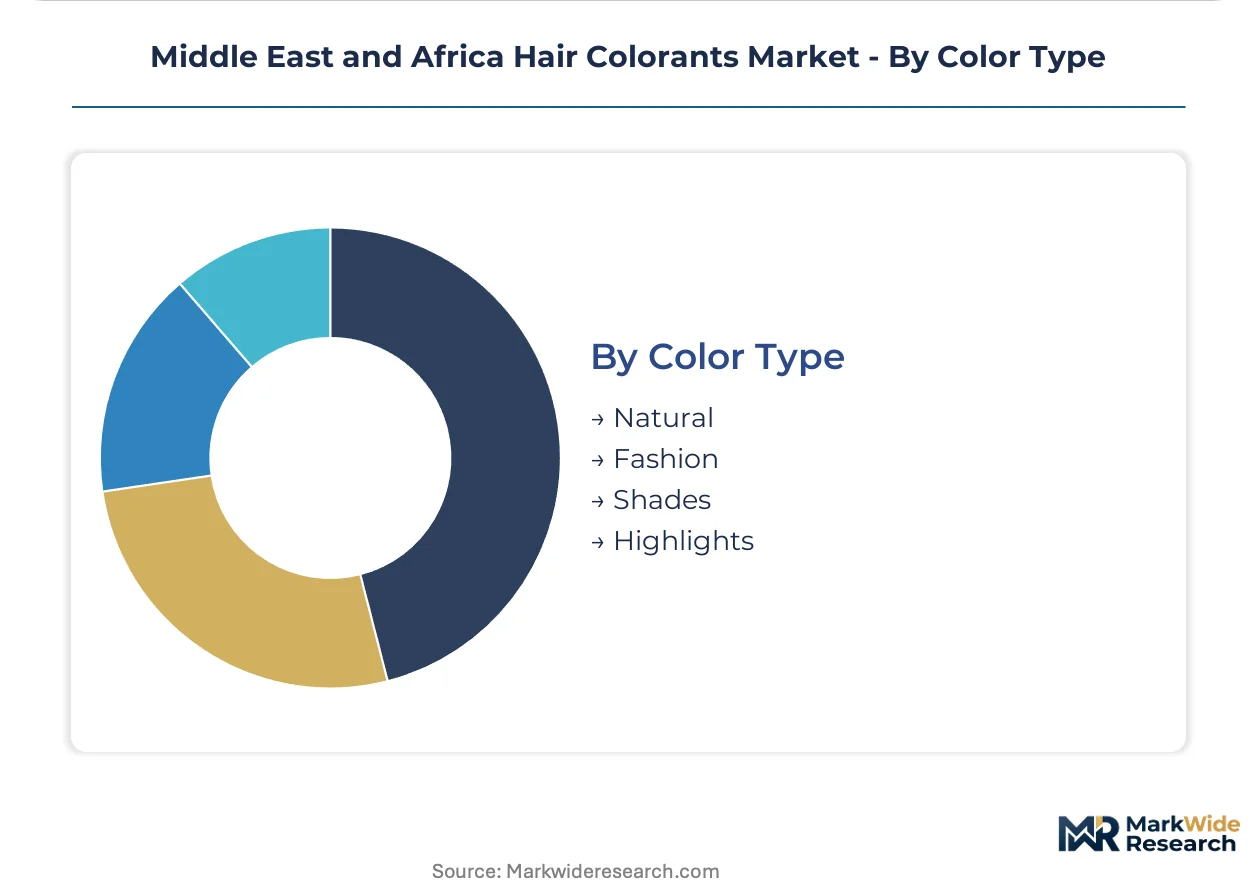
Color Type:
Shade portfolio strategy must reconcile chemical formulation constraints with cultural and demographic preferences across Afro-textured and diverse hair types.
- Natural:Black, brown, and blonde variants matching or subtly altering native hair color. These shades dominate permanent oxidative volume in Moroccan and Egyptian salon networks where coverage of gray hair drives repeat purchase cycles.
- Fashion:Vivid reds, coppers, purples, and unconventional tones requiring pre-lightening and technical expertise. Addis Ababa's underserved professional channel offers white space for localized fashion shade palettes targeting Afro-textured hair.
- Shades:Systematic color families enabling custom mixing and gradual tonal shifts within the natural spectrum.
- Highlights:Foil and cap techniques requiring specialized lightening products and application training concentrated in premium salon tiers.
Volume foundation rests with Natural tones. Steepest expansion trajectory is visible in Fashion colors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors demand concentration across the Middle East and Africa hair colorants landscape, with professional salon chains in Nigeria's commercial capital driving volume for permanent oxidative systems and setting procurement patterns that radiate toward Ibadan and Abuja.
Saudi Arabia
Riyadh and Jeddah salon networks are expanding ammonia-free service menus as consumer sensitivity to scalp irritation rises. The Saudi Food and Drug Authority enforces stricter paraphenylenediamine disclosure thresholds that accelerate reformulation investments. Eastern Province manufacturing clusters near Dammam are scaling MEA-based alkalizing agent production to serve Gulf export markets.
South Africa
Johannesburg and Cape Town professional channels are consolidating procurement through designated technical distributors. The national cosmetics regulator enforces updated Consumer Protection Act labeling standards requiring quantitative PPD percentages above 0.1% concentration. Gauteng-based training academies are certifying stylists on gentler oxidative systems at accelerating rates.
Egypt
Cairo's salon chains are rewriting service protocols around MEA-based permanent colorants as manufacturer-sponsored certification programs expand. The Ministry of Health maintains separate import licensing for high-PPD oxidative dyes that creates cross-border shipment delays. Alexandria and Nile Delta manufacturing facilities benefit from protected domestic market access.
Nigeria
Lagos-based multi-location operators are centralizing colorant purchasing through volume-aggregated contracts with technical distributors. Younger demographics in urban centers experiment with fashion color palettes through semi-permanent direct dyes. Ibadan and Abuja independent stylists are losing direct manufacturer access as procurement concentrates toward certified salon networks.
United Arab Emirates
Dubai's hospitality sector spas are adopting plant-derived direct dye systems under sustainable procurement guidelines tied to green building codes. Abu Dhabi retail channels stock ammonia-free permanent lines for self-selection by informed consumers. Sharjah distribution hubs serve as re-export nodes for Gulf Cooperation Council markets.
Middle East and Africa Hair Colorants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and regulatory compliance capabilities, with established suppliers capturing salon loyalty through technical education investments while mass-market competitors compete on sachet pricing in rural East Africa. The vendor base organizes around three archetypes: multinational beauty conglomerates with professional education infrastructure, regional specialists in ammonia-free alkalizing chemistry, and price-focused formulators serving informal retail channels. Dominant competitive moves include portfolio diversification into MEA-based permanent lines and strategic partnerships with salon chain procurement consolidators.
Within the multinational tier, L'Oréal S.A., Henkel AG & Co. KGaA, and Kao Corporation occupy positions that exemplify divergent strategic emphases. The Paris-based S.A. structure anchors professional education programs across Moroccan and Egyptian salon networks. The Düsseldorf-based KGaA competes on ammonia-free permanent formulations commanding shelf space in Saudi Arabian hypermarkets. The Japanese Corporation represents Asian-origin investment in regional manufacturing capacity for oxidative dye systems.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Coty Inc. |
| Revlon, Inc. |
| Avon Products, Inc. |
| Hoyu Co., Ltd. |
| Unilever PLC |
| Procter & Gamble Company |
| Others |
Supply & Pricing Matrix
Salon chain procurement consolidation in Lagos and Nairobi is forcing manufacturers to restructure volume discount frameworks and technical service bundling, compressing margin structures for suppliers unable to anchor long-term training contracts. This buyer-side concentration shifts pricing power toward certified distributor networks while squeezing independent stylists into higher per-unit costs.
Pricing Analysis
Stylist certification outcomes anchor value-based pricing for permanent oxidative systems, with manufacturers commanding premium positioning through 12-24 month technical education contracts. Price differentiation rests on MEA-based formulation chemistry and SFDA compliance tier, separating salon-grade lines from mass-market sachet alternatives. Cost compression in East African rural segments is intensifying because direct dye substitution threatens semi-permanent oxidative volume. Independent professionals in Ibadan and Abuja face acute price sensitivity, whereas Lagos-based multi-location operators leverage volume aggregation for preferential terms.
Supply Chain Analysis
Direct-to-salon channels handle professional-grade demand through certified distributor networks in Nigeria and Kenya, while mass retail flows through hypermarket and pharmacy chains in Saudi Arabia and South Africa. Manufacturing concentration sits with Morocco, Egypt, and Saudi Arabia's Eastern Province production clusters. Raw material dependencies draw from Asian bulk chemical suppliers for resorcinol and m-phenylenediamine coupling intermediates. Single-source vulnerability for alkalizing agent precursors creates exposure to import licensing fragmentation. Distribution runs through Sharjah re-export hubs serving Gulf Cooperation Council markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with divergent SFDA and Egyptian MOH standards forcing dual-SKU investments that weaker formulators cannot absorb.
For Market Incumbents: Cement salon loyalty through exclusive MEA-system certification academies in Casablanca and Cairo, locking in 12-24 month supply contracts before procurement consolidation accelerates. Deepen backward integration into Moroccan alkalizing agent production to offset resorcinol cost volatility from Asian suppliers. Prioritize regulatory affairs staffing to manage parallel South African and Saudi disclosure thresholds without SKU proliferation. For New Entrants and Emerging Players: Plant-derived direct dye chemistry offers white-space entry into Dubai's hospitality spa sector under green building procurement guidelines. Target Addis Ababa's underserved professional channel with localized fashion shade palettes formulated for Afro-textured hair. Pursue technical distributor partnerships rather than direct salon relationships to bypass Lagos procurement consolidation barriers. For Investors and Strategic Acquirers: Re-rating potential sits with regional ammonia-free formulation specialists given accelerating MEA substitution programs and salon certification expansion. Long-term viability favors manufacturers with captive alkalizing agent supply and regulatory affairs infrastructure spanning multiple national jurisdictions. Watch for Egyptian MOH import licensing relaxation as a signal for cross-border volume consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| MEA-Based Formulation Scale-Up | Moroccan production facilities capture salon demand shifting from ammonia systems. |
| Certified Distributor Partnerships | Lagos and Nairobi salon chains lock in supply relationships through technical training contracts. |
| Regulatory Affairs Investment | Dual compliance with SFDA and Egyptian MOH thresholds protects cross-border market access. |
| Localized Shade Development | Addis Ababa fashion color portfolios address underserved Afro-textured hair segments. |
| Sustainable Procurement Positioning | Dubai green building codes create channel access for plant-derived direct dye systems. |
Research Methodology
Independent corroboration across formulation chemists at Moroccan and Egyptian training academies, procurement managers at Lagos-based salon chains, and regulatory affairs leads at manufacturers serving Saudi and South African markets underwrites the qualitative findings. Secondary validation draws from SFDA disclosure filings, Egyptian Ministry of Health import licensing records, South African Consumer Protection Act cosmetics standards, and regional trade flow data. Bottom-up salon density estimates and top-down formulation production capacity triangulate market sizing.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, modeling permanence level, packaging format, end-user type, and color category as core segmentation dimensions. CAGRs were derived from iterative reconciliation of salon service expansion rates, sachet-to-bottle channel migration patterns, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate MEA substitution program timelines and urban salon density trajectories in Lagos, Nairobi, and Addis Ababa.
Several conditions sit outside the modeled scope, including potential harmonization of Gulf Cooperation Council cosmetics standards and abrupt shifts in Egyptian import licensing enforcement. Forecasts reflect assumptions about sustained stylist certification adoption and stable alkalizing agent supply from Moroccan manufacturing clusters. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Plastic Color Concentrates Market