
 Fatty Methyl Ester Sulfonate Market | 2026-2036
Fatty Methyl Ester Sulfonate Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Methyl Ester Sulfonate Market Analysis
Specialized oleochemical process engineers is rotating toward Asia-Pacific production hubs, tightening talent availability for European and North American facilities. Stepan Company leverages backward integration into renewable feedstocks to secure margin stability across detergent-grade output. KLK OLEO anchors its position through palm oil supply chain control in Malaysia, while Lion Corporation dominates powder-form manufacturing for Japanese and export household markets.
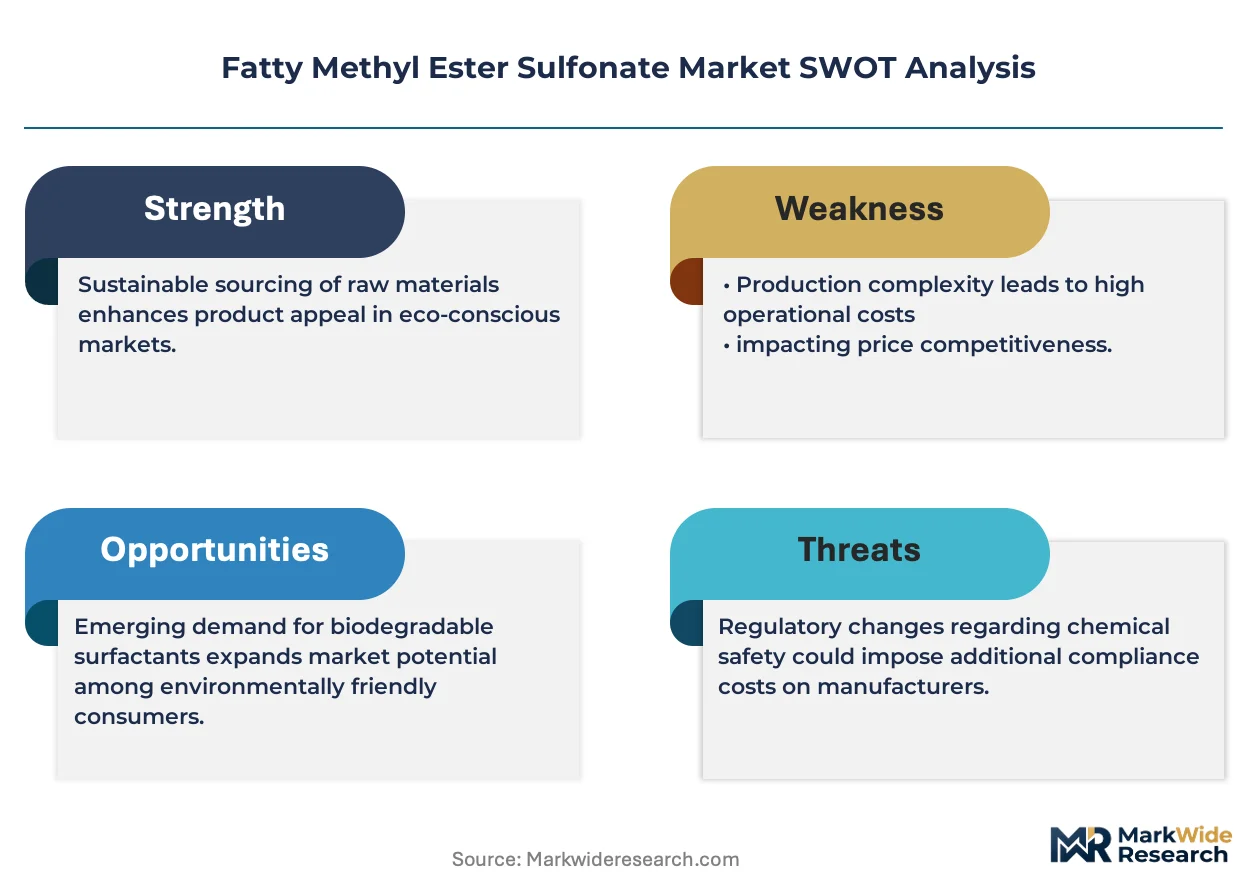
Fatty methyl ester sulfonate denotes an anionic surfactant synthesized via sulfonation of fatty acid methyl esters, typically yielding C16-C18 alkyl chain lengths with active matter concentrations between 80% and 90% in commercial paste or powder grades. The compound functions primarily as a biodegradable foaming and cleansing agent in laundry detergents, dishwashing liquids, and personal care formulations, substituting for petroleum-derived linear alkylbenzene sulfonates in eco-conscious product lines. Liquid concentrates command premium positioning in industrial cleaning contracts where dilution flexibility reduces freight costs, while powder grades sustain volume leadership in mass-market household detergents across South Asian and African distribution networks. Emulsifier-grade specifications occupy narrower but higher-margin niches in agricultural adjuvant formulations.
EPA Safer Choice standards and REACH Annex XVII restrictions on hazardous surfactant residues are elevating bio-based anionic chemistry specifications across detergent supply chains. BIS certification requirements in India and Ecolabel criteria in EU member states further differentiate market access tiers for imported versus domestically produced fatty methyl ester sulfonate grades. Stakeholders must monitor feedstock volatility in palm kernel and coconut oil markets alongside evolving biodegradability test protocols to align capacity planning with regulatory compliance timelines.
Market Dynamics
Feedstock concentration in Malaysian and Indonesian palm oil estates is compressing margin structures for European and North American formulators who lack backward integration into oleochemical supply chains.
Growth Catalysts
- REACH Annex XVII restrictions:Hazardous surfactant residue limits in the European Union are accelerating substitution of petroleum-derived linear alkylbenzene sulfonates with biodegradable fatty methyl ester sulfonate grades in laundry detergent formulations.
- Powder detergent manufacturing:Household cleaning product lines across South Asian distribution networks are expanding production capacity for high-alkalinity powder grades that leverage C16-C18 chain length compatibility with regional washing habits.
- EPA Safer Choice certification:Industrial cleaning contract specifications in the United States are mandating bio-based anionic surfactant content for federal procurement eligibility, creating specification pull-through to commercial janitorial supply chains.
Market Restraints
- Palm kernel oil volatility:Weather-driven supply disruptions in Malaysian estates transmit directly to fatty acid methyl ester feedstock pricing, destabilizing cost structures for non-integrated sulfonation facilities.
- Technical performance ceiling:Cold-water dissolution kinetics of powder-grade fatty methyl ester sulfonate lag petroleum-derived alternatives in sub-15°C wash cycles, limiting penetration in Nordic household markets.
- Substitution by alkyl polyglucosides:Non-ionic sugar-based surfactants are capturing share in premium personal care formulations where mildness claims outweigh anionic foaming performance requirements.
Strategic Opportunities
- Agricultural adjuvant specifications:Emulsifier-grade fatty methyl ester sulfonate with enhanced electrolyte tolerance is penetrating crop protection formulation markets in Brazil where ANVISA bio-based mandates are tightening.
- EU Green Deal bio-surfactant procurement:Public sector cleaning contracts across German and French municipal authorities are introducing minimum renewable carbon content thresholds that favor oleochemical-derived anionic chemistry.
- Liquid concentrate industrial channels:Dilution-flexible paste grades are displacing pre-formulated products in North American commercial cleaning supply chains where freight cost reduction drives purchasing decisions.
Industry Challenges
- Sulfonation process engineering talent:Specialized oleochemical reactor operators are migrating to Asia-Pacific production hubs, constraining European facility expansion timelines and technical service capabilities.
- BIS certification timelines:Indian domestic manufacturing requirements for imported surfactant grades are extending product registration cycles, delaying market entry for new supply sources.
- Legacy detergent formulation integration:Powder-grade fatty methyl ester sulfonate compatibility with existing spray-drying tower configurations requires capital retrofit investment that mid-scale formulators defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Methyl Ester Sulfonate Market |
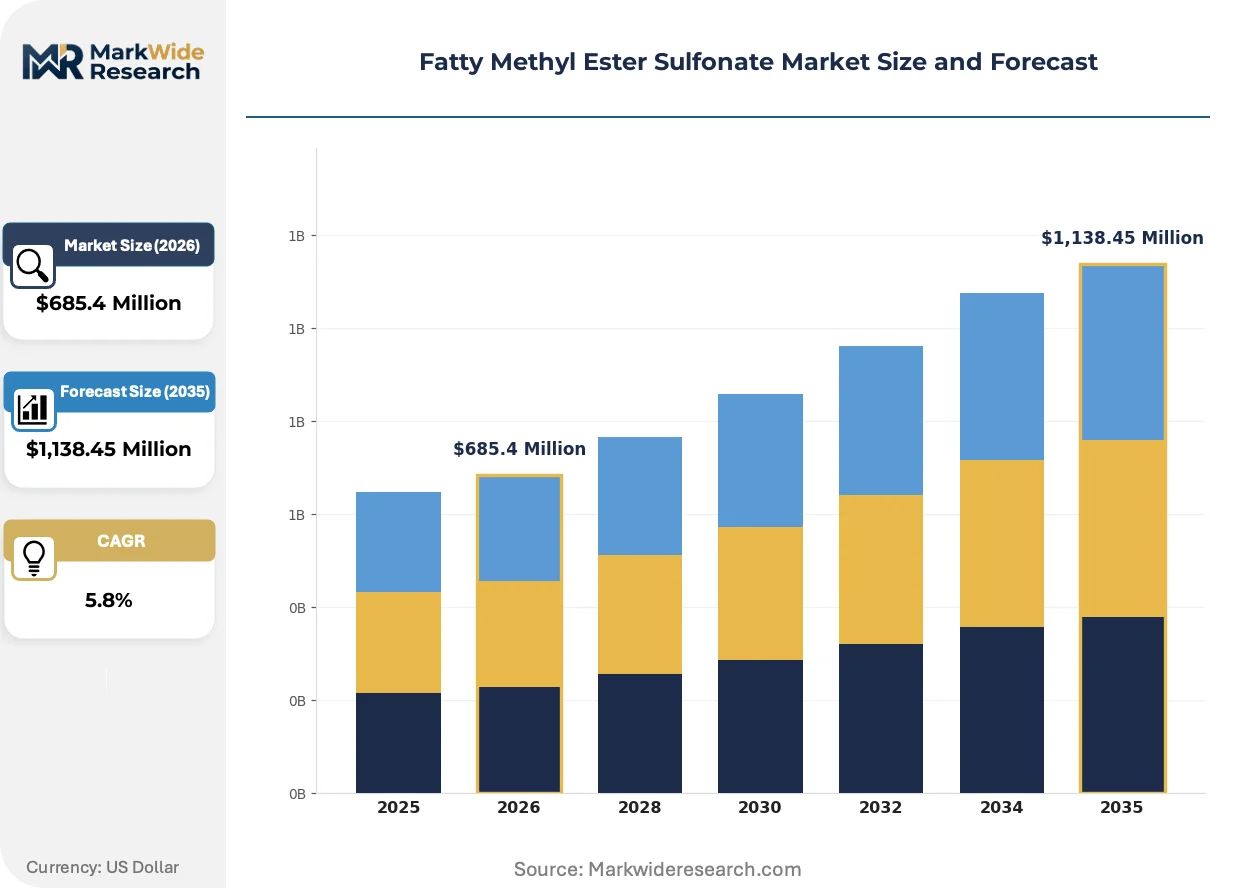
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Detergents, Emulsifiers, Solvents Application: Household Cleaning, Personal Care, Industrial Cleaning, Agriculture End User: Manufacturers, Distributors, Retailers, Service Providers Form: Liquid, Powder, Concentrate, Granule |
| Companies Covered | Stepan Company, Zanyu Technology Group Co., Ltd., KLK OLEO, FENCHEM, Emery Oleochemicals, Wilmar International Ltd, Chemithon Corporation, KPL International Limited, Lion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Methyl Ester Sulfonate Market Emerging Trajectories
Formulation chemistry is splitting along temperature-performance axes as regional wash habits diverge, while regulatory carbon accounting penetrates procurement specifications.
Continuous sulfonation reactor technology is bifurcating the production landscape between high-throughput paste manufacturers and batch-oriented powder-grade specialists. Detergent formulators in Japan and South Korea are adopting liquid concentrate intermediates for flexible dilution protocols. This technology is compressing the traditional powder-liquid volume ratio in industrial cleaning contracts while enabling just-in-time inventory models.
ECHA guidance on persistent organic pollutant screening is elevating biodegradability test protocol stringency for surfactant imports into European Union member states. Formulators must now document primary and ultimate biodegradation kinetics under OECD 301B standards to maintain REACH compliance. Powder detergent brands with mass-market positioning in Germany and the Netherlands are reformulating to meet tightened aquatic toxicity thresholds ahead of 2027 regulatory review cycles.
Certification-driven specification is displacing price-first procurement in institutional cleaning contracts across North American healthcare and education sectors. Buyers now require EPA Safer Choice or Green Seal verification before technical evaluation, compressing supplier qualification pools. This pattern concentrates sourcing decisions among vertically integrated oleochemical producers with in-house toxicology documentation capabilities.
Fatty Methyl Ester Sulfonate Market Segmentation
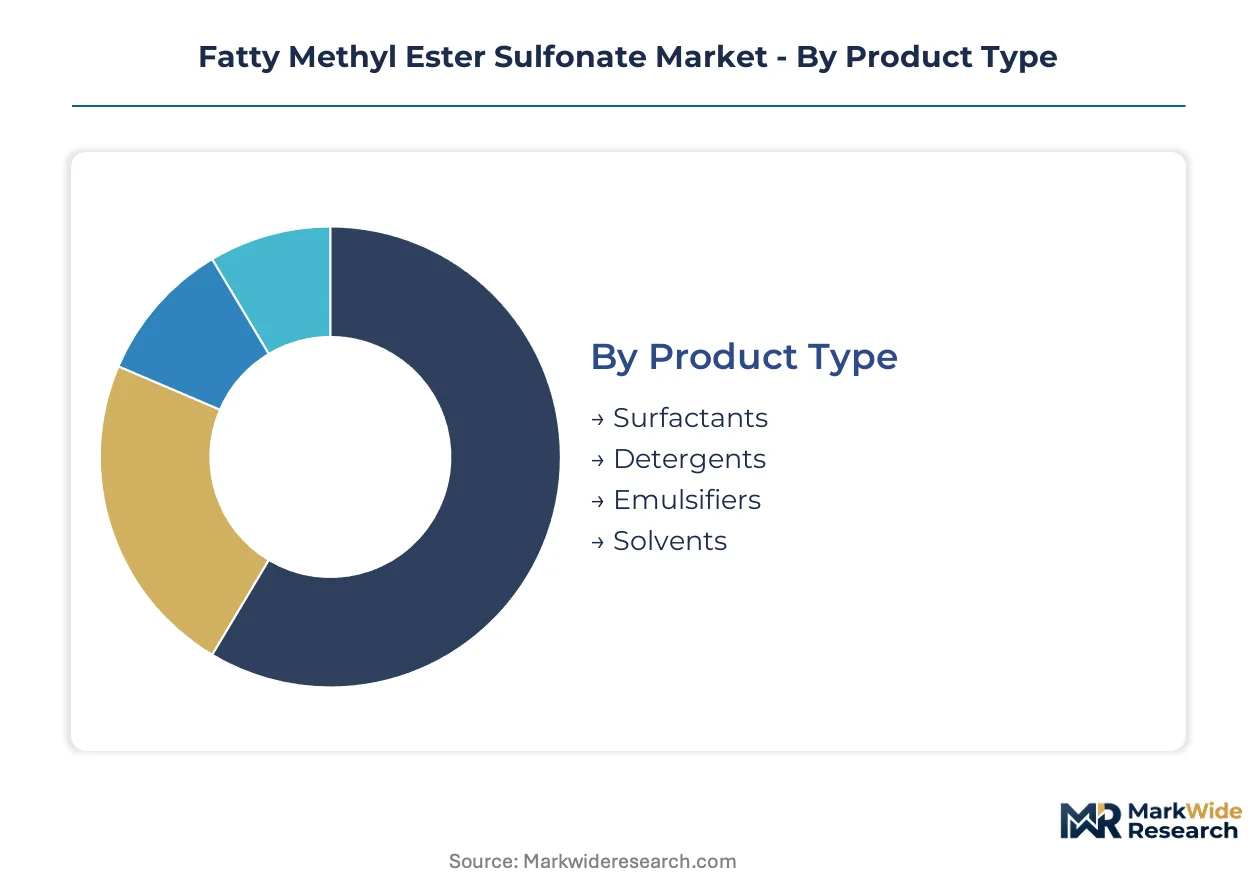
Segmentation in fatty methyl ester sulfonate reveals where substitution pressure concentrates and where formulation chemistry creates defensive moats. Product type and application splits expose vulnerability to alkyl polyglucoside incursion, while form and end-user dimensions illuminate margin capture opportunities.
Product Type:
Surfactant-grade segments face the most acute substitution threat from sugar-based non-ionics in personal care channels, while detergent and emulsifier grades defend position through performance specifications that bio-based alternatives cannot yet match.
- Surfactants:Anionic foaming agents with C16-C18 alkyl chains dominate laundry powder formulations across South Asian distribution networks. Demand concentrates in mass-market household detergents where cost-performance ratios resist milder non-ionic substitutes.
- Detergents:High-alkalinity powder grades engineered for regional washing habits sustain volume leadership in Indian and African markets. Cold-water dissolution limitations in Nordic climates create a performance ceiling that petroleum-derived linear alkylbenzene sulfonates exploit.
- Emulsifiers:Electrolyte-tolerant specifications penetrate agricultural adjuvant markets in Brazil under ANVISA bio-based mandates.
- Solvents:Narrow industrial niches in metalworking fluid formulations where biodegradability requirements are tightening.
Detergent-grade retains volume leadership; emulsifier-grade holds the steepest expansion curve.
Application:
Cost tier stratification separates premium personal care positioning from commoditized industrial channels, with household cleaning occupying the contested middle ground where regulatory pull-through most directly shapes procurement.
- Household Cleaning:Powder detergent manufacturing across South Asian distribution networks leverages C16-C18 chain compatibility with regional washing habits. EPA Safer Choice and EU Ecolabel criteria are compressing supplier pools to vertically integrated oleochemical producers with in-house toxicology documentation.
- Industrial Cleaning:Liquid concentrate specifications displace pre-formulated products in North American commercial supply chains where freight cost reduction drives purchasing decisions. Dilution-flexible paste grades enable just-in-time inventory models that batch-oriented powder specialists cannot replicate.
- Personal Care:Mildness claims favor alkyl polyglucoside substitution in premium formulations, constraining anionic surfactant share to mass-market shampoo and body wash segments.
- Agriculture:Crop protection adjuvant specifications in Brazil demand enhanced electrolyte tolerance that fatty methyl ester sulfonate delivers against petroleum-derived alternatives.
Household cleaning commands the largest revenue base; industrial cleaning climbs fastest on specification-driven procurement.
End User:
Volume concentration among manufacturers with captive sulfonation capacity is squeezing independent distributors and service providers into narrower specification niches.
- Manufacturers:Vertically integrated detergent producers in Malaysia and Indonesia control feedstock-to-formulation economics that European and North American competitors cannot replicate.
- Distributors:Regional chemical traders face margin compression as direct procurement relationships between oleochemical producers and formulators bypass traditional wholesale channels.
- Retailers:Private-label household cleaning brands in German and French markets are introducing minimum renewable carbon content thresholds that favor certified bio-based surfactant grades.
- Service Providers:Commercial janitorial contractors in US healthcare and education sectors now require EPA Safer Choice verification before technical evaluation.
Manufacturers retain supply chain dominance; service providers represent the most specification-sensitive growth pocket.
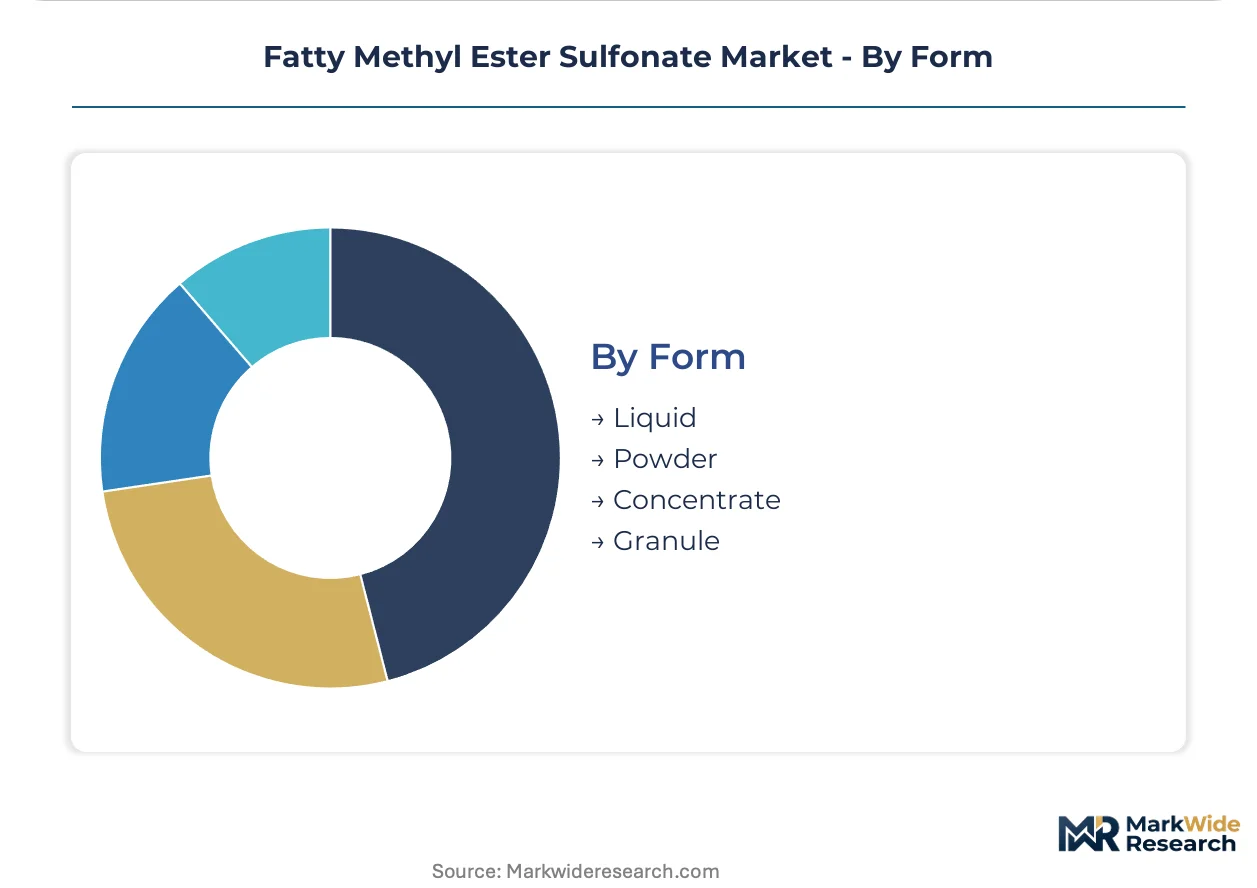
Form:
Supply concentration in Malaysian paste production hubs is forcing powder-grade specialists toward capital-intensive spray-drying retrofits or liquid concentrate pivots.
- Liquid:Concentrate intermediates enable flexible dilution protocols in Japanese and South Korean detergent manufacturing, compressing traditional powder-liquid volume ratios in industrial cleaning contracts.
- Powder:Mass-market household detergents across South Asian and African distribution networks sustain volume leadership despite cold-water dissolution limitations in sub-15°C wash cycles.
- Concentrate:Freight cost advantages in North American commercial cleaning supply chains drive displacement of pre-formulated products.
- Granule:Niche positioning in specialty agricultural formulations where controlled-release properties matter.
Powder sustains volume leadership; liquid concentrate captures the steepest share gains on logistics economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household detergent formulations in India and Southeast Asia favor high-alkalinity powder grades, while Japanese and South Korean manufacturers pivot toward liquid concentrate intermediates. European procurement specifications emphasize renewable carbon content thresholds under EU Green Deal mandates. North American industrial cleaning contracts prioritize freight-cost reduction through dilution-flexible paste grades.
India
Mass-market laundry powder manufacturing concentrates demand for C16-C18 chain surfactants compatible with regional washing habits. BIS certification requirements for imported grades extend registration cycles, delaying new supply source entry. Manufacturing clusters in Gujarat and Maharashtra house domestic sulfonation facilities serving South Asian distribution networks.
Malaysia
Palm oil supply chain control anchors regional oleochemical production economics for detergent-grade output. Malaysian estates transmit weather-driven supply disruptions directly to fatty acid methyl ester feedstock pricing. Klang Valley production hubs concentrate backward-integrated sulfonation capacity serving export markets.
Germany
Municipal cleaning contracts introduce minimum renewable carbon content thresholds favoring bio-based anionic chemistry. ECHA guidance elevates biodegradability test protocol stringency under OECD 301B standards for surfactant imports. Industrial clusters along the Rhine corridor formulate powder detergents to tightened aquatic toxicity thresholds ahead of 2027 regulatory reviews.
United States
Federal procurement eligibility mandates bio-based anionic surfactant content under EPA Safer Choice certification, pulling specification through commercial janitorial supply chains. Healthcare and education sector buyers require Green Seal verification before technical evaluation. Gulf Coast petrochemical corridors face margin pressure from oleochemical-derived substitutes in institutional cleaning contracts.
Brazil
Crop protection adjuvant specifications demand enhanced electrolyte tolerance that fatty methyl ester sulfonate delivers against petroleum-derived alternatives. ANVISA bio-based mandates tighten formulation requirements for agricultural applications. São Paulo state industrial zones concentrate emulsifier-grade production for Latin American export markets.
Fatty Methyl Ester Sulfonate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the current market structure. Malaysian and Indonesian palm oil estate control separates feedstock-integrated producers from formulation-dependent competitors. Three archetypes dominate: vertically integrated oleochemical majors with captive sulfonation capacity, regional powder-grade specialists serving mass-market household channels, and industrial concentrate formulators leveraging dilution-flexible logistics. Capacity expansion in Asia-Pacific hubs and certification-driven portfolio diversification constitute the primary competitive vectors reshaping positioning.
Within the integrated major tier, Stepan Company and KLK OLEO occupy positions defined by upstream control over renewable feedstock supply chains. Zanyu Technology Group Co., Ltd. exemplifies the Asia-Pacific production concentration that is drawing specialized process engineering talent away from European facilities. Lion Corporation anchors the powder-form manufacturing specialization serving Japanese household and export markets. These three represent distinct strategic postures: North American backward integration, Southeast Asian plantation-to-chemical verticality, and East Asian formulation-grade dominance.
| Leading Market Players |
|---|
| Stepan Company |
| Zanyu Technology Group Co., Ltd. |
| KLK OLEO |
| FENCHEM |
| Emery Oleochemicals |
| Wilmar International Ltd |
| Chemithon Corporation |
| KPL International Limited |
| Lion Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Malaysian oleochemical producers and European detergent formulators lock in feedstock access and price visibility across volatile palm oil cycles. These agreements insulate integrated players from spot market swings while exposing non-integrated buyers to margin compression when BIS certification delays extend procurement timelines.
Pricing Analysis
Contract-based long-term offtake dominates pricing structure for detergent-grade volumes, with differentiation driven by certification tier under REACH Annex XVII and volume scale commitments. Cost compression in powder-grade segments intensifies as Asian production hubs exploit captive palm oil supply economics. Mass-market household detergent manufacturers exhibit highest price sensitivity, while agricultural adjuvant formulators accept premium positioning for electrolyte-tolerant specifications.
Supply Chain Analysis
Port congestion at Klang Valley terminals and container availability constraints on Southeast Asia-to-Europe trade lanes elevate inbound logistics costs for non-integrated formulators. Supply concentrates in Malaysia, Indonesia, and India, with raw material dependencies on palm kernel oil, coconut oil, and methanol feedstocks. Single-source vulnerability around Malaysian estate production creates structural risk. Distribution runs through direct procurement relationships that bypass traditional chemical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: REACH compliance documentation and BIS certification timelines create switching costs that lock formulators into validated supplier relationships.
For Market Incumbents: Fortify backward integration into renewable feedstocks to secure margin stability against Asian plantation-to-chemical competitors. Expand sulfonation capacity in Gujarat and Maharashtra clusters to preempt import substitution under tightening Indian domestic manufacturing requirements. Prioritize EPA Safer Choice and EU Ecolabel certification maintenance to defend specification-driven procurement channels against emerging alkyl polyglucoside substitutes.
For New Entrants and Emerging Players: Technical service gaps in cold-water dissolution engineering for Nordic detergent formulators present white-space entry points. Target liquid concentrate industrial cleaning segments in North American commercial supply chains where freight cost reduction drives purchasing decisions and incumbent powder-grade specialists lack dilution-flexible logistics capabilities. Pursue toll manufacturing partnerships with established oleochemical producers to bypass capital-intensive sulfonation reactor investments.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated oleochemical majors with captive plantation supply and in-house toxicology documentation capabilities. Long-term viability hinges on feedstock security and regulatory compliance infrastructure rather than formulation chemistry alone. Watch ANVISA bio-based mandate enforcement in Brazil as inflection indicator for agricultural adjuvant specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Supply | KLK OLEO's plantation control secures margin stability against feedstock volatility. |
| Continuous Sulfonation Reactor Investment | High-throughput paste manufacturing displaces batch-oriented powder specialists in industrial channels. |
| REACH Annex XVII Compliance Certification | ECHA documentation requirements compress supplier pools to integrated producers with toxicology capabilities. |
| Liquid Concentrate Formulation Pivot | Japanese and South Korean manufacturers exploit dilution-flexible logistics to reduce freight costs. |
| Agricultural Adjuvant Specification Development | ANVISA bio-based mandates in Brazil open high-margin electrolyte-tolerant emulsifier markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, oleochemical industry association reports, and regulatory filing databases. Interviews with plant managers at sulfonation facilities, procurement leads at downstream detergent manufacturers, distribution channel partners, and technical R&D directors informed supply chain and pricing dynamics. Bottom-up volume triangulation across grade tiers and end-use segments was cross-validated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product grade tier, application channel, form specification, and regional production hub across the analysis window. CAGRs were derived from trend extrapolation of historical volume movements adjusted for regulatory compliance timelines and feedstock substitution patterns. Forecast inputs incorporated REACH Annex XVII implementation schedules and BIS certification processing rates.
Forecasts assume regulatory continuity in EU REACH, US EPA Safer Choice, and Indian BIS regimes; material policy shifts would require re-modeling. Palm kernel oil price volatility and sulfonation process engineering talent migration represent primary revision triggers. Recalibration cycles align with material shifts in bio-based surfactant procurement mandates and oleochemical capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Alkyl Polyglucosides Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Zeolite for Detergents Market
Surfactants
Alkylamines Market
Surfactants
Lauramide DEA Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Cetanol Market
Surfactants
Cetyl Chloride Market
Surfactants
Global Methyl Soyate Market