
 Europe Natural Dyes and Pigments Market | 2026-2036
Europe Natural Dyes and Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Natural Dyes and Pigments Market Intelligence
The premium-commodity divide in natural dyes and pigments is shifting as certified organic extracts command triple the price of conventional botanical powders while both categories expand volume. GNT Group B.V. leverages its vertical integration from agricultural sourcing to finished colorant to sustain margin capture across the value chain. Koninklijke DSM N.V. anchors its position through biotechnology-derived pigments that compete with traditional extraction methods on batch consistency.
Natural dyes and pigments comprise color-bearing substances derived from plant tissues, insect secretions, or mineral deposits, typically processed through aqueous extraction, fermentation, or controlled drying to achieve specified tinctorial strength and lightfastness ratings for industrial application. Their primary commercial purpose centers on replacing petroleum-derived colorants in consumer-facing products where regulatory and brand sustainability pressures intensify. The application dimension shows textiles occupying the deepest volume pool while cosmetics extracts represent the fastest margin expansion as formulation complexity rises. Product type segmentation reveals pigments consolidating share among industrial manufacturers seeking standardized dispersibility, whereas artisans and smaller formulators sustain demand for liquid dyes requiring less processing infrastructure.
REACH registration requirements and the EU Green Deal's chemical hazard classification protocols are reshaping market access by elevating compliance costs for synthetic competitors and accelerating substitution timelines. ECHA's expanding restricted substance candidate list directly channels reformulation budgets toward natural alternatives in textile and food contact applications. France's ANSM and Germany's BfR maintain divergent interpretation frameworks for botanical colorant safety dossiers, creating uneven approval pathways that stakeholders must monitor for portfolio prioritization.
Market Dynamics
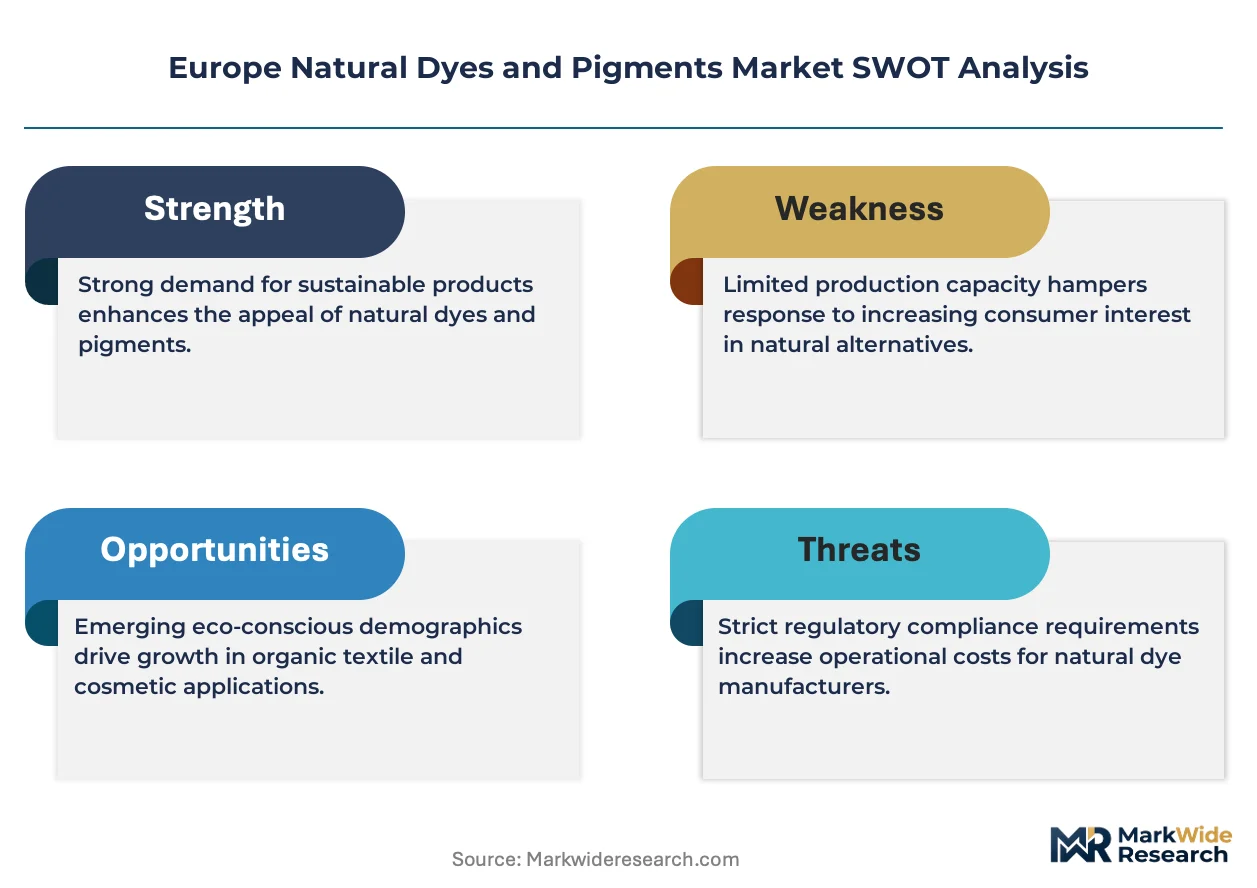
REACH registration costs and EU Green Deal chemical hazard protocols are accelerating substitution away from synthetic azo dyes toward plant-derived alternatives, compressing reformulation timelines across textile and food contact applications.
Growth Catalysts
- REACH Restriction Cascade:ECHA's expanding candidate list elevates compliance burdens for petrochemical-based competitors, redirecting R&D budgets toward botanical extraction methods.
- Apparel Brand Certification Mandates:German textile manufacturers have established strict supplier protocols requiring traceable natural inputs, creating pull-through demand across Nordic and Benelux sourcing networks.
- Biotechnology-Enabled Consistency:Fermentation-derived pigments now achieve batch-to-batch uniformity that rivals synthetic standards, unlocking adoption in industrial-scale coloration.
Market Restraints
- Agricultural Input Volatility:Climate-sensitive madder root and indigo harvests concentrate supply risk in Mediterranean and Baltic cultivation zones.
- Technical Lightfastness Ceiling:Natural pigments remain below synthetic benchmarks for UV stability in outdoor textile applications.
- France-Germany Regulatory Divergence:ANSM and BfR maintain conflicting botanical safety dossier requirements, fragmenting approval pathways.
Strategic Opportunities
- Eastern European Cultivation Expansion:Poland and Romania offer underexploited agricultural land for organic dye crop production with lower labor costs than Western EU.
- Cosmetics Formulation Complexity:Premium skincare brands seek certified organic extracts for colorant functions, commanding margin multiples above textile grades.
- CSRD-Driven Supply Chain Disclosure:Corporate sustainability reporting mandates force dye procurement transparency, advantaging certified natural suppliers.
Industry Challenges
- Phytochemistry Expertise Scarcity:Industrial-scale extraction requires specialized knowledge in plant metabolite stabilization that outpaces European technical training pipelines.
- Multi-Jurisdiction Certification Lag:Cross-border botanical approvals between France, Germany, and Italy extend commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Natural Dyes and Pigments Market |
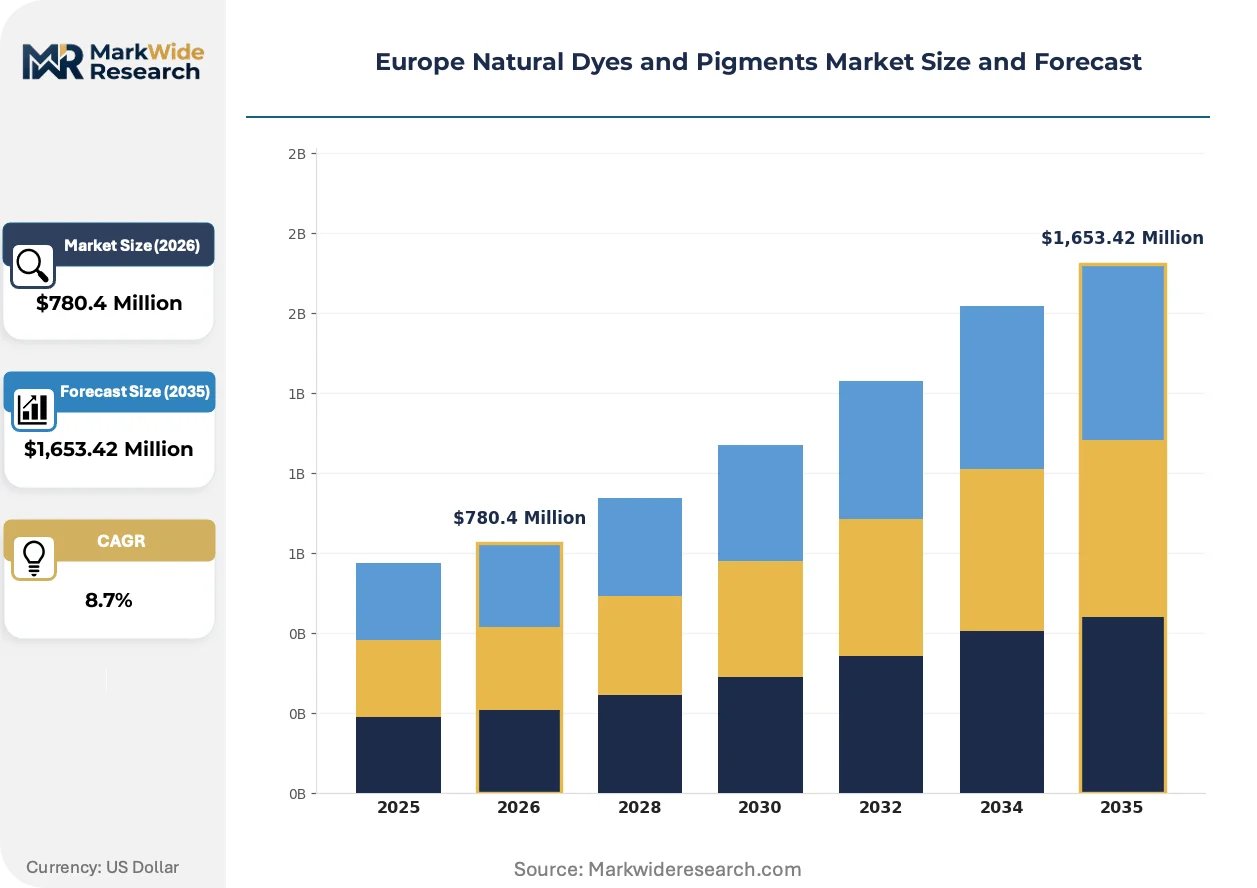
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,653.42 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: dyes, pigments, colorants, extracts Application: textiles, cosmetics, food, pharmaceuticals Form: liquid, powder, paste, granules End User: manufacturers, artisans, retailers, formulators |
| Companies Covered | BASF SE, GNT Group B.V., Koninklijke DSM N.V., ABBEY COLOR, EW Nutrition, Döhler, DDW The Color House, Vidya Europe Production SAS, DYNADIS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Natural Dyes and Pigments Market Strategic Shifts & Innovations
Bioprocessing advances and regulatory disclosure mandates are compressing the cost-performance gap between natural and synthetic colorants while fragmenting procurement authority across sustainability and technical functions.
Supercritical CO2 extraction is automating pigment recovery from agricultural waste streams at yields that challenge conventional aqueous methods. Dutch and German textile finishers are retrofitting equipment to accommodate these closed-loop systems. The technology is automating quality control steps that previously required manual batch testing, reducing skilled labor dependence in mid-scale facilities.
EU Green Deal chemical hazard classification protocols are forcing reformulation roadmaps across food contact and children's apparel segments. ECHA's 2024-2025 candidate list expansion directly channels substitution investment toward botanical alternatives. French packaging manufacturers face accelerated compliance deadlines compared to German counterparts, creating uneven adoption curves.
Technical buyers now split procurement authority between sustainability officers and laboratory quality managers, complicating vendor selection criteria. Long-term supply agreements with certified organic growers are displacing spot-market purchasing in premium segments. This bifurcation is most visible in German automotive interior applications, where OEMs mandate both batch consistency documentation and carbon footprint verification.
Europe Natural Dyes and Pigments Market Segmentation
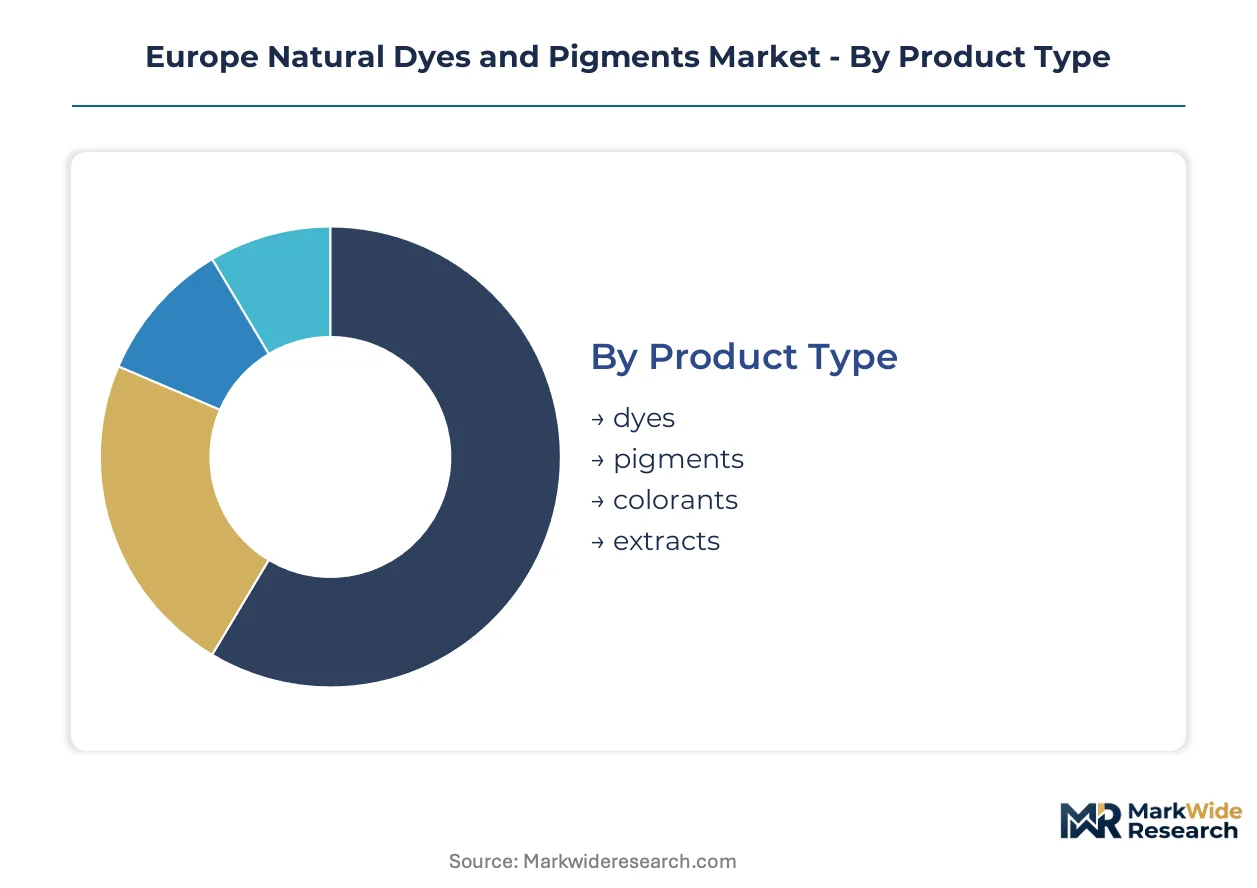
Natural dyes and pigments serve divergent technical requirements across European manufacturing, where extraction method and formulation complexity determine commercial viability. Segmentation reveals how procurement authority splits between sustainability officers and laboratory quality managers, reshaping vendor selection criteria.
Product Type:
Buyers in this category differentiate primarily by processing intensity and standardization needs, with industrial manufacturers favoring pre-dispersed formats while artisans accept raw botanical inputs.
- Pigments:Insoluble color-bearing particles derived from mineral deposits or plant tissues, processed to specified dispersibility and particle size distributions. German automotive interior OEMs mandate these for batch consistency documentation alongside carbon footprint verification.
- Dyes:Soluble colorants requiring aqueous or solvent-based application, typically extracted through fermentation or controlled drying to achieve tinctorial strength ratings. French and Italian textile finishers concentrate procurement here for water-based finishing lines.
- Colorants:Broad category encompassing both dye and pigment functions in standardized industrial grades.
- Extracts:Concentrated botanical preparations retaining secondary metabolites for multifunctional applications.
Pigments lead volumes today; extracts are gaining share fastest.
Application:
End-use concentration varies by regulatory pressure intensity, with food contact and children's apparel facing accelerated substitution timelines under ECHA candidate list expansions.
- Textiles:Volume-dominant segment spanning apparel, home furnishings, and technical fabrics. REACH restriction cascades and EU Green Deal protocols compress reformulation timelines, with Nordic and Benelux sourcing networks pulling demand from German supplier certification mandates.
- Cosmetics:Premium skincare brands command margin multiples above textile grades through certified organic extract demand. ANSM and BfR divergent safety dossier requirements fragment approval pathways for botanical colorants.
- Food:EFSA-compliant colorants for confectionery and beverage applications.
- Pharmaceuticals:Excipient and coating colorants meeting EP monograph specifications.
Textiles anchor current procurement volumes; cosmetics climbs the fastest.
Form:
Processing infrastructure availability determines format selection, with mid-scale facilities automating quality control through supercritical CO2-compatible systems.
- Liquid:Pre-dispersed aqueous or solvent-based preparations requiring minimal downstream processing. Dutch textile finishers retrofit equipment for closed-loop recovery systems.
- Powder:Dried, milled colorants with specified moisture content and flow characteristics. Baltic and Mediterranean cultivation zones supply raw material for indigo and madder root derivatives.
- Paste:Semi-solid concentrates for high-solids coating applications.
- Granules:Dust-free, free-flowing formats for automated dosing systems.
Powder dominates manufacturing intake; liquid formats expand most quickly.
End User:
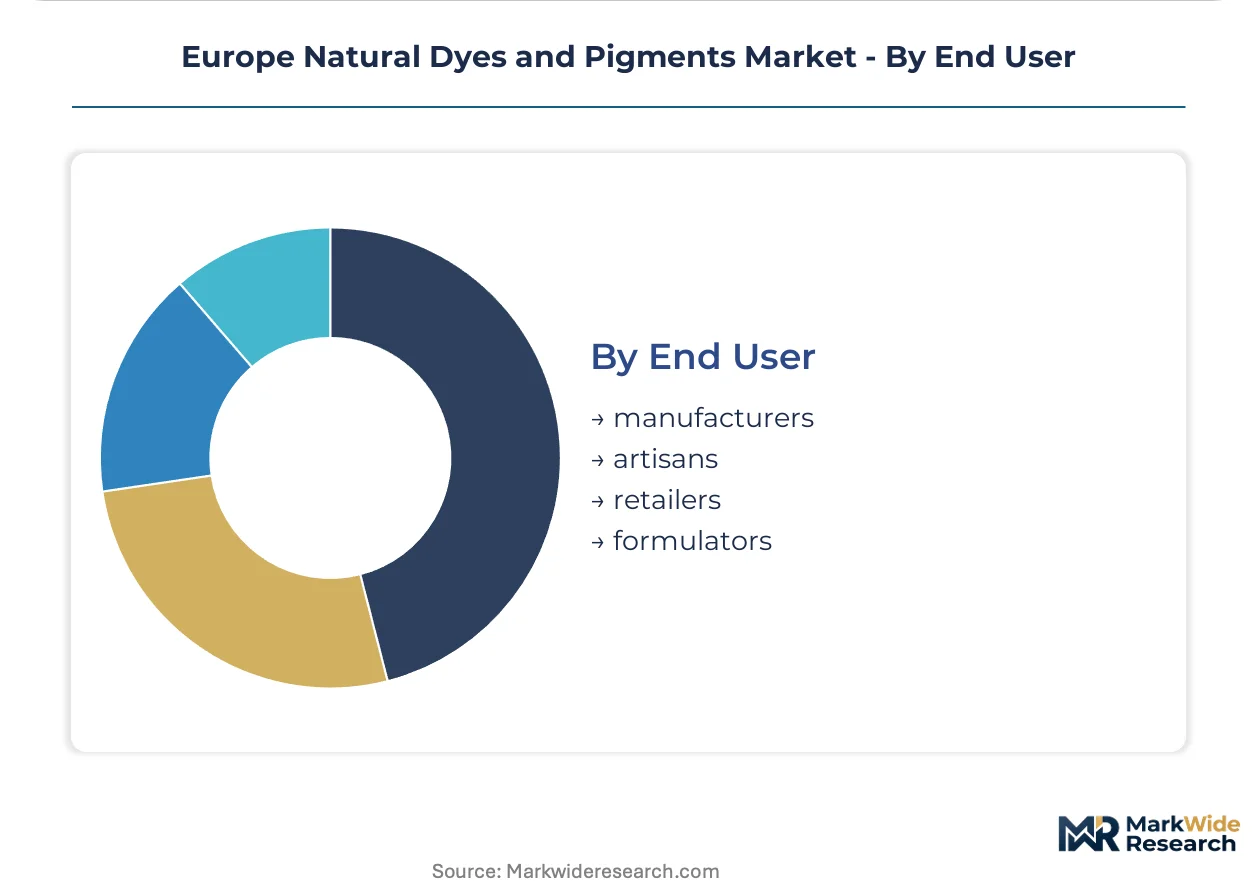
Procurement scale and certification requirements split this category, with large manufacturers demanding traceability documentation that artisans bypass.
- Manufacturers:Industrial-scale textile, food, and cosmetics producers requiring batch consistency documentation. CSRD-driven supply chain disclosure mandates force dye procurement transparency, advantaging certified natural suppliers.
- Formulators:Mid-tier compounders blending colorants into finished products. Poland and Romania offer underexploited agricultural land for organic dye crop production with lower labor costs than Western EU.
- Artisans:Small-scale practitioners sourcing raw botanical inputs.
- Retailers:Private-label brands and direct-to-consumer channels.
Manufacturers command volume leadership; formulators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized phytochemistry expertise clusters in Dutch and German research corridors, anchoring extraction technology development. Baltic and Mediterranean cultivation zones supply climate-sensitive botanical feedstocks. Regulatory divergence between Paris and Berlin fragments commercialization timelines.
Germany
Automotive interior OEMs in Stuttgart and Munich mandate batch consistency documentation alongside carbon footprint verification for natural pigments. BfR maintains strict botanical safety dossier requirements that exceed ECHA baseline standards. North Rhine-Westphalia textile finishers retrofit equipment for closed-loop supercritical CO2 systems.
France
ANSM interprets botanical colorant safety frameworks more restrictively than German counterparts, extending approval timelines. Premium skincare brands in Paris command margin multiples for certified organic extracts. Packaging manufacturers face accelerated EU Green Deal compliance deadlines compared to neighboring jurisdictions.
Netherlands
Groningen-based extraction specialists pioneer agricultural waste stream valorization for pigment recovery. Dutch textile finishers automate quality control through supercritical CO2-compatible infrastructure. Randstad logistics hubs coordinate Nordic and Benelux sourcing networks for German-certified suppliers.
Italy
Lombard and Tuscan textile finishers concentrate procurement in water-based dye lines for heritage apparel production. Artisan-scale demand sustains raw botanical input markets alongside industrial pigment grades. Emilia-Romagna processing facilities bridge conventional extraction with biotechnology-derived alternatives.
Poland
Underexploited agricultural land in Mazovia and Greater Poland supports organic dye crop expansion at labor costs below Western EU levels. Formulators establish mid-tier blending operations to serve German manufacturer demand. Warsaw-based distributors navigate multi-jurisdiction certification lag between Paris, Berlin, and Rome.
Europe Natural Dyes and Pigments Market Key Industry Players
Top-tier vendors anchor biotechnology-enabled consistency, while agricultural sourcing specialists and mid-scale formulators occupy differentiated positions. The vendor base organizes around three strategic archetypes: vertically integrated agricultural processors, fermentation-derived pigment developers, and regional extraction specialists. Capacity expansion and backward integration into captive cultivation represent the dominant competitive moves as supply security outweighs spot-market flexibility.
Among Dutch and German technology developers, Koninklijke DSM N.V. and GNT Group B.V. exemplify contrasting archetypes—biotechnology-derived batch uniformity versus agricultural vertical integration. BASF SE occupies a position bridging synthetic heritage with natural substitution portfolios. These anchors represent the spectrum from fermentation-based consistency to field-to-finished-colorant control.
| Leading Market Players |
|---|
| BASF SE |
| GNT Group B.V. |
| Koninklijke DSM N.V. |
| ABBEY COLOR |
| EW Nutrition |
| Döhler |
| DDW The Color House |
| Vidya Europe Production SAS |
| DYNADIS |
| Others |
Cost & Logistics Intelligence
German automotive interior OEMs and Nordic apparel brand procurement offices concentrate purchasing power across the value chain, anchoring contract-based long-term offtake agreements that displace spot-market volatility. This buyer concentration sustains premium pricing for certified organic extracts while compressing margins on conventional botanical powders.
Pricing Analysis
Service bundling separates extraction technology licensing from raw material supply, with Dutch supercritical CO2 equipment providers commanding separate fee structures from Baltic indigo cultivators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in economy-grade conventional powders is intensifying because Eastern European cultivation expansion adds supply volume. Small-scale artisans and independent formulators show highest price sensitivity, while German automotive OEMs absorb premium tiers without volume reduction.
Supply Chain Analysis
Botanical feedstock supply rests on Mediterranean indigo cultivation zones, Baltic madder root harvests, and Polish organic dye crop expansion. Climate-sensitive agricultural inputs, fermentation-derived biotechnology pigments, and supercritical CO2 extraction equipment constitute critical dependencies. Single-source vulnerability concentrates in Mediterranean indigo harvests exposed to drought frequency. Distribution runs through Randstad logistics hubs coordinating Nordic and Benelux sourcing networks, with Warsaw-based distributors navigating multi-jurisdiction certification lag.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as REACH restriction cascades and EU Green Deal mandates lock in substitution trajectories that outpace cyclical demand fluctuations.
For Market Incumbents: Acquire captive cultivation assets in Poland and Romania to secure climate-resilient feedstock supply. Biotechnology-derived pigment capacity in Dutch and German research corridors anchors batch consistency advantages against emerging agricultural sourcing specialists. Certification investment with ECHA pre-registration dossiers defends market access as ANSM and BfR divergence extends approval timelines for competitors. For New Entrants and Emerging Players: The premium-economy price gap in certified organic cosmetics extracts offers white-space entry below established botanical suppliers. Eastern European formulator operations serving German manufacturer demand represent the most penetrable segment. A co-development partnership with Groningen-based extraction technology developers accelerates supercritical CO2 capability without captive R&D investment. For Investors and Strategic Acquirers: Specialty chemical conglomerates with synthetic dye heritage are the most active acquirer in this space, seeking natural substitution portfolios for defensive repositioning. Vertically integrated agricultural processors with field-to-finished-colorant control command scarcity premiums across the analysis window. Watch biotechnology-enabled batch consistency breakthroughs in fermentation-derived pigments as the inflection signal for accelerated industrial adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Polish and Romanian organic dye crop expansion secures supply against Mediterranean climate volatility. |
| Biotechnology-Derived Pigment Scale-Up | Fermentation-based batch uniformity unlocks German automotive interior OEM specification compliance. |
| Supercritical CO2 Equipment Retrofit | Dutch textile finishers automate quality control through closed-loop agricultural waste stream valorization. |
| Multi-Jurisdiction Certification Investment | Parallel ANSM and BfR dossier preparation compresses commercialization timelines by 18-24 months. |
| Long-Term Supply Agreement with Certified Growers | Nordic and Benelux sourcing networks lock in German apparel brand procurement mandates. |
Research Approach
Bottom-up textile and cosmetics manufacturer modeling reconciled against top-down botanical extraction capacity tracking forms the analytical core. Primary interviews with plant managers at Dutch and German extraction facilities, procurement leads at Stuttgart automotive OEMs, sustainability officers at Nordic apparel brands, and technical R&D directors at biotechnology pigment developers combined with secondary validation from ECHA registration databases, EU Green Deal implementation reports, REACH candidate list expansions, and customs trade data for botanical feedstock flows.
Input-output matrices map extraction method productivity against end-use application requirements across the projection horizon. Segmentation dimensions include product type tier, application vertical, form factor, and end-user scale category. CAGRs derive from regression analysis of historical substitution patterns and regulatory compliance deadline impacts. Industry-specific forecast inputs incorporate CSRD-driven supply chain disclosure adoption curves and ECHA candidate list expansion schedules.
Caveats apply where ECHA regulatory acceleration, biotechnology batch consistency breakthroughs, or Eastern European agricultural expansion could materially shift the outlook. Forecasts reflect assumptions about REACH enforcement intensity and EU Green Deal chemical hazard classification protocol implementation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Inorganic Pigments Market