
 Acid Orange Market | 2026-2036
Acid Orange Market Size, Share, and Industry Trends Forecast 2026-2036
Acid Orange Market Analysis
India is tilting the acid orange supply landscape through expanding dyestuff capacity in Gujarat and Maharashtra. Vinayak Ingredients leverages its western India manufacturing base to serve domestic textile mills and export channels. Megha International sustains a broad azo dye portfolio that covers Acid Orange 7 through Acid Orange 14 variants. Merck KGaA anchors the high-purity segment with analytical-grade offerings for laboratory and specialty coating applications.
Acid orange denotes a class of azo dyes characterized by sulfonic acid groups that confer water solubility and affinity for protein fibers, typically synthesized through diazotization of aniline derivatives followed by coupling with naphthol components. These dyes color wool, silk, nylon, and leather through ionic bonding between sulfonate anions and cationic fiber sites. Powder formulations dominate volume shipments due to stability in storage and ease of standardization for textile bath operations. Liquid acid orange preparations capture share in continuous dyeing lines where automated dosing reduces batch variation. Leather applications represent a concentrated margin pool as automotive upholstery specifications tighten colorfastness thresholds.
India's Central Pollution Control Board enforces effluent discharge limits on dyehouse operations, elevating capital requirements for zero-liquid-discharge compliance. The EU REACH regulation restricts certain aromatic amines in consumer textiles, forcing reformulation of legacy acid orange chemistries for export-bound production. China's MEE implements stricter wastewater COD thresholds in Zhejiang and Jiangsu dye manufacturing clusters. Stakeholders must monitor regulatory divergence between Asian production hubs and European import standards to anticipate reformulation cycles and capacity relocation.
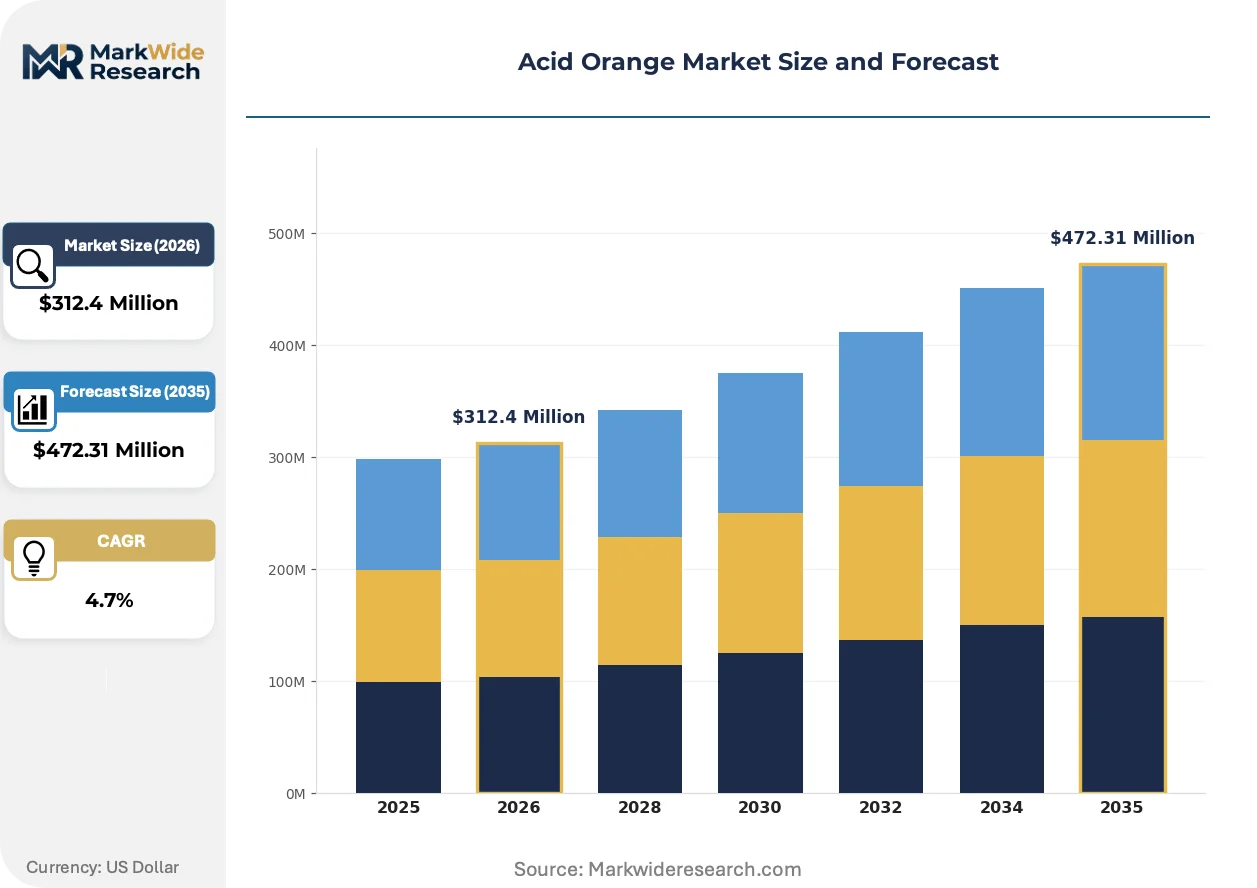
Market Dynamics
Formulation chemistry is pivoting as REACH and MEE regulations force replacement of legacy coupling components with safer aromatic amines, compressing reformulation cycles and elevating R&D intensity for dyestuff producers serving export markets.
Growth Catalysts
- EU REACH compliance deadlines:The 2026 restriction window on benzidine derivatives is accelerating reformulation investment among European textile importers, pulling through demand for compliant acid orange variants from South Asian suppliers.
- Automotive leather specifications:Colorfastness thresholds for upholstery applications are tightening across German and Italian automotive supply chains, concentrating margin pools in high-performance dye grades.
- Zero-liquid-discharge mandates:India's Central Pollution Control Board enforcement is consolidating dyestuff capacity toward Gujarat-based producers with captive effluent treatment infrastructure.
Market Restraints
- Aniline derivative cost volatility:Feedstock prices for diazotization precursors fluctuate with crude oil derivatives and naphtha cracking economics, compressing formulation margins unpredictably.
- Zhejiang-Jiangsu supply concentration:China's MEE wastewater thresholds are idling smaller dye intermediates capacity, creating bottleneck risk for global azo dye precursor supply.
- Natural dye substitution:Extract-based colorants from agricultural waste streams are capturing niche share in premium wool garment segments where chemical-free positioning commands price premiums.
Strategic Opportunities
- Continuous dyeing automation:Liquid acid orange preparations are penetrating Turkish and Vietnamese textile corridors where automated dosing systems reduce bath variation and water consumption simultaneously.
- Bio-based coupling components:Fermentation-derived naphthol alternatives are advancing through pilot-scale validation, offering regulatory-compliant pathways for EU-bound production.
- Digital color matching platforms:Spectrophotometry-integrated formulation software is reducing lab-to-production cycle times for custom shade development in distributed dyehouse networks.
Industry Challenges
- Cross-regulatory compliance engineering:Dyestuff formulators must maintain parallel product lines satisfying divergent EU REACH, US EPA, and India BIS aromatic amine limits, fragmenting batch economics.
- Legacy equipment retrofit costs:Continuous dyeing line conversion from powder to liquid handling systems demands capital outlays that mid-scale Tiruppur and Surat operations struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acid Orange Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid Orange 7, Acid Orange 12, Acid Orange 14, Acid Orange 15 Application: Textiles, Coatings, Printing Inks, Leather End User: Textile Manufacturers, Automotive Suppliers, Paint Producers, Leather Goods Manufacturers Form: Powder, Liquid, Granule, Paste |
| Companies Covered | Sigma-Aldrich Corporation, Vinayak Ingredients (India) Pvt. Ltd., Megha International, Shramik Chemicals, Krishna Dyestuff Company, Aeromax Industries, Sterling Pigments & Chemicals, Merck KGaA, MAGNIL DYE CHEM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acid Orange Market Emerging Trajectories
Spectrophotometric formulation systems are compressing shade-matching timelines while regulatory chemistry restrictions and procurement digitization are restructuring how dye specifications travel from brand houses to production floors.
Digital twin platforms for color formulation are virtualizing laboratory trial processes that previously consumed physical fiber substrates and dye volumes. Large European apparel brands are deploying these systems across Bangladesh and Vietnam supply bases, shrinking sample turnaround from weeks to days. This virtualization is compressing the competitive advantage of established dyehouses with legacy empirical expertise.
REACH authorization requirements for aromatic amines are forcing systematic substitution of legacy acid orange chemistries ahead of 2026 sunset dates. Formulators are validating alternative coupling components through toxicological dossiers that ECHA reviews under accelerated timelines. Specialty chemical suppliers with pre-registered safer alternatives are capturing specification control from commodity dye traders.
Brand-led chemical management initiatives are displacing traditional spot-market dye purchasing with audited supplier lists and restricted substance protocols. Tier-1 textile mills in India and Turkey now contract directly with dyestuff producers rather than intermediaries, compressing margin layers. This consolidation is most visible in Inditex and H&M supply chains where ZDHC conformance gates filter acid orange sourcing to certified manufacturers.
Acid Orange Market Segmentation
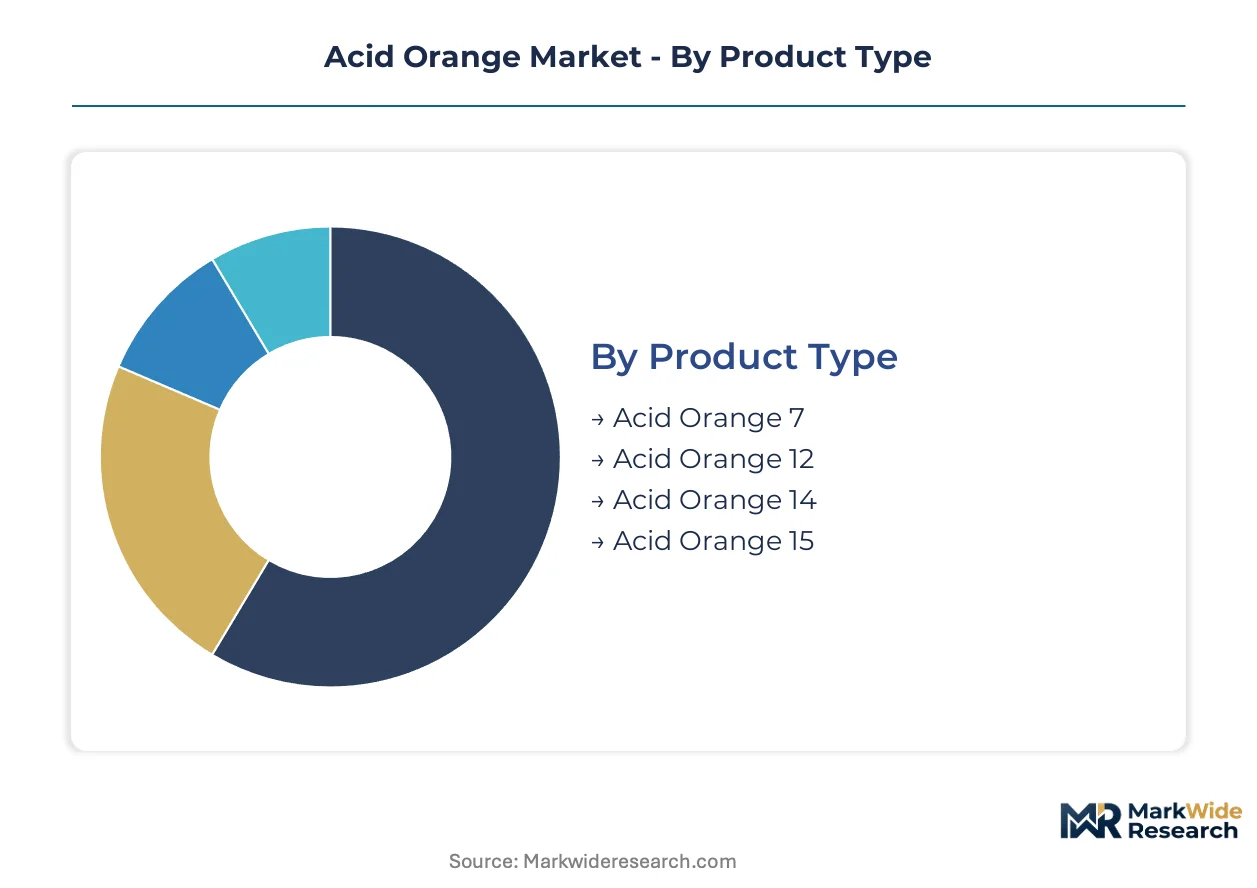
Acid orange dye specifications fragment across molecular variants, application requirements, and handling formats. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Textile mills deploy distinct chromophore structures based on fiber affinity requirements and fastness specifications.
- Acid Orange 7:The monoazo structure binds wool and silk through sulfonic acid groups with moderate lightfastness ratings. Tiruppur garment exporters specify this variant for cost-sensitive cotton-wool blends where washfastness demands remain moderate.
- Acid Orange 12:Disazo construction delivers superior substantivity on polyamide fibers. Automotive upholstery suppliers in Germany and Italy source this grade for leather applications where perspiration and light exposure thresholds are stringent.
- Acid Orange 14:Modified coupling chemistry suits nylon carpet fiber dyeing at elevated temperature baths. BIS certification requirements in India restrict import formulations lacking approved impurity profiles.
- Acid Orange 15:Specialized chromophore for inkjet printing systems requiring narrow particle size distribution. Digital textile printing corridors in Turkey specify this grade for reactive-acid hybrid formulations.
The dominant share belongs to Acid Orange 7, while Acid Orange 12 is closing the gap fastest.
Application:
End-use concentration determines pricing power and reformulation frequency across regulatory jurisdictions.
- Textiles:Wool, silk, and nylon fiber dyeing in batch and continuous processes. Surat powerloom clusters and Bangladesh knitwear exporters absorb volume shipments, though REACH aromatic amine limits force pre-shipment testing for EU-bound goods.
- Leather:Automotive upholstery and fashion goods applications command premium specifications. German OEM colorfastness protocols exceed residential furniture standards, concentrating margin in certified supply chains.
- Coatings:Industrial and decorative paint systems requiring water-soluble colorants. Powder coating manufacturers in Maharashtra specify acid orange for architectural aluminum finishes.
- Printing Inks:Flexographic and gravure systems for packaging and publication grades. Water-based ink formulations in Vietnam offset the shift from solvent systems.
Textile absorption still leads volume, though leather applications generate the steepest expansion trajectory.
End User:
Procurement sophistication varies sharply between commodity garment producers and specification-driven automotive tiers.
- Textile Manufacturers:Integrated mills and job dyers across South Asia. Gujarat-based operations with captive effluent treatment infrastructure capture preferential supply terms under CPCB enforcement.
- Automotive Suppliers:Tier-1 and Tier-2 leather processors serving German and Italian OEMs. ZDHC conformance gates filter sourcing to certified acid orange producers with full toxicological dossiers.
- Paint Producers:Decorative and industrial coating formulators. Maharashtra and Gujarat industrial clusters specify powder grades for automated dosing systems.
- Leather Goods Manufacturers:Fashion accessories and footwear producers. Export-oriented units in Tamil Nadu face dual compliance with EU REACH and domestic BIS limits.
Automotive suppliers extract the tightest specification control, while textile manufacturers still move the largest absolute volumes.
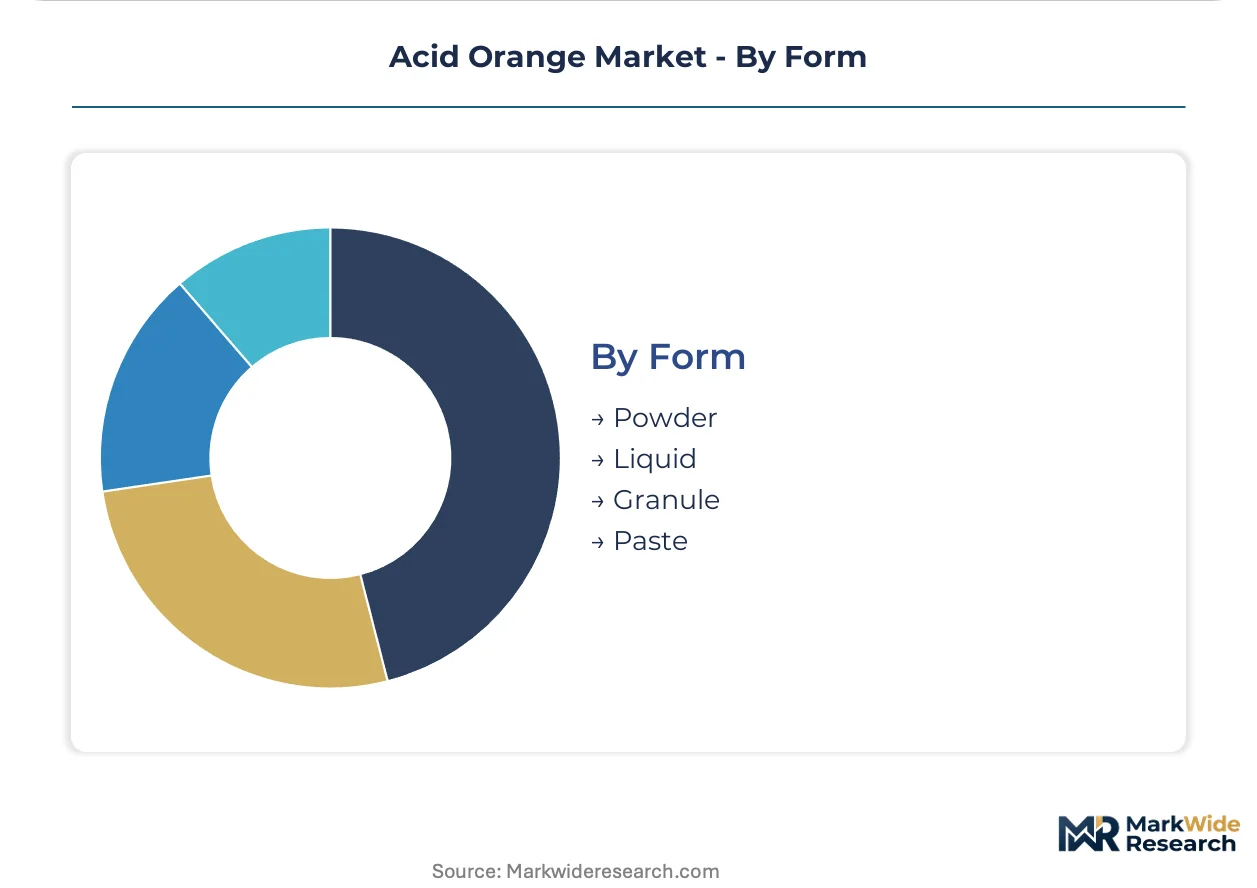
Form:
Physical format selection balances storage stability against process automation and water consumption targets.
- Powder:Dominant shipment format for textile batch dyeing operations. Standardized strength specifications simplify bath calculations for Tiruppur and Surat dyehouses.
- Liquid:Automated dosing systems in Turkish and Vietnamese continuous dyeing lines favor this format. Reduced batch variation and lower water consumption align with brand sustainability protocols.
- Granule:Dust-free handling characteristics suit leather finishing operations. Automotive upholstery processors specify this form for workplace exposure compliance.
- Paste:High-concentration dispersions for printing ink manufacturing. Narrow viscosity tolerances support flexographic press stability.
Powder retains volume leadership, though liquid preparations are gaining share fastest in automated corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European textile importers prioritize REACH-compliant formulations with full toxicological dossiers, while South Asian manufacturers optimize for cost-sensitive batch operations with standardized powder grades.
India
Textile mills in Gujarat and Maharashtra absorb the largest regional volumes for wool and silk dyeing. The Central Pollution Control Board enforces zero-liquid-discharge mandates that consolidate capacity toward producers with captive effluent infrastructure. Surat powerloom clusters and Tiruppur garment export belts drive specification demand for Acid Orange 7 through 14 variants.
Germany
Automotive upholstery suppliers command premium specifications for leather applications exceeding residential furniture standards. ECHA reviews toxicological dossiers for alternative coupling components under accelerated REACH timelines. Baden-Württemberg leather processors source high-performance acid orange grades for OEM supply chains serving BMW and Mercedes-Benz.
China
Zhejiang and Jiangsu dye manufacturing clusters face MEE wastewater COD thresholds that idle smaller intermediates capacity. The dual carbon goals pressure energy-intensive diazotization operations toward process intensification. Shaoxing textile chemical corridors reformulate legacy benzidine-derived chemistries for EU-bound export production.
Turkey
Continuous dyeing automation in Bursa and Istanbul corridors favors liquid acid orange preparations for automated dosing systems. Water consumption reduction aligns with brand sustainability protocols from Inditex and H&M supply chains. Denizli textile processors integrate spectrophotometric color matching to compress sample turnaround timelines.
Vietnam
Dong Nai and Binh Duong provinces absorb volume shipments for knitwear export production serving EU and US markets. Water-based ink formulations offset solvent system phase-outs in flexographic printing applications. Ho Chi Minh City corridor dyehouses adopt digital color matching platforms to reduce lab-to-production cycle times.
Acid Orange Market Vendor Landscape
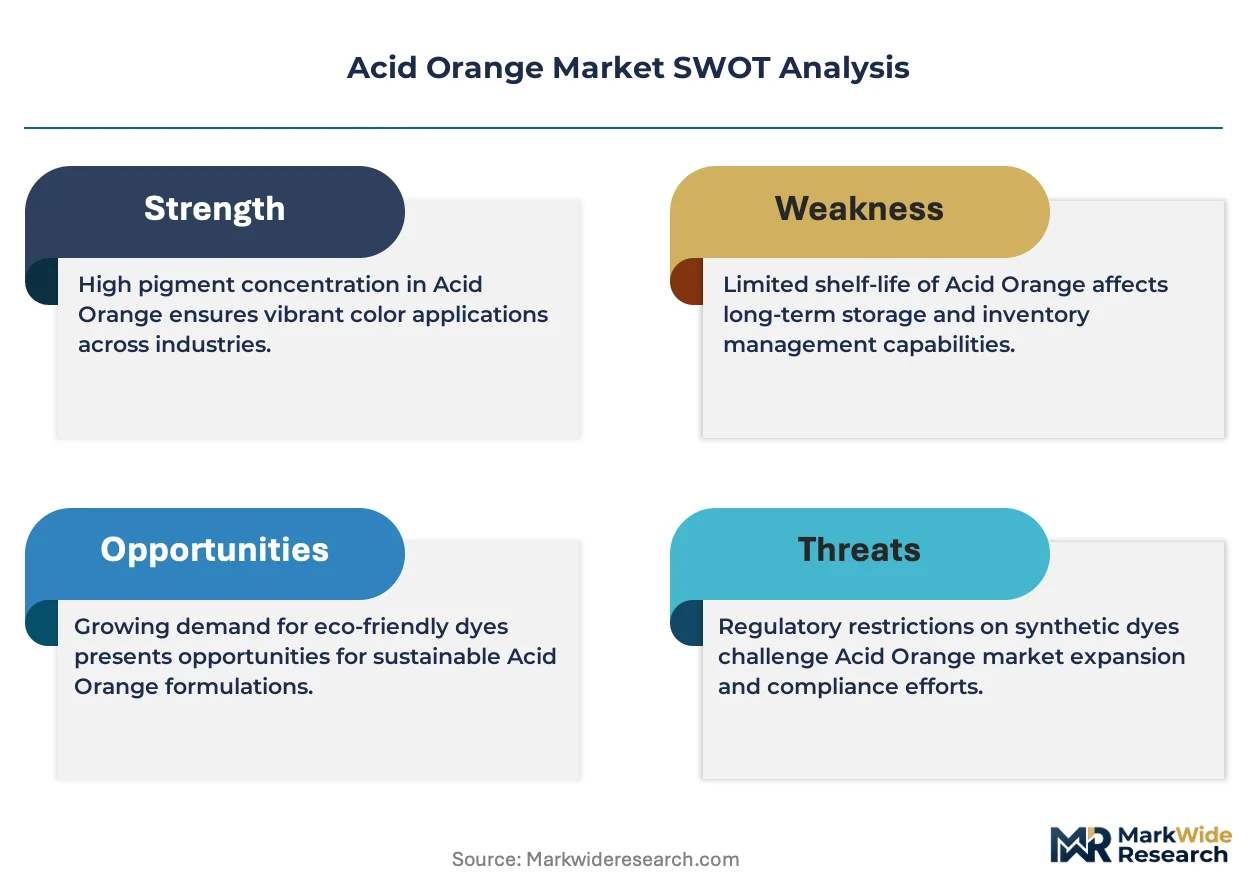
Capability concentration sits with specialty chemical suppliers possessing pre-registered REACH alternatives; scale advantage sits with integrated South Asian producers with captive intermediates capacity. The vendor base stratifies across three tiers: multinational analytical-grade specialists, regional dyestuff formulators with BIS certification, and commodity traders serving spot-market textile corridors. Strategic moves center on backward integration into naphthol intermediates and toxicological dossier pre-registration for EU authorization windows.
Among Indian formulators, Vinayak Ingredients and Megha International exemplify the regional certified-manufacturer archetype with western India manufacturing bases. Merck KGaA anchors the analytical-grade segment for laboratory and specialty coating applications. These three occupy positions spanning commodity textile supply and high-purity specification control.
| Leading Market Players |
|---|
| Sigma-Aldrich Corporation |
| Vinayak Ingredients (India) Pvt. Ltd. |
| Megha International |
| Shramik Chemicals |
| Krishna Dyestuff Company |
| Aeromax Industries |
| Sterling Pigments & Chemicals |
| Merck KGaA |
| MAGNIL DYE CHEM |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Zhejiang-Jiangsu dye intermediates clusters compresses supplier margins while elevating pricing leverage for integrated South Asian formulators with captive naphthol production. This utilization asymmetry pushes contract structures toward volume-commitment offtakes that lock in feedstock access for Tiruppur and Surat textile corridors.
Pricing Analysis
Long-term offtake contracts dominate procurement between certified Indian formulators and EU-bound textile exporters, insulating against aniline derivative spot volatility. Price differentiation rests on REACH pre-registration status and ZDHC conformance tier, with automotive leather specifications commanding substantial premiums over garment-grade powder shipments. Cost compression in standard Acid Orange 7 formulations intensifies as Chinese MEE enforcement idles smaller intermediates capacity. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to colorfastness liability exposure, while Surat powerloom clusters negotiate aggressively on standardized bath strengths.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing for Vietnamese and Bangladeshi textile mills under brand sustainability audit pressure. Raw material dependencies center on aniline derivatives from naphtha cracking economics, naphthol coupling components from coal-tar distillation, and sulfonation reagents from sulfuric acid supply. Single-source vulnerability concentrates in legacy benzidine-derived precursor stocks facing REACH sunset deadlines. Distribution runs through certified manufacturer-direct channels displacing commodity traders as ZDHC gates harden across Inditex and H&M supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acid Orange Market participants should treat toxicological dossier services and reformulation consulting as the fastest-expanding recurring-revenue layer, outpacing commodity dye volume growth as REACH authorization windows tighten.
For Market Incumbents: Pre-empt specification control erosion by accelerating backward integration into naphthol intermediates before MEE enforcement consolidates Chinese supply. Lock in automotive leather certification through ECHA pre-registration of alternative coupling components, defending margin pools against fermentation-derived substitute entrants. Prioritize captive effluent infrastructure investments in Gujarat to capture CPCB-mandated capacity consolidation. For New Entrants and Emerging Players: Vietnam's Dong Nai-Binh Duong corridor offers underpenetrated white-space for liquid acid orange preparations serving continuous dyeing automation. Target spectrophotometry-integrated formulation services for Turkish denim processors seeking sample turnaround compression. Enter through private-label partnerships with established BIS-certified manufacturers rather than greenfield capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical suppliers with pre-registered REACH alternatives and toxicological dossier libraries. Long-term viability over a multi-year horizon favors acquisition targets combining western India manufacturing bases with automotive leather certification. Watch for MEE enforcement intensity in Zhejiang-Jiangsu as the inflection signal for precursor supply disruption and margin redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphthol Intermediates | Captive supply of coupling components insulates against MEE-driven Chinese precursor idling. |
| REACH Alternative Pre-Registration | ECHA toxicological dossier submission secures specification control for EU-bound automotive leather supply. |
| Zero-Liquid-Discharge Capacity Expansion | CPCB-compliant Gujarat facilities capture preferential supply terms under enforcement consolidation. |
| Liquid Preparation Formulation Scale-Up | Automated dosing compatibility penetrates Turkish and Vietnamese continuous dyeing corridors. |
| Spectrophotometry Platform Partnership | Digital color matching integration compresses lab-to-production cycle times for distributed dyehouse networks. |
Methodological Framework
Initial hypotheses were tested against primary input from dyestuff plant managers, textile procurement leads at Tiruppur and Surat mills, leather finishing technical directors, and distribution channel partners in Vietnam and Turkey, then refined against secondary validation from customs trade data, Chemicals and Petrochemicals Manufacturers Association reports, ECHA authorization databases, and SEC filings of listed specialty chemical suppliers. Bottom-up volume triangulation across molecular variants and application segments was cross-checked against top-down value estimates from production capacity and utilization rates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions including chromophore structure tier, end-use industry concentration, physical form factor, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted projection of textile production indices, leather upholstery specifications evolution, and inkjet printing penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale Indian formulators or accelerated fermentation-derived substitute commercialization would shift outcomes. Macroeconomic contraction in EU apparel import demand, regulatory divergence between REACH and BIS aromatic amine limits, or breakthrough scale in bio-based coupling chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Organic Lake Pigments Market