
 Rubber Color Masterbatch Market | 2026-2036
Rubber Color Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Color Masterbatch Market Analysis
Automotive component buyers are bifurcating from commodity tire producers in procurement priorities. Avient Corporation leverages its compounding expertise to serve medical-grade silicone coloration. Thai Bamroong Chemicals Co., Ltd. anchors Southeast Asian supply through localized pigment dispersion facilities. Shanghai Yuku Chemical Technology Co., Ltd. competes on custom-matched batches for electronics-grade EPDM compounds.
Rubber color masterbatch denotes concentrated pigment-carrier systems, typically 30-80% colorant loading in EPDM or SBR binder matrices, designed for homogeneous dispersion during Banbury or twin-screw mixing. The product prevents pigment agglomeration, reduces dusting, and stabilizes hue consistency across vulcanization cycles. Opaque formulations command the widest volume footprint, while weather-resistant grades capture expanding margin pools in outdoor infrastructure and marine applications. Tires remain the largest application outlet, though automotive components exhibit faster specification upgrades as OEMs tighten delta-E color tolerance bands.
REACH pigment restrictions and EPA chemical data reporting obligations are elevating substitution costs for cadmium and lead-based colorants. ECHA substance evaluation protocols now demand full supply-chain disclosure for azo-based organic pigments. ISO 14001 environmental management certifications are becoming de facto qualifiers for tier-one automotive supplier status. Stakeholders must monitor regulatory divergence between EU hazard classifications and US TSCA Section 5 new chemical review timelines to anticipate reformulation cycles.
Market Dynamics
REACH pigment restrictions are fragmenting supplier bases as cadmium and lead-based colorants face phased elimination, forcing compounders to rebuild formulation portfolios around organic and rare-earth alternatives while automotive OEMs tighten delta-E tolerance specifications.
Growth Catalysts
- EPDM infrastructure demand:Marine fender and bridge bearing manufacturers specify weather-resistant grades with 15-year color retention guarantees, expanding volume commitments for high-performance masterbatches.
- REACH substitution mandates:ECHA substance evaluation protocols for azo-based organic pigments accelerate reformulation R&D, creating first-mover advantages for compliant compounders in Germany's industrial corridor.
- Medical-grade silicone expansion:ISO 13485-certified device manufacturers require USP Class VI validated color systems, opening premium pricing tiers for specialized dispersion expertise.
Market Restraints
- Pigment cost volatility:Rare-earth cerium and yttrium oxide prices fluctuate with Chinese export quota adjustments, compressing margins on high-heat-stable yellow and red formulations.
- Carrier polymer concentration:EPDM and SBR binder supply concentrates among three Southeast Asian petrochemical complexes, exposing compounders to force majeure disruptions during monsoon logistics constraints.
- Technical dispersion limits:Carbon black competitive grades above 50 phr loading exhibit agglomeration in low-shear Banbury mixing, restricting dark shade applications for certain tire architectures.
Strategic Opportunities
- India PLI scheme alignment:Domestic tire capacity expansion under production-linked incentives creates localized masterbatch demand requiring BIS-certified pigment systems.
- Recycled rubber integration:Devulcanized EPDM from end-of-life roofing membranes needs compatible color stabilization, merging circular economy mandates with formulation innovation.
- Direct-to-molder digital platforms:Custom-matched batch ordering via spectrophotometer-linked portals shortens specification cycles for electronics-grade compounders in Japan.
Industry Challenges
- Colorimetrist talent scarcity:Delta-E matching expertise combining spectrophotometry and vulcanization chemistry commands premium compensation, constraining regional expansion for mid-tier compounders.
- Multi-certification capex burdens:Simultaneous IATF 16949 automotive, ISO 13485 medical, and EMAS environmental audits require dedicated quality infrastructure investment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Color Masterbatch Market |
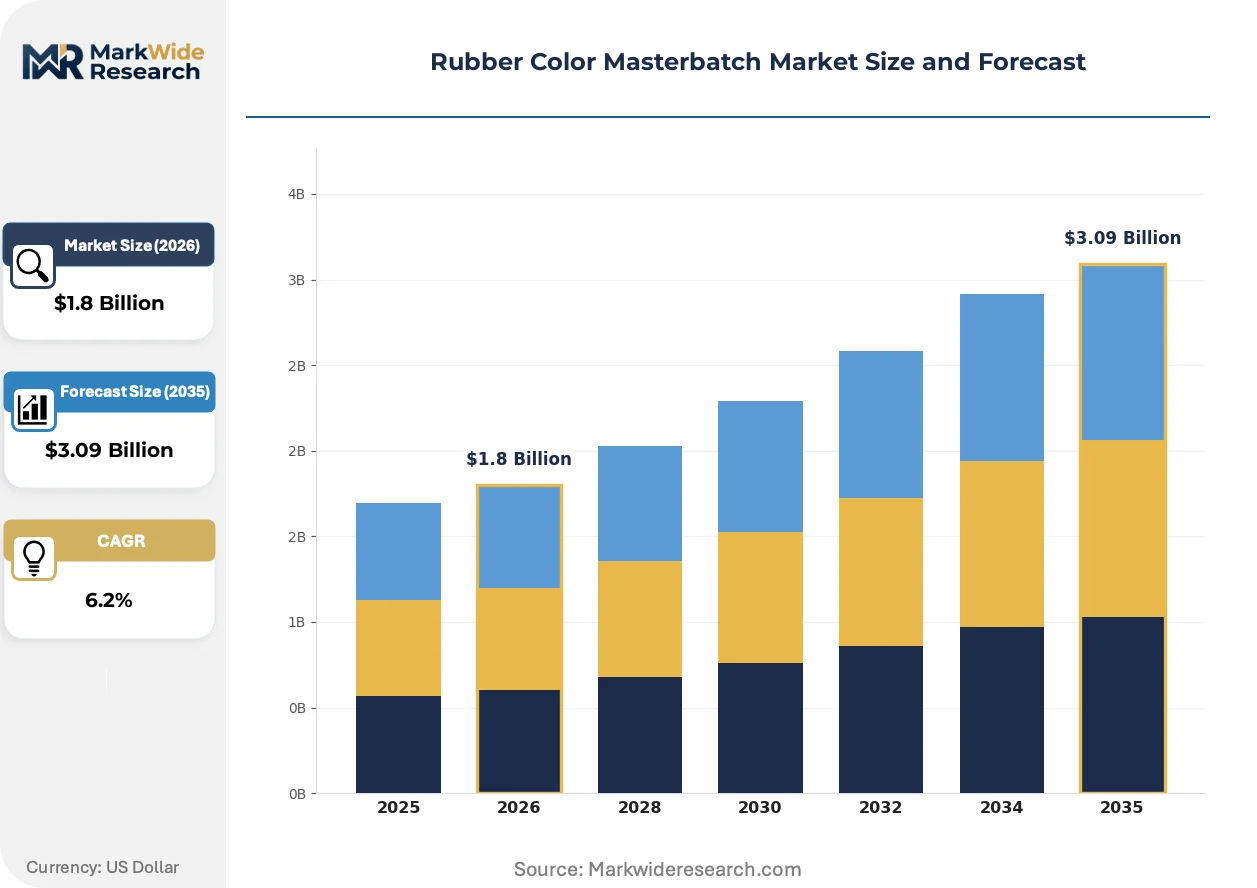
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Opaque, Lightfast, Weather-resistant Application: Tires, Seals, Hoses, Automotive Components End User: Automotive, Consumer Goods, Construction, Electronics Delivery Mode: Direct, Distribution, Online, Third-party |
| Companies Covered | Universal Masterbatch LLP, Thai Bamroong Chemicals Co., Ltd., Aron Universal Limited, Avient Corporation, Shanghai Yuku Chemical Technology Co., Ltd., Prisma Color Limited, PT Basis Pancakarya, Ampacet Corporation, Hangzhou Xiaoluan Imp & Exp Co.,Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Color Masterbatch Market Emerging Trajectories
Pre-dispersed pigment technologies are compressing traditional compounding steps while regulatory disclosure requirements deepen supply-chain traceability obligations across all tier levels.
Surface-treated organic pigments with silane coupling agents are decomposing the historical trade-off between color strength and heat stability in peroxide-cured EPDM systems. Automotive under-the-hood component manufacturers in Germany's Cologne-Düsseldorf corridor specify these grades for 150°C continuous service conditions. The technology is decomposing commodity masterbatch pricing power by enabling lower loadings without hue degradation.
ECHA's expanded SCIP database obligations for SVHC-containing articles now require full pigment supply-chain disclosure from raw material to finished rubber part. Tire manufacturers face 18-month reformulation cycles to eliminate candidate-listed substances before mandatory reporting deadlines. Southeast Asian export compounders are establishing EU-liaison regulatory affairs functions to manage substance volume tracking.
Automotive OEMs now mandate locked-in color specifications 36 months before platform launch, compressing traditional 12-month masterbatch qualification windows. Tier-one suppliers in Thailand and China are building captive spectrophotometry labs to accelerate delta-E approval cycles. Electronics-grade EPDM compounders in Japan's Kanto region exhibit the most aggressive timeline compression, driven by smartphone gasket refresh cycles.
Rubber Color Masterbatch Market Segmentation

Rubber color masterbatch segmentation reveals divergent supply chain configurations. Product type and application categories split between domestic compounders serving regional tire plants versus export-oriented specialists targeting automotive OEMs with locked-in color specifications.
Product Type:
Geographic demand patterns split sharply across these four formulations. Weather-resistant grades concentrate in Germany's Cologne-Düsseldorf corridor for infrastructure exports, while opaque formulations serve high-volume domestic tire production.
- Opaque:These formulations carry 30-80% pigment loading in EPDM or SBR binders, engineered for homogeneous dispersion during Banbury mixing. Domestic tire manufacturers in Thailand and China absorb the largest volumes, prioritizing dust reduction and hue stability across vulcanization cycles. The segment anchors volume commitments from compounders with captive dispersion facilities.
- Weather-resistant:Marine fender and bridge bearing manufacturers specify these grades with 15-year color retention guarantees. Demand concentrates in Germany's industrial corridor, where ECHA REACH mandates accelerate reformulation toward compliant organic and rare-earth alternatives. The segment captures expanding margin pools in outdoor infrastructure applications.
- Transparent:Silicone carrier systems with low-refractive-index pigments serve medical-grade tubing and optical sealing applications requiring USP Class VI validation.
- Lightfast:Peroxide-cured EPDM compounds with surface-treated organic pigments target automotive under-the-hood components facing 150°C continuous service conditions.
Opaque formulations command the established base. The steepest expansion runs through weather-resistant grades.
Application:
Cost tier stratification separates commodity tire applications from premium automotive component specifications. Delta-E tolerance bands tighten progressively from hoses through seals to under-the-hood components.
- Tires:Carbon black competitive grades above 50 phr loading face technical dispersion limits in low-shear Banbury mixing, constraining dark shade architectures. Volume concentrates among three Southeast Asian petrochemical complexes supplying EPDM and SBR binders. The segment remains vulnerable to force majeure disruptions during monsoon logistics constraints.
- Automotive Components:OEMs now mandate locked-in color specifications 36 months before platform launch, compressing traditional 12-month masterbatch qualification windows. Tier-one suppliers in Thailand and China are building captive spectrophotometry labs to accelerate delta-E approval cycles. Electronics-grade EPDM compounders in Japan's Kanto region exhibit the most aggressive timeline compression.
- Seals:Gasket applications for smartphone refresh cycles require custom-matched batches with compressed specification windows.
- Hoses:Fluid transfer systems in construction equipment specify weather-resistant grades for UV-exposed installations.
Tire applications absorb the volume base. Automotive components are climbing the fastest on specification upgrade intensity.
End User:
Customer type determines certification burden and pricing power. Automotive and medical device manufacturers impose multi-standard compliance, while construction buyers prioritize weathering performance over documentation depth.
- Automotive:IATF 16949 certification is becoming a de facto qualifier for tier-one supplier status. OEMs bifurcate procurement between commodity tire producers and component specialists with tightened delta-E tolerance bands. The segment demands simultaneous quality infrastructure investment across automotive, medical, and environmental standards.
- Electronics:Smartphone gasket manufacturers in Japan's Kanto region drive the most aggressive timeline compression. Custom-matched batch ordering via spectrophotometer-linked portals shortens specification cycles for EPDM compounders serving device refresh cycles.
- Construction:Bridge bearing and marine fender manufacturers specify weather-resistant grades with extended color retention guarantees.
- Consumer Goods:Appliance seals and sporting goods applications prioritize cost-optimized opaque formulations with standard dispersion requirements.
Automotive end users anchor the revenue base. Electronics applications are gaining share fastest on specification intensity and shortened product cycles.
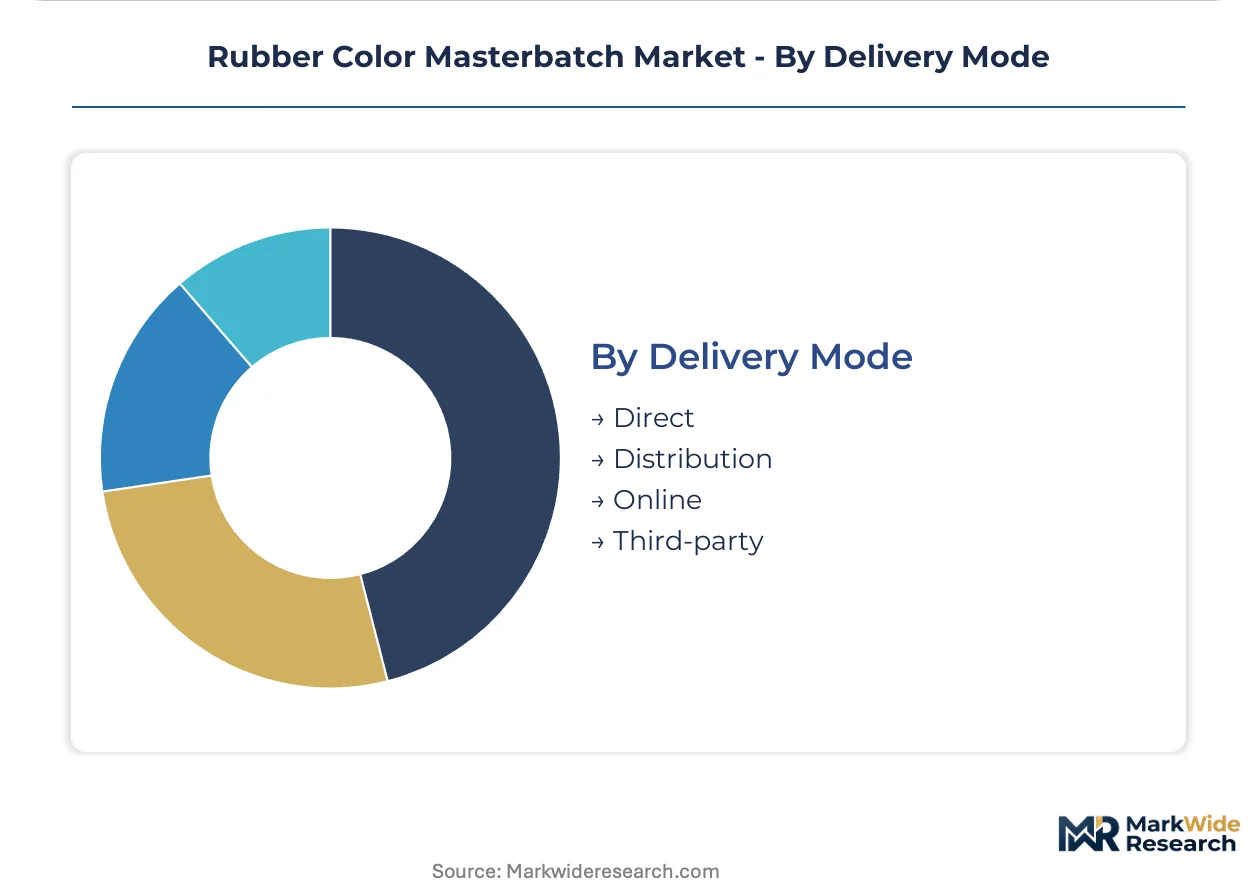
Delivery Mode:
Supply concentration shapes channel strategy. Direct relationships dominate high-volume tire accounts, while distribution and digital platforms serve fragmented electronics and construction demand.
- Direct:Long-term supply agreements with automotive OEMs and major tire manufacturers lock in volume commitments. These relationships require dedicated regulatory affairs functions to manage ECHA SCIP database obligations and substance volume tracking across the supply chain.
- Distribution:Regional distributors serve mid-tier compounders lacking in-house spectrophotometry capabilities. The channel bridges fragmented construction and consumer goods demand in Southeast Asian markets.
- Online:Digital platforms for custom-matched batch ordering are emerging in Japan's electronics corridor, linking spectrophotometer data directly to compounding schedules.
- Third-party:Contract compounders provide overflow capacity during qualification windows or force majeure disruptions at primary facilities.
Direct delivery commands the established base. The steepest expansion runs through online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tire manufacturers concentrate procurement in Germany, Thailand, China, and the United States, while electronics-grade compounders in Japan drive specification intensity. REACH mandates in Europe and India's PLI scheme are redirecting formulation strategies and capacity investments across these buyer clusters.
Germany
Bridge bearing and marine fender manufacturers in the Cologne-Düsseldorf corridor specify weather-resistant grades with 15-year color retention guarantees. ECHA REACH restrictions on heavy-metal pigments force reformulation toward organic and rare-earth alternatives. The industrial corridor hosts compounders building dedicated regulatory affairs functions to manage SCIP database obligations.
Thailand
Domestic tire plants absorb the largest volumes of opaque formulations with 30-80% pigment loading in EPDM binders. Localized pigment dispersion facilities anchor Southeast Asian supply for regional automotive component exports. Monsoon logistics constraints expose compounders to force majeure disruptions at concentrated petrochemical complexes.
China
Electronics-grade EPDM compounders serving smartphone gasket refresh cycles demand custom-matched batches with compressed specification windows. Shanghai-based specialists compete on spectrophotometer-linked portals for direct-to-molder digital ordering. The Yangtze River Delta concentrates capacity for high-volume opaque masterbatch production.
United States
Medical-grade silicone device manufacturers require USP Class VI validated color systems with ISO 13485 certification. EPA chemical data reporting obligations elevate substitution costs for legacy pigment formulations. Avient Corporation leverages compounding expertise to serve premium pricing tiers in this regulated segment.
India
Domestic tire capacity expansion under the PLI scheme creates localized masterbatch demand requiring BIS-certified pigment systems. Construction equipment manufacturers specify weather-resistant grades for UV-exposed hose installations. Maharashtra and Gujarat industrial corridors attract compounders building captive quality infrastructure for automotive supplier qualification.
Rubber Color Masterbatch Market Vendor Landscape
Player mix skews toward mid-scale compounders with captive dispersion expertise rather than integrated petrochemical giants. The vendor base organizes around three strategic archetypes: automotive-tier specialists with IATF 16949 certification, medical-grade silicone coloration experts with ISO 13485 validation, and electronics-focused custom matchers with spectrophotometry capabilities. Competitive moves concentrate on geographic expansion into India's PLI-driven tire corridor and portfolio diversification toward recycled rubber-compatible formulations.
Within the medical-grade and automotive-tier archetypes, Avient Corporation exemplifies compounding expertise leveraged across regulated segments, while Thai Bamroong Chemicals Co., Ltd. anchors Southeast Asian supply through localized dispersion infrastructure. Shanghai Yuku Chemical Technology Co., Ltd. occupies a position among electronics-grade specialists competing on custom-matched batch capabilities. These three represent the geographic and certification-driven segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Universal Masterbatch LLP |
| Thai Bamroong Chemicals Co., Ltd. |
| Aron Universal Limited |
| Avient Corporation |
| Shanghai Yuku Chemical Technology Co., Ltd. |
| Prisma Color Limited |
| PT Basis Pancakarya |
| Ampacet Corporation |
| Hangzhou Xiaoluan Imp & Exp Co.,Ltd |
| Others |
Supply Flow & Price Mechanics
Eighteen-month reformulation cycles for ECHA SCIP compliance create inventory velocity premiums for compounders with locked-in pigment supply agreements, concentrating margin capture among German corridor specialists while compressing pricing power for spot-market dependent operators.
Pricing Analysis
Surface-treated organic pigment formulations command a technology-generation premium over legacy azo-based systems, with silane-coupled grades capturing higher pricing tiers for 150°C continuous service applications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical grades from IATF 16949 automotive tiers and commodity opaque formulations. Cost compression in standard opaque masterbatches is intensifying because of rare-earth cerium and yttrium oxide price volatility tied to Chinese export quota adjustments. Tire manufacturers exhibit the highest price sensitivity due to volume procurement scale, while medical device OEMs demonstrate the lowest sensitivity given USP Class VI validation requirements.
Supply Chain Analysis
Container availability constraints on Southeast Asian trade lanes expose compounders to monsoon-season logistics disruptions when EPDM and SBR binder supply concentrates among three Thai petrochemical complexes. Raw material dependencies center on rare-earth oxide pigments from Chinese processors, EPDM feedstock from Thai and South Korean crackers, and silane coupling agents from German specialty chemical producers. Single-source vulnerability in rare-earth pigment supply creates exposure to export quota volatility. Distribution runs through direct long-term agreements with automotive OEMs and tire manufacturers, with regional distributors bridging fragmented electronics and construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as REACH substitution mandates force reformulation R&D investment, creating first-mover advantages for compliant compounders before mandatory reporting deadlines eliminate non-compliant alternatives.
For Market Incumbents: Secure IATF 16949 and ISO 13485 certification moats by building captive spectrophotometry labs in Thailand and China to compress delta-E approval cycles. Invest in backward integration into surface-treated organic pigment production to defend margin position against rare-earth cost volatility and emerging custom-matching specialists.
For New Entrants and Emerging Players: ISO 13485 fast-track certification opens premium medical-grade silicone coloration segments where Avient Corporation currently anchors pricing power. Target India's PLI-driven tire corridor with BIS-certified pigment systems for domestic capacity expansion. Pursue direct-to-molder digital platforms linking spectrophotometer data to compounding schedules as the primary go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to divest non-core masterbatch operations lacking regulatory affairs infrastructure for ECHA SCIP compliance. Long-term viability hinges on formulation portfolios compatible with recycled rubber integration and devulcanized EPDM color stabilization. Monitor rare-earth export quota announcements as the critical inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surface-Treated Pigments | Silane coupling agent production in Germany's Cologne-Düsseldorf corridor captures technology-generation premiums. |
| Captive Spectrophotometry Lab Buildout | Thai and Chinese tier-one suppliers accelerate delta-E cycles for 36-month locked-in OEM specifications. |
| ISO 13485 Certification Investment | Medical-grade silicone coloration opens USP Class VI validated pricing tiers beyond commodity tire applications. |
| Recycled Rubber Formulation Development | Devulcanized EPDM compatibility merges circular economy mandates with color stabilization innovation. |
| Direct-to-Molder Digital Platform Launch | Spectrophotometer-linked portals in Japan's Kanto region compress specification windows for electronics-grade compounders. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with rubber compounding plant managers, automotive tier-one procurement leads, medical device regulatory affairs directors, and specialty pigment distribution channel partners; and secondary validation through customs and trade data, ECHA substance evaluation protocols, SEC filings from listed compounders, and automotive OEM supplier qualification databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and delivery mode dimensions.
Across the analysis window, forecasts employed a segmented analytical framework modeling opaque, weather-resistant, transparent, and lightfast product tiers against tire, automotive component, seal, and hose applications. CAGRs derived from elasticity-adjusted demand projections incorporating EPDM infrastructure spending cycles, REACH reformulation timelines, and medical device silicone expansion rates. Industry-specific inputs included pigment loading efficiency curves and vulcanization cycle color stability coefficients.
Decision-makers should treat outputs as directional under assumptions of stable rare-earth export quota regimes and REACH enforcement consistency; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Rubber Foam Materials Market
Rubber
Global Crumb Rubber Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Gum Rosin Market
Rubber
Nitrile Elastomers Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Isobutylene Market
Rubber
Rubber Compound Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Liquid Polybutadiene Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Rubber Carbon Black Market
Rubber
Isoprene Rubber Market
Rubber
Recycled Elastomers Market