
 Lithol Rubine BK Market | 2026-2036
Lithol Rubine BK Market Size, Share, and Industry Trends Forecast 2026-2036
Lithol Rubine BK Market Analytics
Chinese pigment manufacturers are restructuring capacity networks to serve coating and ink formulators across Asia. Shandong Hongrun Huagong leverages integrated azo pigment synthesis to control intermediate supply costs. Zhejiang Shengda Charter Win Chemicals anchors export volumes through specialized powder grades for European compliance markets. BASF competes on REACH-certified dispersion formulations, while Hangzhou Dimacolor differentiates via rapid custom color matching for regional printing houses.
Lithol Rubine BK denotes a calcium-based azo red pigment (CI Pigment Red 57:1) synthesized through diazotization and coupling reactions, yielding a blue-shade red with lightfastness ratings of 4-5 and oil absorption near 45-55 g/100g. The pigment serves primarily in offset printing inks, decorative coatings, and polyolefin plastics where moderate heat stability and vivid color saturation prove essential. Powder grades retain structural dominance in high-volume ink milling operations where dry blending efficiency determines throughput economics. Dispersion formats capture accelerating preference among waterborne coating producers seeking reduced dust exposure and batch consistency. The liquid segment occupies a niche serving continuous-feed inkjet and narrow-web flexographic installations.
REACH registration obligations and EU F-Gas Regulation indirectly tighten environmental benchmarks for pigment manufacturing effluents and solvent recovery systems. China's MIIT enforces GB standards on industrial wastewater discharge from azo dye and pigment facilities, elevating compliance capital for domestic producers. India's BIS certification requirements for imported colorants add procedural friction for non-domestic suppliers. Stakeholders must monitor evolving substance restriction lists and carbon border adjustment mechanisms to preserve market access across jurisdictions.
Market Dynamics
REACH and RoHS compliance thresholds in Europe are forcing azo pigment manufacturers to reconfigure synthesis pathways and effluent treatment systems, compressing margins for non-compliant grades while rewarding cleaner production investments.
Growth Catalysts
- Automotive coatings procurement:OEM specification of high-chroma red pigments for exterior finishes drives volume commitments from tier-one coating suppliers in Germany and Japan.
- REACH-certified dispersion demand:European ink formulators prioritize pre-dispersed pigment concentrates to reduce batch variability and accelerate regulatory documentation.
- China's ink production clustering:Concentrated downstream demand in Zhejiang and Shandong provinces generates economies of scale for domestic azo pigment synthesis.
Market Restraints
- 4-chloro-2-nitroaniline cost volatility:Key diazo component pricing fluctuates with upstream nitrochlorobenzene supply constraints in India and China.
- Heavy metal contamination liability:Trace barium and lead thresholds under EU F-Gas Regulation and REACH Annex XVII require costly purification upgrades.
- Organic pigment substitution:DPP and quinacridone reds encroach on premium decorative coating segments where lightfastness requirements exceed CI Pigment Red 57:1 ratings.
Strategic Opportunities
- Waterborne coating conversion:North American architectural paint manufacturers seek low-VOC compatible dispersion grades to meet EPA emission standards.
- India's BIS certification gap:Domestic testing infrastructure shortages create first-mover advantage for pre-certified import suppliers in specialty packaging inks.
- Digital printing integration:Narrow-web flexographic and inkjet press installations demand liquid pigment preparations with precise particle size distribution control.
Industry Challenges
- Diazotization process engineering expertise:Skilled technicians capable of controlling exothermic coupling reactions remain scarce in emerging production regions.
- Wastewater treatment capex:China's MIIT enforcement of GB 31571-2015 standards mandates anaerobic-aerobic biological treatment systems costing 15-20% of facility investment.
- Substance registration timeline compression:ECHA evaluation periods for new azo pigment variants extend 18-24 months, delaying market entry for reformulated cleaner grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithol Rubine BK Market |
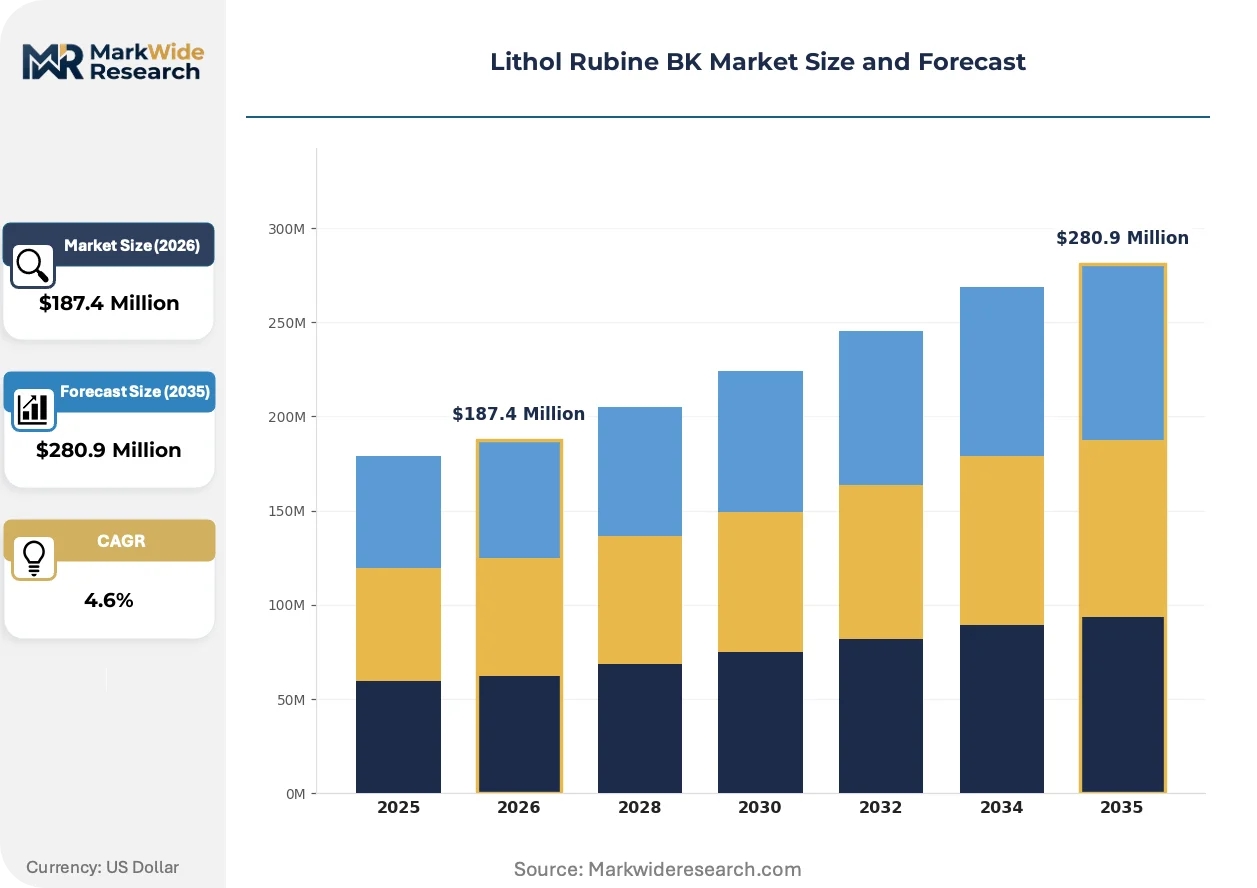
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersions, Powders, Granules, Liquid Application: Coatings, Inks, Plastics, Textiles End User: Chemical Industry, Textile Manufacturers, Printing Companies, Paint Producers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Shandong Hongrun Huagong, Zhejiang Shengda Charter Win Chemicals, Hangzhou Dimacolor, Shandong Yinxing, Dezhou Bige, Tianjin Daming Huaming Chemical, Clariant, Ataman Kimya, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithol Rubine BK Market Evolving Landscape
Dispersion technology and regulatory chemistry are converging to reshape how pigment suppliers capture value, with format innovation outpacing basic synthesis improvements.
Surface-treated pigment preparations is unifying particle stabilization and regulatory pre-certification into single-supply offerings. Waterborne coating manufacturers in Italy and the Netherlands adopt these grades to eliminate in-house dispersion equipment and accelerate batch release. This unifying trend compresses the supplier base toward integrated dispersion specialists capable of certifying full formulation compliance.
EU F-Gas Regulation amendments tighten solvent recovery mandates for azo pigment manufacturing effluents. German production facilities face mandatory closed-loop dichloromethane recovery systems by 2027. Pigment dispersion houses serving European ink formulators now prioritize aqueous milling technologies to preempt regulatory displacement.
Specification-driven procurement now dominates coating raw material selection, with automotive OEMs mandating full substance disclosure down to 100 ppm thresholds. Tier-one suppliers in Stuttgart and Detroit reject conventional pigment powders lacking structured regulatory data packages. This behavioral shift concentrates volume with dispersion houses offering embedded compliance documentation rather than commodity pigment traders.
Lithol Rubine BK Market Segmentation
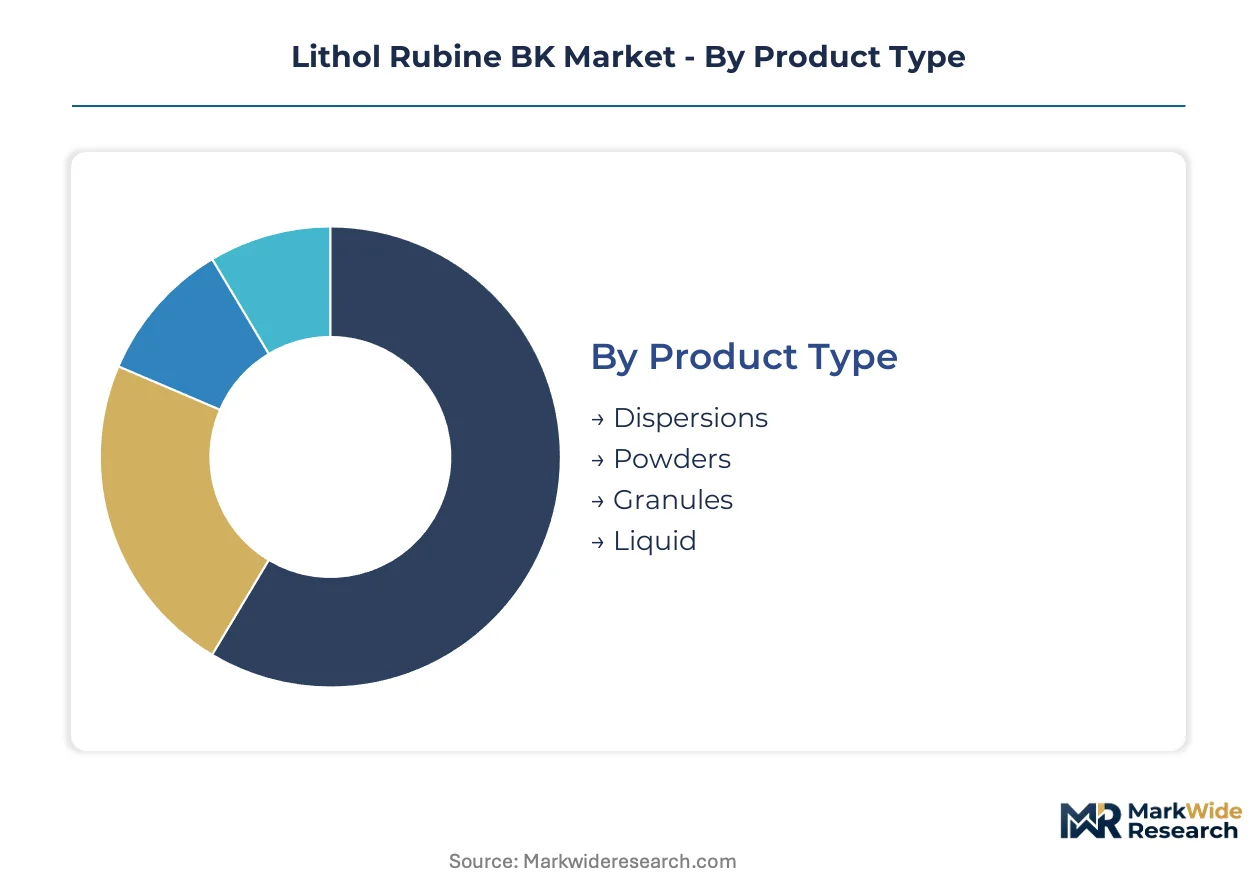
Format selection determines batch economics and regulatory compliance pathways for azo pigment procurement. Specification requirements vary sharply between high-volume ink milling and precision coating applications.
Product Type:
Particle preparation technology separates commodity procurement from value-added supply relationships.
- Powders:Dry pigment grades dominate offset ink production where ball mill dispersion efficiency governs throughput economics. High-volume printing houses in China's Shandong and Zhejiang clusters favor powder formats for direct incorporation into lithographic ink bases, though dust exposure drives investment in local exhaust ventilation.
- Dispersions:Pre-milled aqueous and solvent-based concentrates capture accelerating preference among waterborne coating manufacturers seeking REACH-compliant documentation packages. European architectural paint formulators in the Netherlands and Italy source dispersion grades to eliminate in-house milling equipment and accelerate batch release timelines.
- Liquid:Pumpable preparations serve continuous-feed inkjet and narrow-web flexographic installations where precise viscosity control proves essential. Digital press operators specify liquid formats for automated dosing systems.
- Granules:Low-dust agglomerated grades address occupational exposure concerns in plastics compounding operations. Polyolefin masterbatch producers favor granule formats for direct extruder feeding.
Mature deployment sits with powders. Newer deployment is concentrated in dispersions.
Application:
End-use performance specifications dictate pigment selection across durability, heat stability, and migration resistance requirements.
- Inks:Offset lithographic printing consumes the largest volume share, with publication and packaging segments specifying CI Pigment Red 57:1 for blue-shade red reproduction. Water-based flexographic inks for corrugated packaging represent the steepest expansion trajectory as brand owners mandate heavy metal-free formulations.
- Coatings:Decorative architectural paints and automotive refinish systems demand dispersion-grade pigments with documented REACH compliance. German OEM coating suppliers specify full substance disclosure down to 100 ppm thresholds.
- Plastics:Polyolefin masterbatch applications require heat stability above 220°C for injection molding operations. Moderate lightfastness ratings limit use to interior applications.
- Textiles:Niche consumption in synthetic fiber coloration where migration resistance proves critical. Screen printing on polyester fabrics drives intermittent demand.
Volume concentration favors inks. Margin expansion concentrates in coatings.
End User:
Procurement sophistication varies from specification-driven automotive supply chains to price-sensitive commodity buyers.
- Printing Companies:Commercial offset and packaging converters drive powder-grade volume through centralized purchasing consortia. Large Japanese printing groups negotiate long-term azo pigment supply agreements.
- Paint Producers:Architectural and industrial coating manufacturers prioritize dispersion formats with embedded regulatory documentation. Italian decorative paint specialists source REACH-certified concentrates from integrated suppliers.
- Chemical Industry:Masterbatch compounders and specialty resin formulators require granule and powder grades with consistent particle size distribution for automated processing.
- Textile Manufacturers:Synthetic fiber producers and fabric finishers specify pigment preparations with demonstrated migration resistance under thermal fixation conditions.
Contract discipline sits with paint producers. Spot purchasing concentrates in textile manufacturers.
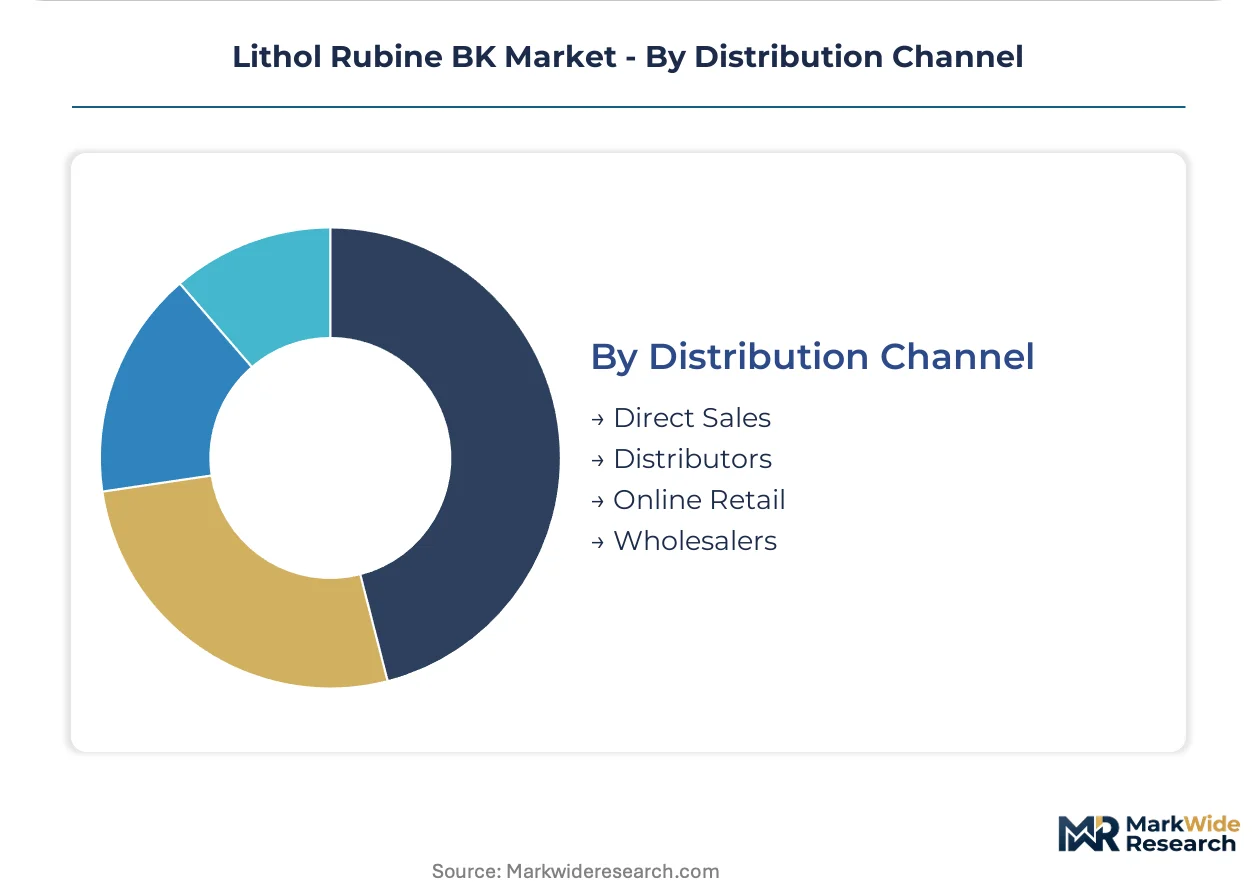
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to production clusters.
- Distributors:Regional pigment distributors aggregate small-batch orders from specialty ink and coating formulators. German chemical distributors maintain stocked inventory of REACH-compliant azo pigment grades for just-in-time delivery.
- Direct Sales:Large-volume coating and ink manufacturers negotiate direct supply agreements with Shandong and Zhejiang producers. Annual volume commitments secure preferential pricing and dedicated production slots.
- Wholesalers:Commodity-grade powder transactions flow through pigment wholesalers serving mid-tier printing houses. Price transparency pressures margins in this channel.
- Online Retail:Sample quantities and small-lot specialty grades move through B2B platforms. Technical pigment specifications require pre-sale consultation, limiting pure online penetration.
Relationship depth sits with direct sales. Transaction velocity concentrates in distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
4-chloro-2-nitroaniline synthesis clusters in Shandong and Zhejiang provinces anchor Asia-Pacific pigment supply chains. REACH-certified dispersion demand in Germany and regulatory tightening across India redirect procurement toward compliant-grade suppliers.
China
Offset ink manufacturers in Zhejiang and Shandong provinces drive powder-grade consumption through consolidated purchasing. MIIT enforces GB 31571-2015 wastewater standards, elevating capital requirements for azo pigment facilities. Hangzhou dispersion specialists serve waterborne coating formulators seeking reduced dust exposure.
Germany
Automotive OEM coating suppliers specify full substance disclosure down to 100 ppm thresholds for exterior finish pigments. ECHA REACH registration obligations compress margins for non-compliant grades while rewarding cleaner production investments. Stuttgart-based tier-one suppliers mandate embedded compliance documentation from dispersion houses.
India
Packaging ink formulators in Maharashtra and Gujarat seek pre-certified import grades to bypass BIS testing infrastructure shortages. Central pollution control mandates tighten effluent discharge from chemical manufacturing zones. Mumbai specialty converters negotiate direct supply agreements with Shandong producers for annual volume commitments.
United States
Architectural paint manufacturers in Ohio and Pennsylvania pursue low-VOC compatible dispersion grades to meet EPA emission standards. State-level air quality regulations accelerate waterborne coating conversion across industrial Midwest markets. Cleveland-area coating compounders eliminate in-house milling equipment through pre-dispersed pigment procurement.
Japan
Commercial printing groups in Tokyo and Osaka negotiate long-term azo pigment supply agreements for offset lithographic operations. METI chemical substance management frameworks align with REACH-equivalent disclosure requirements. Yokohama ink formulators prioritize REACH-certified concentrates to reduce batch variability.
Lithol Rubine BK Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue dispersion specialization and regulatory pre-certification. The vendor base stratifies between integrated synthesis operators and downstream formulation specialists. Three archetypes dominate: Shandong-Zhejiang integrated manufacturers controlling intermediate supply, European dispersion houses certifying REACH compliance, and regional custom color matchers serving printing clusters. Capacity expansion and backward integration into diazo component production represent the dominant competitive vectors.
Within the integrated synthesis tier, Shandong Hongrun Huagong and Zhejiang Shengda Charter Win Chemicals exemplify Chinese producers leveraging captive intermediate supply. Hangzhou Dimacolor occupies a position among regional specialists emphasizing rapid custom color matching. BASF represents the European archetype anchoring REACH-certified dispersion formulations. These three entities collectively illustrate the geographic and functional segmentation shaping procurement decisions across coating and ink value chains.
| Leading Market Players |
|---|
| Shandong Hongrun Huagong |
| Zhejiang Shengda Charter Win Chemicals |
| Hangzhou Dimacolor |
| Shandong Yinxing |
| Dezhou Bige |
| Tianjin Daming Huaming Chemical |
| Clariant |
| Ataman Kimya |
| BASF |
| Others |
Value Network & Pricing Analysis
4-chloro-2-nitroaniline cost volatility cascades through Shandong and Zhejiang synthesis clusters into three-tier pricing stratification across powder, dispersion, and liquid pigment grades. REACH-compliant dispersion premiums widen against commodity powder benchmarks as European ink formulators absorb documentation costs.
Pricing Analysis
Service-bundling separates REACH-certified dispersion houses from commodity powder traders, with compliance documentation and technical support embedded in premium tier pricing. Price differentiation hinges on certification grade and volume scale, with annual offtake commitments securing preferential slotting at integrated Chinese producers. Cost compression in standard powder grades is intensifying because nitrochlorobenzene feedstock constraints in India elevate diazo component costs. Spot purchasers in mid-tier printing houses exhibit highest price sensitivity, while German automotive OEM coating suppliers demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Diazotization chemistry rests on captive 4-chloro-2-nitroaniline production in Shandong and Zhejiang provinces, with Indian and German facilities serving secondary supply roles. Critical inputs span nitrochlorobenzene intermediates, coupling agents, and calcium salt precipitation reagents. Single-source vulnerability concentrates in Shandong intermediate synthesis, where environmental enforcement under MIIT GB standards threatens capacity continuity. Distribution runs through direct sales agreements for large-volume coating manufacturers and regional distributors for specialty ink formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized diazo coupling capacity constraints prop pricing power for integrated producers, with wastewater treatment capex requirements blocking marginal entrants from scaling synthesis operations.
For Market Incumbents: Extend REACH-certified dispersion portfolios to capture specification-driven procurement from Stuttgart and Detroit automotive coating suppliers. Deepen backward integration into nitrochlorobenzene intermediates to buffer 4-chloro-2-nitroaniline cost volatility. Prioritize aqueous milling technology investments to preempt EU F-Gas Regulation displacement of solvent-based processes. For New Entrants and Emerging Players: Launch via BIS pre-certified import channels targeting Maharashtra and Gujarat packaging ink formulators constrained by domestic testing infrastructure gaps. Concentrate initial penetration on waterborne coating dispersion grades for North American architectural paint manufacturers seeking EPA-compliant low-VOC inputs. Emphasize rapid custom color matching capabilities to differentiate from established powder-grade commodity suppliers. For Investors and Strategic Acquirers: ECHA evaluation period extensions for new azo pigment variants is the leading indicator that regulatory chemistry capabilities will concentrate value in integrated dispersion specialists. Five-to-ten year viability favors producers with captive intermediate supply and embedded compliance documentation infrastructure. Target acquisition archetypes include Hangzhou-region dispersion houses with aqueous milling technology and established European pigment registration portfolios. Watch MIIT enforcement intensity against Shandong wastewater discharge as capacity constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrochlorobenzene | Captive 4-chloro-2-nitroaniline supply buffers Shandong producers against Indian feedstock volatility. |
| Aqueous Milling Technology Deployment | Preempts EU F-Gas Regulation solvent recovery mandates for German dispersion facilities. |
| BIS Pre-Certification Investment | Creates first-mover access to Maharashtra packaging ink formulators facing testing infrastructure gaps. |
| REACH Registration Portfolio Expansion | Locks in Stuttgart automotive OEM specification requirements for exterior finish pigments. |
| Long-Term Supply Agreements with Japanese Printing Groups | Secures volume commitments from Tokyo and Osaka commercial offset operations. |
Research Methodology
Trade flow databases, ECHA registration filings, and MIIT environmental enforcement records formed the secondary backbone for supply-side calibration. Primary interviews with azo pigment plant managers, coating procurement leads at German Tier 1 suppliers, ink formulator technical directors, and distribution channel partners in Zhejiang and Shandong provinces validated production cost structures and specification requirements. Bottom-up capacity modeling triangulated against top-down end-use consumption estimates across offset printing, automotive coatings, and polyolefin masterbatch applications.
Historical capacity utilization and pricing trendlines anchored the projection framework across the analysis window. Segmentation dimensions spanned product format, application end-use, and regional regulatory compliance tier. CAGRs derived from coupling volume forecasts with value-per-ton assumptions for powder versus dispersion grade premiums. Forecast inputs incorporated diazo component cost trajectories and REACH registration timeline compression effects on new grade commercialization.
The model assumes a particular technology adoption path for aqueous dispersion processes; alternative pathways for solvent-based milling with closed-loop recovery would alter the outlook for European production economics. Forecasts reflect assumptions regarding MIIT enforcement continuity, ECHA evaluation period stability, and nitrochlorobenzene supply chain resilience. Shifts in automotive OEM specification thresholds, Indian BIS certification infrastructure development, and carbon border adjustment mechanism scope warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Aluminum Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Global Paper Dyes Market
Dyes and Pigments
Global White Inorganic Pigments Market