
 Pigment Additive Film Market | 2026-2036
Pigment Additive Film Market Size, Share, and Industry Trends Forecast 2026-2036
Pigment Additive Film Market Analytics
Flexible food packaging is restructuring demand toward high-clarity, UV-resistant polyethylene films that preserve shelf appeal. DIC Corporation leverages its integrated pigment and resin capabilities to dominate Asian supply chains for multilayer packaging. BASF SE anchors European demand through specialized antioxidant masterbatches that extend film service life in agricultural applications. Sun Chemical Corporation differentiates via water-based dispersion technologies that reduce volatile organic compound exposure in printing ink formulations.
Pigment additive film denotes a polymer substrate incorporating colorants, stabilizers, or functional modifiers at concentrations typically ranging from 0.5% to 5% by weight, extruded or cast to achieve controlled opacity, weather resistance, or aesthetic properties for industrial lamination and surface protection. Color additives command the largest volume share within product type classifications, though UV stabilizers are gaining fastest in agricultural and construction films where photodegradation resistance extends replacement cycles. Among material substrates, polypropylene films carry premium positioning in automotive interior applications, while polyethylene grades sustain volume leadership across consumer goods packaging due to cost-efficient blown-film processability.
REACH registration requirements and RoHS substance restrictions are tightening permissible thresholds for cadmium and lead-based pigments across European converter operations, compelling reformulation investments. The EPA oversees analogous heavy-metal limitations in US interstate commerce, while China's GB standards mandate migration testing for food-contact film layers. Stakeholders must monitor evolving substance restriction timelines and pre-qualify alternative pigment systems before existing formulations lose market access authorization.
Market Dynamics
REACH restrictions on heavy-metal pigments are forcing European converters to rebuild formulation roadmaps from the ground up, redirecting procurement toward organic alternatives while automotive interior specifications tighten in Germany.
Growth Catalysts
- UV-stabilized polyethylene grades:Packaging film converters are expanding procurement of these materials for food-contact applications where shelf appeal preservation drives specification upgrades.
- REACH pigment restrictions:The regulatory pressure on cadmium and lead-based colorants is accelerating reformulation investments toward compliant organic pigment systems.
- Agricultural film replacement cycles:Photodegradation resistance requirements in farming applications are pulling demand for advanced UV stabilizer masterbatches.
Market Restraints
- Titanium dioxide feedstock volatility:White pigment input costs fluctuate with ilmenite and rutile ore availability, squeezing margin predictability for film compounders.
- Specialized additive supplier concentration:Antioxidant masterbatch production clusters in Western Europe, creating geographic vulnerability for Asian packaging converters.
- Migration testing bottlenecks:China's GB standards for food-contact film layers impose extended certification timelines that delay new formulation launches.
Strategic Opportunities
- Water-based dispersion technologies:VOC reduction mandates in printing ink applications are opening white space for solvent-free pigment delivery systems.
- Multilayer packaging integration:The convergence of barrier film engineering with functional additive loading enables premium positioning in Asian supply chains.
- Automotive interior specification tightening:Germany's OEMs are mandating higher heat-resistance grades for polypropylene films, creating tier-one supplier upgrade opportunities.
Industry Challenges
- Reformulation chemistry expertise:Heavy-metal pigment phase-outs require rare compounding skills in organic colorant dispersion and polymer compatibility.
- Pre-qualification timeline compression:Alternative pigment systems must complete substance restriction compliance before existing formulations lose market access authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigment Additive Film Market |
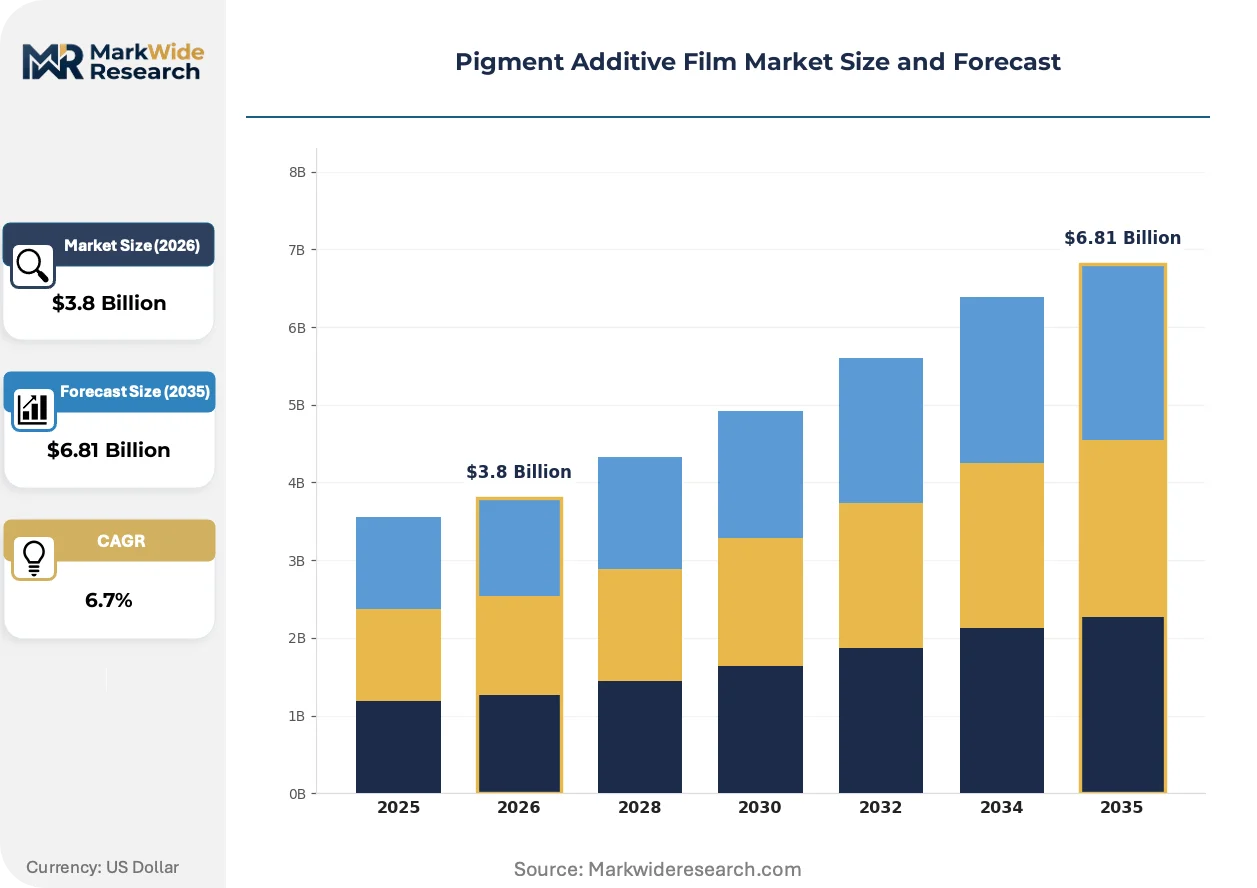
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Additives, Opacifiers, UV Stabilizers, Antioxidants Application: Packaging Films, Coatings, Printing Inks, Adhesives Material: Polyethylene, Polypropylene, PVC, PET End User: Consumer Goods, Automotive, Electronics, Construction |
| Companies Covered | DIC Corporation, Sun Chemical Corporation, BASF SE, The Lubrizol Corporation, Ampacet Corporation, Clariant AG, Evonik Industries AG, Toyo Ink SC Holdings Co., Ltd., Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigment Additive Film Market Evolving Landscape
Formulation science is pivoting toward bio-based dispersants and non-heavy-metal colorants as regulatory chemistry constraints tighten across major converter markets.
Water-based pigment dispersions are overtaking solvent-borne systems in flexible packaging printing. Food-contact film laminators in North America and Western Europe are specifying these systems to meet VOC exposure limits. The shift is compressing demand for traditional solvent carriers and reallocating R&D budgets toward aqueous rheology modifiers.
ECHA's REACH substance restriction timelines are tightening cadmium and lead pigment thresholds across European converter operations. Compounders must pre-qualify replacement organic systems ahead of authorization sunsets. Agricultural and construction film segments face the steepest compliance costs due to weathering-grade performance requirements.
Specification-driven procurement is consolidating buyer power among multinational packaging groups. Regional converters are losing access to tier-one masterbatch supply as volume commitments concentrate with integrated resin-pigment producers. The pattern is most visible in Asian flexible packaging hubs where DIC Corporation's captive supply chains dominate multilayer film procurement.
Pigment Additive Film Market Segmentation
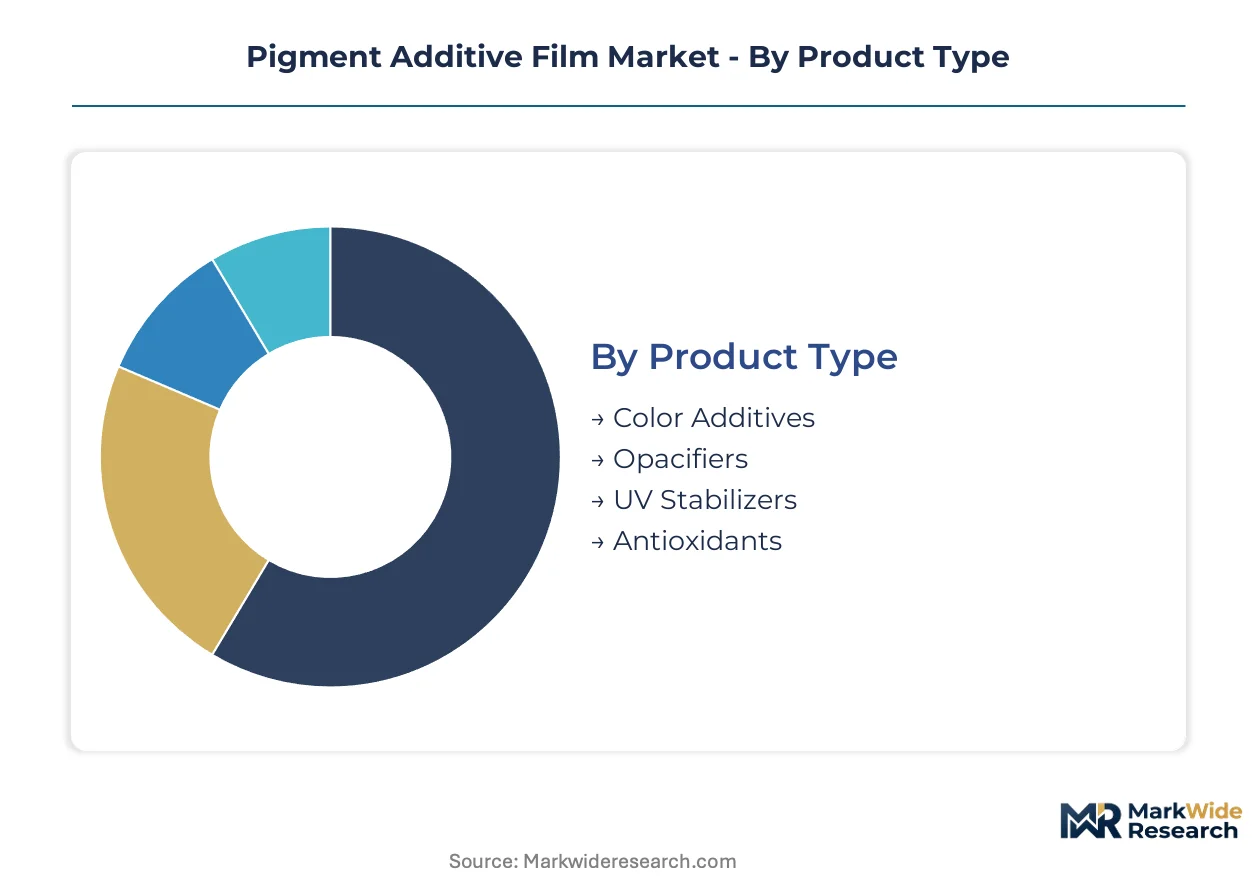
Pigment additive film formulations vary sharply in technical complexity and margin profile across functional categories. Specification requirements from automotive OEMs and food-contact regulators create divergent customization pressures that reshape procurement patterns.
Product Type:
Standardized commodity pigments compete with engineered additive packages calibrated to exacting performance thresholds across this spectrum.
- Color Additives:Organic and inorganic pigment concentrates delivering controlled hue, saturation, and opacity at loadings typically between 0.5% and 3% by film weight. Demand concentrates in German automotive interior specifications where heat-resistant polypropylene films require cadmium-free reformulation under REACH timelines.
- UV Stabilizers:Hindered amine light stabilizers and UV absorber masterbatches engineered to extend polymer service life under photodegradation stress. Agricultural film replacement cycles in outdoor applications are pulling procurement toward high-performance grades that justify premium positioning.
- Opacifiers:Titanium dioxide and alternative white pigment dispersions controlling light transmission and print substrate contrast.
- Antioxidants:Phenolic and phosphite stabilizer systems interrupting thermal oxidation chains during processing and end-use exposure.
Most installed capacity flows through Color Additives. Expansion is steepest in UV Stabilizers.
Application:
Volume concentration versus value capture diverges markedly across film conversion, surface coating, and ink deposition processes.
- Packaging Films:Multilayer polyethylene and polypropylene structures incorporating functional additives for barrier, aesthetic, and shelf-life extension. Food-contact laminators in North America are specifying high-clarity UV-stabilized grades to meet FDA migration thresholds while preserving visual appeal.
- Printing Inks:Pigment dispersions in solvent-borne, water-based, or UV-curable carrier systems for flexible substrate decoration. Water-based technologies are gaining share fastest as VOC reduction mandates compress demand for traditional solvent carriers.
- Coatings:Protective and decorative surface layers applied to film substrates or end-use articles.
- Adhesives:Tinted and stabilized bonding layers for lamination and assembly operations.
Blown-film processability sustains Packaging Films as the volume anchor. Regulatory chemistry constraints are accelerating reformulation investment in Printing Inks.
Material:
Cost-efficiency imperatives clash with specification premiums across commodity and engineering polymer substrates.
- Polyethylene:Low-density and linear-low-density grades dominating blown-film packaging through cost-efficient processability and broad additive compatibility. Consumer goods packaging converters are expanding procurement of UV-stabilized polyethylene for food-contact applications where shelf appeal drives specification upgrades.
- Polypropylene:Oriented and cast films commanding premium positioning in automotive interior applications. Germany's OEMs are mandating higher heat-resistance grades that tighten supplier qualification thresholds.
- PVC:Rigid and flexible calendered or extruded films with established pigment dispersion infrastructure.
- PET:Biaxially oriented films with superior dimensional stability and optical clarity for demanding lamination.
Polyethylene carries the broadest installed base. Polypropylene captures the steepest specification-driven margin expansion.
End User:
Regulatory exposure and performance liability create divergent risk-reward profiles across downstream verticals.
- Automotive:Interior trim films, instrument panel skins, and surface protection layers subject to OEM durability and emissions specifications. German tier-one suppliers are consolidating procurement with integrated resin-pigment producers capable of meeting tightening heat-resistance and fogging standards.
- Consumer Goods:Flexible packaging, labels, and decorative films for food, personal care, and household products. REACH and FDA migration requirements are redirecting formulation roadmaps toward pre-qualified organic pigment systems ahead of heavy-metal authorization sunsets.
- Construction:Geomembranes, vapor barriers, and protective sheeting exposed to weathering degradation.
- Electronics:Insulation films, display components, and surface protection with dielectric or optical functional requirements.
Consumer Goods channels the highest unit volume. Automotive commands the most stringent qualification barriers and attendant margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing pigment additive film production toward jurisdictions with lower compliance burdens, while REACH-mandated reformulation costs concentrate high-value formulation expertise in Western Europe.
United States
Food-contact film laminators are specifying UV-stabilized polyethylene grades to meet FDA migration thresholds for flexible packaging. The EPA enforces heavy-metal limitations in interstate commerce that parallel European restrictions. Converter operations cluster in the Midwest industrial corridor around Chicago, where blown-film capacity serves North American consumer goods packaging demand.
Germany
Automotive OEMs are tightening heat-resistance specifications for polypropylene interior films that command premium positioning. ECHA REACH substance restrictions are accelerating cadmium and lead pigment phase-outs with compressed pre-qualification timelines. The Baden-Württemberg automotive supplier belt is consolidating procurement with integrated resin-pigment producers capable of meeting fogging and durability standards.
China
Multilayer packaging converters are expanding capacity for high-clarity films serving export-oriented food-contact applications. GB standards mandate extended migration testing timelines that delay new formulation launches. The Yangtze River Delta manufacturing belt around Shanghai anchors pigment dispersion capacity for Asian flexible packaging supply chains.
Japan
Specialty film producers are developing heat-resistant grades for automotive and electronics applications with stringent optical requirements. METI oversees chemical substance management frameworks that align with REACH principles. The Chubu region around Nagoya hosts precision film extrusion operations serving tier-one automotive component suppliers.
India
Packaging converters are scaling procurement of UV-stabilized polyethylene for domestic consumer goods and agricultural film segments. BIS certification requirements for food-contact materials are tightening import substitution pressures. The Gujarat chemical manufacturing corridor is attracting masterbatch compounding investments to serve South Asian flexible packaging demand.
Pigment Additive Film Market Competitive Landscape
REACH-driven reformulation investments dominate the current landscape, compelling compounders to rebuild technical capabilities ahead of authorization sunsets. The market structure separates integrated resin-pigment producers from specialized masterbatch formulators and regional distribution-focused converters. Three archetypes occupy distinct positions: chemical conglomerates with captive raw material access, independent additive specialists with formulation expertise, and film converters backward-integrating into compounding. Consolidation through acquisition and geographic expansion represent the primary competitive vectors.
Among integrated chemical conglomerates, DIC Corporation and BASF SE exemplify archetypes combining resin production with pigment and stabilizer formulation capabilities. Sun Chemical Corporation occupies a position within the specialized dispersion technology tier, representing water-based system expertise. These three anchors illustrate how regulatory chemistry constraints are rewarding players with pre-qualified organic pigment portfolios and multilayer packaging integration capabilities.
| Leading Market Players |
|---|
| DIC Corporation |
| Sun Chemical Corporation |
| BASF SE |
| The Lubrizol Corporation |
| Ampacet Corporation |
| Clariant AG |
| Evonik Industries AG |
| Toyo Ink SC Holdings Co., Ltd. |
| Avient Corporation |
| Others |
Value Network & Pricing Analysis
Formulation chemist clusters in the Baden-Württemberg automotive corridor anchor Europe's highest labor-cost tier, widening the spread between REACH-compliant organic pigment formulations and commodity heavy-metal alternatives sourced from lower-cost Asian compounding centers.
Pricing Analysis
Distributor margins on antioxidant masterbatches compress pricing transparency for mid-tier packaging converters. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade heat-resistant polypropylene films from agricultural UV-stabilized polyethylene and commodity color concentrates. Price differentiation hinges on REACH certification tier and volume scale commitments. Cost compression in standard-grade titanium dioxide dispersions is intensifying because ilmenite ore supply volatility feeds through to compounder input costs. Agricultural film converters exhibit the sharpest price sensitivity, while German automotive tier-one suppliers prioritize specification compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston orchestrate hub-and-spoke patterns for antioxidant masterbatch flows to blown-film converters. Supply concentrates in Germany, China, and Japan, with pigment dispersion capacity clustering around the Yangtze River Delta and the Chubu region. Raw material dependencies rest on ilmenite and rutile ore for titanium dioxide, hindered amine light stabilizer precursors from South Korean petrochemical complexes, and organic pigment intermediates from Indian specialty chemical manufacturers. Single-source vulnerability in hindered amine light stabilizer supply creates chokepoint exposure. Distribution runs through integrated resin-pigment producers directly to multinational packaging groups, bypassing traditional masterbatch distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as specification tightening in German automotive interior films redirects procurement toward pre-qualified organic pigment systems with embedded compliance premiums.
For Market Incumbents: Lock in captive supply relationships with Yangtze River Delta multilayer packaging converters before REACH authorization sunsets eliminate heavy-metal formulation alternatives. Backward integration into hindered amine light stabilizer production mitigates single-source supply risk from South Korean petrochemical suppliers. Certification investment in FDA food-contact migration testing accelerates pre-qualification timelines for North American laminator procurement. For New Entrants and Emerging Players: Launch via water-based dispersion technology partnerships with North American flexible packaging printers seeking VOC reduction compliance. Agricultural film replacement cycles in India offer the most penetrable white space, with BIS certification requirements creating import substitution headroom against established European suppliers. Target domestic Indian masterbatch compounding through Gujarat chemical corridor joint ventures to bypass extended GB standards migration testing bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among independent additive specialists with stranded heavy-metal pigment portfolios facing REACH authorization cliffs. Long-term viability across the projection horizon favors compounders with pre-qualified organic colorant libraries and automotive OEM direct qualification relationships. Acquisition target archetype: mid-cap German automotive film formulators with captive fogging and heat-resistance testing capabilities. Watch ECHA substance restriction timeline acceleration as the inflection signal for distressed portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hindered Amine Light Stabilizers | Captive supply from South Korean petrochemical feedstock reduces margin volatility from single-source exposure. |
| REACH-Compliant Organic Pigment Pre-Qualification | Early authorization completion locks in German automotive tier-one supplier procurement before competitor reformulation. |
| Water-Based Dispersion Technology Launch | VOC reduction compliance opens North American flexible packaging printer specifications previously closed to solvent carriers. |
| Gujarat Chemical Corridor Joint Venture | Domestic Indian compounding capacity bypasses China's GB standards migration testing delays for South Asian agricultural film demand. |
| Automotive Interior Film Fogging Certification Investment | OEM direct qualification in Baden-Württemberg supplier belt secures premium positioning as heat-resistance specifications tighten. |
Research Methodology
Bottom-up packaging film and automotive interior modeling reconciled against top-down pigment masterbatch production tracking forms the analytical core of this study. Primary interviews with blown-film plant managers, automotive OEM procurement leads, masterbatch R&D directors, and flexible packaging laminator technical buyers combined with secondary validation from ECHA REACH substance restriction databases, FDA food-contact migration threshold filings, customs trade data on titanium dioxide feedstock flows, and SEC 10-K disclosures from integrated chemical conglomerates. Triangulation between demand-side specification requirements and supply-side capacity announcements anchors volume estimates.
Historical trendline analysis of automotive interior film specification evolution and agricultural replacement cycle patterns informed the projection framework. Segmentation dimensions modeled include functional additive category, polymer substrate type, end-use vertical, and regional regulatory cluster. CAGRs derived from installed capacity expansion announcements cross-referenced against end-user procurement intention surveys. Forecast inputs incorporated REACH authorization sunset timelines, GB standards migration testing duration assumptions, and ilmenite ore supply elasticity estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA substance restriction timelines or ilmenite supply disruptions. Outputs reflect documented assumptions on regulatory enforcement consistency and polymer substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Laser Sensitive Pigments Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Azo Pigments Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Cacao Husk Pigment Market