
 Pharmaceutical Dyes Market | 2026-2036
Pharmaceutical Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Dyes Market Analytics
Buyer concentration among pharmaceutical manufacturers is pivoting as large contract development and manufacturing organizations consolidate procurement, while mid-tier biotechnology firms fragment demand across specialized suppliers. Clariant AG leverages its pigment chemistry heritage to sustain premium positioning in tablet coating applications. Dynemic Products Ltd. anchors its competitive stance through deep specialization in lake pigments and aluminum-based colorants for oral solid dosages. KISCO LTD competes primarily on manufacturing scale across Asian pharmaceutical manufacturing hubs.
Pharmaceutical dyes encompass colorants specifically formulated for drug delivery systems, typically meeting purity specifications exceeding food-grade standards with heavy metal limits below 10 ppm and complete batch certification for identity and strength. These substances serve the essential industrial purpose of enabling product identification, enhancing patient compliance through visual differentiation, and supporting brand protection against counterfeiting. Synthetic dyes currently dominate volume consumption in injection coloring due to their cost efficiency and color consistency, while natural dyes represent the fastest-expanding margin pool as clean-label formulation requirements intensify across European and North American regulatory jurisdictions. Powder formulations retain structural importance for capsule filling operations, though liquid dye suspensions are gaining share in continuous manufacturing lines where dosing precision and dust containment prove critical.
FDA color certification under 21 CFR 74 and 81 governs batch-by-batch safety verification for all synthetic dyes entering U.S. drug products, while REACH registration and the EU's updated MDR framework impose additional substance disclosure burdens on European suppliers. India's CDSCO aligns with ICH Q3D guidelines on elemental impurities, creating a convergent regulatory baseline that multinational dye vendors must satisfy across multiple jurisdictions. Stakeholders should monitor evolving pharmacopeial harmonization between USP-NF and EP monographs, as divergence in dye specification limits would fragment compliance architectures and reshape supplier qualification costs.
Market Dynamics
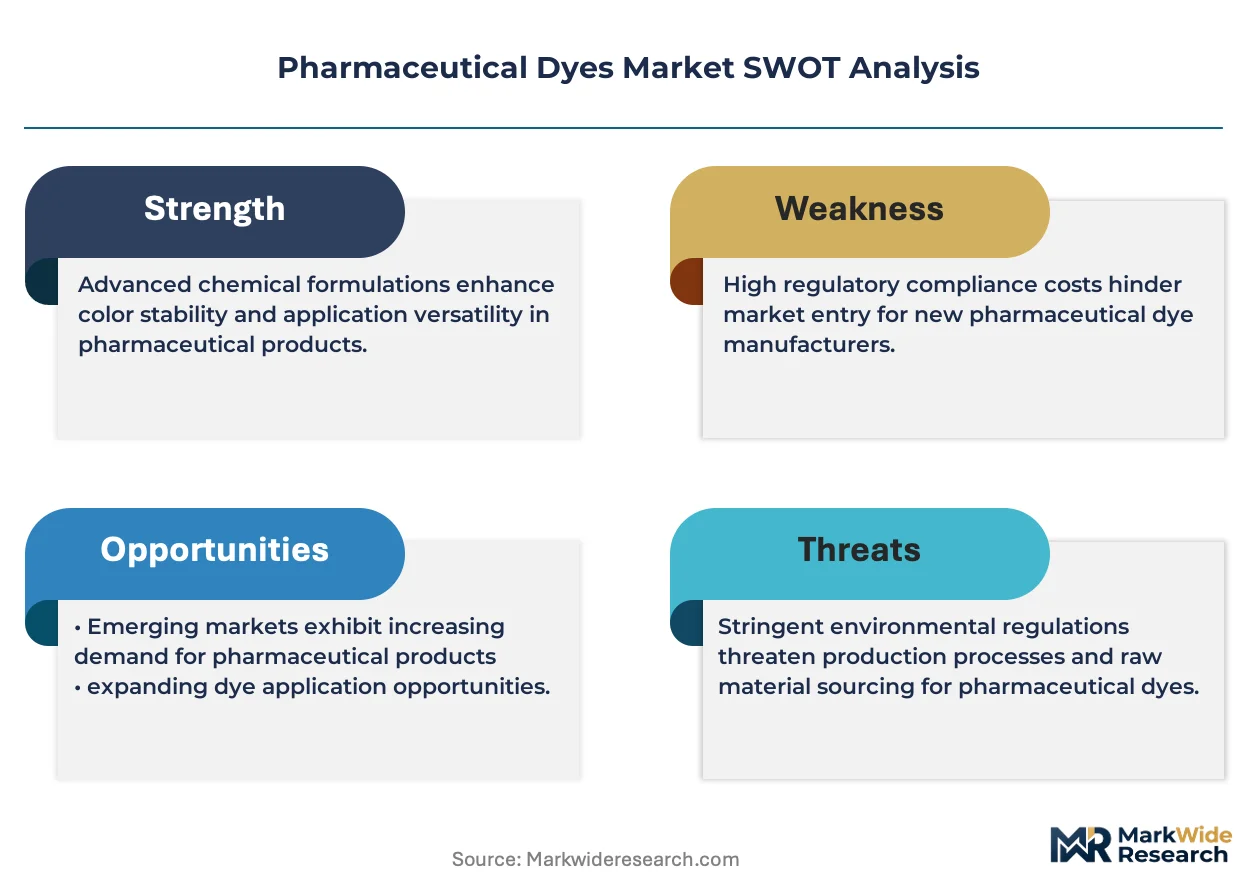
Contract development and manufacturing organizations are consolidating procurement power while tightening purity specifications, forcing dye suppliers to absorb certification costs or cede volume to vertically integrated competitors.
Growth Catalysts
- CDSCO alignment with ICH Q3D:India's adoption of harmonized elemental impurity standards reduces duplicative testing for multinational suppliers, accelerating qualification timelines for Hyderabad and Ahmedabad manufacturing clusters.
- Continuous manufacturing adoption:Liquid dye suspensions enable real-time dosing precision in continuous tablet coating lines, displacing powder formulations that require dust containment infrastructure.
- EMA synthetic dye purity guidelines:Tightening European specifications for heavy metal limits below 10 ppm creates premium pricing tiers for certified batches, rewarding suppliers with in-house analytical capabilities.
Market Restraints
- Titanium dioxide substitution pressure:EFSA's 2021 reclassification of TiO2 as a suspected carcinogen forces reformulation of white pigment coatings, raising R&D costs and batch failure rates during transition periods.
- Aluminum lake supply concentration:Three Indian manufacturers control 70% of global aluminum-based colorant capacity, exposing formulators to input volatility when BIS certification delays interrupt shipments.
- FDA batch certification backlog:Color additive certification under 21 CFR 74 currently requires 45-60 day review cycles, constraining just-in-time inventory strategies for U.S.-bound oral solid dosages.
Strategic Opportunities
- Clean-label natural dye penetration:European and North American regulatory jurisdictions are mandating ingredient transparency, opening margin pools for spirulina-derived blues and beetroot reds in pediatric formulations.
- PLI scheme localization:India's production-linked incentive scheme for active pharmaceutical ingredients extends to excipient manufacturing, enabling captive dye production for domestic formulation exporters.
- Anti-counterfeiting traceability:Covert spectral taggants embedded in coating dyes allow brand authentication through handheld scanners, creating recurring revenue streams beyond commodity colorant sales.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS operators capable of validating heavy metal content below 10 ppm command 40% salary premiums, constraining quality control throughput at mid-tier suppliers.
- Legacy ERP integration friction:Continuous manufacturing lines require real-time dye dosing synchronization with MES platforms, forcing capital-intensive upgrades at facilities running 1990s-era batch management systems.
- REACH substance disclosure complexity:Full chemical composition reporting for dye intermediates exposes proprietary formulation knowledge, deterring European market entry by specialized Asian lake pigment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Dyes Market |
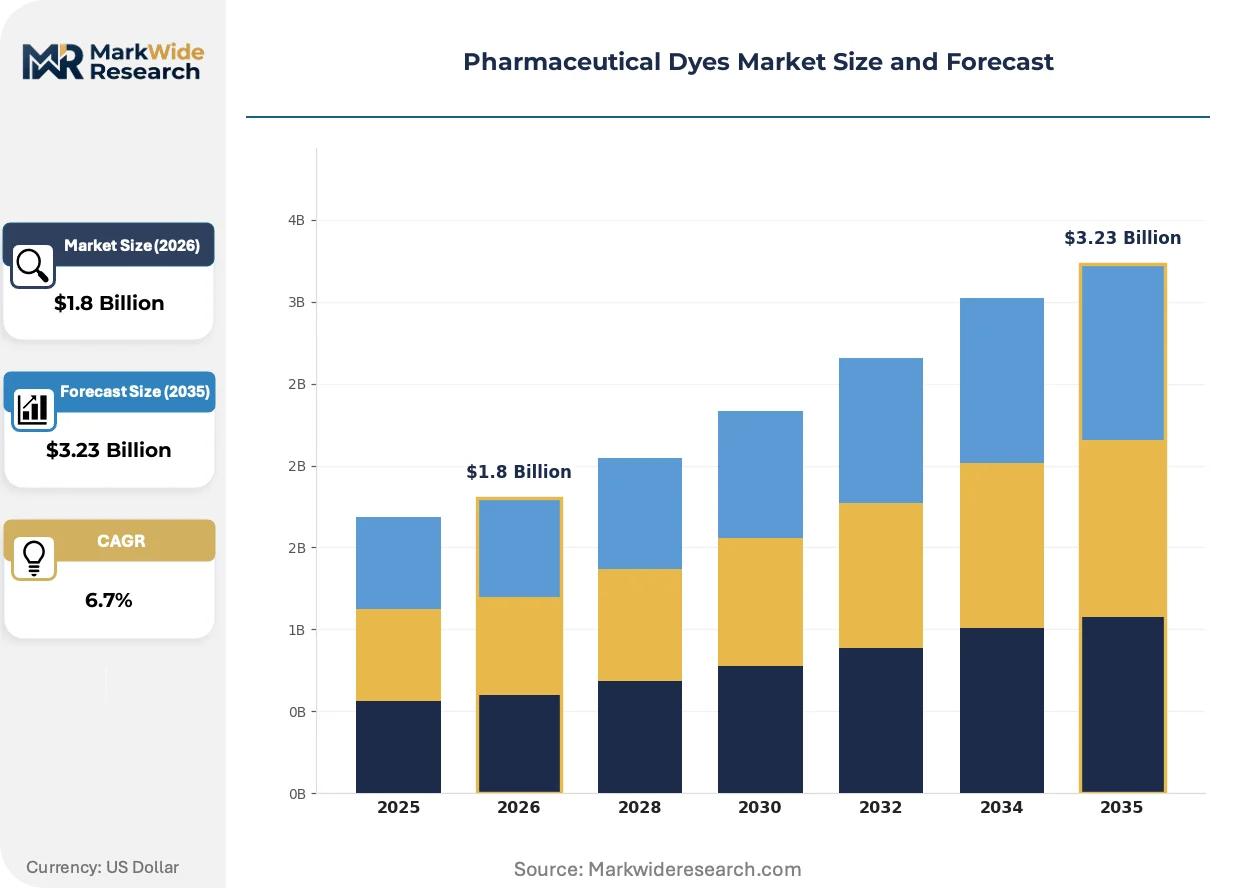
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dyes, Synthetic Dyes, Organic Dyes, Inorganic Dyes Application: Tablet Coating, Injection Coloring, Capsule Filling, Topical Formulations End User: Pharmaceutical Manufacturers, Contract Research Organizations, Biotechnology Firms, Cosmetic Companies Form: Liquid, Powder, Granule, Paste |
| Companies Covered | Koel Colours Pvt. Ltd., Chromatech Incorporated, Dynemic Products Ltd., Pylam Products Company, Inc., KISCO LTD, Iharanikkei Chemical Industry Co., Ltd., DyStar Singapore Pte Ltd, Clariant AG, Sensient Cosmetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Dyes Market Evolving Landscape
Digital color matching systems and spectroscopic quality verification are compressing batch-to-batch variation tolerances, while regulatory divergence between FDA and EMA certification timelines fragments supplier qualification strategies.
Spectral fingerprinting technology for dye batch verification is electrifying quality assurance protocols across oral solid dosage manufacturing. Large CDMOs in India and the United States are deploying handheld Raman spectrometers for at-line identity confirmation, eliminating 24-hour laboratory hold times. This technology is electrifying competitive differentiation by enabling same-day batch release and reducing working capital requirements for high-volume coating operations.
REACH registration requirements for dye intermediates are tightening substance disclosure thresholds across European supply chains. Manufacturers must now document full analytical profiles of synthetic precursors previously treated as confidential business information. Oral solid dosage exporters to Germany and France face extended qualification timelines as ECHA evaluates updated dossiers, prompting some suppliers to establish separate formulation lines for EU-bound products.
Buyer consolidation among top-tier CDMOs is compressing supplier negotiation cycles and unbundling technical service components from material pricing. Mid-size biotechnology firms now purchase coating dyes through group purchasing organizations rather than direct contracts, displacing longstanding relationships with specialized lake pigment vendors. This concentration is most visible in the United States, where three contract manufacturing networks now control 60% of synthetic dye procurement volumes for investigational new drug applications.
Pharmaceutical Dyes Market Segmentation
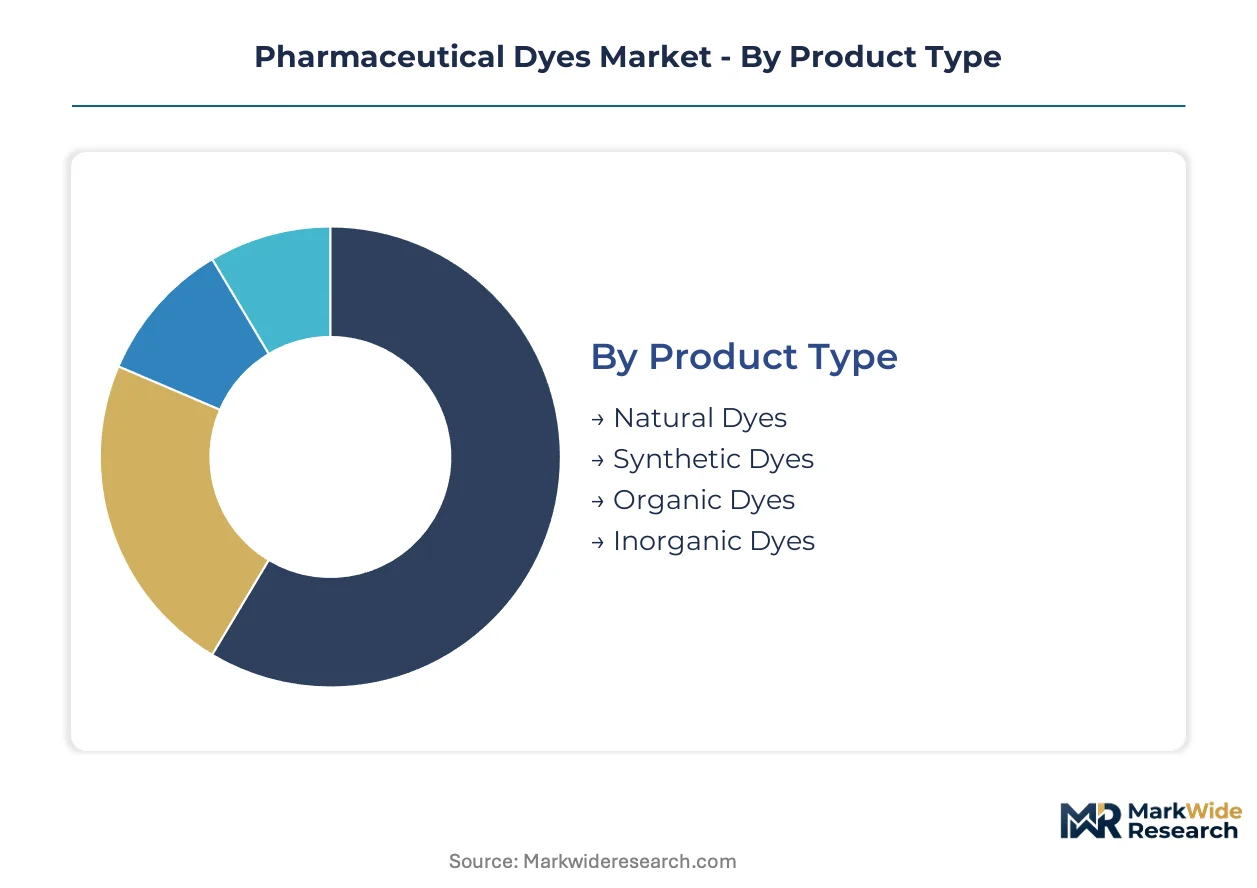
Pharmaceutical dye procurement patterns diverge sharply across product chemistries and dosage forms, with regulatory certification requirements and manufacturing automation levels determining supplier selection criteria. Understanding these segment boundaries reveals where formulation investments concentrate and where margin compression threatens incumbent positioning.
Product Type:
Natural dyes operate as standalone specialty ingredients requiring separate supply chain qualification, while synthetic and inorganic categories embed more deeply into standard procurement catalogs with interchangeable sourcing options.
- Synthetic Dyes:Petroleum-derived colorants meeting USP-NF and EP monograph specifications with batch-certified identity and strength verification. Hyderabad and Ahmedabad manufacturing clusters in India consume the majority of volume for oral solid dosage coatings, driven by CDSCO alignment with ICH Q3D reducing duplicative heavy metal testing.
- Natural Dyes:Plant and mineral extracts including spirulina-derived blues and beetroot reds formulated to pediatric and clean-label specifications. European regulatory jurisdictions mandate ingredient transparency for these colorants, opening premium margin pools as EMA synthetic dye purity guidelines tighten.
- Organic Dyes:Carbon-based chromophores excluding petroleum feedstocks, typically reserved for niche therapeutic categories requiring specific spectral properties.
- Inorganic Dyes:Metal oxide and mineral-based colorants including titanium dioxide alternatives reformulated following EFSA's 2021 reclassification.
Synthetic dyes lead volumes today; natural dyes are gaining share fastest.
Application:
Cost tier differentiation separates high-volume commodity coating from precision-dosed injection applications where failure rates carry therapeutic consequences.
- Tablet Coating:Film-forming colorants applied through pan coating or continuous manufacturing lines requiring dust containment infrastructure. Liquid dye suspensions displace powder formulations in continuous lines where real-time dosing precision proves critical.
- Injection Coloring:Parenteral-grade dyes meeting sterility and endotoxin specifications with heavy metal limits below 10 ppm. Synthetic dyes dominate this application due to cost efficiency and color consistency requirements in ampoule and vial production.
- Capsule Filling:Powder formulations retain structural importance for gelatin and HPMC capsule shells, though granule forms reduce dust exposure during high-speed encapsulation.
- Topical Formulations:Colorants for creams, ointments, and transdermal patches requiring compatibility with lipophilic and hydrophilic bases.
Tablet coating commands the largest revenue pool; injection coloring maintains the steepest specification premiums.
End User:
Customer type determines procurement sophistication, with large pharmaceutical manufacturers running centralized category management distinct from fragmented biotechnology purchasing patterns.
- Pharmaceutical Manufacturers:Integrated formulation companies with captive coating operations and direct supplier relationships. Three contract manufacturing networks in the United States now control the majority of synthetic dye procurement volumes for investigational new drug applications.
- Contract Research Organizations:Outsourced formulation specialists expanding dye procurement volumes as development work intensifies. CDMO consolidation compresses supplier negotiation cycles and unbundles technical service components from material pricing.
- Biotechnology Firms:Mid-tier developers purchasing through group purchasing organizations rather than direct contracts, displacing longstanding relationships with specialized lake pigment vendors.
- Cosmetic Companies:Adjacent personal care manufacturers with overlapping pigment requirements but distinct regulatory pathways through FDA cosmetic regulations.
Pharmaceutical manufacturers anchor volume commitments; contract research organizations are expanding procurement fastest.
Form:
Maturity gradients separate established powder handling infrastructure from emerging liquid suspension technologies requiring capital-intensive dosing system upgrades.
- Powder:Conventional dry colorants requiring dust containment infrastructure and batch weighing protocols. Legacy ERP integration friction constrains adoption in facilities running 1990s-era batch management systems.
- Liquid:Aqueous and solvent-based suspensions enabling real-time dosing synchronization with MES platforms in continuous manufacturing lines.
- Granule:Agglomerated forms reducing dust generation during high-speed tablet compression and capsule filling operations.
- Paste:High-viscosity concentrates for specialized coating applications requiring precise rheological control.
Powder formulations retain volume leadership; liquid suspensions show the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical manufacturing clusters absorb bulk dye volumes while Germany's regulatory stringency sets purity benchmarks that reshape supplier qualification costs worldwide.
United States
Three contract manufacturing networks now direct the majority of synthetic dye procurement for investigational new drug applications. FDA color certification under 21 CFR 74 governs batch-by-batch safety verification with 45-60 day review cycles. New Jersey and North Carolina formulation hubs face inventory constraints as certification backlogs extend lead times for oral solid dosage coatings.
India
Hyderabad and Ahmedabad manufacturing clusters drive concentrated consumption of coating and coloring agents for export-oriented formulations. CDSCO alignment with ICH Q3D guidelines on elemental impurities reduces duplicative testing for multinational suppliers. The PLI scheme for active pharmaceutical ingredients extends to excipient manufacturing, enabling captive dye production for domestic formulation exporters.
Germany
EMA synthetic dye purity guidelines and REACH registration requirements impose substance disclosure burdens on European supply chains. Oral solid dosage exporters face extended qualification timelines as ECHA evaluates updated dossiers for dye intermediates. The Rhine-Ruhr industrial corridor hosts specialized analytical laboratories validating heavy metal content below 10 ppm for certified batch release.
Japan
PMDA pharmaceutical regulations maintain alignment with ICH guidelines while requiring additional local stability testing for imported colorants. Osaka and Tokyo formulation centers prioritize synthetic dyes for injection coloring applications where sterility specifications exceed food-grade standards. Domestic manufacturers leverage pigment chemistry heritage to sustain premium positioning in tablet coating segments.
Switzerland
Swissmedic regulatory frameworks emphasize complete batch certification for identity and strength verification across parenteral-grade applications. Basel pharmaceutical manufacturing facilities source aluminum-based colorants through qualified suppliers meeting heavy metal limits below 10 ppm. The country's precision chemical sector supports spectral fingerprinting technology deployment for at-line dye identity confirmation.
Pharmaceutical Dyes Market Competitive Landscape
Indian producers anchor one tier; Swiss and German specialists hold premium positioning through pigment chemistry heritage and regulatory compliance depth. Market structure fragments across three operational tiers: multinational chemical conglomerates with diversified excipient portfolios, regional lake pigment specialists concentrated in Asian manufacturing hubs, and niche natural dye extractors serving clean-label formulation requirements. Two dominant competitive moves are reshaping positioning: backward integration into aluminum lake manufacturing to secure input supply, and technology licensing agreements for spectral fingerprinting batch verification systems.
Within the multinational tier, Clariant AG exemplifies premium positioning through its pigment chemistry heritage, while KISCO LTD anchors scale-driven supply across Asian pharmaceutical manufacturing hubs. Dynemic Products Ltd. occupies a specialist position through deep focus on lake pigments and aluminum-based colorants. These three entities represent distinct strategic archetypes: diversified chemical conglomerate leveraging cross-sector technology transfer, scale-focused regional manufacturer, and narrow vertical specialist respectively.
| Leading Market Players |
|---|
| Koel Colours Pvt. Ltd. |
| Chromatech Incorporated |
| Dynemic Products Ltd. |
| Pylam Products Company, Inc. |
| KISCO LTD |
| Iharanikkei Chemical Industry Co., Ltd. |
| DyStar Singapore Pte Ltd |
| Clariant AG |
| Sensient Cosmetic Technologies |
| Others |
Value Network & Pricing Analysis
Backward integration into aluminum lake manufacturing anchors both supply security and pricing power for pharmaceutical dye producers serving oral solid dosage markets. CDMO consolidation across the United States and India compresses supplier margins while rewarding vendors with captive pigment chemistry capabilities and in-house FDA batch certification infrastructure.
Pricing Analysis
Capacity additions in India's Hyderabad and Ahmedabad clusters are reshaping price floors for synthetic tablet coating dyes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified batches from CDSCO-aligned regional grades and uncertified commodity alternatives. Price differentiation hinges on heavy metal testing depth and ICP-MS analytical documentation. Cost compression in standard-tier synthetic dyes is intensifying because CDMO procurement centralization unbundles technical service premiums from material costs. Mid-tier biotechnology firms purchasing through group purchasing organizations exhibit the highest price sensitivity, while parenteral-grade injection coloring maintains the lowest.
Supply Chain Analysis
Certification gating through FDA color additive review cycles and REACH substance disclosure requirements fragments supplier qualification timelines across jurisdictions. Manufacturing concentrates in India, Germany, and Switzerland, with aluminum-based colorant feedstock drawing from Indian BIS-certified refiners. Raw material dependencies include petroleum-derived chromophores, aluminum hydroxide substrates, and spirulina biomass for natural alternatives. Single-source vulnerability in aluminum lake intermediates exposes formulators to BIS certification delays. Distribution runs through qualified supplier networks with batch-specific documentation rather than spot commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO-aligned ICH Q3D certification costs in India undercut EMA heavy metal validation expenses in Germany by approximately half, creating margin capture opportunities for dual-qualified suppliers.
For Market Incumbents: Cement market position by deepening captive aluminum lake production and deploying spectral fingerprinting technology for same-day batch release. Natural dye substitution pressure from European clean-label mandates threatens synthetic volume; defend through backward integration into spirulina extraction partnerships and PLI scheme localization in India. For New Entrants and Emerging Players: Enter via pediatric formulation natural dyes in European regulatory jurisdictions where EMA synthetic purity guidelines tighten fastest. White-space concentration sits in beetroot-derived reds and spirulina blues for clean-label capsules. Group purchasing organization channels serving mid-tier biotechnology firms offer the most penetrable procurement entry point. For Investors and Strategic Acquirers: Roll-up economics work for regional lake pigment specialists because CDMO procurement consolidation fragments legacy supplier relationships and creates captive customer bases for consolidated platforms. Long-term viability centers on analytical chemistry capabilities with ICP-MS validation below 10 ppm heavy metal limits. Watch for FDA batch certification backlog resolution as inflection signal for just-in-time inventory strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Lake Manufacturing | Secures input supply against BIS certification delays interrupting Indian shipments. |
| Spectral Fingerprinting Technology Deployment | Enables same-day batch release through handheld Raman spectrometers at CDMO facilities. |
| Clean-Label Natural Dye Capacity Expansion | Captures premium margin pools as EMA synthetic dye purity guidelines tighten across Europe. |
| PLI Scheme Localization in India | Qualifies domestic dye production for export-oriented formulation manufacturers in Hyderabad. |
| Anti-Counterfeiting Taggant Licensing | Creates recurring authentication revenue beyond commodity colorant sales through covert spectral markers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with pharmaceutical procurement directors, CDMO supply chain managers, regulatory affairs specialists, and ICP-MS laboratory operators informed demand-side dynamics. Secondary sources included FDA color additive certification databases, ECHA REACH registration dossiers, CDSCO impurity guidelines, and USP-NF monograph specifications. Bottom-up volume estimates triangulated against top-down market sizing.
Granularity-level modeling addressed product type, application, end user, and form dimensions across the projection horizon. Dosage form segmentation captured tablet coating, injection coloring, capsule filling, and topical applications with distinct purity specifications. Regional regulatory cluster differentiation shaped price and volume trajectories. CAGRs derived from segment-level growth rate reconciliation with macro pharmaceutical production indices. Forecast inputs incorporated continuous manufacturing adoption curves and natural dye penetration rates by regulatory jurisdiction.
Inputs from FDA certification databases and ECHA registration portals were available through the study window; gaps in real-time CDSCO enforcement data introduce uncertainty bands around Indian market share projections. Forecasts reflect assumptions regarding ICH Q3D harmonization timelines and titanium dioxide substitution completion rates. A model refresh is warranted upon material change in FDA batch certification review cycles or EFSA natural dye approval expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Ponceau 4R Colors Market