
 Screen Printing Inks Market | 2026-2036
Screen Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Screen Printing Inks Market Analysis
Multi-source procurement among large-format textile and electronics printers is consolidating around fewer ink suppliers with integrated pigment and resin capabilities. Sun Chemical leverages captive manufacturing of photoinitiators and specialty monomers to secure UV-curable ink supply chains. Nazdar Ink Technologies anchors its position through deep specialization in industrial screen printing for membrane switches and automotive overlays. Sakata INX Corporation competes by controlling regional distribution networks across East Asian electronics manufacturing zones.
Screen printing inks are viscous formulations comprising pigments, binders, solvents, and additives designed for forced transfer through a woven mesh stencil onto substrates ranging from cotton textiles to glass and ceramic. These inks cure through thermal evaporation, oxidation, or ultraviolet polymerization depending on chemistry, delivering opacity, durability, and precise deposit thickness critical to functional and decorative applications. UV-curable and water-based ink types are capturing share from solvent-based systems as environmental compliance tightens and energy costs reshape operating economics. Within applications, electronics and packaging segments attract premium pricing due to conductivity, adhesion, and chemical resistance specifications that exclude commodity formulations.
EPA regulations on hazardous air pollutants and OSHA permissible exposure limits constrain solvent-based ink formulations in the United States, while REACH registration requirements and RoHS substance restrictions in Europe compel reformulation investments across the supply base. China's MEE enforces volatile organic compound emission standards that directly affect screen printing operations in the Yangtze River and Pearl River Delta manufacturing clusters. Stakeholders must monitor regulatory divergence across these jurisdictions when locating formulation and blending assets.
Market Dynamics
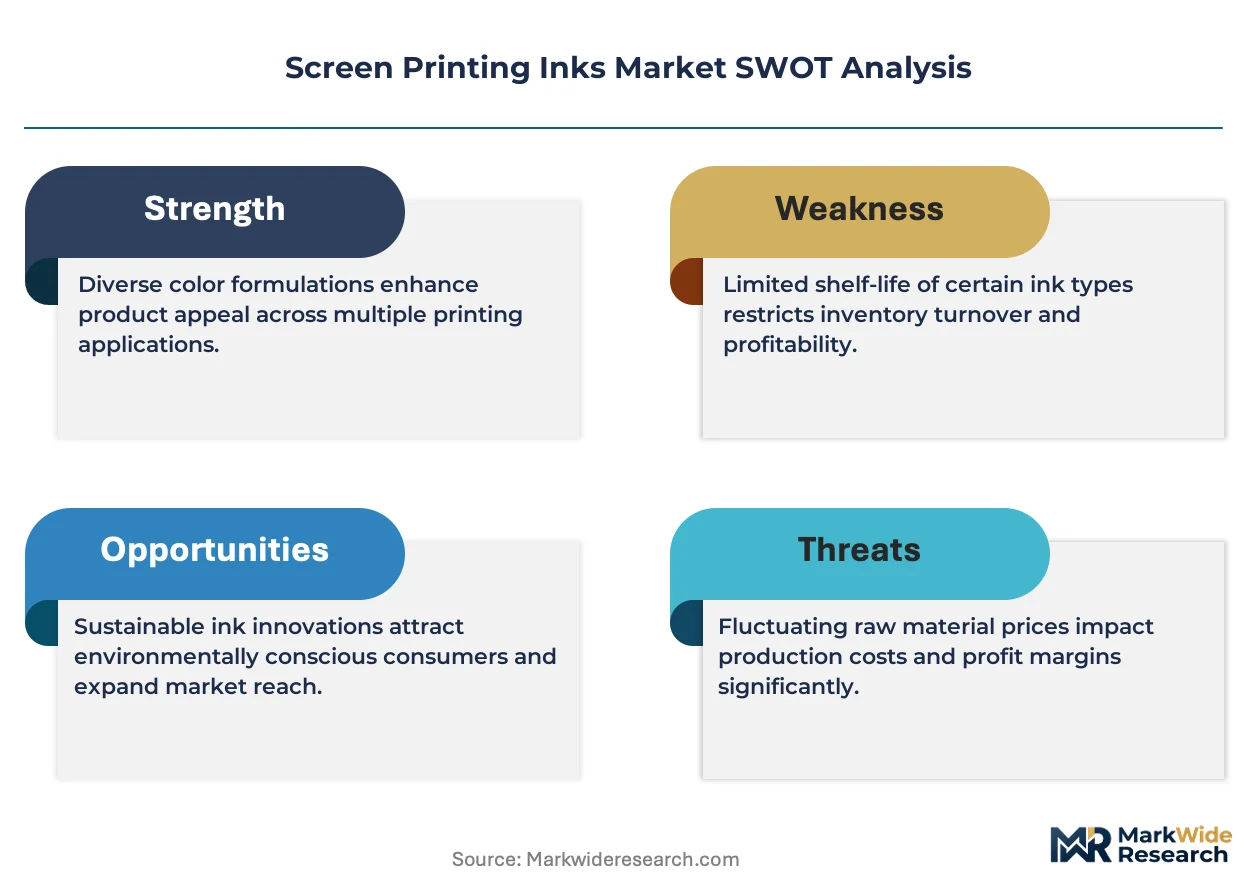
Formulation chemistry is pivoting under dual pressure from REACH substance restrictions and electronics manufacturers demanding thinner, more conductive ink deposits for miniaturized PCBs.
Growth Catalysts
- UV-curable ink systems:Electronics fabricators in China's Yangtze River Delta are converting solvent-based lines to reduce curing energy and VOC emissions. This technology delivers instant polymerization without thermal damage to sensitive substrates.
- REACH Annex XVII restrictions:European heavy metal pigment bans are forcing reformulation investments that create competitive moats for compliant suppliers. RoHS substance limits on cadmium and lead extend these requirements to exported goods.
- Printed circuit board densification:5G infrastructure and automotive sensor modules require precision screen-printed conductive traces. PCB manufacturers in South Korea and Taiwan are qualifying next-generation silver flake and carbon-based inks.
Market Restraints
- Photoinitiator supply concentration:German and Japanese chemical producers control 80% of specialty photoinitiator output for UV inks. Any disruption to benzoin ether or phosphine oxide supply cascades through ink formulation.
- Silver price volatility:Conductive inks for membrane switches and RFID antennas contain 60-80% silver flake by weight. London Bullion Market Association spot price swings directly compress blender margins.
- Solvent substitution limits:Water-based screen inks still fail adhesion tests on untreated polypropylene and fluoropolymer substrates used in chemical-resistant labeling.
Strategic Opportunities
- India electronics manufacturing:Production-linked incentive schemes for semiconductor and PCB fabrication are attracting Foxconn and Dixon Technologies operations. Domestic ink blending capacity remains underdeveloped relative to projected demand.
- Stretchable electronics:Wearable health monitors and soft robotics require silver nanowire and liquid metal formulations that survive 20%+ elongation cycles. This application commands 3-4x commodity ink pricing.
- Biobased monomer feedstocks:ISO 14001-certified brands are sourcing acrylated epoxidized soybean oil and lignin-derived oligomers to meet EU Green Deal carbon intensity disclosure requirements.
Industry Challenges
- Formulation chemist scarcity:UV ink development requires expertise in radical photopolymerization kinetics and pigment-photoinitiator compatibility. European and North American technical universities produce fewer polymer chemists than industry demand.
- Multi-jurisdiction registration:A single UV-curable ink SKU requires separate EPA TSCA premanufacture notices, ECHA REACH dossiers, and China MEE new chemical notifications. Registration timelines extend 18-36 months.
- Legacy solvent line depreciation:Textile printers in Bangladesh and Vietnam face stranded asset risk as major apparel brands enforce ZDHC Manufacturing Restricted Substances List compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screen Printing Inks Market |
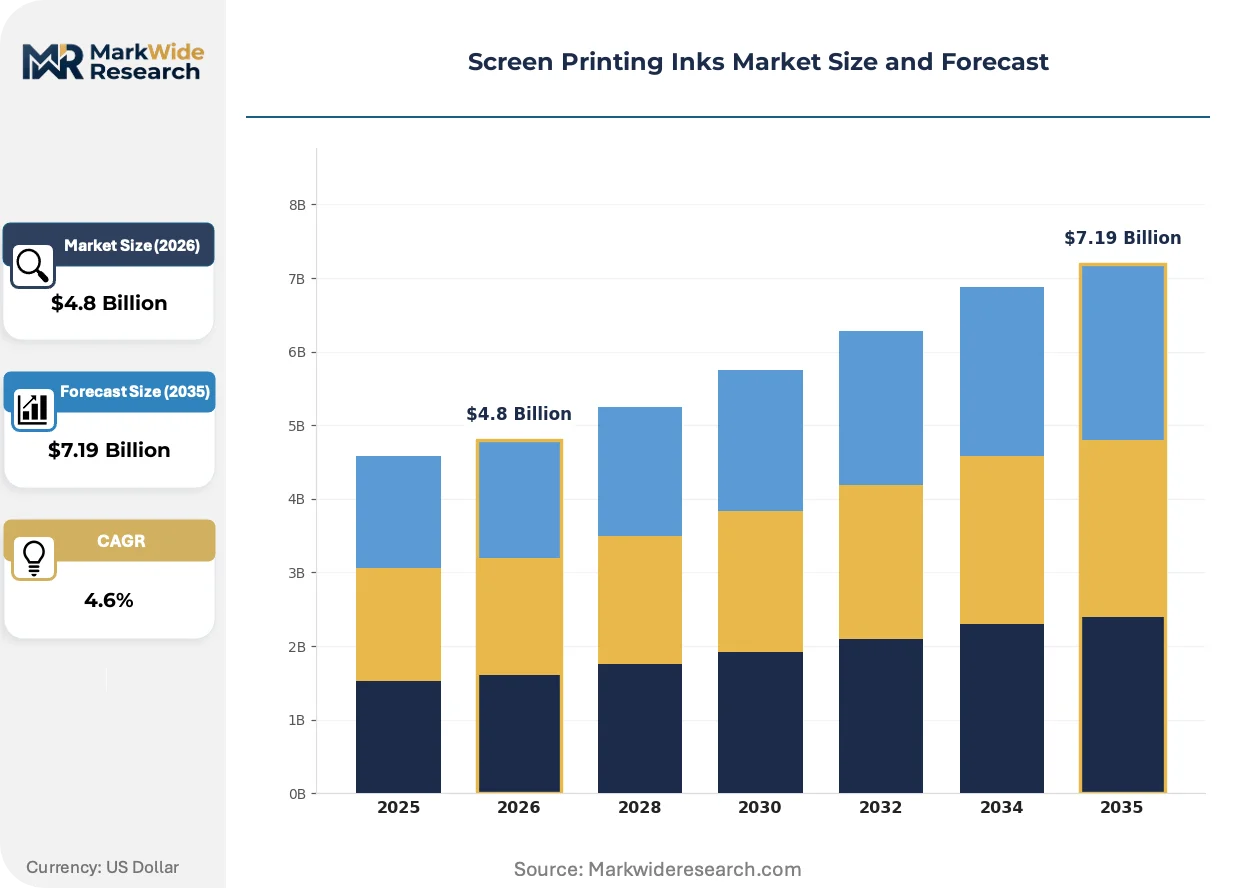
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Plastisol Inks, Water-Based Inks, Solvent-Based Inks, UV-Curable Inks Application: Textiles, Packaging, Electronics, Signage End User: Apparel Manufacturers, Commercial Printers, Advertising Agencies, Product Manufacturers Displacement Mode: Manual Printing, Automatic Printing, Hybrid Printing, Digital Printing |
| Companies Covered | Sun Chemical, Nazdar Ink Technologies, Sakata INX Corporation, Fujifilm Sericol, Marabu GmbH & Co. KG, DIC Corporation, Toyo Ink SC Holdings Co., Ltd., Siegwerk Druckfarben AG & Co. KGaA, Huber Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screen Printing Inks Market Emerging Trajectories
Digital hybrid workflows and sustainability mandates are compressing the traditional screen printing value chain, forcing ink suppliers to integrate prepress services and waste reduction guarantees into core offerings.
LED-UV curing technology is modularizing screen printing operations across narrow-web label and industrial graphics segments. Narrow-web converters in Italy and the United States are retrofitting mercury arc systems with 395nm LED arrays to eliminate ozone extraction and reduce energy draw by 50-70%. This shift is modularizing production floor layouts, enabling cell-based manufacturing where curing stations reposition based on job size rather than fixed line configurations.
China's MEE is enforcing GB 37822-2019 volatile organic compound emission standards that mandate leak detection and repair programs for ink storage and dispensing. Screen printing houses in the Pearl River Delta face quarterly compliance audits with automatic shutdown provisions for violations. Small and mid-size textile printers are consolidating into shared service facilities with centralized solvent recovery to distribute capital burden.
Brand-led chemical management is restructuring procurement relationships in apparel and packaging. Zara, H&M, and Target Corporation now require Tier 2 ink supplier disclosure through the ZDHC Gateway platform. Bangladeshi and Turkish textile screen printers are bypassing local distributors to contract directly with formulators who provide batch-level MRSL test reports, compressing traditional three-tier distribution into direct technical partnerships.
Screen Printing Inks Market Segmentation
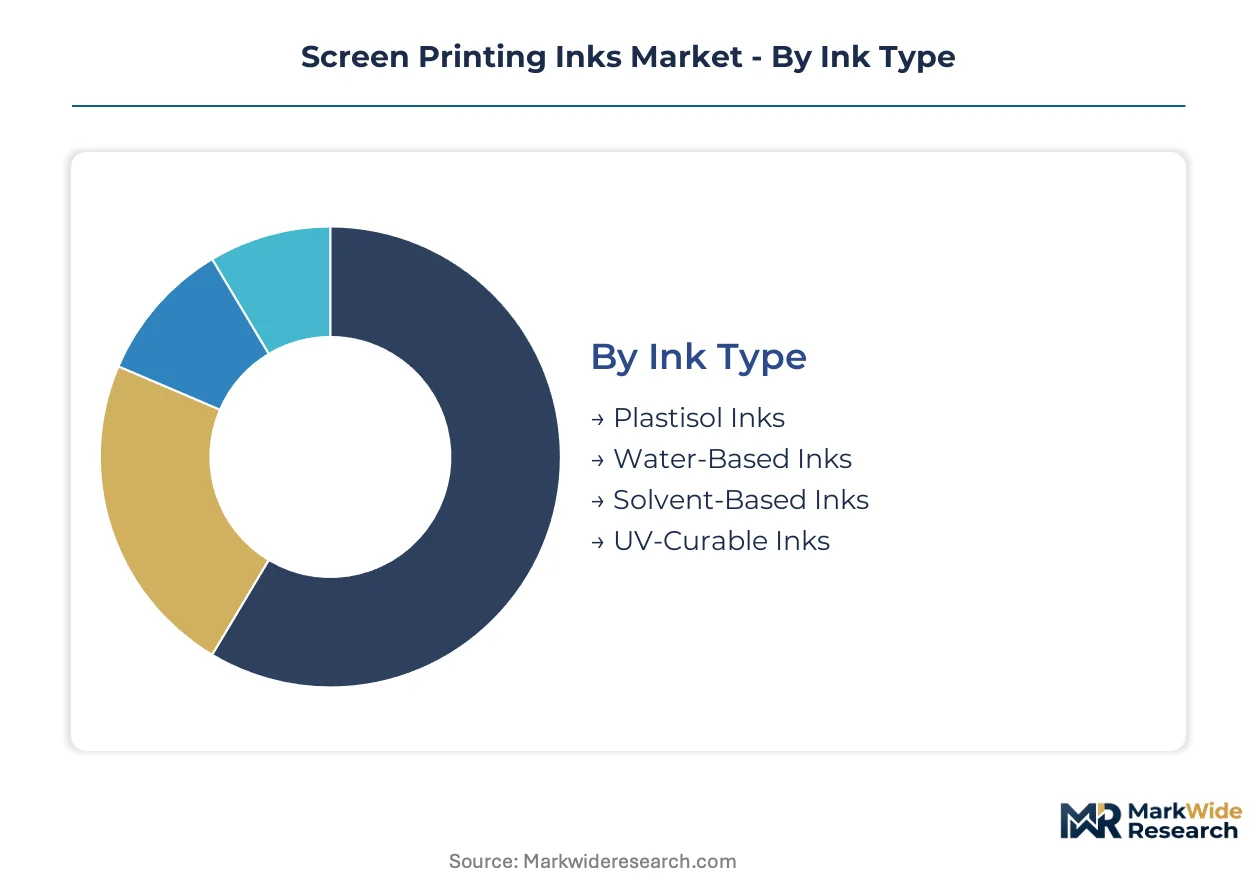
Screen printing ink procurement patterns diverge sharply across chemistry types, application requirements, and production automation levels. Buyers prioritize curing speed, substrate compatibility, and regulatory compliance when selecting formulations, creating distinct competitive arenas within each segment dimension.
Ink Type:
Cost tier separates commodity textile printers from electronics fabricators seeking precision conductivity specifications.
- Plastisol Inks:PVC resin-based systems suspended in plasticizer carriers deliver opacity and stretchability on cotton and polyester blends. Bangladeshi and Vietnamese apparel exporters consume bulk volumes for fast-fashion contract manufacturing, though ZDHC MRSL compliance is forcing phthalate-free reformulation investments.
- UV-Curable Inks:Photoinitiator-acrylate formulations polymerize instantly under 395nm LED or mercury arc exposure, eliminating thermal damage to sensitive substrates. South Korean and Taiwanese PCB manufacturers are qualifying these systems for 5G infrastructure conductive trace applications where deposit thickness precision matters.
- Water-Based Inks:Acrylic or polyurethane dispersions in water carriers serve European textile printers facing REACH VOC restrictions.
- Solvent-Based Inks:Volatile organic solvent systems retain adhesion dominance on untreated polypropylene and fluoropolymer substrates for chemical-resistant industrial labeling.
Solvent-based formulations lead volumes today; UV-curable systems are gaining share fastest.
Application:
Margin structure varies dramatically between decorative surface printing and functional electronics deposition.
- Electronics:Silver flake and carbon-based conductive inks for PCB traces, membrane switches, and RFID antennas command premium pricing due to conductivity specifications and chemical resistance requirements. Fabricators in China's Yangtze River Delta and South Korea's Gyeonggi Province drive qualification programs for miniaturized 5G and automotive sensor modules.
- Textiles:Cotton, polyester, and blended fabric printing for apparel and home furnishings represents high-volume, price-sensitive demand concentrated in Bangladesh, Vietnam, and Turkey. Zara and H&M now mandate ZDHC Gateway disclosure from Tier 2 ink suppliers.
- Packaging:Glass, metal, and rigid plastic container decoration for food, beverage, and cosmetic applications.
- Signage:Outdoor durable graphics on vinyl, acrylic, and aluminum composite panels for advertising and wayfinding.
Textile applications dominate current volume; electronics printing shows the steepest expansion trajectory.
End User:
Customer scale and technical sophistication determine whether ink procurement runs through distributors or direct formulator relationships.
- Apparel Manufacturers:High-volume garment producers in Bangladesh and Vietnam purchase plastisol and water-based inks through consolidated distributor networks, though brand-led MRSL enforcement is compressing supply tiers.
- Product Manufacturers:Electronics OEMs and automotive suppliers in China, South Korea, and Taiwan source conductive and overlay inks through direct technical partnerships with formulators providing batch-level test documentation.
- Commercial Printers:Mid-size graphics and packaging converters balancing multiple substrate requirements.
- Advertising Agencies:Campaign-driven signage and promotional material buyers with project-based demand patterns.
Apparel manufacturers anchor current demand; product manufacturers in electronics are expanding procurement most rapidly.
Displacement Mode:
Automation intensity separates high-mix, short-run operations from continuous production environments.
- Automatic Printing:Servo-driven press systems with automated substrate handling and registration deliver throughput for electronics and packaging segments. China's Pearl River Delta textile and PCB houses are retrofitting manual lines to meet MEE VOC enforcement and labor cost pressures.
- Digital Printing:Inkjet and hybrid workflows are displacing pure screen methods in narrow-web label and prototyping applications. Italian and United States converters combine digital front-ends with screen stations for tactile and metallic effects.
- Manual Printing:Operator-controlled squeegee pressure and flood stroke adjustment persists in artisan textile and short-run signage applications.
- Hybrid Printing:Integrated production lines combining screen, digital, and finishing processes.
Automatic printing commands the largest installed base; digital hybrid configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing screen printing ink production toward jurisdictions where compliance costs and enforcement intensity create operational advantages for reformulation-capable suppliers.
China
PCB fabricators and textile exporters in the Yangtze River Delta and Pearl River Delta drive concentrated ink consumption. MEE enforces GB 37822-2019 VOC emission standards with quarterly audits and automatic shutdown provisions. Suzhou and Shenzhen clusters are retrofitting solvent-based lines to UV-curable systems under dual carbon policy timelines.
United States
Electronics OEMs in California and Texas qualify conductive inks for automotive sensor and 5G infrastructure modules. EPA hazardous air pollutant regulations and OSHA permissible exposure limits constrain solvent-based formulation. Silicon Valley and Austin manufacturing zones prioritize UV-curable and water-based chemistries for environmental liability reduction.
Germany
Industrial graphics and membrane switch producers in Bavaria and North Rhine-Westphalia specify REACH-compliant formulations. ECHA registration requirements and RoHS substance restrictions on cadmium and lead compel heavy metal pigment elimination. Stuttgart and Düsseldorf industrial corridors source photoinitiators and specialty monomers from integrated chemical producers.
South Korea
PCB manufacturers in Gyeonggi Province and Busan-Ulsan region qualify next-generation silver flake and carbon-based conductive inks. MFDS chemical safety assessments and K-REACH registration parallel European substance controls. Seoul Capital Area electronics clusters demand deposit thickness precision for miniaturized 5G and automotive modules.
India
Production-linked incentive schemes for semiconductor and PCB fabrication attract Foxconn and Dixon Technologies operations to Karnataka and Tamil Nadu. BIS certification requirements and state-level pollution control board VOC enforcement remain less stringent than Chinese or European standards. Domestic ink blending capacity lags projected demand in Bengaluru and Chennai electronics zones.
Screen Printing Inks Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty conductivity and sustainability-certified segments. The supplier base concentrates around integrated pigment and resin manufacturers with captive photoinitiator supply. Three archetypes dominate: multinational chemical conglomerates with vertical raw material control, mid-size formulators with deep industrial specialization, and regional distributors with East Asian electronics corridor access. Competitive moves center on formulation registration acceleration and LED-UV curing technology licensing.
Among multinational chemical producers, Sun Chemical, DIC Corporation, and Siegwerk Druckfarben AG & Co. KGaA represent integrated supply chain archetypes with in-house photoinitiator and specialty monomer production. These entities anchor positions through regulatory compliance dossier breadth across EPA, ECHA, and China MEE jurisdictions. Mid-scale specialists such as Nazdar Ink Technologies and Marabu GmbH & Co. KG exemplify industrial application-focused positioning, occupying technical partnership roles with electronics fabricators requiring batch-level test documentation. Sakata INX Corporation and Toyo Ink SC Holdings Co., Ltd. sit within East Asian electronics manufacturing corridor networks, leveraging regional distribution density for just-in-time supply to Yangtze River Delta and Gyeonggi Province clusters.
| Leading Market Players |
|---|
| Sun Chemical |
| Nazdar Ink Technologies |
| Sakata INX Corporation |
| Fujifilm Sericol |
| Marabu GmbH & Co. KG |
| DIC Corporation |
| Toyo Ink SC Holdings Co., Ltd. |
| Siegwerk Druckfarben AG & Co. KGaA |
| Huber Group |
| Others |
Supply Flow & Price Mechanics
Electronics OEMs in China's Yangtze River Delta and South Korea's Gyeonggi Province concentrate procurement power for conductive ink formulations, anchoring contract-based long-term offtake pricing with volume-scaled discounts and REACH compliance premiums.
Pricing Analysis
Distributor margins compress in textile segments while direct-to-OEM channels dominate electronics. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified conductive inks from commodity textile formulations. Cost compression in plastisol systems intensifies because Bangladeshi apparel exporters face ZDHC MRSL enforcement without brand pricing power. Textile printers show highest price sensitivity; PCB fabricators accept premium positioning for silver flake conductivity specifications.
Supply Chain Analysis
Photoinitiator supply rests on German and Japanese specialty chemical producers controlling benzoin ether and phosphine oxide output. Silver flake feedstock draws from London Bullion Market Association spot markets; acrylic monomers and PVC resins source from integrated petrochemical complexes in China, Germany, and the United States. Single-source vulnerability in photoinitiator concentration creates formulation disruption risk. Distribution runs through regional technical distributors for textile segments and direct formulator partnerships for electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screen printing ink demand compounds under regulatory acceleration, with China's GB 37822-2019 VOC enforcement and Europe's REACH Annex XVII restrictions forcing reformulation investments that reshape competitive positioning.
For Market Incumbents: Lock in photoinitiator supply through captive production or exclusive offtake agreements with German and Japanese specialty chemical producers. Accelerate EPA TSCA and ECHA REACH dossier breadth to outpace multi-jurisdiction registration timelines that constrain emerging competitors. Vertical integration into acrylated epoxidized soybean oil feedstocks defends margin position against biobased certification requirements in EU Green Deal procurement. For New Entrants and Emerging Players: Regional distributors in India's Karnataka and Tamil Nadu electronics corridors represent the most penetrable channel partner type for conductive ink market entry. Production-linked incentive schemes for semiconductor fabrication create demand without incumbent supply infrastructure. Target stretchable electronics applications for silver nanowire formulations commanding premium positioning through wearable health monitor OEMs. For Investors and Strategic Acquirers: Specialty chemical conglomerates with integrated pigment capabilities are the most active acquirer in this space, pursuing mid-scale formulators with deep industrial specialization in membrane switches and automotive overlays. Five-to-ten year viability hinges on LED-UV curing technology licensing portfolios and regulatory compliance dossier breadth. Watch photoinitiator supply disruption as inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiators | Sun Chemical's captive benzoin ether production secures UV-curable ink supply chains against German and Japanese concentration. |
| REACH Compliance Dossier Expansion | ECHA registration breadth creates competitive moats for electronics ink suppliers serving European PCB fabricators. |
| LED-UV Curing Technology Licensing | Italian narrow-web converters retrofit mercury arc systems with 395nm arrays to eliminate ozone extraction costs. |
| Biobased Monomer Feedstock Sourcing | ISO 14001-certified brands adopt acrylated epoxidized soybean oil to meet EU Green Deal carbon intensity disclosures. |
| Direct Technical Partnership Model | Bangladeshi textile printers bypass distributors for ZDHC Gateway-compliant formulators providing batch-level MRSL test reports. |
Methodological Framework
Multiple input streams — primary interviews with ink formulation chemists, PCB procurement leads, and textile plant managers; secondary validation through ECHA registration databases, EPA TSCA premanufacture notices, and China MEE new chemical notifications — were reconciled through bottom-up and top-down triangulation.
Historical shipment data from customs records and ACC chemical trade reports were cross-referenced against panel input from photoinitiator producers and regional distributors across the analysis window. Segmentation modeling incorporated ink chemistry type, application vertical, curing technology, and end-user automation level. CAGRs were derived from elasticity-adjusted demand projections for electronics densification and regulatory substitution effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silver price volatility, photoinitiator supply disruption, and divergence in VOC enforcement intensity across Chinese, European, and Indian jurisdictions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Printing Plate Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market
Printing Inks
Offset Ink Market
Printing Inks
Food Grade Inks Market
Printing Inks
Ink Resins Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
United States Printing Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Screen Printing Mesh Market