
 Phthalocyanine Blue Market | 2026-2036
Phthalocyanine Blue Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalocyanine Blue Market Analytics
Asset-light toll manufacturing and third-party pigment dispersion leasing is fragmenting the competitive landscape for phthalocyanine blue production. BASF SE leverages its integrated copper phthalocyanine crude-to-pigment chain to sustain margin control across European coatings supply. Clariant specializes in surface-treated pigment grades that dominate inkjet and packaging ink specifications. Sun Chemical anchors North American supply security through captive dispersion facilities and direct mill relationships.
Phthalocyanine blue denotes a copper-centered synthetic organic pigment with a porphyrazine macrocyclic structure, delivering exceptional lightfastness, thermal stability above 300°C, and a color index designation of Pigment Blue 15. Manufacturers synthesize the compound through urea fusion of phthalic anhydride with copper salt catalysts, then condition particle size through acid swelling or bead milling to achieve target opacity and dispersibility for coatings, plastics, and printing applications. The pigment segment leads value capture due to downstream formulation complexity and certification requirements, while powder grades represent the fastest-growing form category as dry-delivery logistics reduce solvent handling costs. Coatings application channels concentrate margin pools in automotive OEM and coil coating segments where weathering performance specifications are most stringent.
EPA regulates copper phthalocyanine pigment manufacturing under TSCA Section 5 premanufacture notification requirements, while REACH mandates registration and hazard communication for imported pigment volumes into Europe. China's MEE enforces emission standards on phthalocyanine crude synthesis facilities, constraining unconditioned capacity additions. India's BIS certification for pigment purity in food-contact plastics shapes import eligibility for regional compounders. Stakeholders must monitor regulatory divergence on heavy metal content thresholds and perfluorinated substance restrictions that could displace legacy pigment stabilization chemistries.
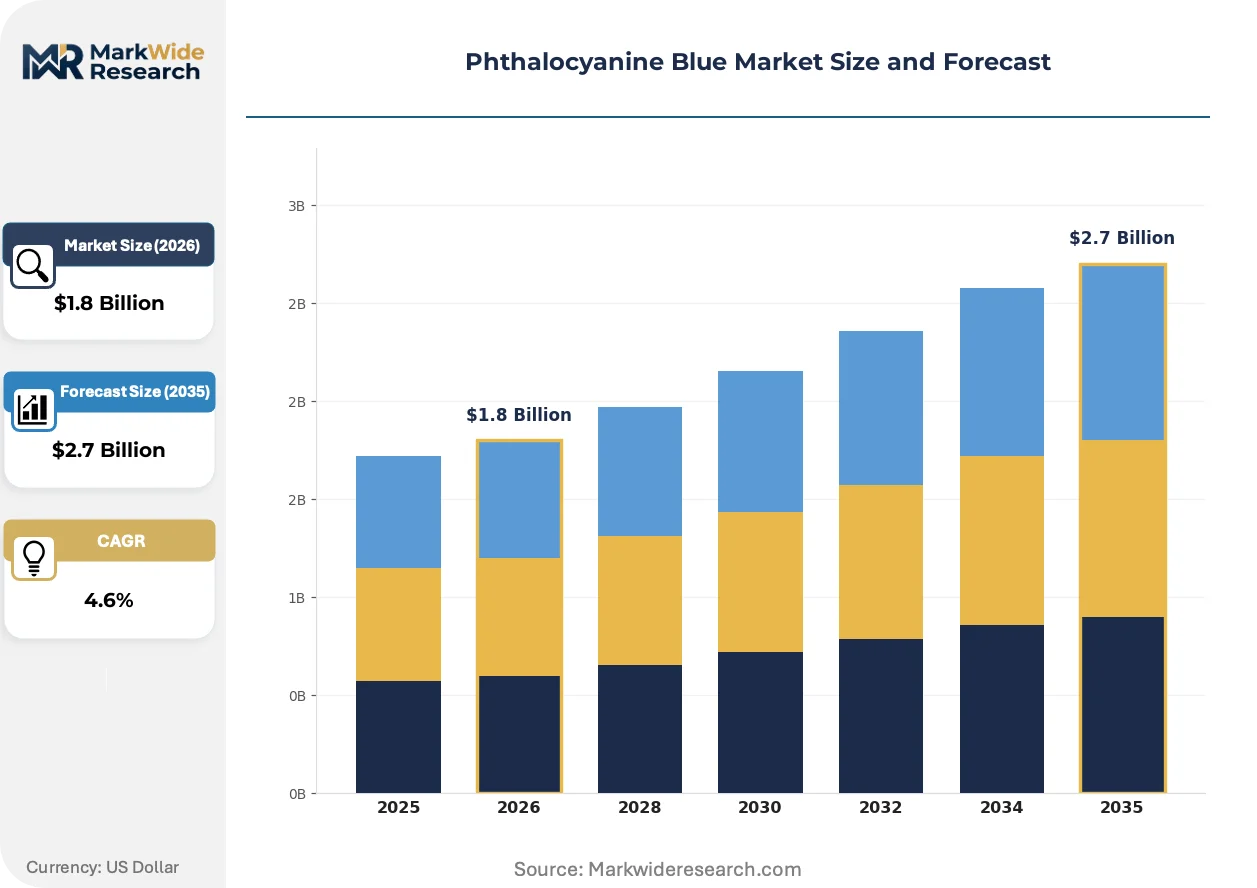
Market Dynamics
REACH compliance and tightening VOC regulations are redirecting formulation strategies toward copper phthalocyanine complexes with lower environmental footprints, forcing manufacturers to reconfigure synthesis and conditioning processes.
Growth Catalysts
- Automotive coatings procurement:OEMs in Germany and Japan are expanding specification of high-performance pigments for exterior finishes that withstand accelerated weathering protocols.
- REACH registration tailwinds:ECHA's phased registration requirements for imported pigment volumes are consolidating compliant supplier bases and elevating entry barriers for non-registered producers.
- Acid swelling process refinements:Continuous bead milling technologies are reducing particle size distribution variance and improving dispersibility in waterborne coating systems.
Market Restraints
- Copper salt input volatility:Electrolytic copper price swings directly compress margins on phthalocyanine crude synthesis, particularly for non-integrated producers lacking captive metal supply.
- China supply concentration:Domestic pigment production capacity scaling has concentrated global output in Shandong and Zhejiang provinces, creating single-point vulnerability to MEE emission enforcement actions.
- Perfluorinated surfactant restrictions:Legacy pigment stabilization chemistries face displacement under emerging PFAS regulations in multiple jurisdictions, requiring reformulation investment.
Strategic Opportunities
- India food-contact plastics:BIS certification requirements for pigment purity in packaging applications are creating import eligibility barriers that compliant suppliers can exploit.
- Waterborne inkjet inks:Surface-treated pigment grades meeting narrow particle size specifications are capturing share in high-speed commercial printing installations.
- Dry-delivery logistics:Powder grade pigment shipments are reducing solvent handling costs and enabling just-in-time procurement models for mid-size coating compounders.
Industry Challenges
- Colorimetric certification timelines:Automotive OEM qualification protocols for new pigment grades require 18-24 month weathering validation, compressing product development cycles.
- Particle engineering talent scarcity:Specialized expertise in acid swelling and bead milling process control is concentrated among retiring technicians in European and Japanese facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalocyanine Blue Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude, Pigment, Powder, Paste Application: Coatings, Plastics, Inks, Textiles Form: Liquid, Solid, Gel, Emulsion End User: Manufacturers, Artists, Retailers, Hobbyists |
| Companies Covered | BASF SE, Clariant, DIC Corporation, Sun Chemical, Heubach GmbH, Sudarshan Chemical Industries Ltd., Meghmani Pigments, Kolorjet Chemicals Pvt Ltd., Kesar Petroproducts Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalocyanine Blue Market Evolving Landscape
Formulation chemistry and regulatory chemistry are converging to reshape how pigment manufacturers design particle surfaces, stabilize dispersions, and document environmental compliance across coating and ink applications.
Surface-treated pigment grades engineered for narrow particle size distribution are rendering obsolete conventional untreated powders in high-resolution inkjet and packaging ink specifications. Japanese printing equipment manufacturers are adopting these grades fastest, demanding sub-100 nanometer primary particle control. The shift is compressing margin pools among commodity powder suppliers unable to fund conditioning infrastructure.
REACH's phased registration and hazard communication mandates are forcing pigment importers into European coatings supply chains to document full substance dossiers or face market exclusion. ECHA's enforcement of updated safety data sheet requirements is elevating compliance costs for smaller traders. Automotive OEMs and coil coaters in Germany and Italy are responding by consolidating supplier panels to registered producers with established only-representative structures.
Direct mill relationships and captive dispersion facilities are displacing traditional distributor networks in North American supply security strategies. Large coating compounders are negotiating toll manufacturing agreements that bypass conventional pigment resale channels. The restructuring is most visible in automotive OEM supply chains where just-in-time color matching requirements favor vertically integrated dispersion capacity.
Phthalocyanine Blue Market Segmentation
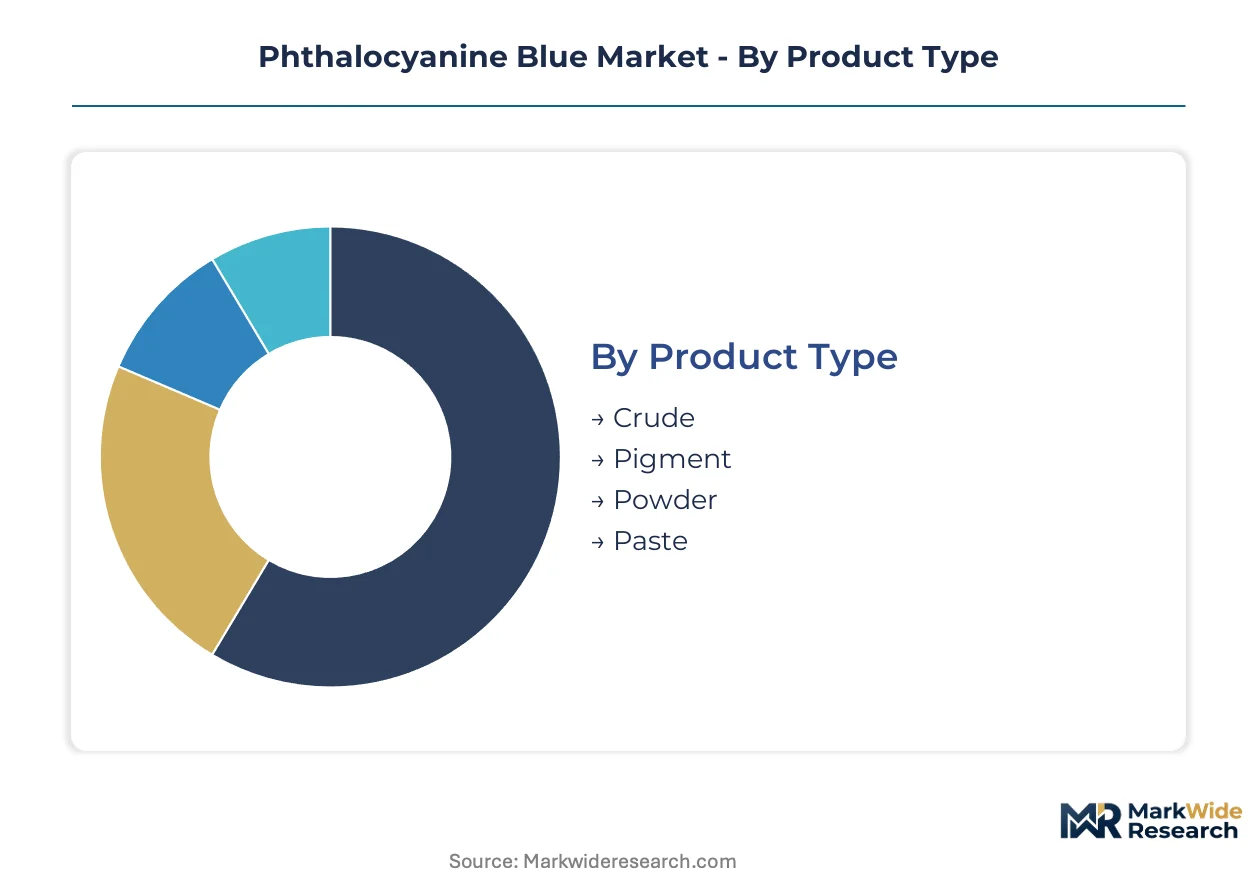
Segmentation in phthalocyanine blue reveals how value migrates through distinct processing stages and customer requirements. Technical service intensity varies sharply across crude synthesis, conditioning, and dispersion steps. Manufacturers configure operations around segments where particle engineering expertise or regulatory documentation creates defendable margin.
Product Type:
After-sales service intensity concentrates in pigment conditioning and dispersion stages where customers require technical troubleshooting for color matching failures.
- Crude:Unrefined copper phthalocyanine intermediate synthesized through urea fusion demands minimal post-sale support. Buyers in China and India integrate crude into captive finishing operations. Electrolytic copper price swings compress margins for non-integrated producers lacking metal supply security.
- Pigment:Surface-treated grades engineered for narrow particle size distribution command intensive application support. REACH registration dossiers and automotive OEM weathering certifications require dedicated regulatory affairs staffing. ECHA compliance documentation represents a recurring service burden that registered suppliers monetize through premium positioning.
- Powder:Dry-delivery logistics reduce solvent handling costs for mid-size coating compounders. MEE emission enforcement in Shandong constrains unconditioned capacity additions.
- Paste:Pre-dispersed concentrates eliminate milling investment for small ink manufacturers. Shelf-life stability and viscosity control require formulation guidance.
By volume, Crude leads. By growth pace, Pigment is ahead.
Application:
Cost tier differentiation separates specification-grade automotive coatings from commodity packaging applications.
- Coatings:Automotive OEM and coil coating segments concentrate margin pools where weathering performance specifications are most stringent. Acid swelling process refinements and continuous bead milling technologies improve dispersibility in waterborne systems. German and Japanese OEMs are expanding procurement of high-performance pigments for exterior finishes.
- Plastics:Food-contact applications in India require BIS certification for pigment purity, creating import eligibility barriers. Masterbatch compounders demand thermal stability above 300°C for engineering polymer processing.
- Inks:Inkjet and packaging ink specifications favor surface-treated grades with sub-100 nanometer primary particle control. Japanese printing equipment manufacturers are adopting these grades fastest.
- Textiles:Fiber dyeing applications use lower-cost crude derivatives with less stringent lightfastness requirements. Discharge permit compliance dominates supplier selection.
Coatings captures the highest value per kilogram. Inks is expanding most quickly.
Form:
Customer type determines whether liquid delivery, solid handling, or specialized rheology modifications prove economically optimal.
- Liquid:Ready-to-use dispersions eliminate milling investment and dust exposure for small coating compounders. Just-in-time procurement models favor regional toll manufacturing relationships.
- Solid:Powder grades enable dry-delivery logistics that reduce solvent handling costs and simplify inventory management. The fastest-growing form category as environmental regulations tighten.
- Gel:High-solids concentrates balance flow properties with reduced shipping weight for distant customers.
- Emulsion:Water-based systems align with VOC regulation compliance in European and North American jurisdictions.
Solid dominates shipment volumes. Liquid shows the steepest expansion trajectory.
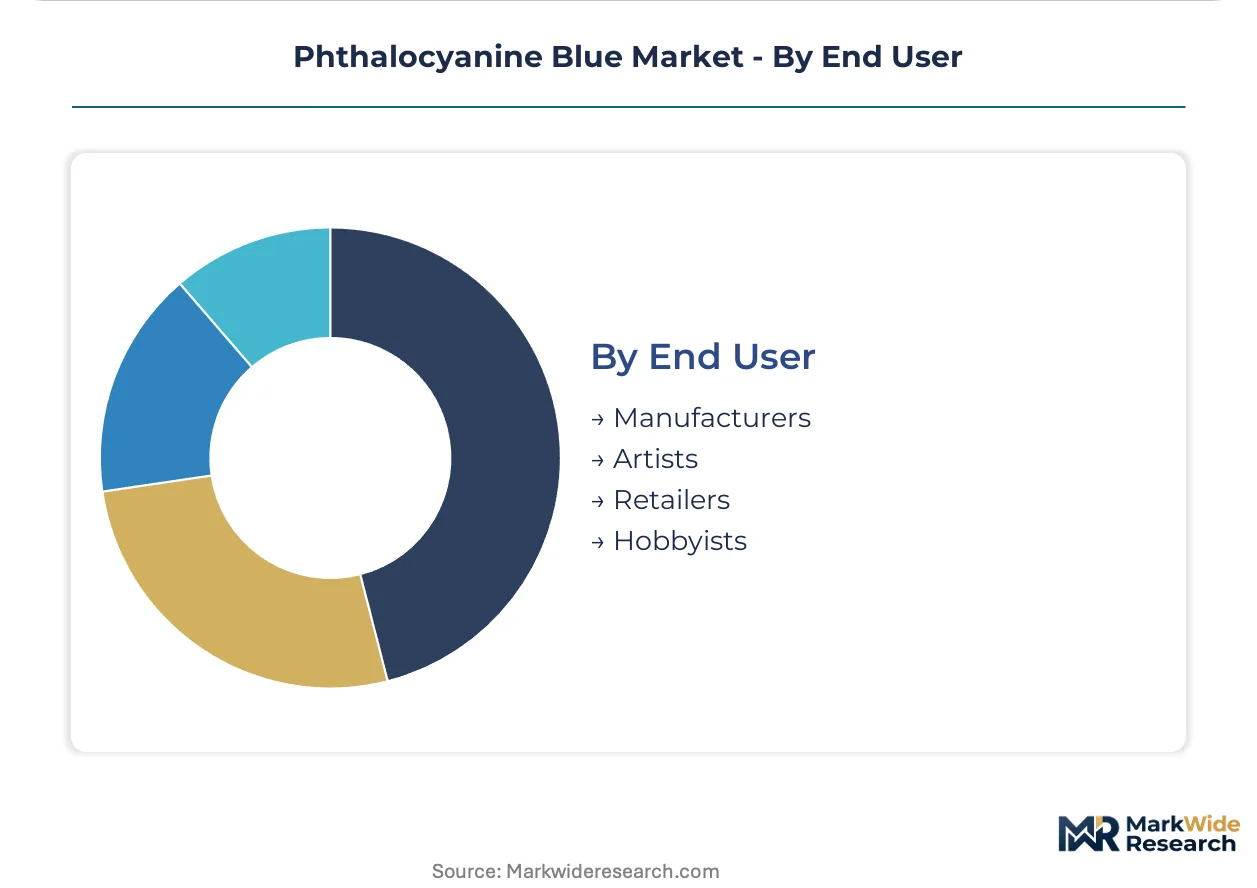
End User:
Supply concentration patterns diverge between large-scale manufacturers with captive dispersion capacity and fragmented artisanal demand.
- Manufacturers:Automotive OEMs and coil coaters consolidate supplier panels to registered producers with established only-representative structures. Direct mill relationships and captive dispersion facilities are displacing traditional distributor networks in North American supply security strategies.
- Artists:Professional pigment requirements for lightfastness and color permanence support premium pricing for certified grades. Small batch sizes elevate per-kilogram service costs.
- Retailers:Private-label art supply distributors demand consistent color matching across production lots with minimal technical interaction.
- Hobbyists:Price-sensitive consumers purchase pre-formulated paints with phthalocyanine blue as an undisclosed component. No direct pigment procurement relationship exists.
Manufacturers account for the dominant volume share. Artists generate the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration mandates and automotive OEM procurement protocols are redirecting pigment supply toward compliant producers in Germany and Japan. China's MEE emission standards are constraining unconditioned capacity additions in Shandong and Zhejiang provinces.
Germany
Automotive OEMs in Stuttgart and Munich are expanding specification of high-performance pigments for exterior finishes under accelerated weathering protocols. ECHA's phased registration requirements for imported pigment volumes are consolidating compliant supplier bases. BASF SE's integrated copper phthalocyanine crude-to-pigment chain in Ludwigshafen sustains margin control across European coatings supply.
China
Domestic pigment production capacity and downstream coatings output continue to scale in Yangtze River Delta manufacturing clusters. MEE enforces emission standards on phthalocyanine crude synthesis facilities, constraining unconditioned capacity additions. Shandong and Zhejiang provinces concentrate global output, creating single-point vulnerability to enforcement actions.
Japan
Printing equipment manufacturers in Tokyo and Osaka are adopting surface-treated pigment grades fastest, demanding sub-100 nanometer primary particle control. METI oversees chemical substance management under CSCL frameworks. Kansai region inkjet ink compounders are consolidating procurement to registered suppliers with established technical service capabilities.
India
Masterbatch compounders in Maharashtra and Gujarat demand thermal stability above 300°C for engineering polymer processing. BIS certification for pigment purity in food-contact plastics shapes import eligibility for regional compounders. Ankleshwar industrial corridor hosts expanding dispersion facilities serving packaging applications.
United States
Coating compounders in Ohio and Michigan are negotiating toll manufacturing agreements that bypass conventional pigment resale channels. EPA regulates copper phthalocyanine pigment manufacturing under TSCA Section 5 premanufacture notification requirements. Sun Chemical anchors North American supply security through captive dispersion facilities.
Phthalocyanine Blue Market Competitive Landscape
Channel-controlling players compete with product-specialist players across crude synthesis, conditioning, and dispersion stages. The vendor base organizes around three strategic archetypes: integrated crude-to-pigment manufacturers, surface-treatment specialists, and toll dispersion operators. Consolidation pressure concentrates among registered suppliers with established only-representative structures in Europe. Dominant competitive moves include backward integration into copper salt supply and geographic expansion through toll manufacturing partnerships.
Among European-integrated chemical conglomerates, BASF SE and Clariant occupy positions exemplifying crude-to-pigment control and surface-engineered specialization respectively. BASF SE represents the archetype of margin defense through captive metal supply and synthesis integration. Clariant sits within the premium-tier vector where REACH dossier depth and automotive OEM certification create defensible positioning. Sun Chemical anchors North American supply security strategies through direct mill relationships and captive dispersion capacity, representing the regional-integration archetype against distributor-network competitors.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| DIC Corporation |
| Sun Chemical |
| Heubach GmbH |
| Sudarshan Chemical Industries Ltd. |
| Meghmani Pigments |
| Kolorjet Chemicals Pvt Ltd. |
| Kesar Petroproducts Ltd. |
| Others |
Value Network & Pricing Analysis
Shandong and Zhejiang provinces concentrate global phthalocyanine crude synthesis capacity, and their MEE emission compliance costs directly transmit into downstream pigment pricing power for integrated manufacturers. Electrolytic copper price volatility and REACH registration dossier burdens create divergent margin structures between commodity crude traders and certified pigment suppliers.
Pricing Analysis
Certification level (REACH-registered versus non-registered) creates the primary spread between pigment grades, with automotive OEM weathering certifications commanding substantial premia over standard industrial coatings specifications. Pricing stratifies across premium surface-treated grades, standard conditioned pigments, and economy crude intermediates based on particle size control precision and regulatory documentation depth. Cost compression in commodity powder tiers is intensifying because Chinese capacity scaling outpaces quality differentiation investment. Mid-size coating compounders exhibit highest price sensitivity due to toll manufacturing dependency, while automotive OEM procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Electrolytic copper salt, phthalic anhydride, and urea derivatives anchor upstream feedstock dependencies for phthalocyanine synthesis operations. Manufacturing concentrates in China, Germany, and India, with dispersion and conditioning capacity distributed across North America and Europe to serve just-in-time coating compounder requirements. Single-source vulnerability to MEE enforcement actions in Shandong province threatens unconditioned crude supply security for non-integrated pigment finishers. Distribution runs through direct mill relationships and captive dispersion facilities that are displacing traditional pigment distributor networks in automotive OEM supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phthalocyanine blue sits in early-cycle expansion as waterborne coatings adoption and REACH registration tailwinds concentrate procurement toward compliant, high-performance pigment suppliers with established technical service capabilities.
For Market Incumbents: Pre-empt emerging toll manufacturing competitors by deepening captive dispersion capacity in automotive OEM supply corridors and accelerating surface-treatment R&D for sub-100 nanometer inkjet specifications. Secure backward integration into electrolytic copper supply to insulate margin from metal price volatility that compresses non-integrated producers. For New Entrants and Emerging Players: Pursue BIS-certified pigment purity positioning for India's food-contact plastics masterbatch segment, where import eligibility barriers protect compliant suppliers from Chinese commodity competition. Establish toll dispersion partnerships with mid-size coating compounders in Ohio and Michigan seeking just-in-time color matching without capital-intensive milling investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among surface-treatment specialists with established REACH only-representative structures and automotive OEM weathering certifications that lock in specification-grade supply relationships. Acquisition targets should display integrated crude-to-pigment synthesis chains or captive dispersion facilities in North American automotive corridors. Monitor ECHA enforcement intensity against non-registered pigment importers as the inflection signal for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Salt Supply | BASF SE's Ludwigshafen complex demonstrates margin defense through captive metal sourcing. |
| Surface-Treatment Capacity Expansion | Sub-100 nanometer particle control captures Japanese inkjet equipment manufacturer specifications. |
| REACH Only-Representative Establishment | ECHA compliance documentation elevates entry barriers against non-registered Chinese competitors. |
| Toll Manufacturing Partnership Formation | Sun Chemical's direct mill relationships anchor North American automotive OEM supply security. |
| Dry-Delivery Logistics Infrastructure | Powder grade shipments reduce solvent handling costs for mid-size coating compounders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coatings procurement managers at automotive OEMs, technical directors at pigment conditioning facilities, regulatory affairs specialists managing REACH dossiers, and plant managers at Shandong crude synthesis operations. Secondary validation drew from ECHA registration databases, customs trade data capturing phthalocyanine pigment flows, SEC 10-K filings of integrated chemical conglomerates, and MEE emission enforcement records. Bottom-up volume estimates from individual facility capacities were triangulated against top-down coatings industry consumption models.
Calibration against historical capacity utilization rates and pigment price indices anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier (crude, pigment, powder, paste), end-use industry (coatings, plastics, inks, textiles), form type (liquid, solid, gel, emulsion), and regional production hub concentration. CAGRs were derived from regression analysis of coatings output growth correlated with pigment intensity coefficients, incorporating automotive OEM specification trends and waterborne formulation penetration curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in electrolytic copper price trajectories, automotive production cycles, or ECHA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on REACH registration compliance rates and MEE emission standard adherence. Cross-checking against coatings industry procurement surveys and pigment trade flow customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Mulch Colorants Market