
 Metallic Pigments Market | 2026-2036
Metallic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Pigments Market Analysis
Automotive exterior coatings is decoupling from traditional solvent-borne systems as waterborne metallic formulations gain share among OEM finishers. BASF SE leverages its integrated coatings chemistry portfolio to supply pigment-dispersion systems that simplify customer formulation. ECKART GmbH anchors its position through vacuum-metalized pigment technology leadership, serving premium automotive and cosmetic applications. Sun Chemical competes on scale in the packaging inks segment, extending its distribution network across North American and European print converters.
Metallic pigments comprise thin-flake metal particles—predominantly aluminum, copper, bronze, and iron—manufactured through ball milling, atomization, or vacuum metallization, typically 1–50 microns in diameter, yielding specular reflection and opacity in applied films. Powder aluminum dominates volume due to its cost-performance ratio in automotive basecoats and architectural coil coatings, while paste and liquid forms command margin premiums in plastics compounding and gravure inks where dispersion quality determines downstream processing efficiency. Copper and bronze pigments occupy niche positions in decorative finishes and anti-microbial coatings, benefiting from specific aesthetic demand in consumer goods and specialty architecture.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based metallic coating formulations in the United States, while REACH registration requirements in Europe enforce substance-level transparency that favors established suppliers with compliance infrastructure. China's GB standards for industrial coatings, administered by MEE, are tightening VOC limits in manufacturing clusters across the Yangtze River Delta and Pearl River Delta. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate reformulation costs and qualification timelines that will determine competitive access.
Market Dynamics
Waterborne metallic coating systems are forcing a wholesale reformulation of automotive exterior finishes as OEMs confront tightening VOC limits across manufacturing clusters in China, Germany, and the United States.
Growth Catalysts
- Automotive OEM Premiumization:Vehicle manufacturers in Stuttgart, Detroit, and Shanghai are specifying metallic basecoats with enhanced specular reflection for luxury segment differentiation.
- REACH Substance Registration:ECHA transparency requirements favor established pigment suppliers with compliance infrastructure, consolidating qualified vendor pools for European coaters.
- Vacuum Metallization Advances:Thin-flake aluminum production through physical vapor deposition yields superior opacity at reduced loadings, penetrating cosmetic and electronics packaging applications.
Market Restraints
- Aluminum Feedstock Volatility:Primary aluminum ingot prices fluctuate with LME trading patterns, compressing margin predictability for flake pigment producers.
- Heavy-Metal Content Restrictions:EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne metallic formulations in United States industrial coating facilities.
- Copper Pigment Substitution:Zinc-based alternatives and interference pigments displace bronze and copper flakes in decorative architectural applications where color shift tolerance exists.
Strategic Opportunities
- Anti-Microbial Copper Integration:Healthcare facility specifications in Japan and South Korea are incorporating copper pigment touch surfaces, opening medical equipment coating channels.
- India PLI Scheme Alignment:Domestic automotive production incentives under India's production-linked incentive framework expand local metallic pigment demand for OEM supply chains.
- Digital Printing Convergence:UV-curable metallic inkjet formulations combine nanoparticle dispersion technology with narrow-web packaging presses, enabling short-run customization.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in waterborne metallic dispersion stabilization commands premium compensation, constraining R&D throughput at mid-tier coating houses.
- Dual Certification Timelines:Simultaneous GB standard qualification for China and REACH dossier preparation extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Pigments Market |
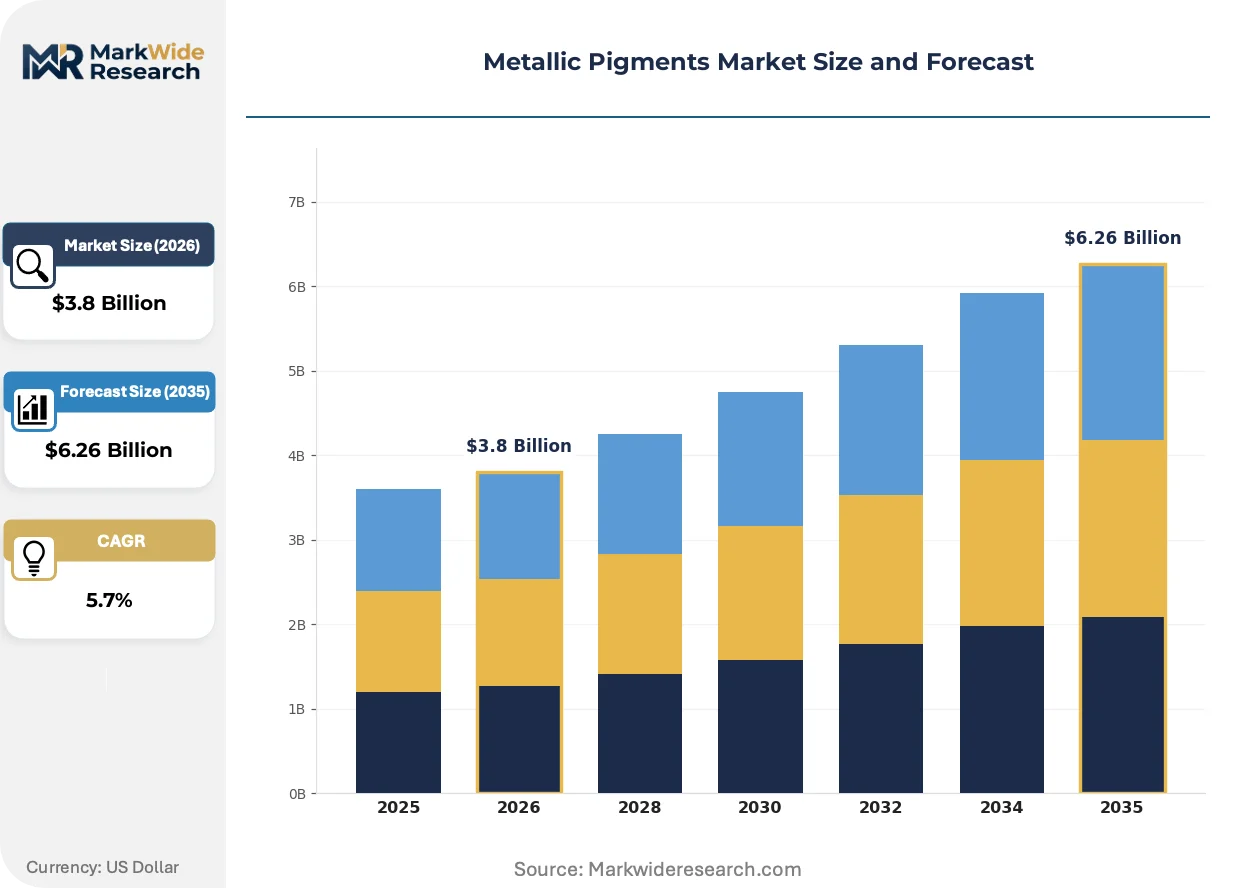
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Bronze, Iron, Copper Application: Paints, Coatings, Plastics, Inks Form: Powder, Paste, Liquid, Granules End User: Automotive, Aerospace, Consumer Goods, Architecture |
| Companies Covered | Carl Schlenk AG, Asahi Kasei Corporation, BASF SE, Clariant AG, Toyo Aluminium, ECKART GmbH, Silberline Manufacturing Company, Sudarshan Chemical Industries Limited, Sun Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Pigments Market Emerging Trajectories
Electrification of automotive powertrains is rerouting metallic pigment demand toward battery enclosure coatings and thermal management films, while regulatory chemistry constraints accelerate material substitution across all major manufacturing geographies.
Encapsulated aluminum flake technology is electrifying corrosion resistance in waterborne automotive basecoats. Tier-1 suppliers to BMW, Mercedes-Benz, and BYD are qualifying silica-coated pigments that eliminate gassing in cathodic electrocoat systems. This encapsulation architecture is compressing the performance gap between solvent-borne and waterborne metallic finishes, enabling full OEM line conversion.
China's MEE GB standards for industrial coatings are tightening VOC limits in Yangtze River Delta manufacturing clusters. Domestic coil coaters and automotive finishers are reformulating metallic systems to comply with sub-420 g/L emission thresholds. Pigment suppliers with established Shanghai technical service laboratories are capturing qualification priority as local OEMs accelerate waterborne transitions.
Specification consolidation among automotive fleet buyers is compressing approved vendor lists for metallic coating systems. Procurement teams at Stellantis, Volkswagen Group, and Geely are mandating pigment pre-dispersion from qualified single-source suppliers rather than accepting raw flake deliveries. This concentration pattern is most visible in Germany and China, where OEM technical centers enforce formulation standardization across global production networks.
Metallic Pigments Market Segmentation
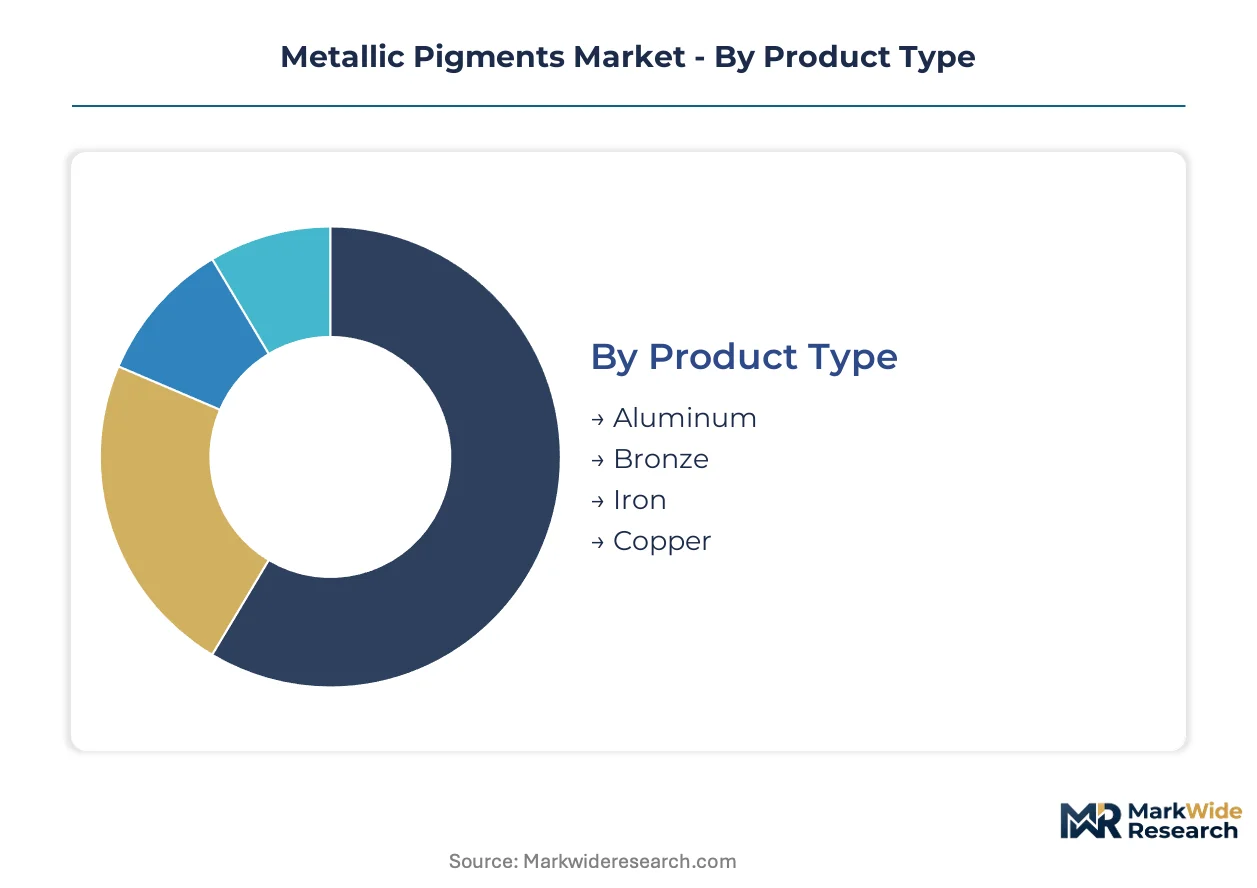
Metallic pigment segmentation reveals distinct value capture patterns across formulation chemistry and downstream integration depth. Product type and form factor determine margin architecture, while application and end-user channels dictate qualification timelines and technical service intensity.
Product Type:
Aluminum and bronze pigments operate as standalone raw materials requiring downstream dispersion, while copper and iron variants increasingly embed in pre-formulated coating systems.
- Aluminum:Thin-flake particles manufactured through ball milling or vacuum metallization deliver specular reflection and opacity at loadings of 5-15% in automotive basecoats. Powder aluminum dominates coil coating applications across manufacturing clusters in Germany, China, and the United States, though LME-linked feedstock pricing compresses margin predictability for pigment producers.
- Bronze:Copper-zinc alloy flakes ranging 10-60 microns provide warm metallic luster in decorative architectural finishes and luxury packaging. Demand concentrates in European consumer goods applications where REACH-registered suppliers hold qualification priority, though zinc-based interference pigments are displacing bronze in color-shift-tolerant specifications.
- Iron:Milled iron oxide-coated metallic particles serve corrosion-resistant primers and industrial maintenance coatings with lower cost positioning than aluminum alternatives.
- Copper:High-purity flakes leverage inherent anti-microbial properties for healthcare touch surfaces in Japanese and South Korean medical equipment specifications.
Aluminum leads volumes today; copper is gaining share fastest.
Application:
Coatings and paints absorb the highest technical service investment, while plastics and inks demand specialized dispersion engineering at compounder and converter sites.
- Paints:Architectural and industrial maintenance formulations utilize metallic pigments for aesthetic differentiation and weathering resistance. Waterborne system transitions across Yangtze River Delta manufacturing clusters are reformulating paint specifications toward encapsulated aluminum grades that eliminate gassing in cathodic electrocoat systems.
- Coatings:Automotive OEM basecoats and clearcoat systems represent the most demanding qualification environment, with BMW, Mercedes-Benz, and BYD specifying silica-coated pigments for exterior durability. Coil coating applications in building materials command volume scale with lower margin intensity than automotive finishes.
- Plastics:Masterbatch compounding for consumer electronics housings and appliance components requires liquid or paste pigment forms with pre-dispersed particle stabilization.
- Inks:Gravure and flexographic packaging applications prioritize narrow particle distribution for print consistency, with UV-curable metallic inkjet formulations enabling short-run customization.
Coatings generates the highest revenue per ton; inks is climbing the fastest.
Form:
Powder and granule forms ship as standalone inputs requiring customer-side dispersion, while paste and liquid variants embed supplier-engineered stabilization chemistry.
- Powder:Dry-flake aluminum dominates automotive basecoat and architectural coil coating volumes due to cost-performance ratio and shipping efficiency. Powder handling requires explosion-proof equipment at customer facilities, limiting adoption among smaller coating houses.
- Paste:Solvent or waterborne dispersions with pre-stabilized particle distribution command margin premiums in plastics compounding and gravure inks where downstream processing efficiency determines total applied cost.
- Liquid:Pumpable concentrates with narrow viscosity specifications serve automated dosing systems in high-volume automotive paint kitchens.
- Granules:Dust-free pelletized forms target powder coating applications and specialized masterbatch feeding equipment.
Powder leads volumes today; paste is expanding most quickly.
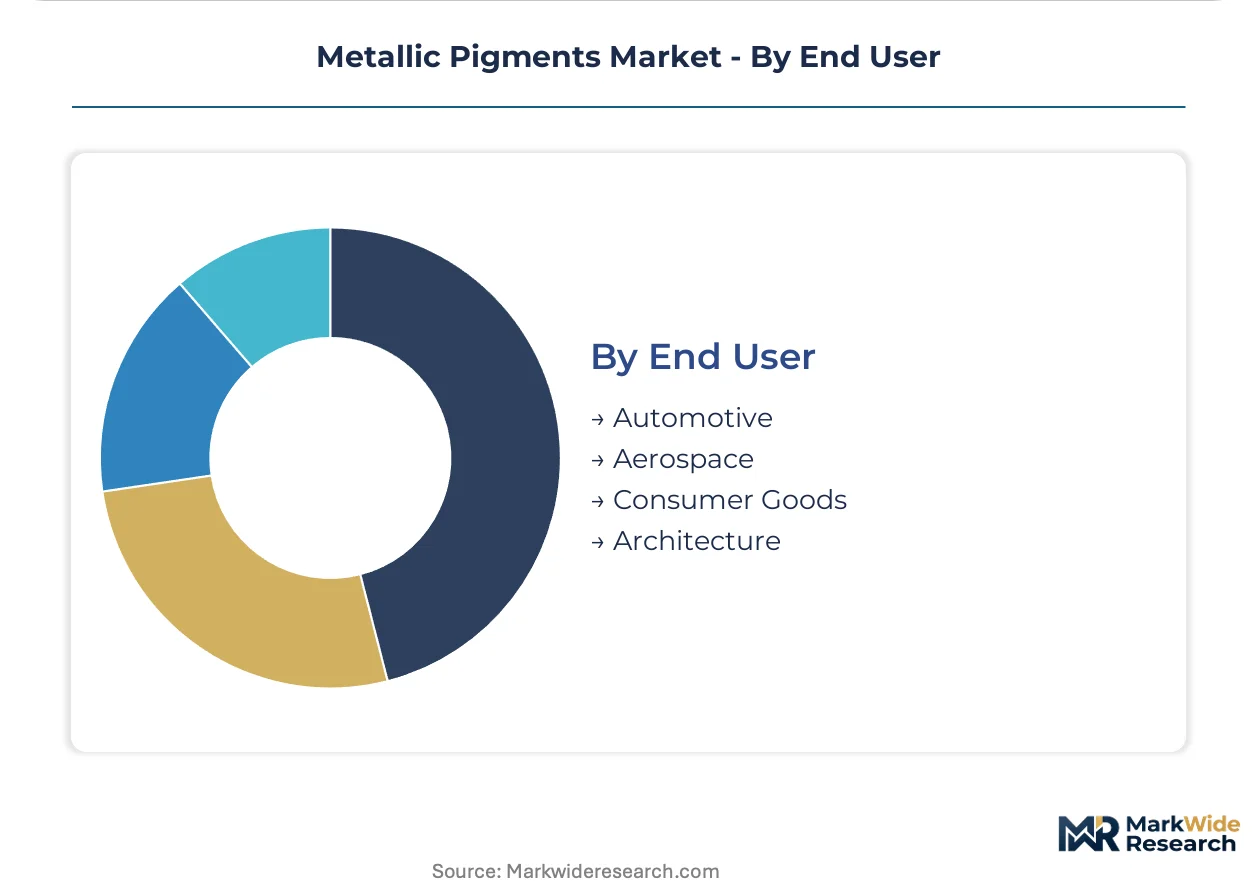
End User:
Automotive and aerospace specifications demand embedded supplier relationships with multi-year qualification cycles, while consumer goods and architecture accommodate faster vendor switching.
- Automotive:OEM exterior finish specifications at Stellantis, Volkswagen Group, and Geely mandate pigment pre-dispersion from qualified single-source suppliers rather than raw flake deliveries. Electrification trends are rerouting demand toward battery enclosure coatings and thermal management films.
- Aerospace:Military and commercial aircraft coatings prioritize corrosion resistance and weight reduction, with vacuum-metalized pigments penetrating radar-absorbent and thermal control applications.
- Consumer Goods:Cosmetics packaging and electronics housings drive cosmetic-grade pigment demand with tight particle size distribution and surface treatment requirements.
- Architecture:Coil-coated building materials and interior decorative finishes utilize bronze and aluminum pigments, with China's domestic construction investment expanding consumption across multiple specification tiers.
Automotive leads volumes today; aerospace shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting metallic pigment production toward jurisdictions with streamlined compliance pathways, as REACH dossier costs and EPA emission thresholds widen the cost-of-compliance gap between established and emerging manufacturing bases.
China
Domestic automotive production and architectural investment are expanding metallic pigment consumption across multiple end-use channels. MEE-administered GB standards for industrial coatings are tightening VOC limits in Yangtze River Delta manufacturing clusters. Domestic coil coaters and automotive finishers in Shanghai and surrounding provinces are reformulating metallic systems to comply with sub-420 g/L emission thresholds.
Germany
Automotive OEM technical centers in Stuttgart enforce formulation standardization across global production networks for metallic basecoat specifications. ECHA transparency requirements favor established pigment suppliers with compliance infrastructure, consolidating qualified vendor pools for European coaters. Pigment suppliers with established technical service laboratories in Bavaria and Baden-Württemberg are capturing qualification priority as OEMs accelerate waterborne transitions.
United States
Vehicle manufacturers in Detroit are specifying metallic basecoats with enhanced specular reflection for luxury segment differentiation. EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based metallic coating formulations in industrial coating facilities. Manufacturing clusters across the Midwest are reformulating toward encapsulated aluminum grades that eliminate gassing in cathodic electrocoat systems.
India
Domestic automotive production incentives under the production-linked incentive framework are expanding local metallic pigment demand for OEM supply chains. BIS certification requirements and evolving automotive component standards are reshaping supplier qualification protocols. Manufacturing investments in Maharashtra and Gujarat are concentrating pigment consumption near expanding OEM assembly operations.
Japan
Healthcare facility specifications are incorporating copper pigment touch surfaces, opening medical equipment coating channels with anti-microbial performance requirements. METI industrial standards and PMDA device regulations govern material qualification timelines for medical applications. Technical development concentrated in the Kanto region around Tokyo is advancing vacuum-metallized pigment formulations for electronics packaging.
Metallic Pigments Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers seek to secure pre-dispersion supply agreements with automotive OEM technical centers. The vendor base organizes around three tiers: integrated chemical conglomerates with coatings chemistry portfolios, specialized metallic pigment manufacturers with vacuum metallization capabilities, and regional compounders serving plastics and inks segments. Two strategic archetypes have emerged: technology leaders pursuing encapsulation and thin-flake advances, and scale operators optimizing powder aluminum cost positions. M&A activity and capacity expansion in waterborne dispersion facilities represent the dominant competitive moves as qualification timelines compress approved vendor lists.
Among German-based specialists, ECKART GmbH and Carl Schlenk AG occupy positions within the premium pigment tier, exemplifying technology-forward archetypes with vacuum metallization heritage. BASF SE represents the integrated chemical conglomerate archetype, anchoring the competitive structure through coatings chemistry portfolio breadth. These three entities illustrate the geographic and strategic clustering that defines supplier positioning across automotive and industrial coating channels.
| Leading Market Players |
|---|
| Carl Schlenk AG |
| Asahi Kasei Corporation |
| BASF SE |
| Clariant AG |
| Toyo Aluminium |
| ECKART GmbH |
| Silberline Manufacturing Company |
| Sudarshan Chemical Industries Limited |
| Sun Chemical |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between vacuum-metallized thin-flake pigments and conventional ball-milled aluminum separates premium automotive qualification from commodity coil coating supply, concentrating pricing power with ECHA-registered German suppliers while compressing margins for LME-tethered powder producers across Chinese manufacturing clusters.
Pricing Analysis
Distributor margin layers in European automotive channels absorb 15-25 point markups over direct OEM contracts, with contract-based long-term offtake dominating volume procurement at Stellantis and Volkswagen Group while spot transactions persist in architectural coil coating. Price differentiation hinges on REACH registration status and silica encapsulation certification, with raw aluminum feedstock volatility intensifying cost compression for unintegrated producers. Tier-1 automotive buyers exhibit lowest price sensitivity due to qualification lock-in, whereas regional Indian and Southeast Asian coaters drive hard bargaining on powder aluminum deliveries.
Supply Chain Analysis
Single-source vulnerability sits with German vacuum metallization capacity for sub-10-micron thin-flake grades qualified at BMW and Mercedes-Benz technical centers. Primary aluminum feedstock draws from Chinese smelters, Russian ingot traders, and Australian bauxite refiners, with pigment finishing concentrated in Germany, China, and the United States. Tariff exposure on aluminum raw materials threatens margin stability for non-integrated compounders. Distribution runs through qualified pre-dispersion suppliers rather than raw flake merchants, compressing approved vendor lists to ECKART, BASF, and Sun Chemical regional facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with China's MEE GB standards tightening VOC limits below 420 g/L across Yangtze River Delta manufacturing clusters and forcing wholesale waterborne reformulation that favors encapsulated pigment suppliers.
For Market Incumbents: Cement qualification priority at expanding Indian OEM technical centers under the PLI scheme, adding waterborne dispersion capacity in Maharashtra or Gujarat before local competitors achieve BIS certification. Lock in backward integration into primary aluminum sourcing to buffer LME price swings threatening margin stability at powder-grade competitors.
For New Entrants and Emerging Players: Enter via anti-microbial copper pigment supply to Japanese and South Korean medical equipment coaters, where PMDA and METI qualification pathways remain less saturated than automotive channels. Target healthcare touch-surface specifications in Kanto-region hospital construction, leveraging lower regulatory barriers than REACH-locked European consumer goods.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier vacuum metallization specialists possessing silica encapsulation IP but lacking automotive OEM qualification scale. Five-to-ten-year viability hinges on waterborne transition completion rates across Chinese and German manufacturing clusters. Watch for MEE enforcement acceleration in Pearl River Delta as inflection signal for encapsulated pigment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Dispersion Capacity Expansion | Captures qualification priority at BYD and Geely as MEE VOC limits tighten. |
| Silica Encapsulation Technology Licensing | Eliminates gassing in cathodic electrocoat systems at BMW and Mercedes-Benz. |
| Backward Integration into Primary Aluminum | Buffers LME price volatility compressing margin predictability for flake producers. |
| Anti-Microbial Copper Pigment Development | Opens PMDA-governed medical equipment channels in Japanese healthcare construction. |
| Joint Venture with Indian Coil Coaters | Aligns with PLI scheme incentives expanding domestic automotive pigment demand. |
Methodological Framework
Direct dialogue with automotive OEM procurement directors, coating formulation chemists, aluminum feedstock traders, and ECHA regulatory consultants grounded qualitative findings in operational reality, cross-referenced with customs trade data, SEC 10-K filings from listed chemical conglomerates, MEE GB standard enforcement notices, and ACC regional production surveys. Bottom-up volume modeling triangulated against top-down value estimates derived from identified contract structures.
Top-down market sizing segmented by pigment type, application channel, form factor, and end-user qualification tier across the projection horizon, with CAGRs derived from regression analysis of historical automotive production correlations and regulatory enforcement trajectories. Modeled inputs included OEM platform electrification rates, waterborne paint kitchen conversion schedules, and REACH dossier submission timelines.
Inputs from ECHA registration databases and MEE enforcement bulletins were available through the study window; gaps in private contract pricing between Tier-1 suppliers and OEMs introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and automotive platform standardization decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Hair Colorants Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Laser Sensitive Pigments Market