
 PU Coatings Market | 2026-2036
PU Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
PU Coatings Market Outlook
The capital-intensity divergence between integrated resin producers and formulation-only specialists is reorganizing competitive tiers in PU coatings. BASF SE leverages captive polyol supply chains to sustain margin compression in raw material cycles. PPG Industries Inc. anchors its position through aerospace and automotive OEM qualification networks that competitors struggle to replicate. Akzo Nobel N.V. differentiates via marine and protective coatings segments where specification stickiness creates defensive moats.
Polyurethane coatings are polymer systems formed by the reaction of polyols with isocyanates, yielding films with hardness ratings from 2H to 6H pencil hardness and elongation at break between 50% and 400% depending on crosslink density. These formulations serve primarily as protective and decorative layers where abrasion resistance, chemical tolerance, and UV stability prove critical. Aqueous coatings command expanding share in wood furniture and interior architectural applications where VOC thresholds below 100 g/L have become standard. Solvent-borne coatings retain dominance in automotive refinish and heavy equipment segments where application speed and humidity tolerance outweigh environmental compliance costs. UV-cured coatings represent the fastest-growing technology subset in electronics and flooring, driven by instant cure cycles that eliminate rack space and work-in-process inventory.
REACH registration requirements and EPA National Emission Standards for Hazardous Air Pollutants constrain isocyanate handling and solvent content across EU and US manufacturing footprints. China's MEE enforces GB standards on VOC emissions from coating operations, pushing domestic producers toward waterborne and high-solids platforms. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance cost asymmetries will determine which formulation technologies achieve scalable cost positions.
Market Dynamics
Waterborne polyurethane formulation mandates under REACH and EPA VOC regulations are forcing solvent-borne substitution across automotive OEM and industrial coating operations, compressing incumbent supply chains while opening formulation-only specialists to margin pressure from integrated resin producers.
Growth Catalysts
- REACH solvent restrictions:EU automotive OEMs now specify waterborne PU for exterior basecoats, accelerating qualified supplier expansion across German and Czech manufacturing clusters.
- Automotive OEM chip-resistance specifications:Exterior durability requirements for EV platforms are expanding PU coating thickness tolerances and crosslink density standards in China and the United States.
- UV-cure instant cycle technology:Electronics manufacturers in South Korea and Taiwan are eliminating rack space and work-in-process inventory through UV-cured PU flooring and device housing applications.
Market Restraints
- Isocyanate feedstock concentration:MDI and TDI supply concentrates among three Asian and Middle Eastern producers, exposing formulators to input cost volatility and force majeure risk.
- Humidity tolerance technical ceiling:Waterborne PU coatings fail to match solvent-borne application speed in high-humidity climates, constraining adoption in Southeast Asian refinish operations.
- EPA NESHAP compliance friction:Isocyanate handling restrictions increase capital requirements for US manufacturing footprint expansion, disadvantaging mid-scale specialists against integrated majors.
Strategic Opportunities
- India construction sector underpenetration:Architectural wood coatings remain dominated by alkyd systems, creating conversion runway as BIS VOC standards tighten and urban commercial construction accelerates.
- Marine protective specification stickiness:Offshore wind installation growth in the North Sea and Baltic is generating demand for PU topcoats with 15+ year salt-spray resistance, rewarding qualified applicator networks.
- AI Act supply chain transparency:EU machinery OEMs now require coating origin documentation for CE-marked equipment, creating certification-based pricing power for EU-based formulators with auditable resin sourcing.
Industry Challenges
- Formulation chemist skill scarcity:Waterborne PU rheology control and film-formation expertise concentrates among aging specialists in Germany and Japan, constraining new facility commissioning timelines.
- Automotive OEM qualification cycle compression:EV platform launch schedules demand coating approvals in 18-24 months versus historical 36-48 month windows, stretching R&D and testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PU Coatings Market |
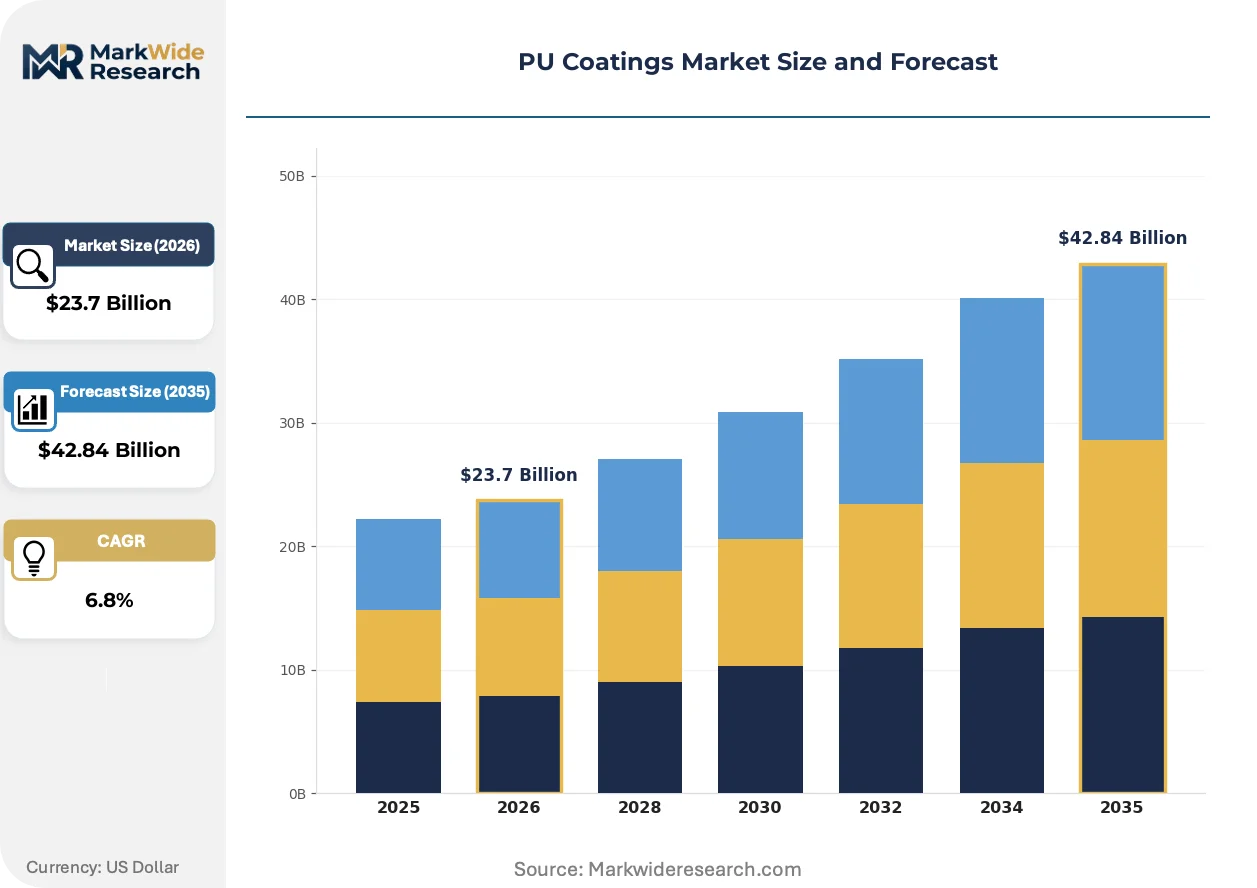
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Coatings, Solvent-borne Coatings, UV-cured Coatings, High-solids Coatings End User: Automotive, Construction, Woodworking, Electronics Application: Floor Coatings, Furniture Coatings, Industrial Coatings, Automotive Coatings Technology: Spray Coating, Roll Coating, Brush Coating, Dip Coating |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., The Sherwin-Williams Company, Axalta Coating Systems, Jotun, BASF SE, RPM International Inc., Asian Paints, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PU Coatings Market Strategic Shifts
Formulation technology is splitting along performance-versus-compliance axes as regulatory pressure intensifies, with application-specific solutions displacing general-purpose platforms across automotive, electronics, and protective segments.
Waterborne polyurethane is bifurcating between high-performance automotive grades achieving solvent-borne humidity tolerance through hybrid acrylic-PU copolymers, and cost-optimized architectural variants accepting reduced block resistance in exchange for sub-50 g/L VOC compliance. German and US automotive OEMs are qualifying the former for exterior basecoat applications at accelerated 12-month validation cycles. This technology split is compressing mid-tier formulators lacking either performance R&D or commodity scale, concentrating share among integrated resin producers and regional waterborne specialists.
REACH authorization requirements for diisocyanate respiratory sensitizers entered full enforcement across EU manufacturing and professional application settings, mandating worker training certification and exposure monitoring. Industrial maintenance and automotive refinish operations face 15-20% labor cost inflation from compliance infrastructure. Spanish and Italian coating applicators are responding through automated spray booth investment and subcontractor consolidation to amortize fixed compliance costs across larger job volumes.
Automotive OEM procurement departments are unbundling coating supply from integrated body-in-white contracts, creating direct specification relationships with tier-2 formulators previously masked by system integrators. This pattern is most visible in German and Chinese EV platform launches, where battery enclosure and exterior panel coating decisions now bypass traditional paint-shop general contractors. The shift exposes formulators to volume commitment risks and price transparency pressures previously absorbed by system suppliers.
PU Coatings Market Segmentation
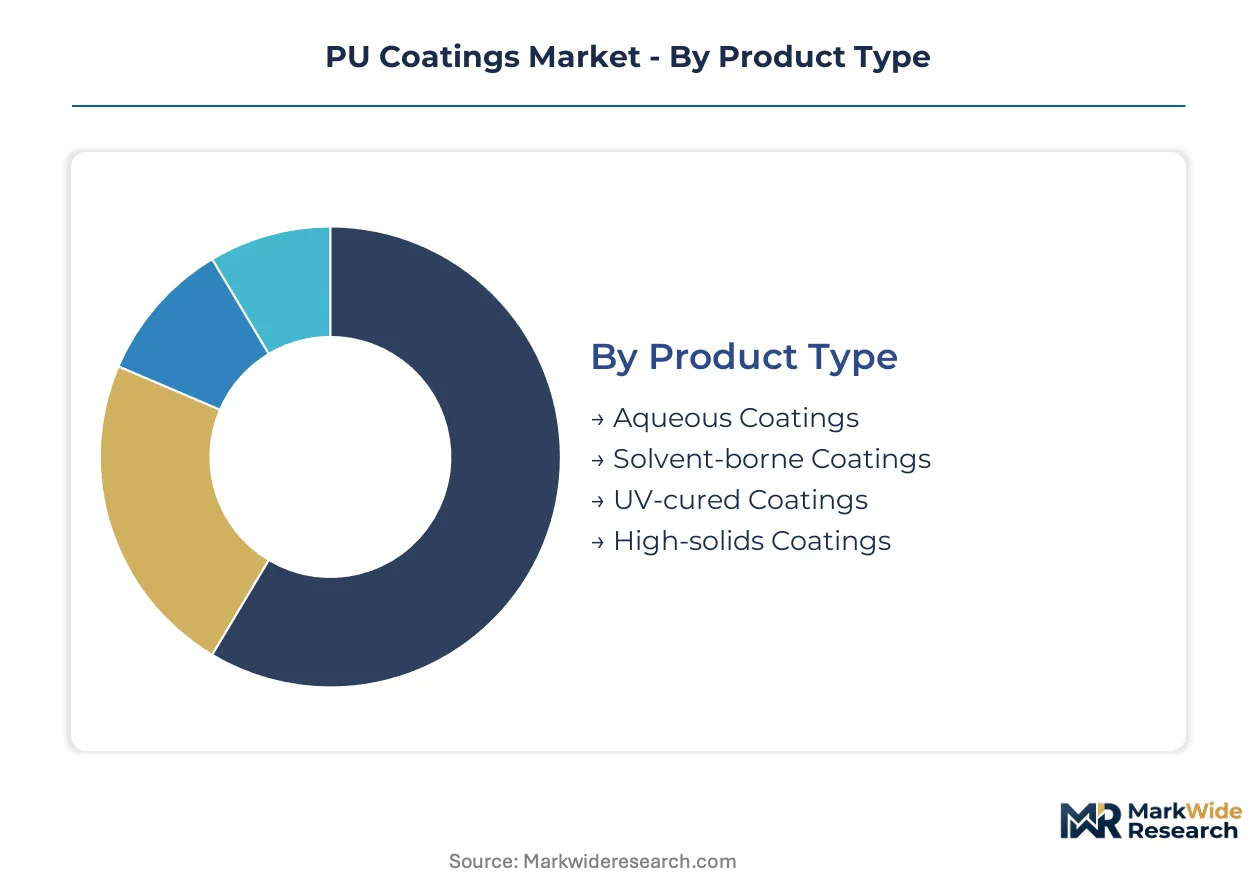
PU coating formulations diverge sharply across end-use specifications, with automotive OEMs demanding chip-resistant exterior films while architectural applications prioritize sub-50 g/L VOC compliance. Technology selection tracks regional regulatory maturity, creating distinct competitive arenas between integrated resin producers and formulation specialists.
Product Type:
Geographic demand patterns split between domestic-consumption coatings in regulated markets and export-oriented solvent-borne platforms serving humidity-sensitive climates.
- Aqueous Coatings:Hybrid acrylic-PU copolymers achieve humidity tolerance matching solvent-borne films in German and US automotive exterior basecoats. REACH and EPA VOC mandates accelerate qualified supplier expansion across Czech and Michigan manufacturing clusters.
- Solvent-borne Coatings:Retain dominance in automotive refinish and heavy equipment where application speed outweighs environmental compliance costs. Southeast Asian humidity constraints sustain demand in Thailand and Indonesian refinish operations despite regulatory pressure.
- UV-cured Coatings:Instant cure cycles eliminate rack space in South Korean and Taiwanese electronics manufacturing.
- High-solids Coatings:Bridge compliance and performance in US industrial maintenance where NESHAP restrictions apply.
Solvent-borne coatings hold the largest share; momentum sits with UV-cured platforms.
End User:
Customer concentration varies by capital intensity, with automotive OEMs driving specification intensity while construction procurement fragments across project-based awards.
- Automotive:EV platform launches demand 18-24 month qualification cycles versus historical 36-48 month windows. Battery enclosure and exterior panel specifications now bypass traditional paint-shop contractors in German and Chinese supply chains.
- Construction:Architectural wood coatings in India remain alkyd-dominated, creating conversion runway as BIS VOC standards tighten.
- Woodworking:Furniture manufacturers in Vietnam and Poland specify waterborne PU for EU export compliance.
- Electronics:Device housing applications in Taiwan and South Korea favor UV-cured films for throughput.
Automotive commands premium pricing power; construction offers volume scale.
Application:
Film thickness tolerances and crosslink density standards segment the market between protective heavy-duty layers and decorative thin-film systems.
- Floor Coatings:Abrasion-resistant PU films with 2H-6H pencil hardness protect industrial and commercial substrates. Electronics manufacturers specify UV-cured flooring in South Korea to eliminate work-in-process inventory.
- Furniture Coatings:Block resistance trade-offs dominate architectural variants seeking sub-50 g/L VOC compliance.
- Industrial Coatings:Offshore wind installations in the North Sea demand 15+ year salt-spray resistance.
- Automotive Coatings:Exterior durability specifications expand PU coating thickness for chip resistance on EV platforms.
Floor coatings anchor revenue stability; automotive coatings climb fastest on EV penetration.
Technology:
Application method selection tracks labor cost structures and capital availability, with automated systems concentrating in high-wage manufacturing bases.
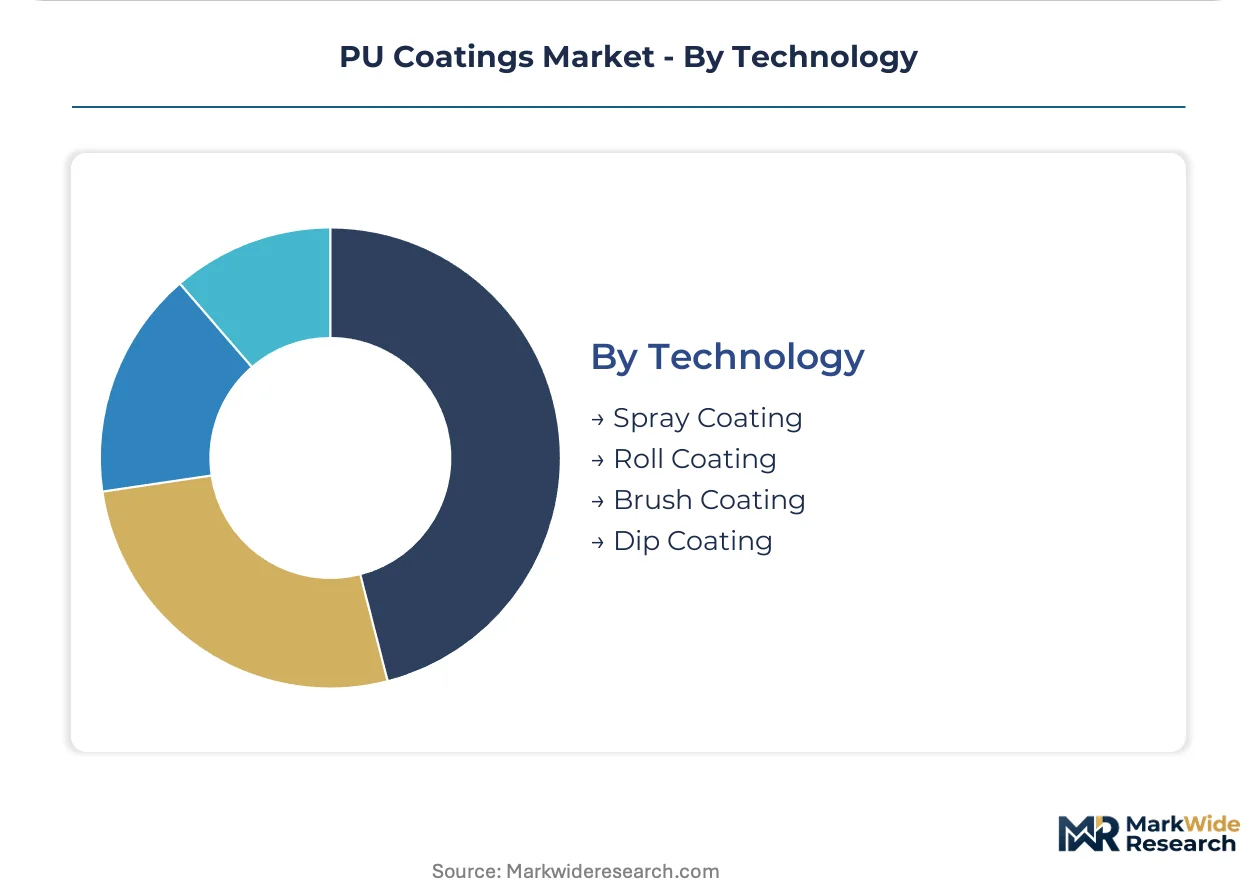
- Spray Coating:Dominates automotive OEM and refinish operations where film uniformity is critical. Spanish and Italian applicators invest in automated spray booths to amortize REACH diisocyanate compliance costs across larger job volumes.
- Roll Coating:Standard for flat-panel furniture and flooring in high-throughput manufacturing.
- Brush Coating:Persists in maintenance and touch-up applications where equipment mobility matters.
- Dip Coating:Serves small-part electronics and hardware with complex geometries.
Spray coating retains the largest installed base; roll coating gains share on furniture export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation cost premiums in Germany and the United States exceed those in China by margins that reflect regulatory compliance infrastructure and captive resin supply chain density. This pricing-power asymmetry is reorganizing manufacturing footprints and supplier qualification networks across automotive and industrial coating end-uses.
China
Automotive OEMs in the Yangtze River Delta and Pearl River Delta are expanding PU coating specifications for EV battery enclosures and exterior panels. MEE enforcement of GB standards on VOC emissions accelerates waterborne and high-solids platform conversion among domestic producers. Manufacturing clusters in Shanghai and Guangzhou host the most intensive supplier qualification activity for chip-resistant exterior films.
Germany
REACH authorization requirements for diisocyanate respiratory sensitizers entered full enforcement across manufacturing and professional application settings. Automotive OEM procurement departments in Bavaria and Baden-Württemberg are unbundling coating supply from integrated body-in-white contracts. Stuttgart and Munich manufacturing corridors concentrate automated spray booth investment to amortize compliance costs.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain isocyanate handling and solvent content across manufacturing footprints. Automotive OEMs in Michigan specify waterborne PU for exterior basecoats with accelerated 12-month validation cycles. Detroit-area manufacturing clusters anchor the most intensive R&D and testing capacity expansion for EV platform coating approvals.
India
Architectural wood coatings remain dominated by alkyd systems, creating conversion runway as BIS VOC standards tighten. Urban commercial construction acceleration in Maharashtra and Gujarat drives specification intensity for waterborne PU in furniture export manufacturing. Mumbai and Ahmedabad industrial corridors concentrate the earliest qualified supplier networks for EU export compliance.
South Korea
Electronics manufacturers specify UV-cured PU flooring and device housing applications to eliminate rack space and work-in-process inventory. MFDS alignment with international chemical registration standards supports formulation technology licensing from German and Japanese specialists. Seoul Capital Area and Busan-Ulsan manufacturing clusters anchor the fastest-growing technology subset in regional electronics supply chains.
PU Coatings Market Competitive Environment
Concentration sits with integrated resin producers wielding captive polyol supply chains against formulation-only specialists exposed to raw material cycle volatility. BASF SE exemplifies the former archetype, while PPG Industries Inc. and Akzo Nobel N.V. occupy positions as formulation-heavy multinationals with aerospace and marine qualification networks. Competitive moves center on backward integration into isocyanate feedstocks and strategic partnerships with automotive OEM procurement departments to secure direct specification relationships.
Among Netherlands-based multinationals, Akzo Nobel N.V. exemplifies the marine and protective coatings specialist archetype where specification stickiness creates defensive positioning. PPG Industries Inc. anchors the aerospace and automotive OEM qualification tier that competitors struggle to replicate. BASF SE represents the integrated resin producer archetype leveraging captive supply chains to sustain margin compression cycles. These three occupy positions across distinct competitive vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| Jotun |
| BASF SE |
| RPM International Inc. |
| Asian Paints |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for diisocyanate respiratory sensitizers gate both supplier qualification networks and price differentiation tiers simultaneously, forcing formulators to absorb compliance infrastructure costs that separate certified premium supply from uncertified commodity alternatives. Automotive OEMs now demand auditable coating origin documentation, compressing margins for non-compliant specialists while rewarding integrated producers with captive resin supply chains.
Pricing Analysis
Configured-to-order pricing for automotive OEM exterior basecoats commands substantial premiums over standard architectural formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EV platform chip-resistance specifications driving the widest spreads. Cost compression in mid-tier waterborne formulations is intensifying because REACH and EPA compliance infrastructure amortizes poorly below threshold volumes. Construction procurement in India exhibits highest price sensitivity, while aerospace qualification networks show lowest elasticity due to specification stickiness.
Supply Chain Analysis
Germany and China anchor isocyanate feedstock conversion and formulation manufacturing for automotive and industrial end-uses. MDI and TDI supply draws from concentrated Asian and Middle Eastern producers, exposing formulators to input cost volatility. Single-source vulnerability in specialty polyol supply constrains new facility commissioning timelines for waterborne PU specialists. Distribution runs through qualified applicator networks in regulated markets and open-channel distributors in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against powder coatings and UV-curable acrylates in electronics and flooring applications, requiring incumbents to embed switching costs through qualification networks and specification lock-in.
For Market Incumbents: Secure automotive OEM direct specification relationships before EV platform launch schedules compress qualification windows further. Deepen backward integration into captive polyol supply to sustain margin compression cycles. Defend against formulation-only specialists by accelerating waterborne humidity tolerance R&D in German and Michigan testing corridors. For New Entrants and Emerging Players: Differentiate on marine protective coatings for offshore wind installations in the North Sea and Baltic, where specification stickiness rewards qualified applicator networks. Target India's architectural wood coating conversion runway as BIS VOC standards tighten. Pursue licensing partnerships with German and Japanese waterborne rheology specialists to bypass formulation chemist scarcity constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional waterborne specialists lacking integrated resin supply chains. Five-to-ten year viability hinges on regulatory divergence between EU and Asian jurisdictions creating persistent cost asymmetries. Watch for REACH authorization enforcement intensity in Southern European applicator markets as inflection indicator for compliance cost amortization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstocks | Captive MDI supply insulates BASF from force majeure volatility in Asian producer networks. |
| Automotive OEM Direct Specification Partnership | Unbundled coating supply contracts in Stuttgart and Shanghai bypass traditional paint-shop intermediaries. |
| Waterborne Humidity Tolerance R&D Expansion | Hybrid acrylic-PU copolymers achieve solvent-borne performance for Southeast Asian refinish conversion. |
| Marine Protective Qualification Network Buildout | 15+ year salt-spray certification captures offshore wind growth in North Sea installation corridors. |
| Automated Spray Booth Capital Deployment | Spanish and Italian applicators amortize REACH diisocyanate compliance costs across consolidated job volumes. |
Study Parameters
Cross-validation between procurement director interviews at automotive OEMs and customs trade data anchors the qualitative findings on supplier concentration and pricing power asymmetries. Primary fieldwork encompassed coating formulator R&D heads, Tier 1 supplier procurement leads, marine protective applicators in Northern Europe, and distribution channel partners in India. Secondary validation drew from ECHA REACH registration databases, EPA NESHAP compliance filings, SEC 10-K disclosures from integrated chemical producers, and BIS standard notification records. Bottom-up formulation demand modeling triangulated against top-down end-use consumption estimates.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and raw material price volatility assumptions throughout the projection horizon. Segmentation dimensions modeled include formulation technology type, end-use industry vertical, application method, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansion timelines and OEM platform launch schedules. Industry-specific inputs encompassed EV battery enclosure coating content per vehicle and offshore wind installation growth trajectories.
Material uncertainties — feedstock supply disruption, regulatory enforcement divergence, and substitution acceleration by powder coatings — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding REACH authorization implementation consistency and waterborne humidity tolerance technical ceilings. Recalibration cycles align with material shifts in automotive OEM qualification timelines and MEE GB standard enforcement intensity in Chinese manufacturing clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyurea Coating Market
Coatings
France Automotive OEM Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Silicate Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
South America Thermal Spray Market
Coatings
E-Coat Market
Coatings
Wood Sealer Market
Coatings
Coating Pigments Market
Coatings
Global Coated Steel Market
Coatings
Electrical Insulation Coatings Market
Coatings
Rail Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
High Performance Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market