
 Zinc Oxide Pigments Market | 2026-2036
Zinc Oxide Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Oxide Pigments Market Analytics
Modular grade bundling is pivoting procurement patterns across the zinc oxide pigments value chain. BASF SE leverages its integrated precursor chemistry to sustain captive supply advantages for coated and micronized variants. EverZinc anchors European demand through specialized production of high-purity grades for pharmaceutical and cosmetic applications. Hindustan Zinc Limited dominates Indian supply through backward integration into mined zinc concentrate, controlling raw material costs across powder and granule forms.
Zinc oxide pigments comprise crystalline ZnO powders synthesized via the French process (direct combustion of zinc metal) or the American process (reduction of zinc ore), with particle sizes ranging from sub-100 nm for transparent grades to several micrometers for standard opacity applications, serving primarily as UV absorbers, vulcanization activators, and antimicrobial agents in industrial formulations. The rubber application segment leads volume consumption through tire manufacturing demand for activation in sulfur vulcanization, while the cosmetics application segment commands premium pricing for transparent and micronized grades meeting pharmaceutical purity standards. Coated product types are gaining structural share as surface-treated variants reduce agglomeration and improve dispersion in polymer matrices.
REACH registration requirements in Europe and EPA oversight under the Toxic Substances Control Act in the United States govern nano-scale zinc oxide classification, labeling thresholds, and environmental release limits, directly influencing formulation choices in sunscreen and coatings. China's GB standards and MIIT industrial guidelines set domestic purity benchmarks and emission controls for French process operations, shaping export competitiveness and local market access. Stakeholders must monitor evolving nano-material definitions across regulatory jurisdictions to anticipate reformulation costs and qualification timelines for next-generation pigment grades.
Market Dynamics
REACH nano-material labeling mandates and EU Green Deal emission ceilings are forcing European zinc oxide suppliers to requalify entire product portfolios, while Chinese domestic absorption of standard grades tightens export availability for international buyers.
Growth Catalysts
- UV-protection formulation expansion:Sunscreen manufacturers in France and Germany are absorbing micronized and transparent zinc oxide grades at accelerating rates to meet SPF 50+ claims without chemical filter restrictions.
- Tire manufacturing concentration:China's domestic rubber compounding sector consumes substantial volumes of French-process zinc oxide for sulfur vulcanization activation, anchoring regional production scale.
- REACH registration completion:Full dossier compliance for nano-scale zinc oxide variants has unlocked sustained access to European cosmetic and pharmaceutical formulation channels.
Market Restraints
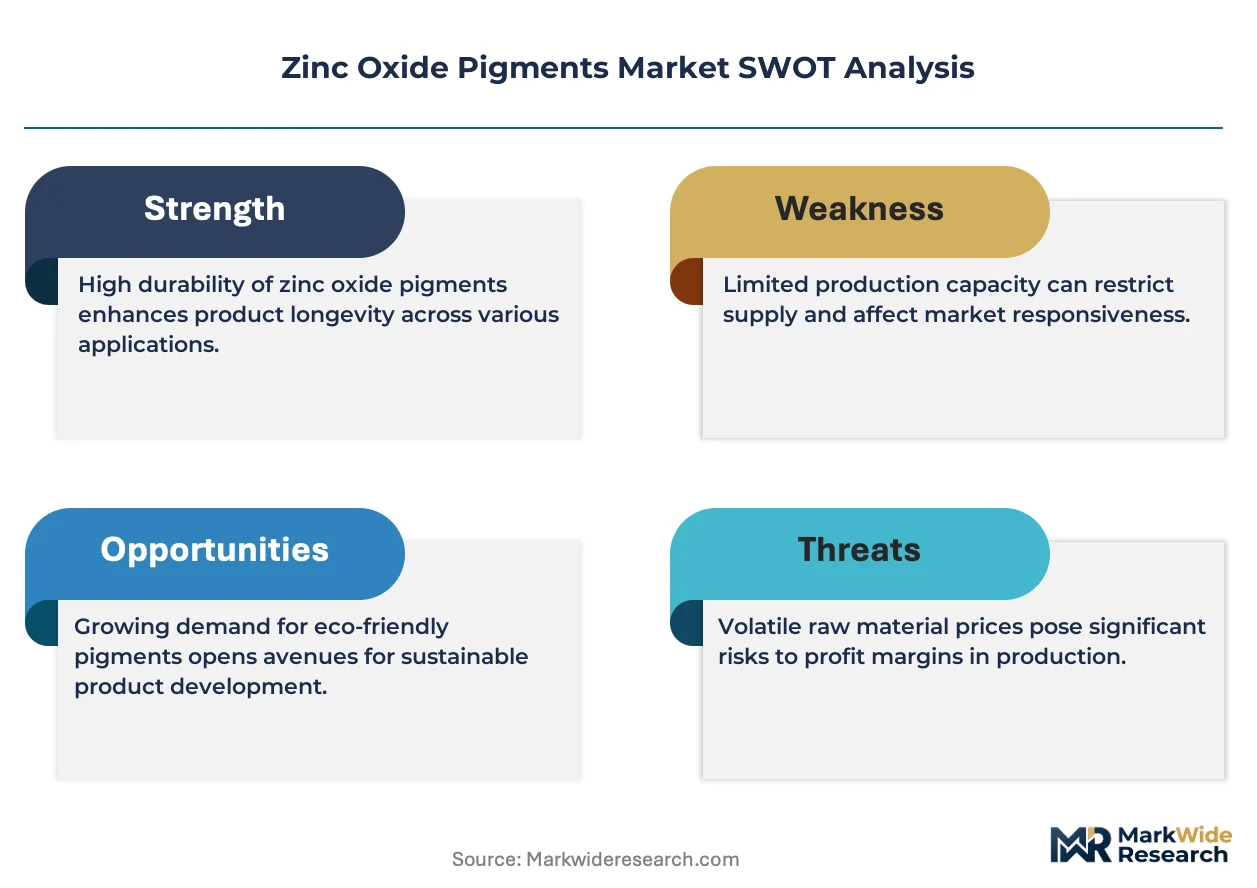
- Zinc metal price volatility:London Metal Exchange zinc ingot fluctuations transmit directly to French-process pigment production costs, compressing margin predictability for non-integrated manufacturers.
- Substitution pressure from titanium dioxide:Opacity-grade zinc oxide faces displacement in interior coatings where TiO2 suppliers have improved dispersibility and reduced photocatalytic degradation.
- Supply concentration in Shandong province:Over half of China's exportable zinc oxide pigment capacity clusters in this coastal region, exposing buyers to concentrated logistics and environmental enforcement risks.
Strategic Opportunities
- Indian pharmaceutical-grade expansion:CDSCO's tightening purity requirements for topical zinc oxide create qualification windows for producers offering USP-grade material with sub-50 ppm heavy metal content.
- Antimicrobial polymer integration:Convergence of zinc oxide surface modification chemistry with masterbatch compounding expertise enables direct supply to medical device housings and food-contact plastics.
- Brazilian tire localization:ANVISA-aligned import substitution policies favor regional zinc oxide production for domestic rubber vulcanization, bypassing ocean freight cost inflation.
Industry Challenges
- Nano-toxicology expertise scarcity:Formulators lack in-house capability to interpret OECD Test Guideline 412 inhalation data for worker exposure assessments, delaying new grade launches.
- Coating line retrofit capex:Surface treatment equipment for silane-coated zinc oxide requires dedicated fluidized bed reactors, demanding capital commitments that mid-scale producers struggle to fund.
- Multi-jurisdiction dossier synchronization:Divergent nano-material definitions between EPA TSCA, REACH, and NMPA filing requirements force redundant toxicology studies and extended qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Oxide Pigments Market |
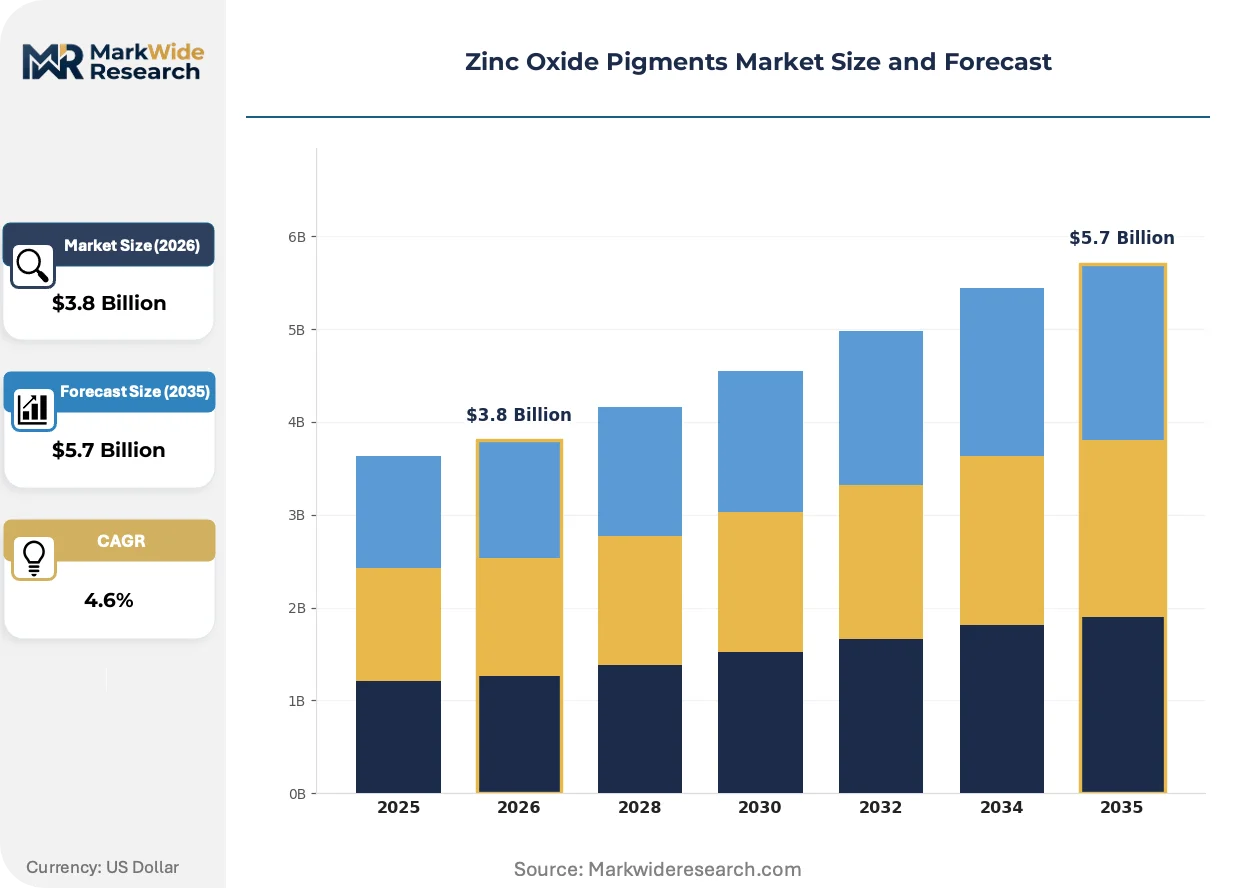
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Transparent, Transparent, Micronized, Coated Application: Coatings, Plastics, Rubber, Cosmetics End Use Industry: Construction, Automotive, Pharmaceuticals, Agriculture Form: Powder, Granules, Paste, Liquid |
| Companies Covered | BASF SE, EverZinc, Hindustan Zinc Limited, U.S. Zinc, Pan-Continental Chemical Co., Ltd., Hakusui Tech, Zinc Nacional, Lanxess, Grillo-Werke AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Oxide Pigments Market Evolving Landscape
Continuous French-process furnace automation and closed-loop emission capture systems are compressing unit economics for standard-grade production, while downstream formulation demands pull toward ever-finer particle distributions and surface-functionalized variants.
Plasma-enhanced chemical vapor deposition for zinc oxide nanoparticle synthesis is decentralizing production geography by enabling modular, lower-throughput units to achieve pharmaceutical-grade purity without the scale economies of traditional combustion furnaces. Regional compounders in Italy and South Korea are installing these systems to serve cosmetic formulators with just-in-time transparent grade supply. This distributed manufacturing model is compressing inventory carrying costs and reducing exposure to bulk shipping rate volatility.
REACH Annex VI nanoform classification amendments are forcing reformulation of sunscreen products containing uncoated zinc oxide particles below 100 nm, with ECHA's 2024 guidance triggering voluntary withdrawals from several European private-label brands. The industrial consequence is accelerated qualification of surface-silanized variants that fall outside the nano definition while maintaining UV attenuation performance. French and German cosmetic manufacturers are absorbing premium pricing for these compliant grades to avoid labeling requirements that consumers associate with safety concerns.
Direct procurement contracts between tire manufacturers and zinc oxide producers are displacing distributor-mediated spot purchases across the European rubber compounding sector. Continental and Michelin have established annual volume agreements with coated-grade specialists, locking in specification-locked supply chains that bypass traditional chemical traders. This concentration of buying power is most visible in Germany's industrial Rhine corridor, where logistics-integrated suppliers now capture margin that previously fragmented across multiple intermediaries.
Zinc Oxide Pigments Market Segmentation
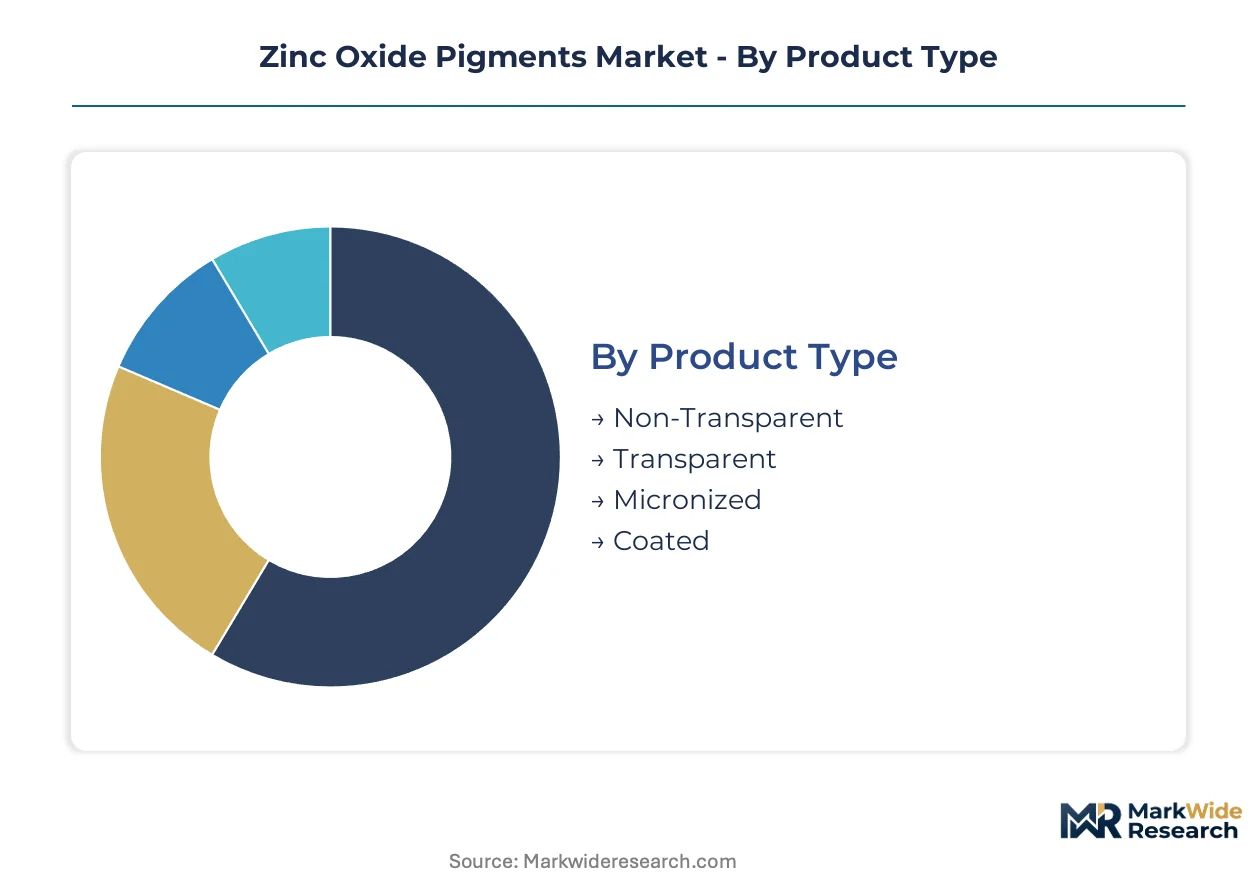
Zinc oxide pigment buyers prioritize performance specifications over base chemistry, driving segmentation around optical properties, dispersion behavior, and regulatory compliance tiers. Formulators in cosmetics and tire manufacturing demand fundamentally different particle architectures, fragmenting procurement patterns across end-use channels.
Product Type:
Particle architecture dictates formulation compatibility and regulatory pathway, with transparency thresholds and surface chemistry determining price realization.
- Coated:Silane or polymer surface treatments reduce agglomeration in polymer matrices and enable REACH-compliant positioning outside nano-material classification. French and German cosmetic formulators absorb silanized grades to sidestep ECHA labeling mandates while maintaining SPF performance.
- Micronized:Sub-micron particle distributions deliver transparent UV attenuation for high-SPF sunscreen formulations. Sunscreen manufacturers in France and Germany source these grades aggressively as chemical filter restrictions tighten.
- Transparent:Engineered refractive index matching enables invisible application in clear cosmetic bases. Korean and Italian compounders deploy these in premium skincare lines.
- Non-Transparent:Standard opacity grades serve industrial coatings and rubber vulcanization where cost efficiency dominates specification.
Volume sits with non-transparent grades for rubber and coatings; growth tilts toward coated variants as regulatory compliance premiums expand.
Application:
End-use performance requirements create divergent purity and particle size specifications, with cosmetic and pharmaceutical channels commanding substantial price premiums over industrial segments.
- Cosmetics:Pharmaceutical-grade purity with sub-50 ppm heavy metal content meets CDSCO and FDA topical standards. Indian and US formulators drive qualification timelines for USP-grade material.
- Rubber:French-process zinc oxide activates sulfur vulcanization in tire manufacturing, with Chinese domestic tire producers anchoring regional consumption scale.
- Coatings:Opacity and photochemical stability requirements position zinc oxide against titanium dioxide in interior and exterior architectural applications.
- Plastics:Antimicrobial masterbatch integration demands surface-modified grades compatible with polyethylene and polypropylene processing temperatures.
Rubber applications capture the largest volume footprint; cosmetics exhibits the steepest expansion trajectory as clean-label sunscreen demand accelerates.
End Use Industry:
Regulatory stringency and specification depth vary dramatically across sectors, with pharmaceutical and automotive channels imposing the most rigorous qualification protocols.
- Automotive:Tire manufacturing concentrates demand for standard-grade zinc oxide in sulfur vulcanization, with direct procurement contracts displacing distributor channels across Germany's industrial Rhine corridor.
- Pharmaceuticals:Topical zinc oxide for dermatological applications requires USP-grade certification with exhaustive heavy metal testing. CDSCO's tightening purity standards in India create qualification windows for specialized producers.
- Construction:Architectural coatings and exterior finishes absorb opacity-grade material, with Chinese infrastructure spending anchoring regional demand.
- Agriculture:Fungicidal formulations and animal feed supplements utilize standard powder grades with less stringent purity requirements than pharmaceutical channels.
Automotive consumption holds the volume base; pharmaceuticals is gaining share fastest as topical application standards tighten globally.
Form:
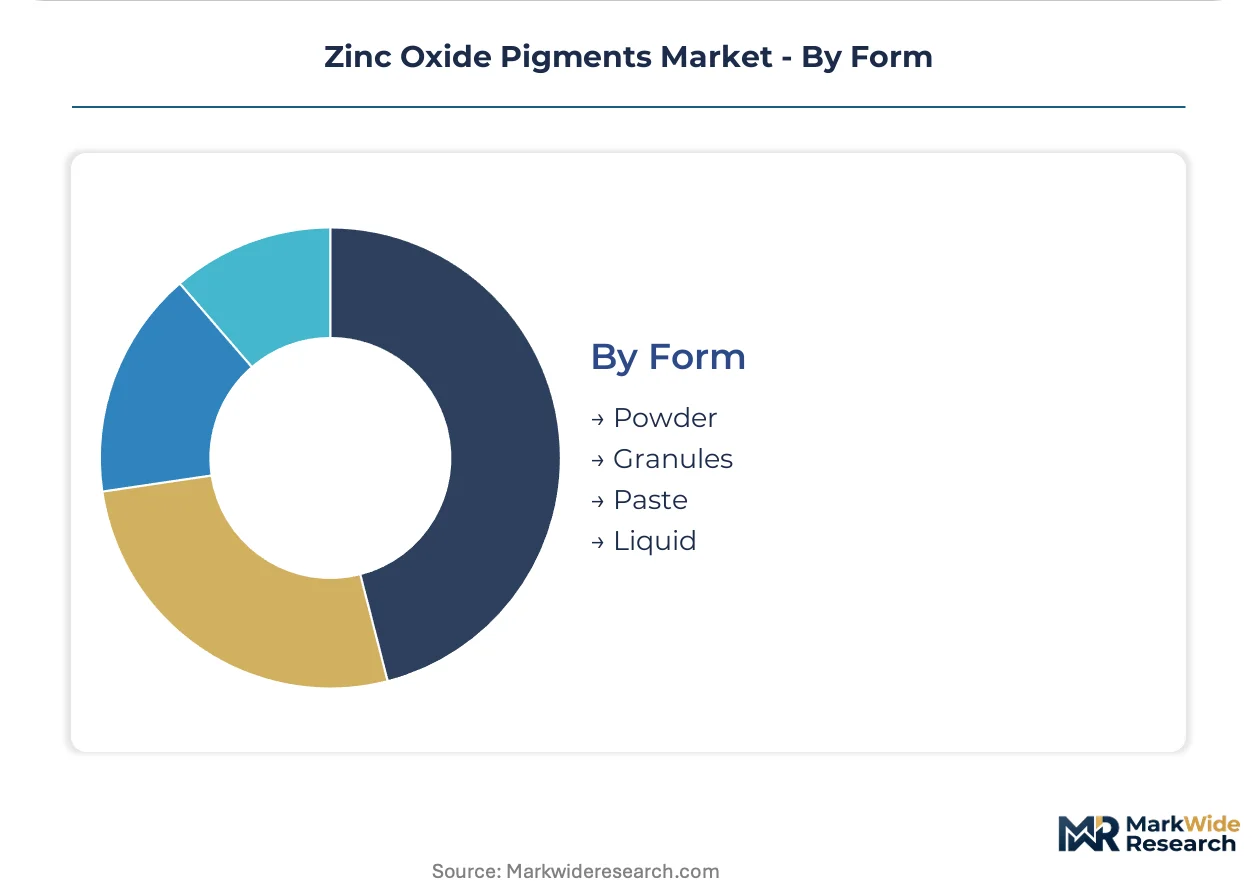
Physical presentation determines handling economics, dispersion efficiency, and compatibility with automated compounding systems across manufacturing scales.
- Powder:The foundational presentation for French-process output, serving rubber compounding and coatings manufacturing where dust control systems manage occupational exposure.
- Granules:Reduced dusting characteristics improve handling in large-scale tire manufacturing and automated feed systems.
- Paste:Pre-dispersed concentrates eliminate milling steps for cosmetic formulators and small-batch coatings producers.
- Liquid:Aqueous suspensions serve specialized ink and fine coatings applications requiring precise viscosity control.
Powder dominates shipment volumes; paste forms are climbing the fastest as cosmetic compounders prioritize processing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's chemical industrial parks concentrate over half of China's exportable zinc oxide pigment capacity, drawing French-process producers into coastal clusters with integrated port logistics and MIIT-supervised emission controls.
China
Domestic tire manufacturing and ceramics production absorb substantial volumes of standard and coated zinc oxide pigments. MIIT industrial guidelines and GB standards set purity benchmarks and emission controls for French process operations. Shandong province's coastal industrial parks host the majority of export-facing production capacity.
Germany
Cosmetic formulators in the Rhine corridor absorb silanized and micronized grades for SPF 50+ sunscreen formulations. REACH Annex VI nanoform classification and ECHA labeling mandates drive qualification of surface-treated variants. Continental and Michelin have established direct procurement contracts with coated-grade specialists, bypassing traditional chemical traders.
United States
Sunscreen manufacturers source transparent and micronized grades to meet FDA topical standards and EPA TSCA nano-material oversight. The country's national pharmaceutical regulator maintains exhaustive heavy metal testing protocols for USP-grade material. Regional compounders deploy plasma-enhanced synthesis systems to serve cosmetic formulators with just-in-time supply.
India
CDSCO's tightening purity requirements for topical zinc oxide create qualification windows for producers offering USP-grade material with sub-50 ppm heavy metal content. Hindustan Zinc Limited controls raw material costs through backward integration into mined zinc concentrate. Domestic pharmaceutical and cosmetic formulation channels drive demand for high-purity powder and granule forms.
Brazil
ANVISA-aligned import substitution policies favor regional zinc oxide production for domestic rubber vulcanization in tire manufacturing. The country's national pharmaceutical regulator sets standards for topical applications. São Paulo state's industrial corridor anchors regional compounding capacity for automotive supply chains.
Zinc Oxide Pigments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the zinc oxide pigments value chain, creating a tiered structure where integrated chemical majors capture scale economies while regional specialists command premium positioning in pharmaceutical and cosmetic grades. The vendor base clusters around three strategic archetypes: backward-integrated mining-chemical conglomerates with captive zinc concentrate supply, European specialists in high-purity and surface-modified grades, and regional French-process producers serving tire and coatings manufacturing. Dominant competitive moves include direct procurement contract formation with automotive and cosmetic end-users, and modular plasma-enhanced synthesis adoption for distributed pharmaceutical-grade production.
Among Germany-based chemical conglomerates, BASF SE and Lanxess occupy positions representing integrated precursor chemistry advantages for coated and micronized variants. EverZinc anchors European demand through specialized production archetypes. Hindustan Zinc Limited exemplifies mining-backed vertical control over raw material costs across powder and granule forms. U.S. Zinc and Pan-Continental Chemical Co., Ltd. represent regional scale-driven producers serving rubber and coatings channels.
| Leading Market Players |
|---|
| BASF SE |
| EverZinc |
| Hindustan Zinc Limited |
| U.S. Zinc |
| Pan-Continental Chemical Co., Ltd. |
| Hakusui Tech |
| Zinc Nacional |
| Lanxess |
| Grillo-Werke AG |
| Others |
Value Network & Pricing Analysis
Process chemist concentration in Shandong province's coastal industrial parks compresses labor-cost differentials between French-process furnace operators and downstream formulators, widening pricing-tier spreads between standard rubber-grade output and surface-silanized cosmetic variants.
Pricing Analysis
Short lead-time premiums for just-in-time pharmaceutical-grade supply from Italian and South Korean plasma-enhanced synthesis units command substantial markups over bulk-contracted standard grades. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified micronized material from industrial rubber activators and agricultural feed-grade powder. Price differentiation hinges on REACH nanoform compliance certification and volume scale, with cosmetic formulators absorbing premium positioning to avoid ECHA labeling mandates. Cost compression in standard grades is intensifying because Chinese domestic tire manufacturers are locking in direct procurement contracts at fixed volumes.
Supply Chain Analysis
Reverse-logistics flows for spent French-process furnace refractories and zinc-containing dust capture residues are minimal, with most producers relying on primary zinc metal feedstock rather than closed-loop material recovery. Supply concentrates in China, Germany, and India, with Shandong province hosting over half of export-facing capacity. Raw material dependencies draw from London Metal Exchange zinc ingots, metallurgical-grade zinc concentrate from Hindustan Zinc's Rajasthan mines, and silane coupling agents for surface modification. Single-source vulnerability runs through concentrated Shandong production clusters exposed to MIIT environmental enforcement actions. Distribution runs through direct annual volume agreements between tire manufacturers and coated-grade specialists, displacing traditional chemical traders across Germany's Rhine corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH registration costs and nano-toxicology expertise requirements are forcing sub-scale French-process operators toward exit or acquisition.
For Market Incumbents: To counter plasma-enhanced synthesis decentralization threatening traditional furnace economics, BASF and EverZinc should deepen captive precursor chemistry advantages and expand silane-coating capacity in Rhine corridor logistics-integrated facilities. Securing direct procurement contracts with Continental and Michelin anchors volume visibility against spot-market volatility. For New Entrants and Emerging Players: Launch via distributed plasma-enhanced synthesis units serving Italian and South Korean cosmetic compounders with just-in-time transparent grade supply, bypassing bulk shipping exposure. Brazilian tire localization under ANVISA-aligned policies offers the most penetrable geography, with São Paulo state's industrial corridor providing regional compounding infrastructure for automotive supply chain integration. For Investors and Strategic Acquirers: Re-rating potential sits with surface-modification specialists given accelerated ECHA-driven qualification of silanized variants outside nano-material classification. Long-term viability favors producers with dual REACH-compliant and USP-grade certification capabilities. Monitor CDSCO purity standard tightening in India as inflection signal for pharmaceutical-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Concentrate | Hindustan Zinc's Rajasthan mining operations secure raw material cost control across powder and granule forms. |
| Plasma-Enhanced Synthesis Adoption | Regional compounders in Italy deploy modular units for pharmaceutical-grade purity without furnace scale economies. |
| Silane Surface Treatment Capacity Expansion | French and German cosmetic formulators absorb premium pricing for REACH-compliant grades avoiding ECHA labeling. |
| Direct Procurement Contract Formation | Continental and Michelin bypass traditional chemical traders through annual volume agreements with coated-grade specialists. |
| CDSCO USP-Grade Qualification | Indian pharmaceutical and cosmetic channels create windows for producers offering sub-50 ppm heavy metal content material. |
Research Methodology
Trade databases, SEC filings, and ECHA registration dossiers formed the secondary backbone, cross-referenced with primary interviews involving French-process plant managers, cosmetic formulation R&D directors, tire manufacturer procurement leads, and zinc concentrate supply specialists. Bottom-up and top-down triangulation validated volume estimates across product type and application segments.
Bottom-up modeling aggregated individual facility capacities and utilization rates, while top-down approaches benchmarked against ACC and Cefic chemical industry reports. Segmentation dimensions included particle architecture tier, end-use industry regulatory stringency, surface modification chemistry, and regional production hub classification. CAGRs were derived from demand elasticity modeling against zinc metal price volatility and REACH compliance cost trajectories. Forecast inputs incorporated MIIT emission control enforcement intensity and CDSCO purity standard evolution.
The model assumes a particular technology adoption path; alternative pathways for plasma-enhanced synthesis scale-up would alter the outlook if modular units achieve cost parity with traditional French-process furnaces. Forecasts reflect assumptions about REACH Annex VI enforcement consistency and Chinese domestic tire demand absorption rates. Practitioners should monitor Shandong environmental enforcement actions and ECHA nanoform guidance revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market