
 Pigment Dispersions Market | 2026-2036
Pigment Dispersions Market Size, Share, and Industry Trends Forecast 2026-2036
Pigment Dispersions Market Intelligence
The development of high-chroma, nano-particle dispersions is redrawing competitive boundaries in the coatings and inks sectors. BASF SE leverages its extensive chemical synthesis capabilities to produce advanced additives and dispersants. Clariant AG differentiates through its focus on specialty pigments for demanding applications in plastics and automotive finishes. Cabot Corporation specializes in high-performance carbon black dispersions for conductive and jetness applications.
Pigment dispersions are stabilized suspensions of fine pigment particles within a liquid carrier, engineered to prevent agglomeration and ensure uniform color delivery. Critical performance is dictated by parameters like particle size distribution. While water-based dispersions gain share from solvent-based systems, the coatings application remains the largest volume driver. The plastics and textiles segments represent areas of notable expansion.
Regulations like the EU’s REACH and US EPA standards on volatile organic compounds (VOCs) directly influence formulation chemistry. These frameworks compel a shift towards compliant water-based systems by restricting specific solvents. For packaging applications, adherence to food contact rules from the FDA and EFSA is mandatory. Future market position hinges on developing high-performance products that meet these evolving regulatory demands.
Market Dynamics
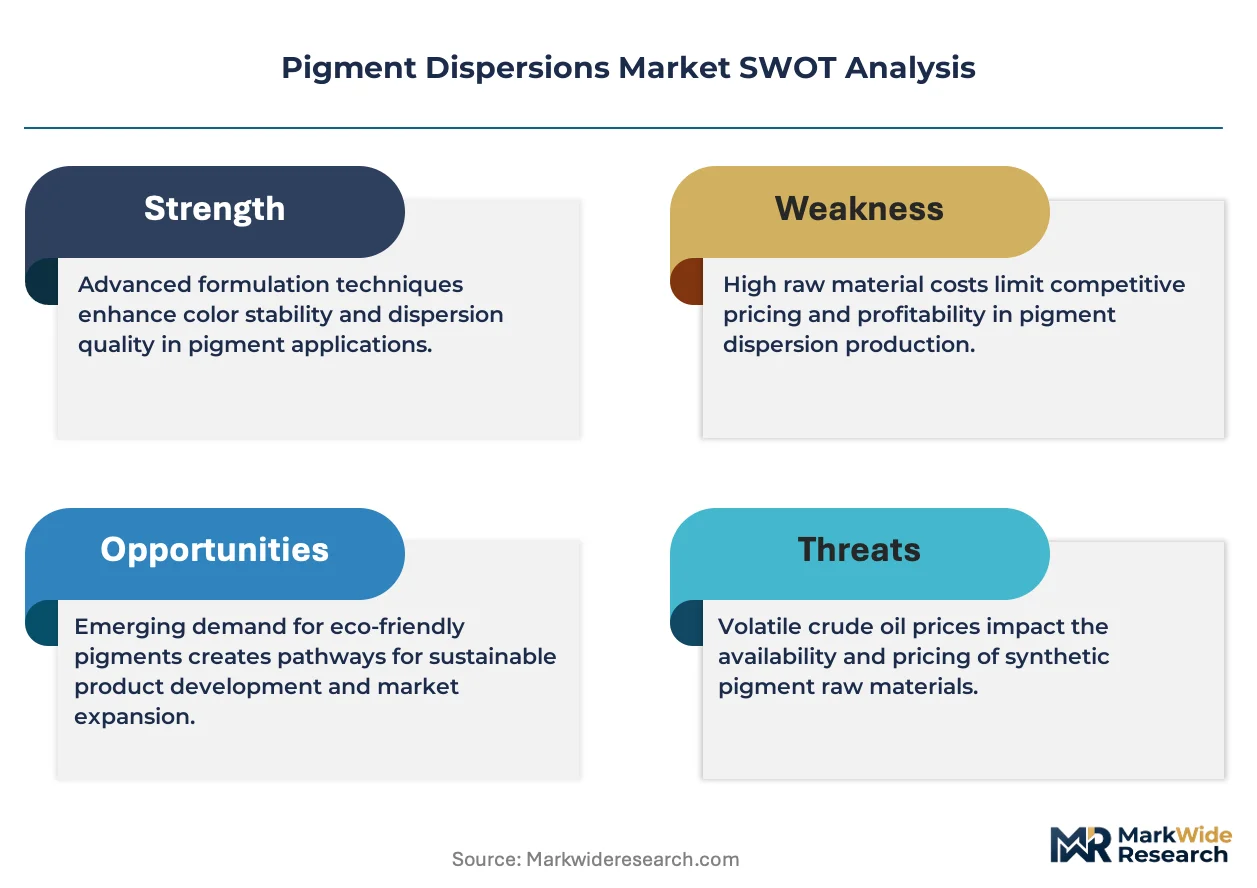
The fundamental dynamic shaping the pigment dispersions market is the regulatory-driven reformulation away from solvent-based systems. This shift, mandated by volatile organic compound (VOC) restrictions in key regions, forces a technological pivot towards water-based and UV-curable alternatives.
Growth Catalysts
- Automotive Sector Demand:The automotive coatings industry requires dispersions that provide superior durability, chemical resistance, and aesthetic finish, driving innovation in high-performance products for OEM and refinish applications.
- Regulatory Mandates:Frameworks like the EU's REACH regulation accelerate the transition to water-based dispersions by restricting hazardous solvents, creating a clear market pathway for compliant formulations.
- Advancements in Nano-Technology:The development of nano-particle dispersions enables higher color strength, transparency, and stability, opening new applications in digital printing inks and advanced electronics.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations in key raw materials, particularly titanium dioxide (TiO2) and specialty organic pigments, which can compress manufacturer margins.
- Technical Performance Gaps:Water-based dispersions can exhibit slower drying times and lower resistance in certain harsh industrial environments compared to legacy solvent-based systems, limiting substitution in some niches.
- Complex Food-Contact Compliance:Adhering to divergent food-contact regulations from bodies like the US FDA and the EU's EFSA for packaging applications creates significant testing and certification hurdles for suppliers.
Strategic Opportunities
- Bio-Based Formulations:Developing dispersions using bio-derived solvents and resins presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious end-users in packaging and consumer goods.
- Conductive Dispersions:High-performance carbon black and silver dispersions for conductive inks and coatings represent a high-value growth area, aligned with the expansion of printed electronics and smart textiles.
- Expansion in Southeast Asia:Rapid industrialization and construction growth in countries like Vietnam and Indonesia create untapped demand for coatings, plastics, and textiles, offering new geographic expansion frontiers.
Industry Challenges
- Reformulation Complexity:Switching from solvent to water-based systems requires significant R&D investment and expertise to maintain performance attributes like adhesion, gloss, and stability, challenging smaller producers. *Supply Chain Consistency: Ensuring a stable supply of high-purity pigments and specialized additives, many of which are sourced from geographically concentrated regions, is a persistent operational challenge for formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigment Dispersions Market |
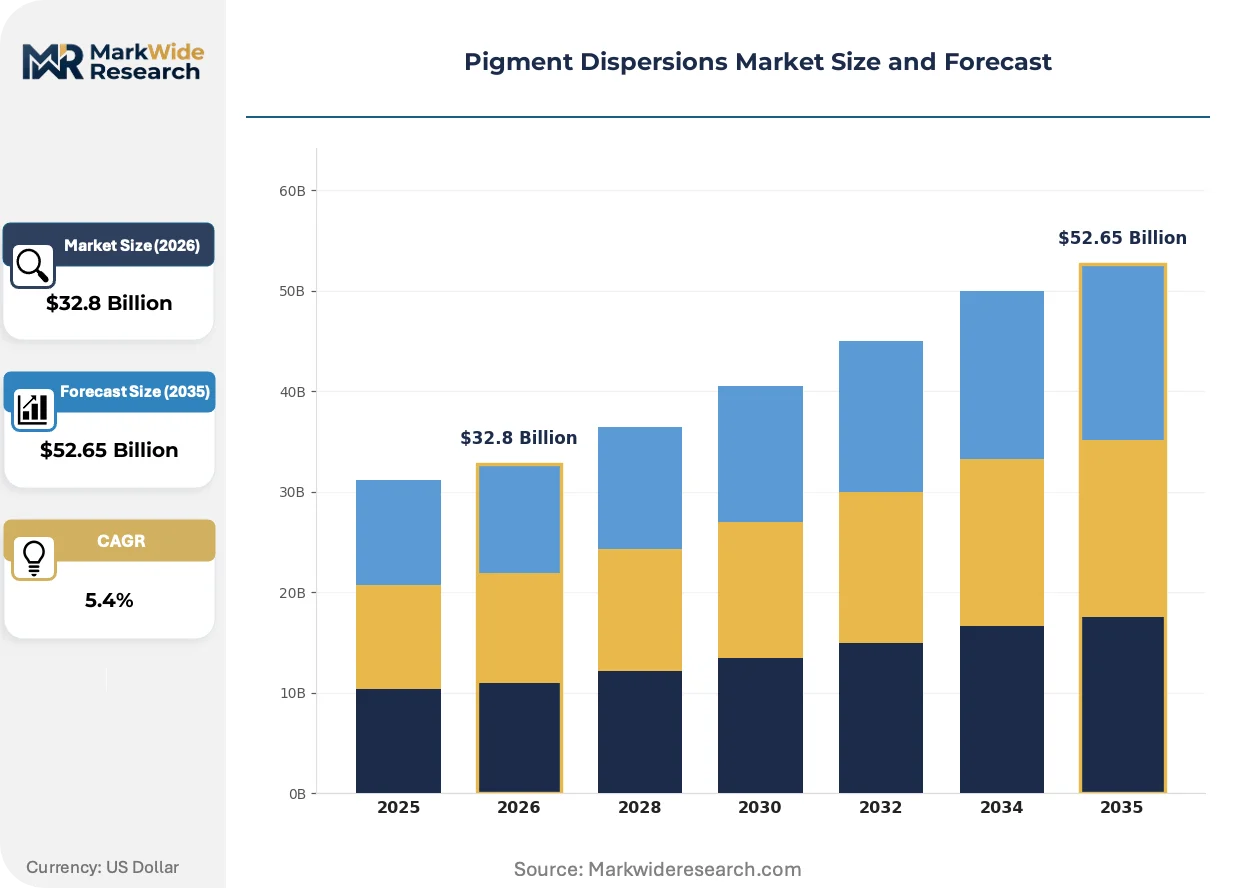
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, UV-Based, Powder, Paste, Emulsion Technology: High-Speed Disperser, Bead Milling, Ultrasonic, Ball Milling, Homogenization Application: Coatings, Inks, Plastics, Textiles, Cosmetics, Construction End User Industry: Paint Manufacturers, Printing, Polymer Producers, Fabricators, Personal Care Producers, Building Materials |
| Companies Covered | PPG Industries, Clariant AG, BASF SE, Heubach GmbH, Cabot Corporation, DIC Corporation, The Sherwin-Williams Company, Penn Colors Inc., Sudarshan Chemical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigment Dispersions Market Strategic Shifts & Innovations
Material science and sustainability are the twin engines of innovation in the pigment dispersions sector. The market is defined by a push for higher performance through advanced particle engineering, alongside a concurrent pull towards environmentally benign formulations mandated by global regulations.
Nano-particle dispersions are formulations engineered with pigment particles at the nanometer scale, providing exceptional color strength and stability. Automotive and high-end printing ink manufacturers are adopting these systems to achieve effects like higher chroma and jetness. This advanced technology is supplanting conventional micron-sized preparations that cannot match the performance required for premium finishes and digital printing applications.
China's "dual carbon" national strategy and associated MEE directives on industrial VOC emissions are accelerating a market-wide shift. This policy forces domestic manufacturers of coatings, inks, and plastics to rapidly adopt water-based or UV-curable technologies to remain compliant. The industrial coatings segment, particularly for furniture and machinery, is most affected and is undergoing a rapid, large-scale reformulation cycle.
A behavioral shift is underway where end-users are specifying dispersions based on functional outcomes rather than just color. This disrupts traditional purchasing, moving it from a simple color-match transaction to a technical specification process focused on metrics like lightfastness, chemical resistance, or food-contact certification. This trend is most visible in the architectural and food packaging segments, where performance and safety documentation are paramount.
Pigment Dispersions Market Segmentation
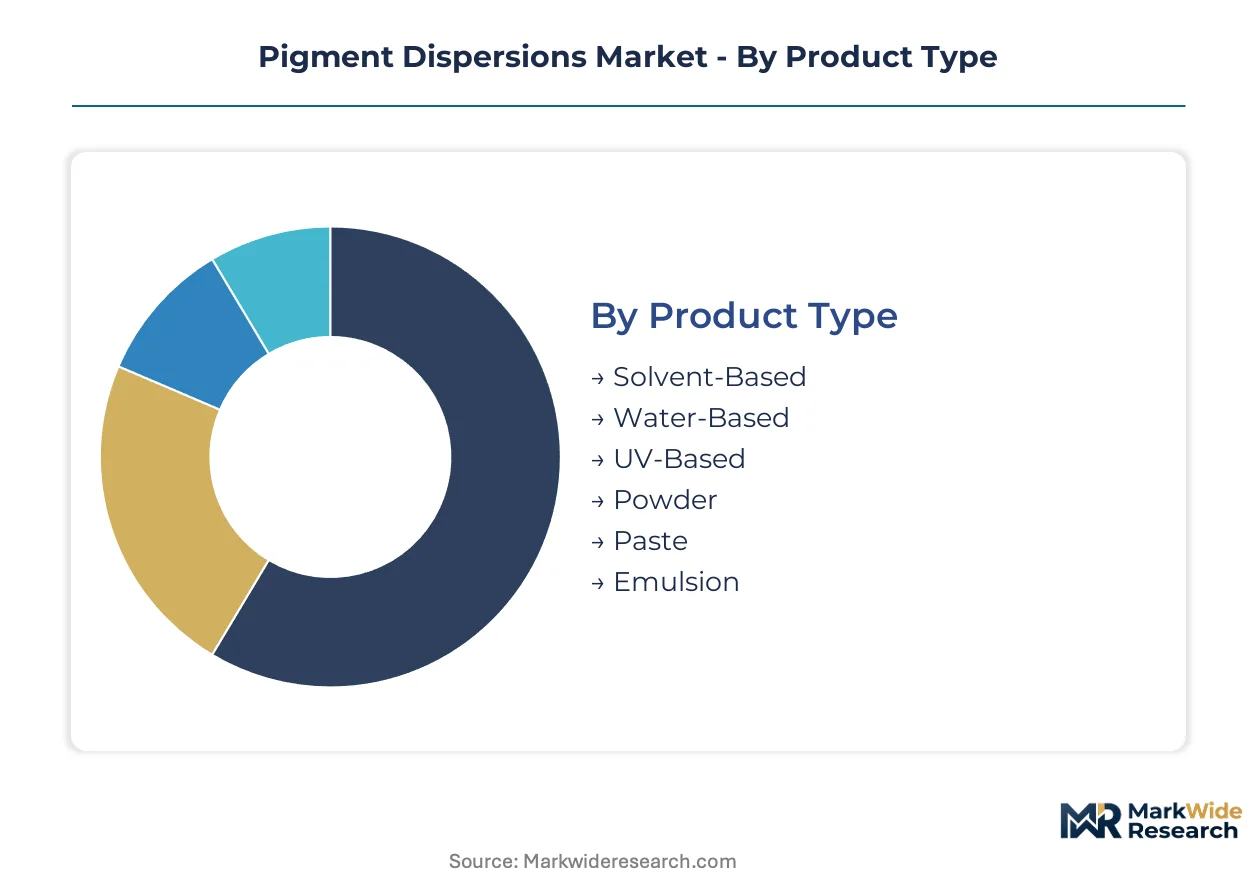
Understanding the segmentation of the pigment dispersions market reveals how diverse product formulations, processing technologies, and end-use applications shape competitive dynamics. This granular analysis highlights where innovation is most impactful and where specific regulatory pressures drive market shifts.
Product Type:
The distribution of pigment dispersions often follows distinct product type channels, each optimized for different performance and regulatory requirements in various industries.
- Solvent-Based:These dispersions utilize organic solvents as the carrier medium, offering rapid drying times and excellent substrate adhesion in many industrial coatings. Demand for these systems is concentrating in automotive refinish and specialized industrial applications where performance outweighs environmental considerations.
- Water-Based:Formulated with water as the primary carrier, these systems reduce volatile organic compound (VOC) emissions, aligning with global environmental regulations like the EU's REACH framework. Growth is concentrating in architectural coatings and packaging inks due to strong regulatory mandates and sustainability goals.
- UV-Based:These dispersions cure rapidly under ultraviolet light, enabling high-speed production and exceptional durability for graphic arts and certain industrial coatings.
- Powder:Pigment powders are dry, finely ground particles that require dispersion at the point of use, common in plastics and dry-mix construction materials.
- Paste:High-concentration pigment pastes are often used as intermediates, offering formulators flexibility in developing custom color solutions for various applications.
- Emulsion:Emulsion dispersions involve pigments suspended in an immiscible liquid, often stabilized by surfactants, finding use in textile printing and certain paint formulations.
By volume, Solvent-Based formulations lead. By growth pace, Water-Based systems are ahead.
Technology:
The choice of dispersion technology directly impacts production costs and the final product's quality, influencing particle size, stability, and color development.
- High-Speed Disperser:This method uses a rotating disc to create high shear forces, suitable for pigments requiring moderate dispersion and often used for general-purpose paints and coatings. This technology is widely adopted by regional paint manufacturers for its cost-effectiveness and versatility.
- Bead Milling:Utilizing small ceramic or glass beads, this technology provides high-energy input for fine particle size reduction, critical for high-chroma inks and automotive topcoats. Demand for bead milling is concentrating in specialty pigment production for digital printing and high-performance coatings.
- Ultrasonic:Ultrasonic technology employs high-frequency sound waves to de-agglomerate pigment particles, offering precise control over dispersion for advanced materials.
- Ball Milling:Ball mills use larger grinding media and are effective for dispersing larger pigment aggregates, commonly applied in ceramic glazes and some industrial coatings.
- Homogenization:This process forces pigment suspensions through a narrow gap at high pressure, achieving uniform particle distribution, particularly useful for cosmetic formulations.
The shift towards finer particle sizes is driving investment into advanced milling techniques.
Application:
Volume consumption for pigment dispersions is heavily concentrated across several key application areas, each with specific performance requirements.
- Coatings:This segment represents the largest application area, demanding dispersions with excellent weatherability, chemical resistance, and color stability for architectural, automotive, and industrial finishes. Automotive coatings manufacturers require high-performance dispersions for superior durability and aesthetic appeal.
- Inks:Pigment dispersions for inks require precise color matching, printability, and lightfastness for packaging, commercial printing, and digital inkjet applications. Digital printing technology is driving innovation in nano-particle dispersions for enhanced color gamut and jetting reliability.
- Plastics:Dispersions are incorporated into plastics to provide color, UV protection, and opacity for consumer goods, automotive parts, and construction materials.
- Textiles:Textile applications utilize pigment dispersions for fabric printing and dyeing, requiring wash fastness and vibrant color reproduction.
- Cosmetics:Pigment dispersions in cosmetics provide color and opacity for makeup products, requiring high purity and regulatory compliance for skin contact.
- Construction:The construction sector uses pigment dispersions for coloring concrete, roofing materials, and specialized coatings, emphasizing durability and weather resistance.
Different applications demand specific performance profiles from pigment dispersions, influencing customer purchasing decisions.
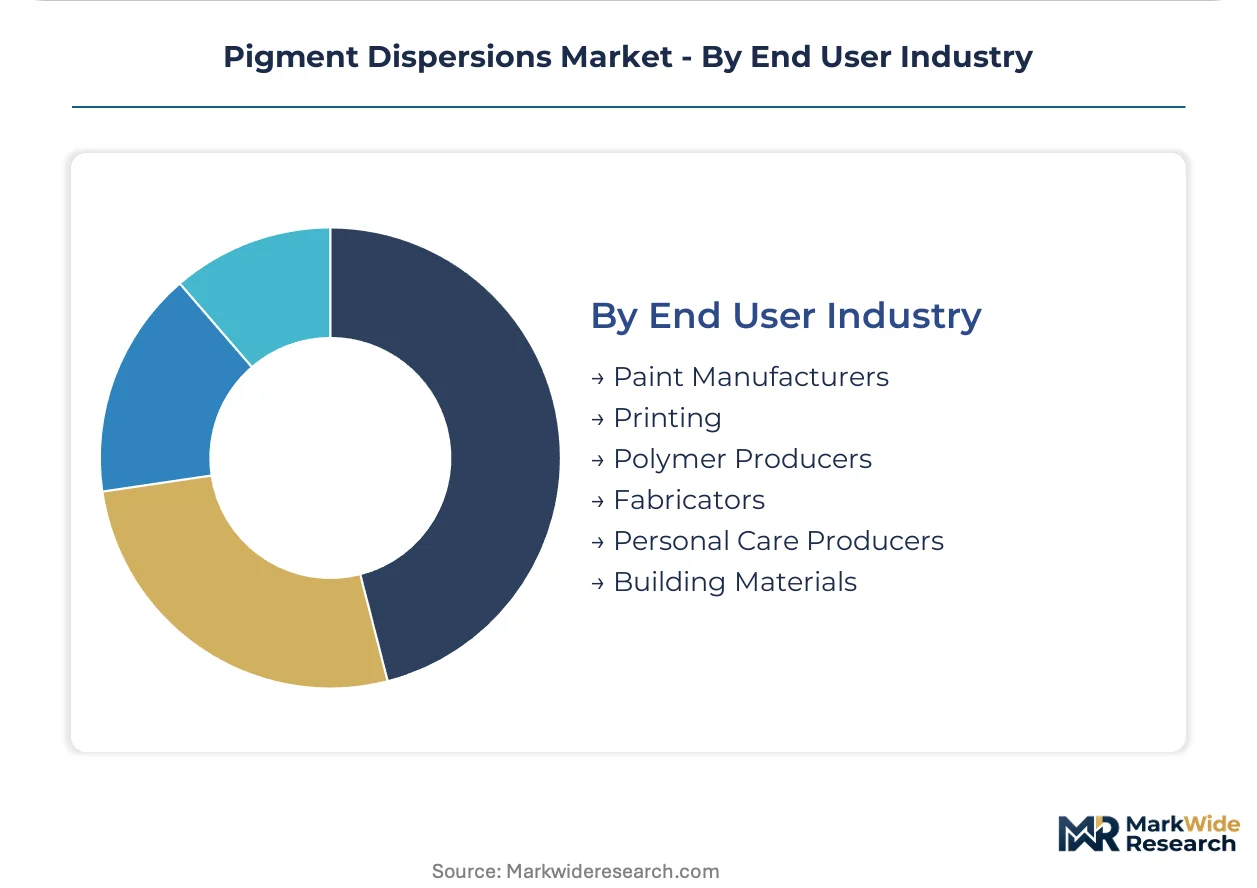
End User Industry:
The maturity of end-user industries dictates their adoption rates of new pigment dispersion technologies and their willingness to invest in specialized formulations.
- Paint Manufacturers:These companies are primary consumers, integrating pigment dispersions into a wide array of decorative, protective, and specialty paint products. Paint manufacturers are actively reformulating towards water-based systems to meet environmental regulations.
- Printing:The printing industry, encompassing packaging, commercial, and digital segments, relies on pigment dispersions for consistent color reproduction and print quality across diverse substrates. Printing companies are investing in UV-curable and water-based inks to reduce VOC emissions.
- Polymer Producers:Polymer producers incorporate pigment dispersions directly into plastic resins to create colored plastics for various manufacturing processes.
- Fabricators:Fabricators use pigment dispersions in composite materials and specialized industrial products, where specific color and functional properties are required.
- Personal Care Producers:This industry utilizes high-purity pigment dispersions for cosmetic and personal care formulations, adhering to stringent safety standards.
- Building Materials:Manufacturers of building materials, including concrete, tiles, and sealants, use pigment dispersions for aesthetic and functional coloring.
Higher value applications within these industries typically allow for premium pigment dispersion formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pigment dispersions market exhibits varied demand elasticity across regions. High-performance applications, such as automotive coatings and digital printing, command premium pricing due to stringent performance requirements. Conversely, commodity segments like architectural paints and basic plastics show greater price sensitivity, driving regional manufacturers towards cost optimization.
China
China's vast manufacturing sector, spanning electronics and consumer goods, drives substantial pigment dispersion demand. The nation's MEE directives on industrial VOC emissions accelerate adoption of water-based technologies. The Yangtze River Delta region, a manufacturing hub, sees significant reformulation activity in industrial coatings.
Germany
Germany's robust automotive sector and advanced industrial manufacturing create strong demand for durable pigment dispersions. The EU's REACH framework mandates a shift towards water-based and compliant formulations. The Rhine-Main chemical cluster actively develops high-performance specialty pigments for demanding applications.
United States
United States demand arises from large architectural coatings and packaging industries, alongside automotive refinish. US EPA standards on volatile organic compounds compel reformulation efforts across various segments. The Gulf Coast chemical corridor supplies critical raw materials, influencing domestic dispersion production and innovation.
India
India's burgeoning construction sector and expanding automotive industry fuel significant demand for pigment dispersions. BIS standards increasingly influence product formulations, particularly for paints and plastics. Gujarat's industrial zones are experiencing growth in both pigment and dispersion manufacturing capabilities.
Japan
Japan's advanced electronics and high-precision printing industries require specialized pigment dispersions. METI initiatives encourage sustainable chemical practices, influencing new product development. The Kanto region hosts significant R&D efforts, particularly for nano-particle dispersions in digital printing applications.
Pigment Dispersions Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the pigment dispersions market. This market exhibits a tiered structure, with global chemical giants focusing on advanced material science alongside specialized dispersion manufacturers. Regional formulators often prioritize cost-effective solutions for local markets. Strategic partnerships and targeted M&A activity drive portfolio diversification and geographic expansion.
Specialists in high-performance pigment dispersions often anchor their strategies around specific material science expertise. Clariant AG, a Swiss-based chemical company, exemplifies differentiation through its focus on specialty pigments tailored for demanding applications in plastics and automotive finishes. BASF SE, a German chemical giant, represents extensive chemical synthesis capabilities, leveraging these to produce advanced additives and dispersants that enhance performance. Furthermore, Cabot Corporation, a US-based firm, occupies a distinct position within the high-performance carbon black segment, providing solutions for conductive and jetness applications across various industries. These companies collectively illustrate the market's emphasis on specialized offerings and material innovation.
| Leading Market Players |
|---|
| PPG Industries |
| Clariant AG |
| BASF SE |
| Heubach GmbH |
| Cabot Corporation |
| DIC Corporation |
| The Sherwin-Williams Company |
| Penn Colors Inc. |
| Sudarshan Chemical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in pigment manufacturing significantly influence the cost structure for dispersions, driving supply concentration among large chemical producers. This concentration directly impacts price floors, particularly for commodity-grade offerings in architectural coatings.
Pricing Analysis
The EU’s REACH framework dictates the pricing tier structure, compelling formulators to invest in compliant, often higher-cost, water-based systems. The dominant pricing model involves contract-based long-term offtake agreements for high-volume specialty dispersions. Price differentiation stems from performance characteristics like lightfastness and specific food-contact certification levels. Cost compression in commodity segments is intensifying due to volatility in raw material prices, particularly for titanium dioxide. Automotive OEM finishes exhibit the least price sensitivity, while architectural coatings remain the most price-sensitive segment.
Supply Chain Analysis
Strategic stockpiling of key pigments and dispersants is common for ensuring supply continuity amidst geopolitical uncertainties. Geographic supply concentration for critical raw materials centers on China for organic pigments and specialty chemicals, alongside Germany for advanced dispersants. Raw material dependencies include titanium dioxide, specialty organic pigments, and various dispersant chemicals. Commodity price volatility, especially for TiO2 and oil-derived chemicals, represents a structural supply chain risk. Distribution runs through a dual model, with direct sales to large paint and ink manufacturers, complemented by specialized distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pigment dispersions market presents a fragmentation opportunity, driven by end-users increasingly specifying dispersions based on functional outcomes rather than just color, creating specialized niches.
For Market Incumbents: Shield existing market share by accelerating investment in advanced water-based and UV-curable technologies, particularly for high-volume applications. Consolidate positions in performance-critical segments like automotive coatings and digital printing through continuous R&D in nano-particle dispersions. Leverage extensive chemical synthesis capabilities to produce proprietary additives and dispersants, creating a barrier against emerging bio-based alternatives and agile niche specialists.
For New Entrants and Emerging Players: Custom formulation support for complex regulatory compliance represents a significant service-layer gap where incumbents under-serve. Target small-to-medium enterprises in packaging and textile printing, which require tailored, compliant solutions but lack in-house R&D. A compelling go-to-market angle involves offering specialized R&D partnerships focused on bio-based solvents, conductive dispersions, or customized food-contact certified systems for specific regional requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pigment dispersion manufacturers that provide highly customized, performance-critical formulations. The long-term viability favors companies with strong intellectual property in nano-technology and robust regulatory compliance expertise for global markets. Target acquisition profiles include mid-sized firms with established positions in high-growth areas like conductive inks or bio-based solutions. A key signal to watch is the adoption rate of bio-based or conductive dispersions in new, high-value electronics and sustainable packaging applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Portfolio Expansion | Meets global VOC regulations and growing demand for sustainable architectural and packaging coatings. |
| Nano-Particle R&D Investment | Enables higher color strength and stability for premium automotive finishes and digital printing inks. |
| Geographic Expansion in Southeast Asia | Captures untapped demand from rapid industrialization and construction growth in emerging markets. |
| Bio-Derived Solvent Integration | Addresses corporate sustainability goals and appeals to environmentally conscious end-users in consumer goods. |
| Food-Contact Certification Enhancement | Secures market access and strengthens trust in packaging applications governed by strict FDA and EFSA rules. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved in-depth conversations with R&D directors, procurement managers, regulatory affairs specialists, and paint formulators across key regions. Secondary data sources included industry association reports, government regulatory documents from EU REACH and US EPA, company annual filings, and specialized trade publications. This approach ensured a comprehensive understanding of market dynamics through both bottom-up market sizing and top-down validation.
The quantitative modeling framework projected market evolution across the analysis window, utilizing a blend of historical growth trends and anticipated market shifts. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from a detailed assessment of these factors. Key industry-specific forecast inputs included raw material price forecasts and regulatory enforcement timelines for VOC emissions.
Underlying assumptions cover stable economic conditions and consistent regulatory enforcement across major markets, with deviation risk concentrated in unforeseen geopolitical events or rapid shifts in raw material supply. Forecasts reflect these assumptions, acknowledging the dynamic nature of the pigment dispersions sector. Revision becomes warranted when significant changes in global trade policies or environmental regulations cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Chlorophyll Color Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Natural Colorants Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Micronized Color Powder Market