
 Bio Based Pigments and Dyes Market | 2026-2036
Bio Based Pigments and Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Based Pigments and Dyes Market Outlook
The EU Green Deal is hardening requirements for petrochemical-derived colorants across European manufacturing supply chains. BASF SE leverages its integrated biotechnology platforms to convert agricultural waste streams into anthraquinone precursors at industrial scale. Clariant anchors its competitive position through specialized fermentation capabilities for carotenoid production in Switzerland. Stony Creek Colors dominates natural indigo cultivation networks across the southeastern United States, supplying denim brands with traceable plant-based alternatives.
Bio based pigments and dyes comprise colorant compounds synthesized or extracted from renewable biological feedstocks including plants, microorganisms, and agricultural residues, with molecular structures ranging from flavonoid glycosides to porphyrin derivatives and functional parameters typically specifying lightfastness ratings of 4-7 on the Blue Wool Scale. Their primary industrial purpose centers on replacing synthetic azo and anthraquinone colorants in applications where regulatory restrictions on heavy metal content and petrochemical sourcing are tightening. Powder formulations retain the largest share of current volume owing to stability in storage and compatibility with conventional dispersion equipment, while liquid concentrates represent the fastest-expanding form segment as water-based coating systems gain share from solvent-borne alternatives. Textile applications command the deepest margin pools due to premium pricing for GOTS-certified natural dyes, though coatings applications are narrowing the gap through automotive OEM specifications for interior bio-based content.
REACH restrictions on aromatic amine releases and the EU F-Gas Regulation are reshaping formulation requirements across the colorant value chain, with ECHA substance evaluations now covering multiple legacy dye intermediates. The US EPA Safer Choice program and state-level California Proposition 65 enforcement are creating parallel compliance obligations for exporters serving North American apparel brands. Stakeholders must monitor pending revisions to OEKO-TEX Standard 100 limits on synthetic dye residuals, as these thresholds will determine which bio-based alternatives achieve qualified supplier status with major textile certification bodies.
Market Dynamics
REACH enforcement and EU Green Deal compliance timelines are forcing textile mills and coating formulators to requalify their entire colorant supply chains around bio-based alternatives, compressing the transition window from voluntary sustainability to mandatory substitution.
Growth Catalysts
- EU Green Deal mandates:Binding decarbonization targets for European manufacturing are eliminating petroleum-derived colorants from automotive interior specifications and apparel supply chains.
- Algae extraction platforms:Phycocyanin and other cyanobacterial pigments now achieve batch consistency matching synthetic benchmarks, opening premium coating applications previously closed to natural alternatives.
- Denim brand sustainability pledges:Major apparel labels have committed to 100% bio-based indigo sourcing by 2030, creating guaranteed offtake agreements for agricultural dye crops.
Market Restraints
- Agricultural feedstock volatility:Weather-dependent yields for indigofera and madder root create input cost instability unmatched by petrochemical precursors.
- Fermentation capacity concentration:Industrial-scale bioreactor infrastructure for bacterial melanin and carotenoid production clusters in Switzerland and Germany, creating geographic supply risk.
- Lightfastness performance gaps:Flavonoid-based yellows and anthocyanin reds still fail to meet automotive exterior durability standards above Blue Wool Scale 4.
Strategic Opportunities
- US Southeast cultivation networks:Tennessee and Kentucky indigo farming cooperatives are scaling to serve denim brands seeking shorter, traceable supply chains outside Asian petrochemical dependencies.
- Food-contact packaging migration:Phycocyanin and chlorophyll derivatives are penetrating edible film and biodegradable container markets as FDA GRAS designations expand.
- CRSD-aligned reporting:Corporate sustainability reporting mandates are creating procurement premiums for dye suppliers with verified Scope 3 emission reductions and agricultural partnership documentation.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial bioprocess engineers capable of optimizing pigment titers in 10,000+ liter bioreactors command salaries exceeding traditional chemical engineering premiums by 40%.
- GOTS certification bottlenecks:Textile certifiers face 18-month backlogs for natural dye facility audits, delaying brand compliance timelines and freezing supplier qualification pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Based Pigments and Dyes Market |
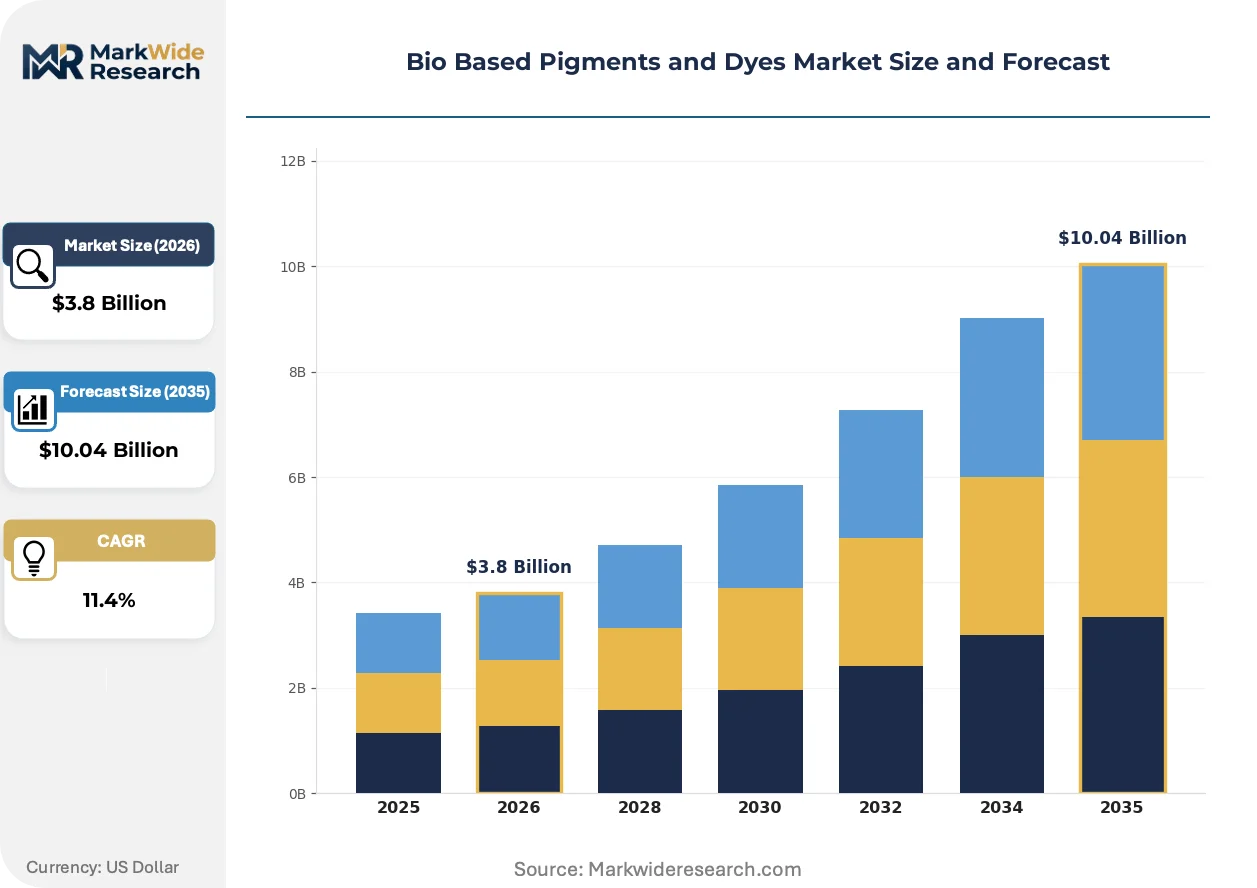
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo, Anthraquinone, Carotenoids, Indigos Application: Textiles, Coatings, Plastics, Inks End User: Apparel, Automotive, Construction, Arts Form: Powder, Liquid, Granules, Paste |
| Companies Covered | BASF SE, Cabot Corporation, Clariant, Huntsman Corporation, Kiri Industries, Sudarshan Chemical, Stony Creek Colors, Sea Colors, Horizon Research Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Based Pigments and Dyes Market Strategic Shifts
Continuous processing technology and closed-loop extraction systems are compressing the cost gap between bio-based and synthetic colorants, while regulatory disclosure requirements are forcing transparency through molecular-level supply chain traceability.
Precision fermentation is automating the production of complex porphyrin and carotenoid structures previously requiring multi-step chemical synthesis. Automotive OEMs in Germany are qualifying these pigments for interior applications at accelerated timelines. The technology is automating quality control protocols that previously required manual batch testing, reducing specification variance to synthetic-grade tolerances.
REACH substance evaluations now cover seventeen legacy dye intermediates previously grandfathered under 2006 registrations. ECHA's 2024-2026 work program prioritizes aromatic amine releases from textile finishing operations. Coating formulators serving the European automotive sector are pre-emptively reformulating around bio-based alternatives to avoid supply disruption from authorization sunsets.
Denim brands are consolidating supplier relationships around vertically integrated pigment-to-garment partnerships that bundle dye cultivation with cut-and-sew capacity. This disintermediation eliminates trading house markups and enables blockchain-tracked provenance claims. The model is concentrating procurement decisions among three to four anchor suppliers per major brand group, most visible in German and Dutch sustainability-led apparel markets.
Bio Based Pigments and Dyes Market Segmentation
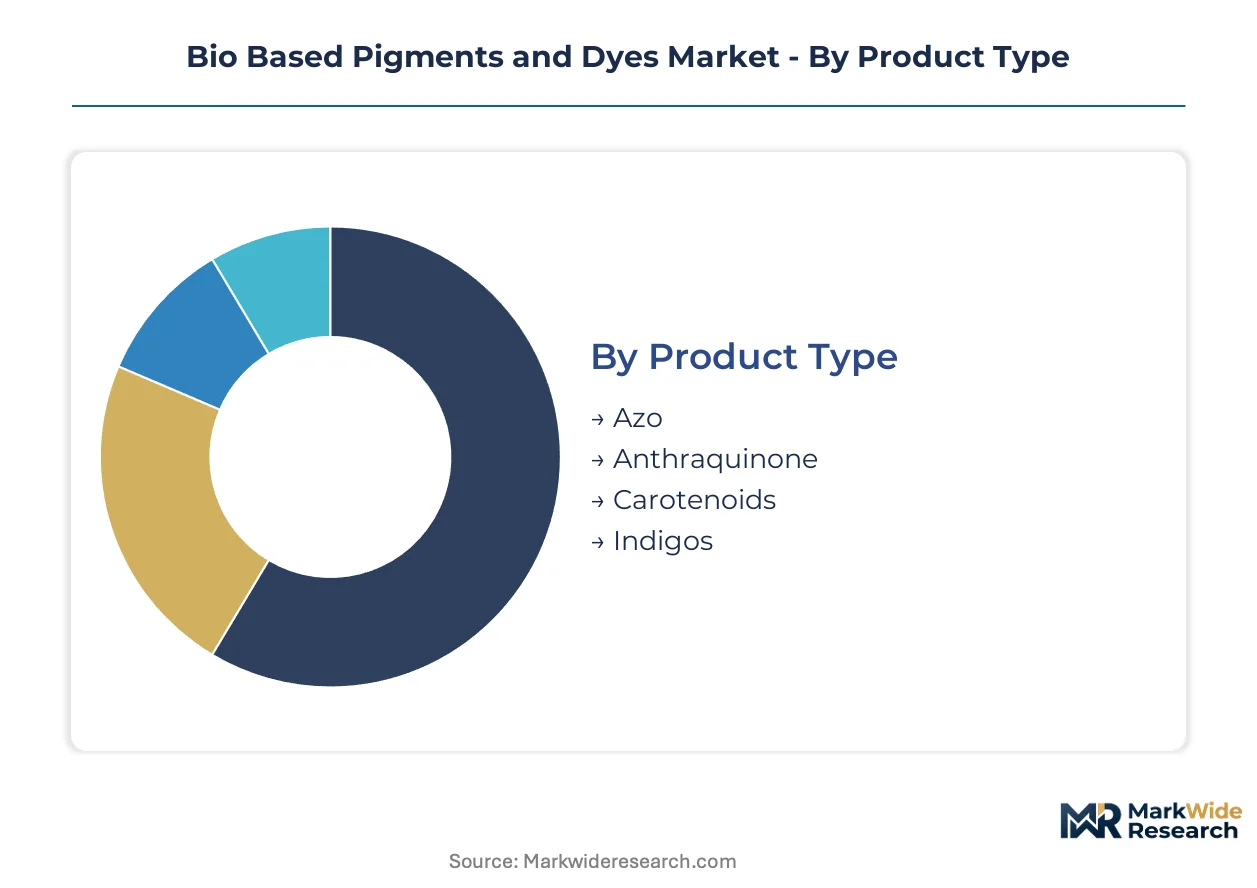
Segmentation in bio-based pigments and dyes reveals how certification requirements fragment procurement decisions across molecular classes and application formats. Each dimension carries distinct regulatory burdens that determine supplier qualification timelines and margin structures.
Product Type:
GOTS certification demands vary sharply by molecular structure, with indigos and carotenoids facing shorter audit pathways than azo-derived alternatives still flagged for aromatic amine testing.
- Indigos:Plant-derived indigotin and bacterial indoxyl precursors dominate denim applications with Blue Wool Scale 4-6 lightfastness ratings. German automotive OEMs specify these for interior leather finishing to meet EU Green Deal bio-content mandates.
- Carotenoids:Fermentation-produced beta-carotene and astaxanthin deliver orange-red spectra with batch consistency matching synthetic benchmarks. Swiss bioreactor clusters supply coating formulators seeking REACH-compliant alternatives to cadmium pigments.
- Anthraquinone:Agricultural waste conversion platforms extract alizarin and purpurin for textile printing pastes.
- Azo:Bio-based azo precursors from lignin degradation remain under ECHA substance evaluation with restricted textile applications.
Indigos sit at the top of the volume ranking, with carotenoids climbing the fastest as coating specifications harden around heavy metal exclusions.
Application:
Cost tier differentiation separates premium-certified textile dyes from commodity coating pigments, with margin structures inversely correlated to formulation complexity.
- Textiles:GOTS-certified natural dyes for apparel command the deepest margin pools through premium positioning with denim brands and luxury knitwear houses. Tennessee indigo cultivation networks supply shorter supply chains for traceability claims.
- Coatings:Phycocyanin and bacterial melanin displace petroleum alternatives in automotive interior specifications, though exterior durability standards above Blue Wool Scale 4 remain unmet by flavonoid yellows.
- Inks:Water-based bio pigment dispersions serve food-contact packaging migration as FDA GRAS designations expand for phycocyanin.
- Plastics:Masterbatch concentrates incorporate carotenoid derivatives for biodegradable container coloration with limited heat stability tolerance.
Textiles holds the revenue concentration, while coatings gains share fastest through automotive OEM sustainability mandates.
End User:
Customer type determines specification stringency, with automotive and apparel buyers imposing molecular-level traceability requirements absent in construction or arts segments.
- Apparel:Denim brands drive indigo procurement consolidation through vertically integrated pigment-to-garment partnerships with blockchain-tracked provenance.
- Automotive:German OEM interior specifications require REACH-compliant bio-based content verification with third-party agricultural partnership documentation.
- Construction:Exterior coating applications tolerate lower lightfastness ratings where regulatory pressure on petrochemical sourcing remains lighter.
- Arts:Small-batch natural dye suppliers serve premium craft markets with minimal certification overhead.
Apparel anchors procurement volume, with automotive expanding most quickly as CSRD-aligned reporting creates procurement premiums.
Form:
Supply concentration clusters powder production in conventional dispersion equipment corridors, while liquid concentrate capacity requires specialized water-based formulation infrastructure.
- Powder:Spray-dried pigment formulations retain stability in storage and compatibility with legacy textile dyeing equipment across European mill networks.
- Liquid:Concentrated dispersions serve water-based coating systems gaining share from solvent-borne alternatives in automotive interior applications.
- Paste:High-solids preparations reduce transportation costs for indigo vat dyeing operations in southeastern US cultivation zones.
- Granules:Dust-free handling formats penetrate plastics compounding with controlled dispersion characteristics.
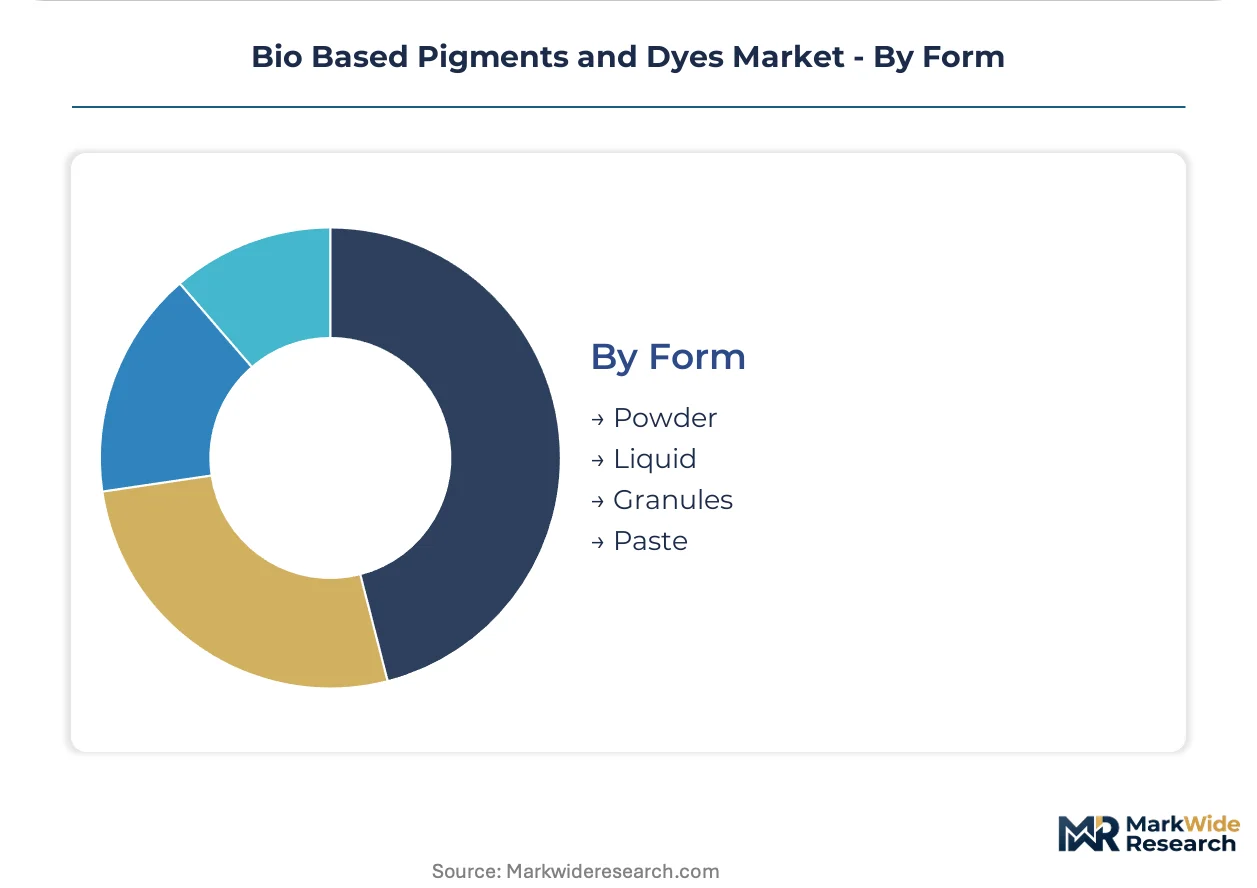
Powder maintains the installed base dominance, with liquid concentrates showing the steepest expansion trajectory as coating chemistry shifts aqueous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traditional dye cultivation emerged from agricultural regions in southern France and northern India during the 18th century, establishing supply patterns that persist in today's bio-based pigment networks. Contemporary production clusters reflect this heritage while integrating precision fermentation infrastructure.
Germany
Automotive OEM sustainability mandates from BMW, Mercedes-Benz, and Volkswagen drive specification tightening for interior bio-based content. REACH enforcement through ECHA substance evaluations eliminates seventeen legacy dye intermediates from supplier qualification lists. Stuttgart and Munich host the densest concentration of bioreactor infrastructure for bacterial melanin production serving coating formulators.
United States
Tennessee and Kentucky indigo farming cooperatives scale cultivation networks to serve denim brands seeking shorter supply chains. EPA Safer Choice program requirements and California Proposition 65 enforcement create parallel compliance obligations for natural dye exporters. Nashville anchors vertically integrated pigment-to-garment partnerships with blockchain-tracked provenance systems.
Switzerland
Specialized fermentation capabilities for carotenoid production cluster around Basel and Zurich biotech corridors. Swissmedic oversight of industrial biotechnology processes ensures batch consistency matching synthetic pigment benchmarks. Clariant anchors regional capacity serving coating formulators seeking REACH-compliant alternatives to cadmium pigments.
India
Historical indigo cultivation regions in Gujarat and Tamil Nadu revive traditional agricultural dye crops for export markets. BIS standards for natural dye quality parameters create certification pathways for GOTS-compliant suppliers. Ahmedabad textile mills integrate backward into indigofera cultivation to secure traceable feedstock for European apparel brand contracts.
France
Provence madder root cultivation networks supply alizarin precursors for premium textile printing applications. ANSM oversight of cosmetic-grade natural colorants creates quality standards migrating into industrial dye specifications. Lyon textile chemistry clusters develop closed-loop extraction systems for agricultural waste valorization into anthraquinone pigments.
Bio Based Pigments and Dyes Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the bio-based pigment value chain, creating a tiered structure where fermentation infrastructure owners capture margin premiums unavailable to toll manufacturers. The vendor base separates into integrated biotechnology platforms, specialized agricultural cultivators, and regional toll processors serving certification-heavy textile segments. Three archetypes dominate: multinational chemical conglomerates with biotech R&D pipelines, vertically integrated natural dye cultivators with captive farmland, and precision fermentation specialists scaling novel microbial pigments. Competitive intensity concentrates around M&A activity targeting fermentation capacity and strategic partnerships bundling dye supply with cut-and-sew manufacturing.
Within the integrated biotechnology tier, BASF SE and Clariant exemplify archetypes combining agricultural waste conversion platforms with industrial-scale bioreactor networks. Stony Creek Colors occupies a distinct position among specialized cultivators, representing the vertically integrated agricultural model with captive indigo farming operations. These three anchors illustrate the strategic divergence between fermentation-derived and plant-extracted pigment pathways competing for automotive and apparel procurement decisions.
| Leading Market Players |
|---|
| BASF SE |
| Cabot Corporation |
| Clariant |
| Huntsman Corporation |
| Kiri Industries |
| Sudarshan Chemical |
| Stony Creek Colors |
| Sea Colors |
| Horizon Research Lab |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation scale-up is compressing production costs for bacterial melanin and carotenoid pigments while simultaneously concentrating supply ownership among Swiss and German bioreactor operators with proprietary strain libraries. This technological transition rewards capital-heavy incumbents with decade-long cost curves that toll manufacturers cannot match, entrenching pricing power upstream while downstream textile mills absorb pass-through volatility from agricultural feedstock seasons.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with GOTS certification tier and volume scale as the primary price differentiation drivers. Cost compression in standard-grade indigo is intensifying because Tennessee cultivation cooperatives are expanding acreage faster than denim brand offtake growth. Apparel brands with sustainability mandates show the least price sensitivity, while construction coating formulators exhibit the highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive interior specifications, while pigment-to-garment partnerships serve denim brand traceability requirements. Supply concentrates in Switzerland, Germany, and the United States for fermentation-derived pigments, with India and France anchoring agricultural extraction networks. Raw material dependencies include indigofera biomass, cyanobacterial cultures, and madder root feedstocks. Single-source vulnerability runs through Swiss bioreactor clusters for carotenoid production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based pigments and dyes market functions as a regulatory compounder where EU Green Deal decarbonization mandates and REACH authorization sunsets create irreversible substitution demand for petroleum-derived colorants.
For Market Incumbents: To counter fermentation capacity concentration in Swiss and German corridors, BASF SE and Clariant must secure backward integration into agricultural waste conversion platforms and expand bioreactor networks into lower-cost geographies. Certification investment in GOTS-compliant facility audits represents a critical lever to capture denim brand procurement consolidation. For New Entrants and Emerging Players: REACH enforcement in Europe opens a window for US Southeast indigo cultivators to disintermediate Asian petrochemical trading houses through vertically integrated pigment-to-garment partnerships. Food-contact packaging applications for phycocyanin offer the most penetrable white-space, with FDA GRAS designation expansion enabling a direct-to-brand go-to-market angle bypassing traditional distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among agricultural cultivation networks with captive farmland but underdeveloped fermentation infrastructure, offering asymmetric upside as precision fermentation technology licenses become available. The signal to watch as an inflection indicator is automotive OEM exterior durability qualification for flavonoid-based yellows above Blue Wool Scale 4.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive indigofera cultivation in Tennessee secures traceable supply for denim brand contracts. |
| Precision Fermentation Scale-Up | Swiss bioreactor expansion matches synthetic pigment batch consistency for automotive interior specifications. |
| GOTS Certification Investment | Natural dye facility audits unlock qualified supplier status with major textile certification bodies. |
| Long-term Supply Agreement | Guaranteed offtake contracts with denim brands de-risk agricultural yield volatility for cultivation cooperatives. |
| Joint Venture for Food-Contact Applications | Phycocyanin partnerships with edible film manufacturers leverage FDA GRAS designations for packaging migration. |
Study Parameters
Direct dialogue with fermentation process engineers, textile mill procurement directors, automotive OEM sustainability officers, and natural dye cultivation cooperative managers grounded the qualitative assessment. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal implementation progress reports, GOTS certification audit backlogs, and SEC filings from publicly traded chemical conglomerates. Bottom-up and top-down triangulation reconciled capacity announcements with downstream demand signals across the projection horizon.
Segmentation outputs reflect modeled dimensions spanning molecular class, application format, end-user industry, and geographic production hub. CAGRs were derived from regression analysis against regulatory compliance timelines and automotive OEM specification adoption curves. Industry-specific forecast inputs include GOTS certification pipeline velocity and REACH authorization sunset schedules.
Revisions become necessary when ECHA expands substance evaluation scope beyond seventeen legacy dye intermediates or when automotive exterior durability standards for bio-based pigments shift. Forecasts reflect assumptions about fermentation titer improvements and agricultural yield stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Organic Lake Pigments Market
Dyes and Pigments
Pigment Additive Film Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
South America Hair Colorants Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Acid Violet 43 Market